 South America Cyanoacrylate Adhesives Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 234


Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 South America Cyanoacrylate Adhesives Market
Khageshwar Rongkali
Senior Analyst

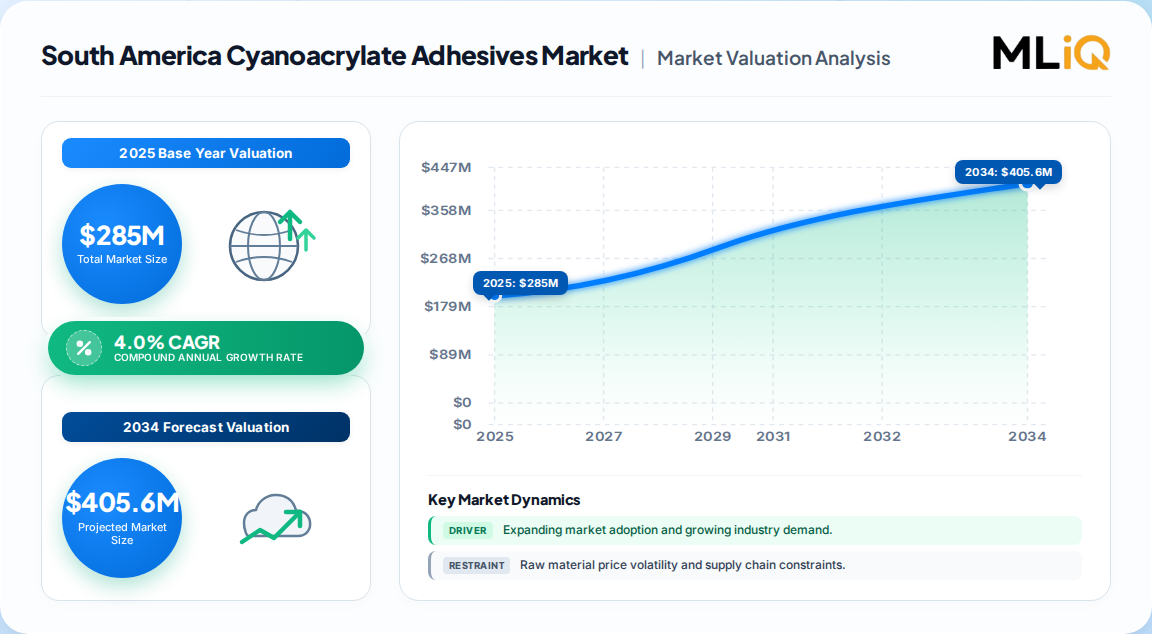
| Year | Market Size |
|---|---|
| 2025 | 285.0 M |
| 2026 | 296.0 M |
| 2027 | 308.0 M |
| 2028 | 321.0 M |
| 2029 | 333.0 M |
| 2030 | 347.0 M |

The South America cyanoacrylate adhesives market comprises fast-curing, single-component instant adhesives (ethyl, methyl and alkoxy ethyl esters) sold into transportation, footwear, furniture, consumer goods, healthcare and electronics across Brazil, Argentina and the rest of the continent. It spans commodity super glues through medical-grade tissue adhesives.
This analysis covers cyanoacrylate instant adhesives by product type (alkoxy ethyl-based, ethyl ester-based, methyl ester-based, other), by end-user industry (transportation, footwear & leather, furniture, consumer goods, healthcare, electronics, other), and by geography (Brazil, Argentina, Rest of South America). Forecasts run 2025–2030 against a 2019–2024 historical base.
This analysis does not cover epoxy, polyurethane, acrylic, hot-melt or silicone adhesives, nor anaerobic threadlockers, structural film adhesives, or adhesive-dispensing equipment. Adjacent markets such as South America acrylic adhesives and general adhesives and sealants are referenced only for benchmarking.
Published estimates for the South America cyanoacrylate adhesives market cluster around a mid-single-digit growth path, with the region representing roughly 3–5% of a global market sized between 2.16 and 2.35 Billion in 2023. South America's absolute value is therefore modest but structurally resilient.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| ~285 Million | 2025 | 2030 | 4.0% | Regional CA adhesives, all end uses | One published regional analysis |
| 2.16 Billion global (2023) | 2023 | 2033 | 2.81% | Global CA, reactive + UV cured | Competing global analysis |
| 2.35 Billion global (2023) | 2023 | 2032 | 5.73% | Global CA, all technologies | Second competing global analysis |
Our analysis suggests the 4.0% regional figure is the most defensible anchor. It sits between two global extremes: the 2.81% view underweights medical and EV-adjacent demand, while the 5.73% view extrapolates Asian electronics growth onto a slower South American industrial base. Brazil's sub-1% GDP trajectory in recent years caps upside.
Segmentation follows two non-geographic axes: chemistry (which determines cure speed, odor, bloom and medical suitability) and end-user industry (which determines volume cyclicality and certification burden). Healthcare is the highest-value pocket; footwear and furniture are the highest-volume.
| Parent segment | Children |
|---|---|
| Product Type | Alkoxy Ethyl-based; Ethyl Ester-based; Methyl Ester-based; Other |
| End-user Industry | Transportation; Footwear & Leather; Furniture; Consumer Goods; Healthcare; Electronics; Other |
Ethyl ester-based grades dominate volume because they balance cost and cure speed for furniture, footwear and consumer goods. Alkoxy ethyl-based grades command a premium where low odor and minimal blooming matter — cosmetics packaging, medical device assembly, electronics. Methyl ester-based products are the lowest-cost, most brittle tier and are losing share as buyers trade up.
Brazil leads the South America cyanoacrylate adhesives market with roughly 58% of regional value, followed by Argentina near 17% and the Rest of South America at about 25%. Brazil's lead rests on industrial breadth rather than any single end use.
Brazil
Argentina
Rest of South America (Chile, Colombia, Peru, Ecuador, Uruguay, Paraguay, Bolivia, Venezuela)
Brazil (~58%): electronics assembly, furniture manufacturing, footwear clusters and a growing medical-device base.
Argentina (~17%): footwear, leather goods and consumer adhesives; import-sensitive and FX-exposed.
Rest of South America (~25%): fragmented, distributor-led, with Chile and Colombia the most attractive secondary markets.
This divergence implies that a Brazil-centric go-to-market is rational, but single-country concentration exposes suppliers to BRL volatility, federal tax shifts and logistics bottlenecks at Santos and Itajaí. Argentina's import controls periodically distort regional pricing.
Growth is driven by healthcare adoption of tissue adhesives, electronics and furniture expansion in Brazil, and the shift toward low-bloom specialty grades. Restraints center on short shelf life, high-temperature performance ceilings and South America's macro volatility.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Healthcare / tissue adhesives | Driver | Strong | N-butyl-2-cyanoacrylate adoption in surgery lifts value per kilo |
| Electronics & furniture in Brazil | Driver | Strong | Assembly-line adhesives replace mechanical fasteners |
| Low-odor, low-bloom reformulation | Driver | Moderate | Premium pricing in cosmetics and medical device assembly |
| Short shelf life and storage sensitivity | Restraint | Strong | Inventory waste, cold-chain cost, distributor reluctance |
| High-temperature limits (~80–100°C) | Restraint | Strong | Disqualifies engine and aerospace applications |
| FX and macro volatility | Restraint | Moderate | Argentina import controls, BRL swings distort demand |
The balance favors growth but not uniformly. Healthcare and electronics are value-accretive and defensible; footwear and furniture are volume-led and price-sensitive. The shelf-life constraint is underappreciated: it structurally favors local blending and regional warehousing over container imports from Asia, which is a genuine moat for incumbents with Brazilian plants.
The South America cyanoacrylate adhesives market is moderately fragmented. Five multinationals — 3M, Henkel, H.B. Fuller, Arkema and Sika — set the technology and certification bar, while regional formulators and distributors compete on price and service.
| Company | Typical positioning | Regional strength | Moat |
|---|---|---|---|
| 3M | Premium industrial and medical | Broad distributor network | Brand and application engineering |
| Henkel (Loctite) | Full-line instant adhesives | Strong Brazil presence | Formulation breadth, OEM approvals |
| H.B. Fuller | Industrial assembly | Growing via acquisition | Customer intimacy, technical service |
| Arkema | Ester chemistry and medical grades | Supply-chain integration | Upstream monomer access |
| Sika | Construction and transport adjacency | Distribution reach | Cross-sell into construction |
Differentiation rests on three levers: medical-grade certification, low-bloom formulation capability, and local inventory depth to offset shelf-life constraints. Multinationals win on specification and approvals; regional formulators win on price and responsiveness. Our analysis suggests the certification moat in healthcare is the most durable barrier in the region.
Selection hinges on chemistry fit, not price per kilo. Buyers specifying medical or electronics applications must verify ISO 10993 biocompatibility, residual monomer limits, and batch traceability — certifications that narrow the qualified supplier set sharply and raise switching costs.
Shelf life is the dominant procurement risk. Cyanoacrylates polymerize on ambient moisture; distributors in hot, humid South American climates face accelerated degradation, so inventory turns and cold-chain discipline matter more than headline pricing. Bulk buyers should negotiate shelf-life guarantees and lot-level certificates of analysis.
Regulatory compliance is fragmented. Medical devices fall under national health-agency regimes (ANVISA in Brazil, ANMAT in Argentina), while industrial grades face chemical inventory and labeling rules. Importers should expect documentation friction at Brazilian customs and budget for local registration lead times. Switching costs are moderate for commodity grades and high for qualified medical grades — a key reason incumbents defend healthcare accounts.
The balance of evidence favors a selective-growth thesis: South America cyanoacrylate adhesives will compound near 4% through 2030, but value pools are shifting toward healthcare and low-bloom specialty grades while commodity ethyl ester volume remains price-led. Vendors treating the region as a commodity export market will see margin compression.
The strongest counter-argument is macro: Brazil's sub-1% GDP history, Argentina's FX distortions, and global forecasts as low as 2.81% CAGR suggest the 4% path could undershoot. We accept that risk for industrial grades but not for healthcare, where surgical adoption is demographic and less cyclical. A second counterpoint — that short shelf life favors imports — actually cuts the other way, reinforcing local blending.
Actionable strategy:
What would change our conclusion: sustained sub-2% Brazilian industrial growth, an ANVISA ruling restricting cyanoacrylate tissue adhesives, or a major monomer supply shock. While this overview covers market structure and directional dynamics, precise sub-segment forecasting — particularly medical-grade volume by procedure type and by state — requires the full report's granular datasets.
| Region | Market Share (%) |
|---|---|
| Brazil | 0.58% |
| Argentina | 0.17% |
| Rest of South America | 0.25% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.0% from 2020-2034 |
| Segmentation |
|
The market is expected to register a CAGR of approximately 4.0% between 2025 and 2030, reaching roughly 347 Million by 2030. Healthcare is the fastest-growing end-user industry, while commodity grades grow closer to GDP.
Brazil leads with roughly 58% of regional value, driven by electronics, furniture, footwear and a growing medical-device base. Argentina follows near 17%, with the rest of the continent making up about a quarter.
3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group and Sika AG are the major players. The market is moderately fragmented, with regional formulators competing on price and service.
Short shelf life and moisture sensitivity top the list, followed by performance limits above 80–100°C. Both favor local blending and inventory discipline over long-haul imports, especially in humid climates.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the cyanoacrylate value chain: ester and monomer suppliers, specialized instant-adhesive producers, contract formulators serving private-label footwear and furniture brands, and regional industrial distributors. Decision-maker designations included VP-level sourcing leaders, heads of formulation R&D, technical directors responsible for certification, and commercial operations leads managing Brazil and Southern Cone channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Ester Producers | 35% |
| Cyanoacrylate Formulators | 40% |
| Industrial Distributors & Traders | 25% |
Findings were cross-checked against UN Comtrade and WTO trade flows for adhesive esters, national customs datasets, corporate 10-K and annual investor filings, patent databases for low-bloom and medical-grade formulations, and technical standards from ISO and ASTM covering biocompatibility and bond-strength testing. National health-agency registration records informed healthcare qualification timelines.
Top-down allocation from macroeconomic and industrial-segment output was run simultaneously with bottom-up modeling of manufacturer capacity, product pricing, and end-use consumption by country, then reconciled against import and distributor sell-through data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |