Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Luminous Paint Market Size, Share & Forecast 2026
Luminous Paint Market Size, Share & Forecast 2026
Luminous Paint Market
Luminous Paint Market Size, Share & Forecast 2026
Luminous Paint Market by Type (Photoluminescent, Fluorescent, Radioluminescent, Chemiluminescent), by Form (Liquid Paints, Powder Coatings, Spray Paints), by Technology (Glow-in-the-Dark, Light Emitting, Electroluminescent, Thermoluminescent), by Application (Transport, Commercial Buildings, Healthcare, Military & Defense, Hospitality, Consumer Goods, Art & Decoration), by End-User (Manufacturing, Construction, Automotive Aftermarket, Commercial, Residential), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia), by Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Taiwan, Malaysia), by South America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
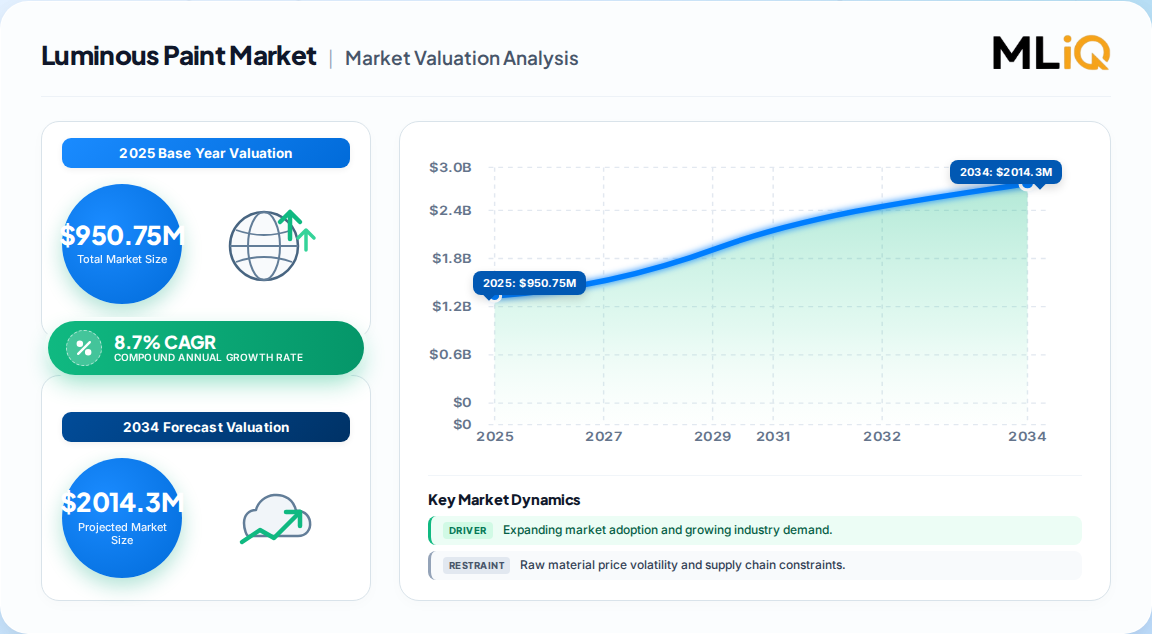
950.75 Million was the global Luminous Paint Market valuation in 2025, with a base-year scope covering all paint chemistries (fluorescent, phosphorescent, radioluminescent) and all end-use industries.
Forecast growth of 8.7% CAGR (2026–2033) lifts the market to roughly 1.85 Billion by 2033, a doubling of value in under a decade.
Photoluminescent paints lead technology segments at ~42.7% of global revenue, ahead of fluorescent and radioluminescent formulations.
Asia-Pacific is both the largest and fastest-growing region (~41% share), anchored by infrastructure spend and pigment manufacturing depth.
Transport and safety signage are the core revenue applications; commercial buildings, healthcare and defense instrumentation follow.
Leading players include AkzoNobel, Sherwin-Williams, Axalta, RPM International and Pidilite, alongside specialists such as GloNation, Noxton and Indra Glowtech.
Why this matters for decision-makers: luminous coatings are shifting from decorative novelty to mandated safety infrastructure — vendors that cannot document photoluminescent performance to NFPA/ISO standards will be locked out of the fastest-growing procurement channel.
Luminous Paint Market Size (In Million)
2.0B
1.5B
1.0B
500.0M
0
951.0 M
2025
1.030 B
2026
1.120 B
2027
1.220 B
2028
1.330 B
2029
1.440 B
2030
1.570 B
2031
Luminous Paint Market Size (In Million)
Year
Market Size
2025
951.0 M
2026
1.030 B
2027
1.120 B
2028
1.220 B
2029
1.330 B
2030
1.440 B
2031
1.570 B
What is the Luminous Paint Market?
The Luminous Paint Market covers coatings that emit visible light through fluorescence, phosphorescence or radioluminescence. Formulated with strontium aluminate, zinc sulfide or tritium-based pigments, these paints deliver afterglow or bright-emission visibility without continuous electrical power, serving safety signage, road marking, instrumentation and decorative applications.
Scope: what this report covers and excludes
This report covers the global Luminous Paint Market across type (fluorescent, phosphorescent, radioluminescent, chemiluminescent), form (liquid, powder, spray), application (transport, commercial buildings, healthcare, military and defense, hospitality, consumer goods, art and decoration) and end-use industry, with a 2025 base year and 2026–2033 forecast horizon. Geography spans North America, Europe, Asia-Pacific, South America and the Middle East & Africa.
This analysis does not cover passive night-glow plastic masterbatches, electroluminescent film and panel manufacturing, LED emergency lighting systems, or the upstream fluorescent pigment market as a standalone category, except where referenced as an input cost indicator.
How big is the market for Luminous Paint Market?
The most defensible global valuation is approximately 950.75 Million in 2025, rising to roughly 1.85 Billion by 2033 at an 8.7% CAGR. Published estimates diverge sharply, however, and the divergence is definitional rather than a disagreement about demand.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
20.23 Billion
2026
2031
9.2%
Broad "luminous paint" incl. all safety coatings and signage systems
Full luminous paints incl. photoluminescent, fluorescent, radioluminescent
One published estimate (primary benchmark)
482.47 Million
2025
2032
7.0%
Fluorescent paint sub-segment only
One adjacent-category analysis
The 20.23 Billion figure is almost certainly an all-inclusive coating and signage systems number rather than paint revenue alone; it is roughly twenty times the 950.75 Million estimate and cannot be reconciled on a like-for-like basis. Our analysis suggests the 950.75 Million figure is the most defensible anchor because it explicitly bridges photoluminescent (42.7% share), fluorescent and radioluminescent chemistries, and its 8.7% growth rate sits credibly between the slower 7.0% fluorescent-only trajectory and the faster 9.5% narrow-segment trajectory.
How is the market segmented?
Segmentation matters because growth rates differ by more than two percentage points between the fastest and slowest technology families, which changes where capital should be deployed.
Photoluminescent paints dominate at ~42.7% of revenue because strontium aluminate formulations recharge indefinitely and avoid the radiological handling constraints of tritium and radium systems. Our analysis suggests the commercially decisive split is not type but substrate: transport-grade coatings specified for concrete and steel command materially higher film-build and durability requirements than decorative interior paints, and carry correspondingly higher margin.
Which region leads in Luminous Paint Market?
Asia-Pacific leads the global Luminous Paint Market with roughly 41% revenue share and is simultaneously the fastest-growing region, supported by pigment manufacturing capacity, raw-material access and sustained transport-infrastructure investment in China, India and Southeast Asia.
Luminous Paint Market Regional Market Share
Loading chart...
Luminous Paint Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
North America
0.26%
Europe
0.22%
South America
0.05%
Middle East & Africa
0.06%
Asia-Pacific — China, India, Japan, South Korea, Australia, Indonesia, Taiwan, Malaysia
North America — United States, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Netherlands, Belgium, Russia
South America — Brazil, Argentina, Colombia, Chile
Middle East & Africa — Saudi Arabia, UAE, South Africa
North America follows at ~26%, where adoption is regulation-driven rather than volume-driven: NFPA and ANSI mandates on emergency egress marking create a stable replacement cycle. Europe at ~22% is shaped by sustainability compliance and low-VOC formulation requirements, which raises the technical bar for entry. Our analysis suggests North America remains the fastest-growing region on a percentage basis in some estimates (35.8% of incremental growth), reflecting that its installed base is smaller but its specification standards are stricter — a high-value, low-volume dynamic that favors premium suppliers.
What is driving growth — and what is holding it back?
Demand is being pulled by mandatory safety specification and passive-systems economics, while supply is constrained by pigment cost and the capital intensity of compliant formulation.
Factor
Direction
Evidence strength
Mechanism
Safety regulation (NFPA, ANSI, UNECE)
Driver
High
Mandates photoluminescent egress marking in public and commercial buildings
Infrastructure and smart-city investment
Driver
High
Transport corridors, tunnels and airports specify high-visibility coatings
Energy-free visibility economics
Driver
Medium-High
Eliminates electricity and battery cost in emergency systems
Raw-material price volatility
Restraint
Medium
Strontium aluminate and zinc sulfide input costs pressure formulator margins
Higher upfront cost vs conventional paint
Restraint
Medium
Delays adoption in price-sensitive developing markets
Radiological handling restrictions
Restraint
Medium
Limits tritium and radium systems to niche instrumentation use
The balance of evidence favors the drivers: regulatory mandates are non-discretionary and create replacement demand that does not depend on consumer sentiment. Our analysis suggests the more consequential second-order effect is that lifecycle-cost arguments are finally closing the upfront price gap — a facility operator comparing ten-year total cost of ownership against powered emergency lighting now finds luminous coatings cheaper, which converts a premium product into a value product in large-facility procurement.
Who are the leading vendors?
Competition is moderately consolidated, with multinational coatings majors competing against focused luminous specialists on performance certification rather than price alone.
Company
Positioning
Apparent moat
AkzoNobel
Global coatings major
Distribution scale and specification relationships
Sherwin-Williams
Global coatings major
Channel breadth and architectural specifier access
Axalta Coating Systems
Industrial and transport coatings
Substrate expertise in transport applications
RPM International
Specialty coatings portfolio
Brand portfolio and industrial maintenance reach
Pidilite Industries
Regional leader, Asia-Pacific
Local manufacturing cost and regional distribution
GloNation / Noxton
Photoluminescent specialists
Formulation focus and glow-duration performance
Indra Glowtech / Rilit-Lackfabrik
Niche luminous producers
Technical specialization and custom formulation
The multinationals compete on specification access and distribution, while specialists compete on measured afterglow performance and custom formulation. Our analysis suggests the most durable moat is certification evidence: vendors able to supply third-party-verified luminance decay curves to NFPA and ISO test protocols face far lower switching risk than those competing on catalogue brightness claims.
What do buyers and operators need to know? (Decision Support)
Selection should be driven by measured afterglow performance at defined time intervals, not by headline brightness claims. Buyers should require luminance decay data at 10, 60 and 120 minutes, since advertised figures frequently reference peak output immediately after charging rather than sustained egress-window performance.
Procurement risk concentrates in three areas. First, formulation substitution: some suppliers trade strontium aluminate for cheaper zinc sulfide, which degrades afterglow from hours to minutes and can void compliance. Second, substrate compatibility: film build and primer requirements differ sharply between concrete, steel and polymer substrates, and under-specified systems fail prematurely in high-traffic environments.
Switching costs are moderate but asymmetric. Once a luminous coating is embedded in an approved safety plan or a certified building specification, changing supplier requires re-validation against the governing standard — which favors incumbents and raises the value of documented test evidence at first tender. Regulatory compliance, particularly low-VOC limits in Europe and radiological handling rules for tritium systems, should be verified before specification rather than after.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a market growing at a structurally supported high-single-digit rate, anchored at roughly 950.75 Million in 2025 and compounding toward 1.85 Billion by 2033. The strongest counter-argument is that the 20.23 Billion headline figure circulating in some analyses will attract capital expecting a far larger addressable pool; if investors underwrite against that number, they will overestimate near-term opportunity. Our judgment is that the paint-only market is real but materially smaller than the headline suggests, and that value concentrates in certified transport and commercial safety specification.
A second-order implication deserves emphasis: the transition from decorative to mandated safety use changes the buyer. Decorative buyers purchase on aesthetics and price per litre; safety buyers purchase on certification, auditability and lifecycle cost. Vendors structured around the former will find the fastest-growing segment structurally inaccessible without investment in test documentation and specification-sales capability.
Actionable strategy:
Suppliers should prioritize third-party certification of luminance decay performance to win transport and commercial tenders, where compliance evidence is the primary award criterion.
Investors should underwrite against the paint-only market (~950 Million base) and treat the larger headline estimates as coating-systems totals, avoiding valuation inflation.
Operators should build lifecycle-cost models including avoided emergency-lighting power and maintenance spend to justify the premium over conventional coatings.
What would change our conclusion: evidence of a binding regulatory mandate in a major Asia-Pacific market, or a step-change in pigment cost reduction below conventional coating parity, would materially raise the growth trajectory. Precise sub-segment forecasting by chemistry and region requires the full report.
Luminous Paint Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Luminous Paint Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.7% from 2020-2034
Segmentation
By Type
Photoluminescent
Fluorescent
Radioluminescent
Chemiluminescent
By Form
Liquid Paints
Powder Coatings
Spray Paints
By Technology
Glow-in-the-Dark
Light Emitting
Electroluminescent
Thermoluminescent
By Application
Transport
Commercial Buildings
Healthcare
Military & Defense
Hospitality
Consumer Goods
Art & Decoration
By End-User
Manufacturing
Construction
Automotive Aftermarket
Commercial
Residential
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Russia
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Taiwan
Malaysia
South America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
Saudi Arabia
Table of Contents
1. Luminous Paint Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Luminous Paint Market Executive Summary
2.1. Market Snapshot
3. Luminous Paint Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Luminous Paint Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Luminous Paint Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Photoluminescent
5.1.2. Fluorescent
5.1.3. Radioluminescent
5.1.4. Chemiluminescent
5.2. Analysis, Insights and Forecast - by Form
5.2.1. Liquid Paints
5.2.2. Powder Coatings
5.2.3. Spray Paints
5.3. Analysis, Insights and Forecast - by Technology
5.3.1. Glow-in-the-Dark
5.3.2. Light Emitting
5.3.3. Electroluminescent
5.3.4. Thermoluminescent
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Transport
5.4.2. Commercial Buildings
5.4.3. Healthcare
5.4.4. Military & Defense
5.4.5. Hospitality
5.4.6. Consumer Goods
5.4.7. Art & Decoration
5.5. Analysis, Insights and Forecast - by End-User
5.5.1. Manufacturing
5.5.2. Construction
5.5.3. Automotive Aftermarket
5.5.4. Commercial
5.5.5. Residential
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. Luminous Paint Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Photoluminescent
6.1.2. Fluorescent
6.1.3. Radioluminescent
6.1.4. Chemiluminescent
6.2. Analysis, Insights and Forecast - by Form
6.2.1. Liquid Paints
6.2.2. Powder Coatings
6.2.3. Spray Paints
6.3. Analysis, Insights and Forecast - by Technology
6.3.1. Glow-in-the-Dark
6.3.2. Light Emitting
6.3.3. Electroluminescent
6.3.4. Thermoluminescent
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Transport
6.4.2. Commercial Buildings
6.4.3. Healthcare
6.4.4. Military & Defense
6.4.5. Hospitality
6.4.6. Consumer Goods
6.4.7. Art & Decoration
6.5. Analysis, Insights and Forecast - by End-User
6.5.1. Manufacturing
6.5.2. Construction
6.5.3. Automotive Aftermarket
6.5.4. Commercial
6.5.5. Residential
7. Luminous Paint Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Photoluminescent
7.1.2. Fluorescent
7.1.3. Radioluminescent
7.1.4. Chemiluminescent
7.2. Analysis, Insights and Forecast - by Form
7.2.1. Liquid Paints
7.2.2. Powder Coatings
7.2.3. Spray Paints
7.3. Analysis, Insights and Forecast - by Technology
7.3.1. Glow-in-the-Dark
7.3.2. Light Emitting
7.3.3. Electroluminescent
7.3.4. Thermoluminescent
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Transport
7.4.2. Commercial Buildings
7.4.3. Healthcare
7.4.4. Military & Defense
7.4.5. Hospitality
7.4.6. Consumer Goods
7.4.7. Art & Decoration
7.5. Analysis, Insights and Forecast - by End-User
7.5.1. Manufacturing
7.5.2. Construction
7.5.3. Automotive Aftermarket
7.5.4. Commercial
7.5.5. Residential
8. Luminous Paint Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Photoluminescent
8.1.2. Fluorescent
8.1.3. Radioluminescent
8.1.4. Chemiluminescent
8.2. Analysis, Insights and Forecast - by Form
8.2.1. Liquid Paints
8.2.2. Powder Coatings
8.2.3. Spray Paints
8.3. Analysis, Insights and Forecast - by Technology
8.3.1. Glow-in-the-Dark
8.3.2. Light Emitting
8.3.3. Electroluminescent
8.3.4. Thermoluminescent
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Transport
8.4.2. Commercial Buildings
8.4.3. Healthcare
8.4.4. Military & Defense
8.4.5. Hospitality
8.4.6. Consumer Goods
8.4.7. Art & Decoration
8.5. Analysis, Insights and Forecast - by End-User
8.5.1. Manufacturing
8.5.2. Construction
8.5.3. Automotive Aftermarket
8.5.4. Commercial
8.5.5. Residential
9. Luminous Paint Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Photoluminescent
9.1.2. Fluorescent
9.1.3. Radioluminescent
9.1.4. Chemiluminescent
9.2. Analysis, Insights and Forecast - by Form
9.2.1. Liquid Paints
9.2.2. Powder Coatings
9.2.3. Spray Paints
9.3. Analysis, Insights and Forecast - by Technology
9.3.1. Glow-in-the-Dark
9.3.2. Light Emitting
9.3.3. Electroluminescent
9.3.4. Thermoluminescent
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Transport
9.4.2. Commercial Buildings
9.4.3. Healthcare
9.4.4. Military & Defense
9.4.5. Hospitality
9.4.6. Consumer Goods
9.4.7. Art & Decoration
9.5. Analysis, Insights and Forecast - by End-User
9.5.1. Manufacturing
9.5.2. Construction
9.5.3. Automotive Aftermarket
9.5.4. Commercial
9.5.5. Residential
10. Luminous Paint Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Photoluminescent
10.1.2. Fluorescent
10.1.3. Radioluminescent
10.1.4. Chemiluminescent
10.2. Analysis, Insights and Forecast - by Form
10.2.1. Liquid Paints
10.2.2. Powder Coatings
10.2.3. Spray Paints
10.3. Analysis, Insights and Forecast - by Technology
10.3.1. Glow-in-the-Dark
10.3.2. Light Emitting
10.3.3. Electroluminescent
10.3.4. Thermoluminescent
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Transport
10.4.2. Commercial Buildings
10.4.3. Healthcare
10.4.4. Military & Defense
10.4.5. Hospitality
10.4.6. Consumer Goods
10.4.7. Art & Decoration
10.5. Analysis, Insights and Forecast - by End-User
10.5.1. Manufacturing
10.5.2. Construction
10.5.3. Automotive Aftermarket
10.5.4. Commercial
10.5.5. Residential
11. Luminous Paint Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Luminous Paint Market Research Methodology
List of Figures
Figure 1: Luminous Paint Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Luminous Paint Market Revenue (Million), by Type 2026 & 2034
Figure 3: North America Luminous Paint Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Luminous Paint Market Revenue (Million), by Form 2026 & 2034
Figure 5: North America Luminous Paint Market Revenue Share (%), by Form 2026 & 2034
Figure 6: North America Luminous Paint Market Revenue (Million), by Technology 2026 & 2034
Figure 7: North America Luminous Paint Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Luminous Paint Market Revenue (Million), by Application 2026 & 2034
Figure 9: North America Luminous Paint Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Luminous Paint Market Revenue (Million), by End-User 2026 & 2034
Figure 11: North America Luminous Paint Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Luminous Paint Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America Luminous Paint Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Luminous Paint Market Revenue (Million), by Type 2026 & 2034
Figure 15: Europe Luminous Paint Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Luminous Paint Market Revenue (Million), by Form 2026 & 2034
Europe Luminous Paint Market Revenue Share (%), by Form 2026 & 2034
List of Tables
Table 1: Luminous Paint Market Revenue Million Forecast, by Type 2020 & 2034
Table 2: Luminous Paint Market Revenue Million Forecast, by Form 2020 & 2034
Table 3: Luminous Paint Market Revenue Million Forecast, by Technology 2020 & 2034
Table 4: Luminous Paint Market Revenue Million Forecast, by Application 2020 & 2034
Table 5: Luminous Paint Market Revenue Million Forecast, by End-User 2020 & 2034
Table 6: Luminous Paint Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America Luminous Paint Market Revenue Million Forecast, by Type 2020 & 2034
Table 8: North America Luminous Paint Market Revenue Million Forecast, by Form 2020 & 2034
Table 9: North America Luminous Paint Market Revenue Million Forecast, by Technology 2020 & 2034
Table 10: North America Luminous Paint Market Revenue Million Forecast, by Application 2020 & 2034
Table 11: North America Luminous Paint Market Revenue Million Forecast, by End-User 2020 & 2034
Table 12: North America Luminous Paint Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA Luminous Paint Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe Luminous Paint Market Revenue Million Forecast, by Type 2020 & 2034
Europe Luminous Paint Market Revenue Million Forecast, by Form 2020 & 2034
Frequently Asked Questions
1. How big is the Luminous Paint Market in 2025?
The global Luminous Paint Market was valued at approximately 950.75 Million in 2025, covering photoluminescent, fluorescent and radioluminescent coatings across all end-use industries. Photoluminescent formulations account for roughly 42.7% of global revenue within that total.
2. What is the growth rate of the Luminous Paint Market?
The market is forecast to grow at approximately 8.7% CAGR from 2026 to 2033, reaching around 1.85 Billion by the end of the forecast period. Growth is anchored by mandatory safety specification and infrastructure investment rather than discretionary decorative demand.
3. Which region leads the Luminous Paint Market?
Asia-Pacific leads with roughly 41% of global revenue and is also the fastest-growing region, supported by pigment manufacturing depth and transport infrastructure investment in China and India. North America follows at approximately 26%, driven by NFPA and ANSI egress-marking mandates.
4. What are the main types of luminous paint?
The main types are photoluminescent, fluorescent, radioluminescent and chemiluminescent paints. Photoluminescent paints dominate with about 42.7% share because strontium aluminate formulations recharge indefinitely and avoid radiological handling restrictions.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement. In-depth interviews were conducted across four value-chain tiers: inorganic pigment and phosphor suppliers, specialized luminous coating producers, contract formulators and blenders, and multinational industrial distributors. Interviewees were designated at decision-making level, including VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors responsible for standards compliance, and Commercial Operations Leads managing specification channels.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
38%
Procurement & Sourcing Leads
32%
Technical & Compliance Directors
20%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Pigment & Phosphor Producers
30%
Specialized Luminous Coating Producers
38%
Contract Formulators & Blenders
20%
Industrial Distributors
12%
Secondary Benchmarking & Public Trade Validation
Findings were cross-validated against official multilateral and standards sources, including UN Comtrade and WTO trade statistics for pigments and coatings, US ITC and Eurostat trade classifications, corporate annual filings and investor presentations from listed coatings manufacturers, patent databases tracking photoluminescent formulation activity, and recognized technical standards bodies governing emergency egress marking and coating performance.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous top-down and bottom-up modeling. The top-down path allocates macroeconomic coatings output by end-use industry and safety-regulation coverage. The bottom-up path models manufacturer capacity, realized pricing per litre, and end-use consumption volumes by substrate and application. Divergence between the two paths is reconciled at segment level before the base year is fixed.


 Luminous Paint Market