 Gear Oil Market
 Size, Share & Forecast 2026-2035
Updated On : Nov 18, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Gear Oil Market

Khageshwar Rongkali
Senior Analyst

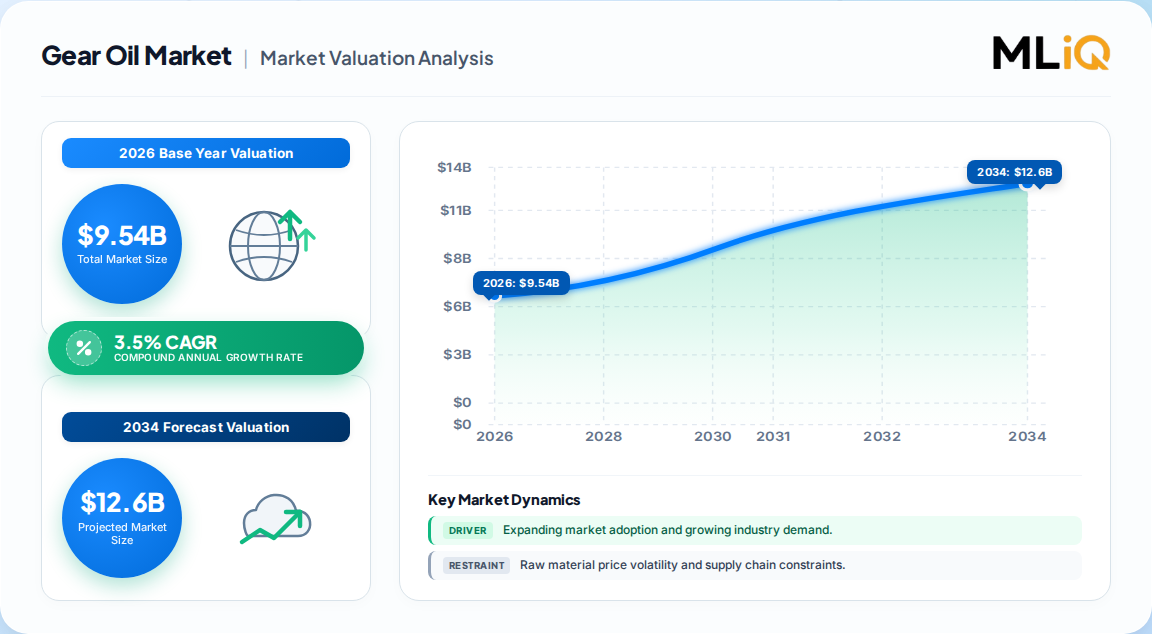
| Year | Market Size |
|---|---|
| 2025 | 9.250 B |
| 2026 | 9.540 B |
| 2035 | 13.05 B |

The Gear Oil Market encompasses the production and sale of specialized lubricants designed to reduce friction, wear, and heat in gear systems, including transmissions, differentials, and industrial gearboxes. These fluids are critical for the performance, durability, and efficiency of machinery across automotive, manufacturing, and energy sectors.
This report provides a comprehensive analysis of the global Gear Oil Market, covering market sizing, segmentation by product type, base oil, and end-use industry, regional dynamics, competitive landscape, and key trends. It includes historical data, current estimates for 2026, and forecasts to 2035. This analysis does not cover adjacent lubricant categories such as engine oils, hydraulic fluids, or greases, except where relevant for market context.
The global Gear Oil Market size was estimated at USD 9.54 Billion in 2026, with forecasts projecting steady growth to USD 13.05 Billion by 2035, reflecting a 3.5% CAGR. This growth is underpinned by sustained demand from industrial automation, automotive production, and infrastructure development across key regions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 9.25 Billion | 2025 | 2035 | 3.5% | Global gear oil, all types | One published estimate |
| USD 9.05 Billion | 2026 | 2030 | 3.7% | Global gear oil, by product & base oil | A competing analysis |
| USD 3.81 Billion | 2024 | 2035 | 3.34% | Automotive gear oil only | A third-party analysis |
Our analysis suggests that the USD 9.54 Billion for 2026 is the most defensible figure, as it aligns with the broader lubricants market trajectory and incorporates the latest data on industrial and automotive demand. The variance in estimates stems from differences in scope, particularly the inclusion of industrial versus automotive-only gear oils.
The Gear Oil Market is segmented by product type, base oil, and end-user industry. These segments provide a granular view of demand drivers and competitive dynamics across different applications and chemistries.
| Parent Segment | Children Segments |
|---|---|
| By Product Type | Transportation, Industrial |
| By Base Oil | Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil |
| By End User | Manufacturing, Construction, Agriculture, Oil & Gas, Mining, Other End Users |
Synthetic and semi-synthetic oils are gaining share due to superior performance and longer drain intervals. The transportation segment remains the largest, but industrial applications are growing faster, driven by automation and stricter maintenance standards.
Asia-Pacific is the leading and fastest-growing region in the Gear Oil Market, expected to account for 36% of global share by 2035. This dominance is fueled by rapid industrialization, expanding automotive production, and infrastructure development in countries like China and India.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.36% |
| North America | 0.27% |
| Europe | 0.22% |
| South America | 0.08% |
| Middle East & Africa | 0.07% |
North America holds the second-largest share, at 27% by 2035, driven by a resurgent automotive sector and oil & gas activities. Europe remains a significant market, with a focus on high-performance and eco-friendly lubricants.
The Gear Oil Market is primarily driven by industrial automation, automotive production growth, and the adoption of synthetic lubricants. However, challenges such as raw material price volatility, the rise of automatic lubrication systems, and environmental concerns are restraining faster expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Industrial automation | Driver | High | Increases machinery utilization and demand for high-performance gear oils |
| Automotive production growth | Driver | High | Expands demand for transportation gear oils |
| Shift to synthetic & bio-based oils | Driver | Medium | Premiumization and longer drain intervals drive value growth |
| Raw material price volatility | Restraint | Medium | Uncertain feedstock costs impact margins and pricing |
| Adoption of automatic lubrication systems | Restraint | Medium | Reduces lubricant consumption per machine |
| Environmental regulations | Restraint | High | Compliance costs and shift to eco-friendly formulations |
Our analysis indicates that the net balance favors growth, as industrial automation and automotive demand in emerging economies outweigh the restraints. However, vendors must navigate price volatility and regulatory pressures by focusing on high-margin, sustainable products.
The Gear Oil Market is highly competitive, with ExxonMobil, Shell, Chevron, BP, and TotalEnergies leading through extensive distribution networks, strong brand equity, and continuous innovation in synthetic and bio-based formulations. These top five players collectively hold around 40% of the global lubricants market, with a significant share in gear oils.
| Company | Headquarters | Key Segments | Strategic Focus |
|---|---|---|---|
| ExxonMobil | USA | Synthetic, Mineral | R&D, global distribution |
| Shell | Netherlands | Synthetic, Bio-based | Sustainability, premium products |
| Chevron | USA | Mineral, Synthetic | Industrial & automotive |
| BP (Castrol) | UK | Synthetic, Semi-synthetic | Brand strength, OEM partnerships |
| TotalEnergies | France | Synthetic, Bio-based | Innovation, emerging markets |
Differentiation is increasingly centered on technology and sustainability. Companies investing in bio-based and high-performance synthetic gear oils are better positioned to capture premium segments and comply with tightening environmental regulations.
Buyers and operators must prioritize performance specifications, compatibility, and lifecycle costs when selecting gear oils. Key criteria include OEM approvals, viscosity grade, and thermal stability. Procurement risks include supply chain disruptions and price volatility, particularly for synthetic base stocks. Switching costs can be significant due to the need for system flushing and potential warranty implications. Regulatory compliance, especially with evolving emissions and waste disposal standards, is critical. Operators should also consider the total cost of ownership, as higher-quality synthetic oils may offer longer drain intervals and reduce maintenance downtime.
The balance of evidence favors a positive outlook for the Gear Oil Market, with steady growth driven by industrial automation and automotive demand. However, the market is undergoing a structural shift toward synthetic and bio-based lubricants, which will reshape competitive dynamics. The strongest counter-argument is that the rise of electric vehicles could reduce demand for traditional gear oils, but this is likely to be offset by new fluid requirements for EV drivetrains and increasing industrial applications.
Our analysis suggests that vendors should prioritize the development of high-performance, sustainable gear oils to capture premium segments and comply with regulations. Investments in R&D for bio-based formulations and partnerships with OEMs will be critical. Operators should consider transitioning to synthetic oils to reduce maintenance costs and improve equipment longevity, despite higher upfront costs.
Actionable Strategy:
What would change our conclusion? A faster-than-expected adoption of automatic lubrication systems or a sharp decline in automotive production could dampen demand. Conversely, accelerated industrialization in emerging markets or breakthroughs in bio-based lubricant technology could drive upside.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.5% from 2020-2034 |
| Segmentation |
|
The global Gear Oil Market was valued at approximately USD 9.54 Billion in 2026 and is forecast to reach USD 13.05 Billion by 2035.
The Gear Oil Market is projected to grow at a CAGR of 3.5% from 2026 to 2035, driven by industrial automation and automotive demand.
Asia-Pacific is the largest and fastest-growing region, expected to hold 36% of the global market share by 2035, fueled by industrialization and automotive production.
The market is segmented by product type (transportation, industrial), base oil (mineral, synthetic, semi-synthetic, bio-based), and end-user (manufacturing, construction, agriculture, oil & gas, mining).
Leading companies include ExxonMobil, Shell, Chevron, BP, and TotalEnergies, who dominate through extensive distribution networks and continuous innovation in synthetic and bio-based formulations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split to ensure data accuracy and depth. We conducted in-depth interviews with key stakeholders across the value chain, including raw material suppliers, specialized gear oil producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This primary research provided granular insights into demand drivers, procurement strategies, and competitive dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 45% |
| Specialized Formulators & Blenders | 35% |
| Industrial Distributors | 20% |
We extensively utilized official multilateral trade databases such as UN Comtrade, WTO, US ITC, and Eurostat to validate cross-border trade flows and regional consumption patterns. Corporate annual filings (10-K, SEC filings, investor presentations) from leading companies were analyzed to map production capacities and market shares. Patent databases and technical standards from industry associations were reviewed to track innovation trends. All secondary sources were cross-referenced to ensure reliability.
We employed simultaneous Top-Down and Bottom-Up modeling approaches. The Top-Down method allocated macroeconomic indicators and industry segment data to derive market size, while the Bottom-Up method aggregated manufacturer capacity, product pricing, and end-use consumption data. This triangulation ensured a robust and defensible market estimate, with discrepancies resolved through further validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |