Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Graphite Anode for LIB Industry Market Outlook 2026
Graphite Anode for LIB Industry
Graphite Anode for LIB Industry Market Outlook 2026
Graphite Anode for LIB Industry by Anode Material Type (Synthetic Graphite, Natural Graphite), by End-Use Application (Electric Vehicles, Energy Storage Systems, Consumer Electronics, Others), by Cell Format (Cylindrical, Prismatic, Pouch), by Purity Grade (Battery-grade coated, Uncoated battery-grade, High-purity 99.95%+), by Asia Pacific (China, Japan, South Korea, India), by Europe (Germany, Sweden, Poland, France), by North America (USA, Canada, Mexico), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, Mozambique) Forecast 2026-2034
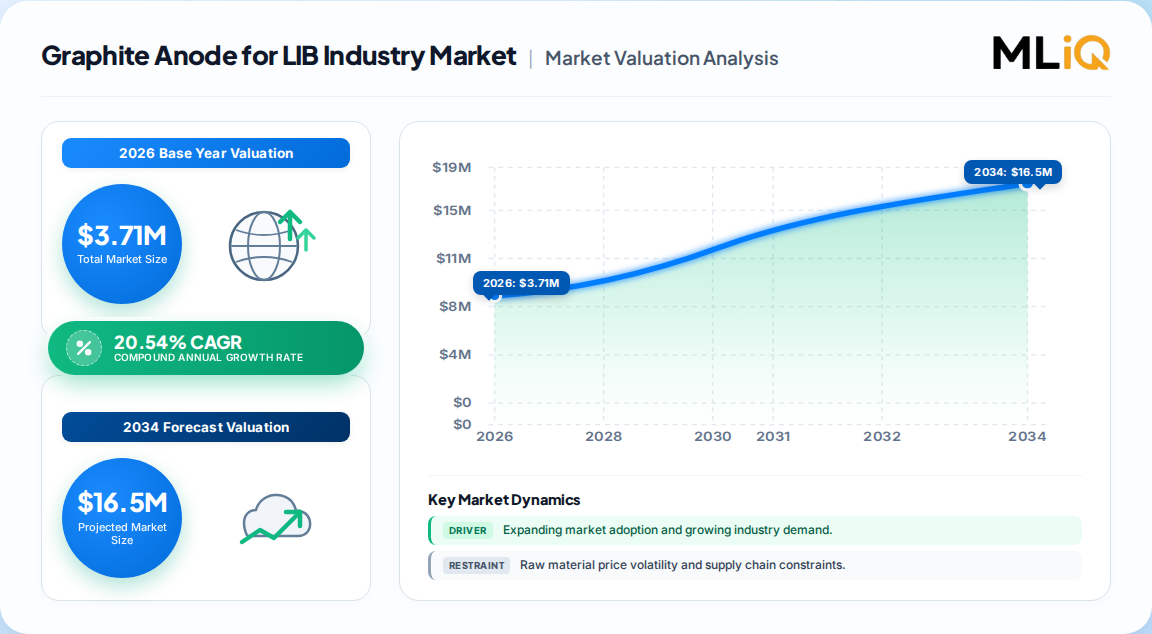
The graphite anode for LIB market is estimated at 3.71 million tons in 2026, on a volume basis, across all battery cell chemistries globally; a competing estimate puts 2026 at 4.2 million tons.
Forecast volume reaches 9.45 million tons by 2031, implying a fixed 20.54% CAGR over the 2026–2031 window.
Synthetic graphite held 56.89% of 2025 anode volume, but natural graphite is projected to expand at 25.21% CAGR through 2031.
Electric vehicles absorbed 71.12% of 2025 anode volume; energy storage systems are the fastest secondary pool at 22.23% CAGR.
Asia-Pacific accounted for 74.22% of 2025 shipments; Europe is the fastest-growing region at 28.12% CAGR, with the Americas scaling from a small base.
Leading suppliers include BTR New Materials, Shanshan, POSCO Chemical, Putailai and SGL Carbon; concentration is medium, with Chinese producers setting the reference price curve.
Why this matters for decision-makers: anode is now an export-controlled input, so offtake security and qualification of non-China capacity matter more than unit price alone.
Graphite Anode for LIB Industry Market Size (In Million)
10.0M
8.0M
6.0M
4.0M
2.0M
0
3.000 M
2025
4.000 M
2026
4.000 M
2027
5.000 M
2028
7.000 M
2029
8.000 M
2030
9.000 M
2031
Graphite Anode for LIB Industry Market Size (In Million)
Year
Market Size
2025
3.000 M
2026
4.000 M
2027
4.000 M
2028
5.000 M
2029
7.000 M
2030
8.000 M
2031
9.000 M
What is the Graphite Anode for LIB Industry market?
The graphite anode for LIB market covers the battery-grade graphite powders — natural, spheroidised and purified, plus synthetic graphitised material — that serve as the negative electrode active material in lithium-ion cells, sold by tonnage and value to cell makers serving EVs, storage and electronics.
Scope: what this report covers and excludes
The scope is global: anode active material shipments by tonnage and value across synthetic and natural graphite, segmented by EV, stationary storage, consumer electronics and other end uses, with 2021 historicals and 2026–2031 forecasts. This analysis does not cover graphite mining and flake concentrate as standalone commodities, silicon-dominant anode active material, cell manufacturing, or recycled anode recovery economics.
How big is the market for Graphite Anode for LIB Industry market?
Volume-based estimates converge tightly on the base year but diverge sharply at the horizon, because the two published series use different terminal years and different definitions of what counts as finished anode material rather than coated or blended product.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
3.08 million tons, rising to 3.71 million tons in 2026
2025
2031 (9.45 mn t)
20.54%
Anode active material, synthetic plus natural, volume only
One published estimate
3.5 million tons, rising to 4.2 million tons in 2026
2025
2035 (23.3 mn t)
20.9%
Anode material incl. blended product, volume only
A competing analysis
The 2026 starting points differ by roughly 13%, a gap consistent with scope rather than demand disagreement. Our analysis suggests the 3.71 million ton figure is the more defensible base because it is anchored to battery cell capacity build schedules and segment shares, while the higher figure likely includes silicon-blended and toll-processed tonnage. Either way, the implication is identical: anode demand roughly doubles every three and a half years, so qualification capacity, not demand, becomes the binding constraint.
How is the market segmented?
Segmentation is defined by material route and cell application; the material split matters most commercially because synthetic and natural graphite carry different cost curves, purification footprints and qualification cycles.
Parent segment
Children
By Anode Material Type
Synthetic Graphite, Natural Graphite
By End-Use Application
Electric Vehicles, Energy Storage Systems, Consumer Electronics, Others
Synthetic dominance in fast-charging and high-energy cells persists on performance grounds, not cost. Natural graphite's 25.21% projected CAGR is a second-order effect of LFP adoption in mid-range EVs and long-duration storage, where thicker electrodes and 4–8 hour discharge windows favour lower-cost natural material.
Which region leads in Graphite Anode for LIB Industry market?
Asia-Pacific leads decisively, with China alone hosting the majority of global spheroidisation and graphitisation capacity; Europe is the fastest-growing region but starts from a modest base.
Graphite Anode for LIB Industry Regional Market Share
Loading chart...
Graphite Anode for LIB Industry Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.74%
Europe
0.11%
North America
0.09%
South America
0.03%
Middle East & Africa
0.03%
Asia-Pacific
China
Japan
South Korea
India
Europe
Germany
Sweden
Poland
France
North America
United States
Canada
Mexico
Latin America
Brazil
Argentina
Middle East & Africa
South Africa
Mozambique
Region
2025 share
Asia-Pacific
74.22%
Europe
11.18%
North America
8.71%
Rest of World
5.89%
Europe's 28.12% CAGR reflects gigafactory localisation and carbon border adjustment pressure rather than demand growth. Our analysis suggests the more interesting signal is the Americas: US imports of natural and synthetic anode material reached 43,400 tons in the first eight months of 2025, up from 28,100 tons a year earlier, indicating that reshoring is currently a sourcing shift, not yet a production shift.
What is driving growth — and what is holding it back?
Growth is dominated by EV cell capacity additions and storage buildout, while the binding restraints are trade policy and the emissions intensity of graphitisation rather than raw material scarcity.
Factor
Direction
Evidence strength
Mechanism
EV-driven cell capacity expansions
Driver
Strong
Multi-year offtake contracts convert cell pipelines into committed anode tonnage
Chinese synthetic cost scale-up
Driver
Strong
Graphitisation co-located with captive power and needle-coke feedstock
Domestic content incentives (IRA 30D, EU, India PLI)
Driver
Moderate
Redirects sourcing to non-China capacity at a cost premium
High-rate pouch and prismatic ESS architectures
Driver
Moderate
Thicker electrodes raise anode mass per cell
China export licensing on spheroidised graphite
Restraint
Strong
Licensing uncertainty blocks Western importers, per EU trade barrier records
Emissions scrutiny on graphitisation furnaces
Restraint
Moderate
Permitting and CBAM costs raise non-China unit economics
The balance favours demand. Every announced EV and storage line is already contracted, whereas supply additions outside China need three to four years and face licensing risk. Decision-makers should treat anode as a regulated dual-use material: China's export control regime, extended in December 2023, consolidated in December 2024, and further tightened in October 2025 before suspension, remains active for synthetic spheroidised graphite. That is a structural premium on qualified non-China volumes.
Who are the leading vendors?
Chinese producers dominate volume, while POSCO Chemical and SGL Carbon anchor the non-China option set; differentiation rests on qualification depth, coating IP and feedstock access rather than price alone.
Company
Home base
Position
BTR New Materials Group
China
Volume leader in synthetic and natural anode
Shanshan Corporation
China
Integrated anode, broad customer base
POSCO Chemical
South Korea
Non-China synthetic capacity, captive needle coke
Putailai (Shanghai)
China
Anode plus coating and process equipment
SGL Carbon
Germany
Specialty synthetic, European supply
Resonac
Japan
High-purity synthetic, performance-led
Moat analysis: Chinese scale players have cost advantages from co-located graphitisation furnaces, whereas European and Korean vendors monetise sustainability attributes and supply-security premiums. The weakest position is a mid-sized producer without captive feedstock or a coating patent portfolio.
What do buyers and operators need to know?
Buyers should prioritise qualification portability over headline price. An anode grade qualified on one cell format rarely transfers without re-validation, so dual-sourcing carries real engineering cost, and switching suppliers mid-programme is typically measured in quarters, not weeks. Procurement teams should therefore contract capacity, not spot tonnage, and secure material origin documentation early.
Compliance is the second gate. Export licensing on Chinese spheroidised synthetic graphite, plus carbon border adjustment reporting in Europe, means landed cost now depends on documentation quality. Operators should model a realistic non-China premium rather than assume parity by 2028. Finally, specification drift toward fast-charge capability raises the value of particle-size control; buyers should weight supplier process capability over catalogue purity figures.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours demand certainty over supply certainty. Anode tonnage roughly doubles from 2026 to 2031 on both published series, which means anyone modelling a softening anode price is effectively assuming a supply response that trade policy currently prevents outside China.
The strongest counter-argument is technological: silicon-blended anodes could displace meaningful graphite tonnage in premium EVs, and sodium-ion could absorb part of the storage pool. Both are real, but neither reaches scale within the forecast window in volumes that offset LFP-driven graphite demand. Our judgement is that substitution risk is concentrated in the 2030s, while qualification risk is immediate.
Actionable strategy:
Secure multi-year offtake with volume bands, not fixed tonnage, and tie pricing to a documented origin-adjusted index.
Qualify at least one non-China anode source before 2028, accepting a modest premium as insurance against licensing disruption.
Weight investment toward natural graphite purification and low-emission graphitisation, where policy incentives and cost curves align.
What would change our conclusion: a durable removal of Chinese export licensing, or silicon anode penetration above 10% of EV anode volume before 2030, would compress the non-China premium and weaken the supply-security thesis.
Graphite Anode for LIB Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Graphite Anode for LIB Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 20.54% from 2020-2034
Segmentation
By Anode Material Type
Synthetic Graphite
Natural Graphite
By End-Use Application
Electric Vehicles
Energy Storage Systems
Consumer Electronics
Others
By Cell Format
Cylindrical
Prismatic
Pouch
By Purity Grade
Battery-grade coated
Uncoated battery-grade
High-purity 99.95%+
By Geography
Asia Pacific
China
Japan
South Korea
India
Europe
Germany
Sweden
Poland
France
North America
USA
Canada
Mexico
Latin America
Brazil
Argentina
Middle East & Africa
South Africa
Mozambique
Table of Contents
1. Graphite Anode for LIB Industry Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Graphite Anode for LIB Industry Executive Summary
2.1. Market Snapshot
3. Graphite Anode for LIB Industry Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Graphite Anode for LIB Industry Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Graphite Anode for LIB Industry Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Anode Material Type
5.1.1. Synthetic Graphite
5.1.2. Natural Graphite
5.2. Analysis, Insights and Forecast - by End-Use Application
5.2.1. Electric Vehicles
5.2.2. Energy Storage Systems
5.2.3. Consumer Electronics
5.2.4. Others
5.3. Analysis, Insights and Forecast - by Cell Format
5.3.1. Cylindrical
5.3.2. Prismatic
5.3.3. Pouch
5.4. Analysis, Insights and Forecast - by Purity Grade
5.4.1. Battery-grade coated
5.4.2. Uncoated battery-grade
5.4.3. High-purity 99.95%+
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. Europe
5.5.3. North America
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Graphite Anode for LIB Industry Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Anode Material Type
6.1.1. Synthetic Graphite
6.1.2. Natural Graphite
6.2. Analysis, Insights and Forecast - by End-Use Application
6.2.1. Electric Vehicles
6.2.2. Energy Storage Systems
6.2.3. Consumer Electronics
6.2.4. Others
6.3. Analysis, Insights and Forecast - by Cell Format
6.3.1. Cylindrical
6.3.2. Prismatic
6.3.3. Pouch
6.4. Analysis, Insights and Forecast - by Purity Grade
6.4.1. Battery-grade coated
6.4.2. Uncoated battery-grade
6.4.3. High-purity 99.95%+
7. Graphite Anode for LIB Industry Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Anode Material Type
7.1.1. Synthetic Graphite
7.1.2. Natural Graphite
7.2. Analysis, Insights and Forecast - by End-Use Application
7.2.1. Electric Vehicles
7.2.2. Energy Storage Systems
7.2.3. Consumer Electronics
7.2.4. Others
7.3. Analysis, Insights and Forecast - by Cell Format
7.3.1. Cylindrical
7.3.2. Prismatic
7.3.3. Pouch
7.4. Analysis, Insights and Forecast - by Purity Grade
7.4.1. Battery-grade coated
7.4.2. Uncoated battery-grade
7.4.3. High-purity 99.95%+
8. Graphite Anode for LIB Industry North America Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Anode Material Type
8.1.1. Synthetic Graphite
8.1.2. Natural Graphite
8.2. Analysis, Insights and Forecast - by End-Use Application
8.2.1. Electric Vehicles
8.2.2. Energy Storage Systems
8.2.3. Consumer Electronics
8.2.4. Others
8.3. Analysis, Insights and Forecast - by Cell Format
8.3.1. Cylindrical
8.3.2. Prismatic
8.3.3. Pouch
8.4. Analysis, Insights and Forecast - by Purity Grade
8.4.1. Battery-grade coated
8.4.2. Uncoated battery-grade
8.4.3. High-purity 99.95%+
9. Graphite Anode for LIB Industry Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Anode Material Type
9.1.1. Synthetic Graphite
9.1.2. Natural Graphite
9.2. Analysis, Insights and Forecast - by End-Use Application
9.2.1. Electric Vehicles
9.2.2. Energy Storage Systems
9.2.3. Consumer Electronics
9.2.4. Others
9.3. Analysis, Insights and Forecast - by Cell Format
9.3.1. Cylindrical
9.3.2. Prismatic
9.3.3. Pouch
9.4. Analysis, Insights and Forecast - by Purity Grade
9.4.1. Battery-grade coated
9.4.2. Uncoated battery-grade
9.4.3. High-purity 99.95%+
10. Graphite Anode for LIB Industry Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Anode Material Type
10.1.1. Synthetic Graphite
10.1.2. Natural Graphite
10.2. Analysis, Insights and Forecast - by End-Use Application
10.2.1. Electric Vehicles
10.2.2. Energy Storage Systems
10.2.3. Consumer Electronics
10.2.4. Others
10.3. Analysis, Insights and Forecast - by Cell Format
10.3.1. Cylindrical
10.3.2. Prismatic
10.3.3. Pouch
10.4. Analysis, Insights and Forecast - by Purity Grade
10.4.1. Battery-grade coated
10.4.2. Uncoated battery-grade
10.4.3. High-purity 99.95%+
11. Graphite Anode for LIB Industry Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Graphite Anode for LIB Industry Research Methodology
List of Figures
Figure 1: Graphite Anode for LIB Industry Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Graphite Anode for LIB Industry Volume Breakdown (tons, %) by Region 2026 & 2034
Figure 3: Asia Pacific Graphite Anode for LIB Industry Revenue (Million), by Anode Material Type 2026 & 2034
Figure 4: Asia Pacific Graphite Anode for LIB Industry Volume (tons), by Anode Material Type 2026 & 2034
Figure 5: Asia Pacific Graphite Anode for LIB Industry Revenue Share (%), by Anode Material Type 2026 & 2034
Figure 6: Asia Pacific Graphite Anode for LIB Industry Volume Share (%), by Anode Material Type 2026 & 2034
Figure 7: Asia Pacific Graphite Anode for LIB Industry Revenue (Million), by End-Use Application 2026 & 2034
Figure 8: Asia Pacific Graphite Anode for LIB Industry Volume (tons), by End-Use Application 2026 & 2034
Figure 9: Asia Pacific Graphite Anode for LIB Industry Revenue Share (%), by End-Use Application 2026 & 2034
Figure 10: Asia Pacific Graphite Anode for LIB Industry Volume Share (%), by End-Use Application 2026 & 2034
Figure 11: Asia Pacific Graphite Anode for LIB Industry Revenue (Million), by Cell Format 2026 & 2034
Figure 12: Asia Pacific Graphite Anode for LIB Industry Volume (tons), by Cell Format 2026 & 2034
Figure 13: Asia Pacific Graphite Anode for LIB Industry Revenue Share (%), by Cell Format 2026 & 2034
Figure 14: Asia Pacific Graphite Anode for LIB Industry Volume Share (%), by Cell Format 2026 & 2034
Figure 15: Asia Pacific Graphite Anode for LIB Industry Revenue (Million), by Purity Grade 2026 & 2034
List of Tables
Table 1: Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 2: Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 3: Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 4: Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 5: Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Table 6: Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Table 7: Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 8: Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 9: Graphite Anode for LIB Industry Revenue Million Forecast, by Region 2020 & 2034
Table 10: Graphite Anode for LIB Industry Volume tons Forecast, by Region 2020 & 2034
Table 11: Asia Pacific Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 12: Asia Pacific Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 13: Asia Pacific Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 14: Asia Pacific Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 15: Asia Pacific Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Asia Pacific Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Frequently Asked Questions
1. How big is the graphite anode for LIB market?
The market is estimated at 3.71 million tons in 2026, growing to 9.45 million tons by 2031 at a 20.54% CAGR. A competing estimate puts 2026 at 4.2 million tons, with the gap reflecting scope rather than demand disagreement.
2. Which anode material type is growing fastest?
Natural graphite is projected to expand at 25.21% CAGR through 2031, faster than synthetic despite synthetic holding 56.89% of 2025 volume. LFP adoption in mid-range EVs and long-duration storage drives the shift toward lower-cost natural material.
3. Which region dominates graphite anode supply?
Asia-Pacific accounted for 74.22% of 2025 shipments, with China hosting most global spheroidisation and graphitisation capacity. Europe is the fastest-growing region at 28.12% CAGR, supported by gigafactory localisation and carbon border adjustment pressure.
4. What are China's export controls on graphite anode material?
China has required export licensing for synthetic spheroidised graphite since 2023, consolidated controls in December 2024, and announced further anode-related measures in October 2025 that were suspended but could still enter force. These controls constrain Western importers directly.
5. Who are the leading graphite anode suppliers?
Leading suppliers include BTR New Materials, Shanshan, POSCO Chemical, Putailai and SGL Carbon. Chinese producers set the reference price curve, while Korean and European vendors compete on supply security and low-carbon attributes rather than unit cost.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study follows a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the anode value chain with natural flake and needle-coke feedstock suppliers, specialised spheroidisation and graphitisation producers, coating and surface-treatment specialists, and global distributors serving cell manufacturers. Interviewees were selected at decision-maker level, principally VP Sourcing, Heads of Battery Materials R&D, Technical Directors for electrode engineering, and Commercial Operations Leads responsible for multi-year offtake negotiation. Interview programmes were weighted toward respondents with direct qualification experience on EV and stationary storage programmes.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
Battery Materials R&D Heads
30%
Technical & Quality Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Natural Graphite & Feedstock Suppliers
40%
Synthetic Anode Producers
35%
Coating & Purification Specialists
15%
Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
Volume and trade-flow benchmarks were validated against official multilateral and national sources, including UN Comtrade, WTO tariff and barrier databases, US ITC trade statistics, Eurostat, and US Geological Survey mineral summaries. Corporate annual filings, SEC submissions and investor presentations were used for capacity mapping and announced expansion timing. Patent filings informed coating and purification capability assessments, supplemented by recognised technical standards and industry association publications on battery-grade graphite specification.
Demand Modeling & Market Sizing Triangulation
Sizing was triangulated simultaneously from the top down, allocating macroeconomic battery demand and cell capacity pipelines across anode intensity per GWh, and from the bottom up, modelling producer capacity, utilisation, realised pricing and end-use consumption by segment. Divergent outputs were reconciled against trade flow data and published capacity announcements, with the residual attributed to definitional scope differences between coated and uncoated material.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Volume in tons for base year
Bottom-up production and capacity triangulation
High
Forecast Horizon
Multi-year compound projection
Historical CAGR, regression analysis and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and commercial filings
High
Sources Referenced
US Geological Survey, Mineral Commodity Summaries (graphite production and reserves)
European Commission Access2Markets trade barrier database (China graphite export restrictions)
International Energy Agency, Global EV Outlook (battery demand benchmarks)
UN Comtrade and Eurostat (graphite and anode material trade flows)
Figure 16: Asia Pacific Graphite Anode for LIB Industry Volume (tons), by Purity Grade 2026 & 2034
Figure 17: Asia Pacific Graphite Anode for LIB Industry Revenue Share (%), by Purity Grade 2026 & 2034
Figure 18: Asia Pacific Graphite Anode for LIB Industry Volume Share (%), by Purity Grade 2026 & 2034
Figure 19: Asia Pacific Graphite Anode for LIB Industry Revenue (Million), by Country 2026 & 2034
Figure 20: Asia Pacific Graphite Anode for LIB Industry Volume (tons), by Country 2026 & 2034
Figure 21: Asia Pacific Graphite Anode for LIB Industry Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Graphite Anode for LIB Industry Volume Share (%), by Country 2026 & 2034
Figure 23: Europe Graphite Anode for LIB Industry Revenue (Million), by Anode Material Type 2026 & 2034
Figure 24: Europe Graphite Anode for LIB Industry Volume (tons), by Anode Material Type 2026 & 2034
Figure 25: Europe Graphite Anode for LIB Industry Revenue Share (%), by Anode Material Type 2026 & 2034
Figure 26: Europe Graphite Anode for LIB Industry Volume Share (%), by Anode Material Type 2026 & 2034
Figure 27: Europe Graphite Anode for LIB Industry Revenue (Million), by End-Use Application 2026 & 2034
Figure 28: Europe Graphite Anode for LIB Industry Volume (tons), by End-Use Application 2026 & 2034
Figure 29: Europe Graphite Anode for LIB Industry Revenue Share (%), by End-Use Application 2026 & 2034
Figure 30: Europe Graphite Anode for LIB Industry Volume Share (%), by End-Use Application 2026 & 2034
Figure 31: Europe Graphite Anode for LIB Industry Revenue (Million), by Cell Format 2026 & 2034
Figure 32: Europe Graphite Anode for LIB Industry Volume (tons), by Cell Format 2026 & 2034
Figure 33: Europe Graphite Anode for LIB Industry Revenue Share (%), by Cell Format 2026 & 2034
Figure 34: Europe Graphite Anode for LIB Industry Volume Share (%), by Cell Format 2026 & 2034
Figure 35: Europe Graphite Anode for LIB Industry Revenue (Million), by Purity Grade 2026 & 2034
Figure 36: Europe Graphite Anode for LIB Industry Volume (tons), by Purity Grade 2026 & 2034
Figure 37: Europe Graphite Anode for LIB Industry Revenue Share (%), by Purity Grade 2026 & 2034
Figure 38: Europe Graphite Anode for LIB Industry Volume Share (%), by Purity Grade 2026 & 2034
Figure 39: Europe Graphite Anode for LIB Industry Revenue (Million), by Country 2026 & 2034
Figure 40: Europe Graphite Anode for LIB Industry Volume (tons), by Country 2026 & 2034
Figure 41: Europe Graphite Anode for LIB Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Europe Graphite Anode for LIB Industry Volume Share (%), by Country 2026 & 2034
Figure 43: North America Graphite Anode for LIB Industry Revenue (Million), by Anode Material Type 2026 & 2034
Figure 44: North America Graphite Anode for LIB Industry Volume (tons), by Anode Material Type 2026 & 2034
Figure 45: North America Graphite Anode for LIB Industry Revenue Share (%), by Anode Material Type 2026 & 2034
Figure 46: North America Graphite Anode for LIB Industry Volume Share (%), by Anode Material Type 2026 & 2034
Figure 47: North America Graphite Anode for LIB Industry Revenue (Million), by End-Use Application 2026 & 2034
Figure 48: North America Graphite Anode for LIB Industry Volume (tons), by End-Use Application 2026 & 2034
Figure 49: North America Graphite Anode for LIB Industry Revenue Share (%), by End-Use Application 2026 & 2034
Figure 50: North America Graphite Anode for LIB Industry Volume Share (%), by End-Use Application 2026 & 2034
Figure 51: North America Graphite Anode for LIB Industry Revenue (Million), by Cell Format 2026 & 2034
Figure 52: North America Graphite Anode for LIB Industry Volume (tons), by Cell Format 2026 & 2034
Figure 53: North America Graphite Anode for LIB Industry Revenue Share (%), by Cell Format 2026 & 2034
Figure 54: North America Graphite Anode for LIB Industry Volume Share (%), by Cell Format 2026 & 2034
Figure 55: North America Graphite Anode for LIB Industry Revenue (Million), by Purity Grade 2026 & 2034
Figure 56: North America Graphite Anode for LIB Industry Volume (tons), by Purity Grade 2026 & 2034
Figure 57: North America Graphite Anode for LIB Industry Revenue Share (%), by Purity Grade 2026 & 2034
Figure 58: North America Graphite Anode for LIB Industry Volume Share (%), by Purity Grade 2026 & 2034
Figure 59: North America Graphite Anode for LIB Industry Revenue (Million), by Country 2026 & 2034
Figure 60: North America Graphite Anode for LIB Industry Volume (tons), by Country 2026 & 2034
Figure 61: North America Graphite Anode for LIB Industry Revenue Share (%), by Country 2026 & 2034
Figure 62: North America Graphite Anode for LIB Industry Volume Share (%), by Country 2026 & 2034
Figure 63: Latin America Graphite Anode for LIB Industry Revenue (Million), by Anode Material Type 2026 & 2034
Figure 64: Latin America Graphite Anode for LIB Industry Volume (tons), by Anode Material Type 2026 & 2034
Figure 65: Latin America Graphite Anode for LIB Industry Revenue Share (%), by Anode Material Type 2026 & 2034
Figure 66: Latin America Graphite Anode for LIB Industry Volume Share (%), by Anode Material Type 2026 & 2034
Figure 67: Latin America Graphite Anode for LIB Industry Revenue (Million), by End-Use Application 2026 & 2034
Figure 68: Latin America Graphite Anode for LIB Industry Volume (tons), by End-Use Application 2026 & 2034
Figure 69: Latin America Graphite Anode for LIB Industry Revenue Share (%), by End-Use Application 2026 & 2034
Figure 70: Latin America Graphite Anode for LIB Industry Volume Share (%), by End-Use Application 2026 & 2034
Figure 71: Latin America Graphite Anode for LIB Industry Revenue (Million), by Cell Format 2026 & 2034
Figure 72: Latin America Graphite Anode for LIB Industry Volume (tons), by Cell Format 2026 & 2034
Figure 73: Latin America Graphite Anode for LIB Industry Revenue Share (%), by Cell Format 2026 & 2034
Figure 74: Latin America Graphite Anode for LIB Industry Volume Share (%), by Cell Format 2026 & 2034
Figure 75: Latin America Graphite Anode for LIB Industry Revenue (Million), by Purity Grade 2026 & 2034
Figure 76: Latin America Graphite Anode for LIB Industry Volume (tons), by Purity Grade 2026 & 2034
Figure 77: Latin America Graphite Anode for LIB Industry Revenue Share (%), by Purity Grade 2026 & 2034
Figure 78: Latin America Graphite Anode for LIB Industry Volume Share (%), by Purity Grade 2026 & 2034
Figure 79: Latin America Graphite Anode for LIB Industry Revenue (Million), by Country 2026 & 2034
Figure 80: Latin America Graphite Anode for LIB Industry Volume (tons), by Country 2026 & 2034
Figure 81: Latin America Graphite Anode for LIB Industry Revenue Share (%), by Country 2026 & 2034
Figure 82: Latin America Graphite Anode for LIB Industry Volume Share (%), by Country 2026 & 2034
Figure 83: Middle East & Africa Graphite Anode for LIB Industry Revenue (Million), by Anode Material Type 2026 & 2034
Figure 84: Middle East & Africa Graphite Anode for LIB Industry Volume (tons), by Anode Material Type 2026 & 2034
Figure 85: Middle East & Africa Graphite Anode for LIB Industry Revenue Share (%), by Anode Material Type 2026 & 2034
Figure 86: Middle East & Africa Graphite Anode for LIB Industry Volume Share (%), by Anode Material Type 2026 & 2034
Figure 87: Middle East & Africa Graphite Anode for LIB Industry Revenue (Million), by End-Use Application 2026 & 2034
Figure 88: Middle East & Africa Graphite Anode for LIB Industry Volume (tons), by End-Use Application 2026 & 2034
Figure 89: Middle East & Africa Graphite Anode for LIB Industry Revenue Share (%), by End-Use Application 2026 & 2034
Figure 90: Middle East & Africa Graphite Anode for LIB Industry Volume Share (%), by End-Use Application 2026 & 2034
Figure 91: Middle East & Africa Graphite Anode for LIB Industry Revenue (Million), by Cell Format 2026 & 2034
Figure 92: Middle East & Africa Graphite Anode for LIB Industry Volume (tons), by Cell Format 2026 & 2034
Figure 93: Middle East & Africa Graphite Anode for LIB Industry Revenue Share (%), by Cell Format 2026 & 2034
Figure 94: Middle East & Africa Graphite Anode for LIB Industry Volume Share (%), by Cell Format 2026 & 2034
Figure 95: Middle East & Africa Graphite Anode for LIB Industry Revenue (Million), by Purity Grade 2026 & 2034
Figure 96: Middle East & Africa Graphite Anode for LIB Industry Volume (tons), by Purity Grade 2026 & 2034
Figure 97: Middle East & Africa Graphite Anode for LIB Industry Revenue Share (%), by Purity Grade 2026 & 2034
Figure 98: Middle East & Africa Graphite Anode for LIB Industry Volume Share (%), by Purity Grade 2026 & 2034
Figure 99: Middle East & Africa Graphite Anode for LIB Industry Revenue (Million), by Country 2026 & 2034
Figure 100: Middle East & Africa Graphite Anode for LIB Industry Volume (tons), by Country 2026 & 2034
Figure 101: Middle East & Africa Graphite Anode for LIB Industry Revenue Share (%), by Country 2026 & 2034
Figure 102: Middle East & Africa Graphite Anode for LIB Industry Volume Share (%), by Country 2026 & 2034
Table 16:
Table 17: Asia Pacific Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 18: Asia Pacific Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 19: Asia Pacific Graphite Anode for LIB Industry Revenue Million Forecast, by Country 2020 & 2034
Table 20: Asia Pacific Graphite Anode for LIB Industry Volume tons Forecast, by Country 2020 & 2034
Table 21: China Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 22: China Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 23: Japan Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 24: Japan Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 25: South Korea Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 26: South Korea Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 27: India Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 28: India Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 29: Europe Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 30: Europe Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 31: Europe Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 32: Europe Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 33: Europe Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Table 34: Europe Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Table 35: Europe Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 36: Europe Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 37: Europe Graphite Anode for LIB Industry Revenue Million Forecast, by Country 2020 & 2034
Table 38: Europe Graphite Anode for LIB Industry Volume tons Forecast, by Country 2020 & 2034
Table 39: Germany Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 40: Germany Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 41: Sweden Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 42: Sweden Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 43: Poland Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 44: Poland Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 45: France Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 46: France Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 47: North America Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 48: North America Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 49: North America Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 50: North America Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 51: North America Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Table 52: North America Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Table 53: North America Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 54: North America Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 55: North America Graphite Anode for LIB Industry Revenue Million Forecast, by Country 2020 & 2034
Table 56: North America Graphite Anode for LIB Industry Volume tons Forecast, by Country 2020 & 2034
Table 57: USA Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 58: USA Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 59: Canada Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 60: Canada Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 61: Mexico Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 62: Mexico Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 63: Latin America Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 64: Latin America Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 65: Latin America Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 66: Latin America Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 67: Latin America Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Table 68: Latin America Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Table 69: Latin America Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 70: Latin America Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 71: Latin America Graphite Anode for LIB Industry Revenue Million Forecast, by Country 2020 & 2034
Table 72: Latin America Graphite Anode for LIB Industry Volume tons Forecast, by Country 2020 & 2034
Table 73: Brazil Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 74: Brazil Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 75: Argentina Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 76: Argentina Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 77: Middle East & Africa Graphite Anode for LIB Industry Revenue Million Forecast, by Anode Material Type 2020 & 2034
Table 78: Middle East & Africa Graphite Anode for LIB Industry Volume tons Forecast, by Anode Material Type 2020 & 2034
Table 79: Middle East & Africa Graphite Anode for LIB Industry Revenue Million Forecast, by End-Use Application 2020 & 2034
Table 80: Middle East & Africa Graphite Anode for LIB Industry Volume tons Forecast, by End-Use Application 2020 & 2034
Table 81: Middle East & Africa Graphite Anode for LIB Industry Revenue Million Forecast, by Cell Format 2020 & 2034
Table 82: Middle East & Africa Graphite Anode for LIB Industry Volume tons Forecast, by Cell Format 2020 & 2034
Table 83: Middle East & Africa Graphite Anode for LIB Industry Revenue Million Forecast, by Purity Grade 2020 & 2034
Table 84: Middle East & Africa Graphite Anode for LIB Industry Volume tons Forecast, by Purity Grade 2020 & 2034
Table 85: Middle East & Africa Graphite Anode for LIB Industry Revenue Million Forecast, by Country 2020 & 2034
Table 86: Middle East & Africa Graphite Anode for LIB Industry Volume tons Forecast, by Country 2020 & 2034
Table 87: South Africa Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 88: South Africa Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
Table 89: Mozambique Graphite Anode for LIB Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 90: Mozambique Graphite Anode for LIB Industry Volume (tons) Forecast, by Application 2020 & 2034
 Graphite Anode for LIB Industry