 Self Leveling Concrete Market
 Size, Share & Forecast 2026
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Self Leveling Concrete Market

Khageshwar Rongkali
Senior Analyst

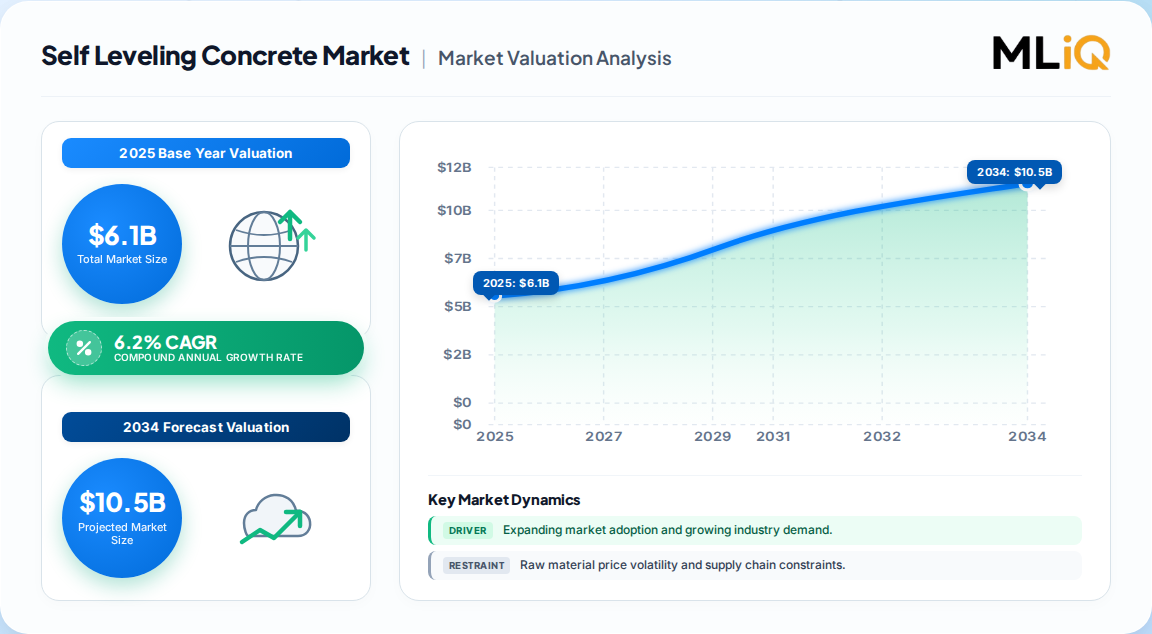
| Year | Market Size |
|---|---|
| 2025 | 6.100 B |
| 2026 | 6.500 B |
| 2027 | 6.900 B |
| 2028 | 7.300 B |
| 2029 | 7.800 B |
| 2030 | 8.300 B |
| 2031 | 8.800 B |

The self leveling concrete market encompasses the production and supply of highly flowable cementitious or polymer-modified compounds that self-level upon pouring to create smooth, flat substrates. These materials are used in floor leveling, resurfacing, and underlayment applications across residential, commercial, industrial, and infrastructure construction. The market is driven by labor savings, time efficiency, and superior surface finish quality compared to traditional screeds.
This report analyzes the global self leveling concrete market by system type (underlayment and overlay), end-use sector (residential, commercial, industrial, infrastructure), and region. It covers market sizing, segmentation, competitive landscape, and strategic outlook for 2026-2033. This analysis does not cover traditional sand-cement screeds, epoxy floor coatings, or adhesives and sealants used in conjunction with self leveling compounds.
The global self leveling concrete market was estimated at 6.1 Billion in 2025, with forecasts varying by source methodology and scope. The table below compares published estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 6.1 Billion | 2025 | 2033 | 6.2% | Global, all end uses | One published analysis |
| 5.4 Billion | 2023 | 2033 | 4.67% | Global, product type segmentation | A competing analysis |
| 4.8 Billion | 2022 | 2028 | 4.0% | Global, type/end-use | Another published estimate |
| 25.63 Million m³ | 2026 | 2031 | 4.12% | Volume, product/end-use sector | One volume-based analysis |
Our analysis suggests the 6.1 Billion (2025) figure is the most defensible for value-based decision-making, as it aligns with current construction spending trends and reflects the post-pandemic recovery in renovation activity. Volume-based estimates (25.63 million cubic meters in 2026) corroborate steady growth but understate value due to price inflation in polymer-modified formulations. The divergence in CAGR (4.0% to 6.2%) reflects differing assumptions on Asia-Pacific urbanization rates and infrastructure spending.
The market is segmented by system type, end-use sector, and product formulation. Underlayment systems account for roughly 70% of revenue, while commercial end-use leads, followed by residential.
| Parent Segment | Children |
|---|---|
| By System Type | Underlayment, Overlay (Topping) |
| By End-Use Sector | Residential, Commercial, Industrial, Infrastructure |
| By Product Type | Polymer-Based, Cement-Based, Others |
| By Application | Flooring, Repair & Renovation, Construction |
Analyst note: The underlayment segment's dominance is tied to the luxury vinyl tile (LVT) boom, which demands ultra-smooth substrates (FF 50+). As click-lock LVT slims to 3.5 mm, the tolerance for substrate irregularities shrinks, driving underlayment demand.
Asia-Pacific leads the global self leveling concrete market with approximately 42% revenue share in 2025, driven by construction booms in China, India, and Southeast Asia. North America and Europe follow with roughly 24% and 21% respectively, where renovation cycles and VOC regulations shape demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.42% |
| North America | 0.24% |
| Europe | 0.21% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
Asia-Pacific's dominance is underpinned by government infrastructure initiatives and a growing middle class. Our analysis indicates the region will remain the fastest-growing, adding 2.1 Billion in absolute value by 2033, though skilled labor shortages pose a downside risk.
Growth is driven by fast-track construction schedules, VOC-free regulatory incentives, and the LVT flooring boom, while restraints include skilled labor gaps, raw material price volatility, and insurance exclusions for moisture-related failures.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| E-commerce fulfillment center construction | Driver | High | 3,000 psi in 72 hours enables rapid racking |
| VOC-free government incentives | Driver | High | LEED/BREEAM and CBAM compliance |
| LVT boom demanding ultra-smooth subfloors | Driver | High | FF 50+ flatness reduces callback risk |
| Carbon-credit monetization via CSA blends | Driver | Medium | 30-40% lower CO2, offsets price premium |
| Installation skill gap | Restraint | High | 28% of pours fail flatness/moisture thresholds |
| Silica-fume supply squeeze | Restraint | Medium | Steel EAF transition tightens supply |
| Insurance exclusions on slab-moisture failures | Restraint | Medium | Elevates premiums for contractors |
Balance: Drivers outweigh restraints, but the skill gap is a critical bottleneck. This implies that vendors investing in certified applicator training will capture share as failure-related costs rise.
Key players include Holcim, MAPEI, Saint-Gobain, Sika, Ardex, LATICRETE, BASF, and CEMEX, competing on formulation innovation, regional manufacturing, and contractor training.
| Company | Key Differentiator | Strategic Focus |
|---|---|---|
| Holcim | CSA-based low-carbon underlayments | Net-zero projects, carbon credits |
| MAPEI | Broad product portfolio & global distribution | Residential renovation, commercial |
| Saint-Gobain | Integrated flooring solutions | LVT compatibility, VOC compliance |
| Sika | Polymer-modified systems | Infrastructure repair, rapid-setting |
| Ardex | Premium underlayment technology | High-performance, training programs |
| LATICRETE | Contractor-focused solutions | Commercial, industrial flooring |
| BASF | MasterEmaco line, Safer Choice certified | Eco-friendly formulations |
Competitive moats are built on formulation patents (CSA blends, bio-based modifiers), distribution networks, and contractor loyalty programs. Smaller players compete on price but face margin pressure from raw material volatility.
Buyers and operators must prioritize formulation compatibility with substrate moisture and flooring type, certified applicator availability, and regulatory compliance (VOC limits, CBAM reporting for imports). Procurement risks include price volatility in cement and silica fume, and switching costs are moderate due to contractor training requirements. In Europe, CBAM's definitive regime (from 2026) adds carbon reporting obligations for imported cement-based products, influencing supplier selection. Our analysis suggests buyers should favor vendors offering turnkey training and rapid-setting CSA blends to minimize project delays and callback costs.
The balance of evidence favors steady, above-GDP growth for the self leveling concrete market, with Asia-Pacific as the primary engine and renovation activity in developed markets providing a stable secondary base. The strongest counter-argument is that rising raw material costs and labor shortages could compress margins and slow adoption, particularly in price-sensitive emerging markets. However, rapid-setting and low-carbon formulations are emerging as premium-priced solutions that offset commodity pressure.
Actionable Strategy:
What evidence would change our conclusion: A sustained drop in Asia-Pacific construction starts below 3% annual growth, or a breakthrough in alternative floor-levelling technologies (e.g., robotic screeding) that reduces material demand, would warrant a downward revision. Conversely, accelerated CBAM enforcement and carbon pricing could boost CSA adoption faster than projected.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.2% from 2020-2034 |
| Segmentation |
|
Fast-track construction in e-commerce fulfillment centers, VOC-free regulatory incentives, and the LVT flooring boom demanding ultra-smooth subfloors are the primary drivers.
Asia-Pacific offers the highest growth potential, driven by urbanization and industrialization in China and India, followed by North America's renovation cycle.
Underlayment systems hold approximately 70% of revenue, driven by subfloor preparation for LVT and other thin flooring materials.
Holcim, MAPEI, Saint-Gobain, Sika, Ardex, LATICRETE, and BASF are among the key players, competing on formulation innovation and contractor training.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain: raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captures ground-level pricing dynamics, formulation trends, and adoption barriers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 40% |
| Specialized Formulators & Blenders | 35% |
| Industrial Distributors | 25% |
We validate findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC), patent databases, and recognized technical standards from ASTM International and ACI. This triangulation ensures that market sizing reflects actual trade flows and regulatory compliance requirements, such as EU CBAM and VOC emission limits.
We simultaneously apply Top-Down (macroeconomic & industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) modeling. This dual approach reconciles volume-based estimates (cubic meters) with value-based figures (USD), using price indices for polymer-modified and cement-based formulations.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |