Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Kosher Salt Market: Size, Share & Growth Outlook 2026
Kosher Salt Market: Size, Share & Growth Outlook 2026
Kosher Salt Market
Kosher Salt Market: Size, Share & Growth Outlook 2026
Kosher Salt Market by Product Type (Flake Kosher Salt, Coarse Grain Kosher Salt, Fine Grain Kosher Salt), by Source (Rock Salt, Sea Salt, Brine-Derived Salt), by Application (Food Processing & Manufacturing, Meat Processing & Curing, Bakery & Confectionery, Seasonings & Spice Blends, Other Culinary Applications), by End User (Food Manufacturers, Foodservice & Restaurants, Household Consumers, Catering Services, Institutional Kitchens), by Distribution Channel (Supermarkets & Hypermarkets, Specialty Food Stores, Online Retail, Foodservice Distributors, Direct B2B Sales), by Packaging Type (Retail Packs, Foodservice Packs, Industrial Bulk Packs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Israel, Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
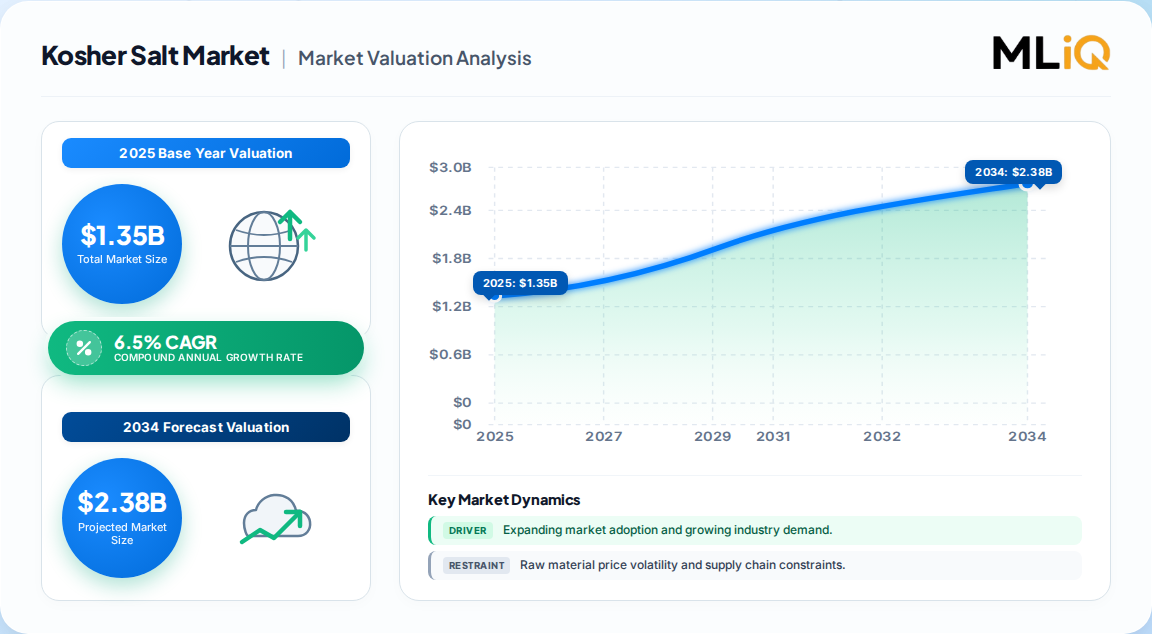
USD 1.35 Billion in 2025 marks the global Kosher Salt Market base, scaling to USD 2.10 Billion by 2032.
The market compounds at 6.5% CAGR (2026–2032) — a USD 750 million absolute revenue expansion over seven years.
Flake kosher salt leads product formats at roughly 48% of revenue, with food processing and manufacturing the largest application at 34%.
North America holds approximately 41% of global value; Asia-Pacific is the fastest-growing consumption frontier.
Leading suppliers include Cargill (Diamond Crystal), Morton Salt, SaltWorks, True Salt, K+S Windsor, Jacobsen Salt Co.
Retail packs dominate packaging at ~56% of revenue, but foodservice distributor channels carry the stickiest recurring volume.
Why this matters for decision-makers: Margin is migrating from commodity crystal volume toward application-specific grain sizes, private-label supply and flavored line extensions — suppliers who stay in bulk coarse salt alone will face structural price compression.
Kosher Salt Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.350 B
2025
1.440 B
2026
1.530 B
2027
1.630 B
2028
1.740 B
2029
1.850 B
2030
1.970 B
2031
Kosher Salt Market Size (In Billion)
Year
Market Size
2025
1.350 B
2026
1.440 B
2027
1.530 B
2028
1.630 B
2029
1.740 B
2030
1.850 B
2031
1.970 B
What is the Kosher Salt Market?
The Kosher Salt Market covers coarse, additive-free culinary salt — typically certified kosher — sold for brining, curing, seasoning and finishing across household, foodservice and industrial food processing. Its large, slow-dissolving crystals and purity distinguish it functionally from table salt, positioning it as both a religious-compliance ingredient and a premium culinary input.
Scope: what this report covers and excludes
This analysis sizes global revenue for kosher-certified and kosher-style culinary salt across retail, foodservice and food-manufacturing channels, segmented by product type, source, application, end user, distribution, packaging and geography. This analysis does not cover industrial non-food salt, water-softening salt, chemical-grade sodium chloride, or broader gourmet sea-salt categories outside kosher positioning.
How big is the Kosher Salt Market?
Estimates diverge sharply — from roughly USD 0.48 billion to USD 1.39 billion for the 2025 base year — largely because publishers define the category boundary differently. The table below isolates where and why.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 1.35 Bn → 2.10 Bn
2025
2032
6.5%
Broad: retail + foodservice + food manufacturing, all crystal types
One published estimate (SMR)
USD 1.39 Bn → 2.74 Bn
2025
2034
7.8%
Broad culinary salt incl. kosher-style, global
A competing analysis
USD 1.31 Bn → 2.23 Bn
2025
2034
6.03%
Retail + foodservice + F&B manufacturers
A competing analysis
USD 1.1 Bn → 1.7 Bn
2026
2033
6.6%
Broad culinary application set
A competing analysis
USD 0.48 Bn → 0.99 Bn
2025
2033
9.40%
Narrow: branded specialty kosher salt
A competing analysis
The USD 1.31–1.39 billion cluster is the most defensible base, corroborated by multiple independent sizing exercises and consistent with cross-checked country-level revenue such as USD 457 million in the United States alone. Our analysis suggests the sub-USD 500 million figure reflects branded specialty product only and understates the true commercial category by roughly two-thirds.
How is the market segmented?
Segmentation hinges on crystal engineering and buyer type: crystal format determines culinary function, while end user determines procurement volume and supply relationship.
Rock salt supplies roughly 55% of revenue on established processing infrastructure; flake formats command premium pricing through differentiated crystal structure. Retail packs hold ~56% of value, but industrial bulk packs carry the largest per-order value.
Which region leads the Kosher Salt Market?
North America leads with roughly 41% of global revenue in 2025 (about USD 553.5 million), anchored by over one million U.S. foodservice locations and entrenched professional-kitchen usage. Europe follows at ~25%, Asia-Pacific at ~22%, Latin America ~7% and Middle East & Africa ~5%.
Kosher Salt Market Regional Market Share
Loading chart...
Kosher Salt Market Regional Market Share
Region
Market Share (%)
North America
0.41%
Europe
0.25%
Asia-Pacific
0.22%
South America
0.07%
Middle East & Africa
0.05%
North America (USA, Canada, Mexico)
USA — ≈USD 457 Mn, ~34% of global demand
Canada — ≈USD 66 Mn; kosher salt ≈8.3% of culinary salt retail value
Europe (Germany, UK, France, Italy)
UK ≈USD 80 Mn; Germany ≈USD 78 Mn; France ≈USD 55 Mn
Asia-Pacific (China, Japan, India, South Korea)
Japan ≈USD 72 Mn; South Korea ≈USD 39 Mn; Australia ≈USD 30 Mn
Latin America (Brazil, Argentina)
Brazil ≈USD 45 Mn, tied to meat-processing demand
Middle East & Africa (Israel, Saudi Arabia, UAE, South Africa)
Israel ≈USD 25 Mn, driven by kosher food preparation
The divergence between North America's 41% share and Asia-Pacific's 22% is instructive. Asia-Pacific already leads raw consumption and large-scale production per one source, yet captures a smaller share of kosher-salt revenue — our analysis reads this as a premium-positioning gap rather than a demand gap. Western markets monetize certification and crystal differentiation; Asian volume is largely absorbed as generic coarse salt.
What is driving growth — and what is holding it back?
Functional salt use in meat and poultry processing is the single most durable demand driver: USDA-linked analyses indicate salt-containing enhancement is applied to roughly 30% of retail chicken and 40% of fresh pork. Cost premium and sodium-reduction policy are the principal brakes.
Factor
Direction
Evidence strength
Mechanism
Meat & poultry processing adoption
Growth
High
Protein extraction, water binding, dry-brining yield gains
Foodservice and home-cooking expansion
Growth
High
Recurring ingredient procurement; culinary media influence
Flavored, smoked, specialty variants
Growth
Medium‑High
Retail listings near USD 58/kg vs ~USD 2.60/kg mainstream
Private-label foodservice supply
Growth
Medium
Access to distributor networks, recurring bulk orders
Price premium vs table salt
Restraint
High
3–10× unit cost deters cost-sensitive and emerging-market buyers
Sodium-reduction regulation
Restraint
Medium
FDA guidance under 2,300 mg/day prompts reformulation
Kosher certification complexity
Restraint
Medium
Compliance burden across sourcing and facility audits
The balance favors growth. Meat processing demand is functional, not discretionary — it survives sodium scrutiny because salt delivers yield and texture, not just taste. But the restraint is real: in price-driven emerging markets, kosher salt must justify a 3–10× premium over table salt on culinary grounds alone. Our analysis suggests the winning play is not defending the premium broadly but narrowing it to applications where crystal structure measurably changes output.
Who are the leading vendors?
Competition splits into three tiers: technology-led flake producers, scaled mainstream salt houses, and premium origin-driven specialists.
Six industrial grain sizes; distributor partnerships
Supplies 5 of top 10 U.S. foodservice distributors
K+S Windsor Salt
Regional mainstream (Canada)
Domestic brand recognition, accessible pricing
~CAD 3.67/kg retail positioning
Jacobsen Salt Co.
Premium origin
Netarts Bay sea salt, culinary branding
~USD 28.66/kg retail
Moats are manufacturing-based, not brand-based. Alberger crystallization cannot be quickly replicated, and the capital intensity of dedicated flake capacity deters new entrants. Our analysis suggests True Salt's private-label model is the more replicable threat — it competes on flexibility and distributor access rather than process IP, and it can scale without a consumer brand.
What do buyers and operators need to know?
Crystal specification is the primary selection criterion, not price per kilogram. Flake dissolves rapidly and gives controlled seasoning; coarse grain suits dry brining and curing where slow, even moisture draw matters; fine grain supports uniform distribution in baking and blends. Buyers specifying the wrong format incur yield losses that dwarf the unit-price differential.
Procurement risk concentrates in supply concentration. Dedicated flake capacity is limited to a small number of facilities, so a single plant disruption can tighten availability materially — the USD 100 million Michigan expansion is partly a resilience investment. Buyers should qualify at least one alternate source with matched crystal characteristics, since switching costs are high: reformulating a seasoning blend or cured-meat process around a different grain size requires re-validation.
Regulatory compliance cuts two ways. Kosher certification must be documented across the supply chain, and sodium-reduction guidance pressures food manufacturers to reformulate. Operators in meat processing should confirm that suppliers can provide certified, additive-free coarse product at consistent particle size, with documentation aligned to labeling requirements.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-migration thesis over a volume thesis. Headline growth of 6.5% is modest, but it masks a sharper split: commodity coarse salt grows near GDP rates while application-specific and flavored formats expand at multiples of that. Suppliers who read the 6.5% average as licence to hold a bulk strategy will cede the margin to competitors building specification-led portfolios.
The strongest counter-argument is that premiumization is fragile. Flavored kosher salt at roughly USD 58/kg sits in a discretionary category exposed to any consumer spending contraction, and the retail listings cited are single-SKU observations rather than sustained volume. If specialty demand stalls, the market reverts to a scale game where Cargill and Morton's capacity advantages dominate. This is a genuine risk, and it is why we weight foodservice and processing contracts above retail specialty.
Actionable strategy:
Investors should underwrite suppliers with dedicated crystal capacity or private-label distributor contracts, not branded retail exposure alone.
Operators should lock multi-year bulk supply with matched-crystal alternates qualified, prioritizing particle-size consistency over headline price.
Producers should extend into application-specific grain sizes and private-label supply to convert commodity revenue into specification-locked recurring volume.
What would change our conclusion: sustained multi-year volume data showing specialty kosher salt plateauing below 15% of category revenue, or a major sodium-reduction mandate forcing functional salt substitution in processed meat. While this overview establishes the strategic frame, precise sub-segment forecasting by grain size and channel requires the full segmentation model.
Kosher Salt Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Kosher Salt Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.5% from 2020-2034
Segmentation
By Product Type
Flake Kosher Salt
Coarse Grain Kosher Salt
Fine Grain Kosher Salt
By Source
Rock Salt
Sea Salt
Brine-Derived Salt
By Application
Food Processing & Manufacturing
Meat Processing & Curing
Bakery & Confectionery
Seasonings & Spice Blends
Other Culinary Applications
By End User
Food Manufacturers
Foodservice & Restaurants
Household Consumers
Catering Services
Institutional Kitchens
By Distribution Channel
Supermarkets & Hypermarkets
Specialty Food Stores
Online Retail
Foodservice Distributors
Direct B2B Sales
By Packaging Type
Retail Packs
Foodservice Packs
Industrial Bulk Packs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Israel
Saudi Arabia
UAE
South Africa
Table of Contents
1. Kosher Salt Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Kosher Salt Market Executive Summary
2.1. Market Snapshot
3. Kosher Salt Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Kosher Salt Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Kosher Salt Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Flake Kosher Salt
5.1.2. Coarse Grain Kosher Salt
5.1.3. Fine Grain Kosher Salt
5.2. Analysis, Insights and Forecast - by Source
5.2.1. Rock Salt
5.2.2. Sea Salt
5.2.3. Brine-Derived Salt
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Food Processing & Manufacturing
5.3.2. Meat Processing & Curing
5.3.3. Bakery & Confectionery
5.3.4. Seasonings & Spice Blends
5.3.5. Other Culinary Applications
5.4. Analysis, Insights and Forecast - by End User
5.4.1. Food Manufacturers
5.4.2. Foodservice & Restaurants
5.4.3. Household Consumers
5.4.4. Catering Services
5.4.5. Institutional Kitchens
5.5. Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Supermarkets & Hypermarkets
5.5.2. Specialty Food Stores
5.5.3. Online Retail
5.5.4. Foodservice Distributors
5.5.5. Direct B2B Sales
5.6. Analysis, Insights and Forecast - by Packaging Type
5.6.1. Retail Packs
5.6.2. Foodservice Packs
5.6.3. Industrial Bulk Packs
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Kosher Salt Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Flake Kosher Salt
6.1.2. Coarse Grain Kosher Salt
6.1.3. Fine Grain Kosher Salt
6.2. Analysis, Insights and Forecast - by Source
6.2.1. Rock Salt
6.2.2. Sea Salt
6.2.3. Brine-Derived Salt
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Food Processing & Manufacturing
6.3.2. Meat Processing & Curing
6.3.3. Bakery & Confectionery
6.3.4. Seasonings & Spice Blends
6.3.5. Other Culinary Applications
6.4. Analysis, Insights and Forecast - by End User
6.4.1. Food Manufacturers
6.4.2. Foodservice & Restaurants
6.4.3. Household Consumers
6.4.4. Catering Services
6.4.5. Institutional Kitchens
6.5. Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Supermarkets & Hypermarkets
6.5.2. Specialty Food Stores
6.5.3. Online Retail
6.5.4. Foodservice Distributors
6.5.5. Direct B2B Sales
6.6. Analysis, Insights and Forecast - by Packaging Type
6.6.1. Retail Packs
6.6.2. Foodservice Packs
6.6.3. Industrial Bulk Packs
7. Kosher Salt Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Flake Kosher Salt
7.1.2. Coarse Grain Kosher Salt
7.1.3. Fine Grain Kosher Salt
7.2. Analysis, Insights and Forecast - by Source
7.2.1. Rock Salt
7.2.2. Sea Salt
7.2.3. Brine-Derived Salt
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Food Processing & Manufacturing
7.3.2. Meat Processing & Curing
7.3.3. Bakery & Confectionery
7.3.4. Seasonings & Spice Blends
7.3.5. Other Culinary Applications
7.4. Analysis, Insights and Forecast - by End User
7.4.1. Food Manufacturers
7.4.2. Foodservice & Restaurants
7.4.3. Household Consumers
7.4.4. Catering Services
7.4.5. Institutional Kitchens
7.5. Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Supermarkets & Hypermarkets
7.5.2. Specialty Food Stores
7.5.3. Online Retail
7.5.4. Foodservice Distributors
7.5.5. Direct B2B Sales
7.6. Analysis, Insights and Forecast - by Packaging Type
7.6.1. Retail Packs
7.6.2. Foodservice Packs
7.6.3. Industrial Bulk Packs
8. Kosher Salt Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Flake Kosher Salt
8.1.2. Coarse Grain Kosher Salt
8.1.3. Fine Grain Kosher Salt
8.2. Analysis, Insights and Forecast - by Source
8.2.1. Rock Salt
8.2.2. Sea Salt
8.2.3. Brine-Derived Salt
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Food Processing & Manufacturing
8.3.2. Meat Processing & Curing
8.3.3. Bakery & Confectionery
8.3.4. Seasonings & Spice Blends
8.3.5. Other Culinary Applications
8.4. Analysis, Insights and Forecast - by End User
8.4.1. Food Manufacturers
8.4.2. Foodservice & Restaurants
8.4.3. Household Consumers
8.4.4. Catering Services
8.4.5. Institutional Kitchens
8.5. Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Supermarkets & Hypermarkets
8.5.2. Specialty Food Stores
8.5.3. Online Retail
8.5.4. Foodservice Distributors
8.5.5. Direct B2B Sales
8.6. Analysis, Insights and Forecast - by Packaging Type
8.6.1. Retail Packs
8.6.2. Foodservice Packs
8.6.3. Industrial Bulk Packs
9. Kosher Salt Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Flake Kosher Salt
9.1.2. Coarse Grain Kosher Salt
9.1.3. Fine Grain Kosher Salt
9.2. Analysis, Insights and Forecast - by Source
9.2.1. Rock Salt
9.2.2. Sea Salt
9.2.3. Brine-Derived Salt
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Food Processing & Manufacturing
9.3.2. Meat Processing & Curing
9.3.3. Bakery & Confectionery
9.3.4. Seasonings & Spice Blends
9.3.5. Other Culinary Applications
9.4. Analysis, Insights and Forecast - by End User
9.4.1. Food Manufacturers
9.4.2. Foodservice & Restaurants
9.4.3. Household Consumers
9.4.4. Catering Services
9.4.5. Institutional Kitchens
9.5. Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Supermarkets & Hypermarkets
9.5.2. Specialty Food Stores
9.5.3. Online Retail
9.5.4. Foodservice Distributors
9.5.5. Direct B2B Sales
9.6. Analysis, Insights and Forecast - by Packaging Type
9.6.1. Retail Packs
9.6.2. Foodservice Packs
9.6.3. Industrial Bulk Packs
10. Kosher Salt Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Flake Kosher Salt
10.1.2. Coarse Grain Kosher Salt
10.1.3. Fine Grain Kosher Salt
10.2. Analysis, Insights and Forecast - by Source
10.2.1. Rock Salt
10.2.2. Sea Salt
10.2.3. Brine-Derived Salt
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Food Processing & Manufacturing
10.3.2. Meat Processing & Curing
10.3.3. Bakery & Confectionery
10.3.4. Seasonings & Spice Blends
10.3.5. Other Culinary Applications
10.4. Analysis, Insights and Forecast - by End User
10.4.1. Food Manufacturers
10.4.2. Foodservice & Restaurants
10.4.3. Household Consumers
10.4.4. Catering Services
10.4.5. Institutional Kitchens
10.5. Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Supermarkets & Hypermarkets
10.5.2. Specialty Food Stores
10.5.3. Online Retail
10.5.4. Foodservice Distributors
10.5.5. Direct B2B Sales
10.6. Analysis, Insights and Forecast - by Packaging Type
10.6.1. Retail Packs
10.6.2. Foodservice Packs
10.6.3. Industrial Bulk Packs
11. Kosher Salt Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Kosher Salt Market Research Methodology
List of Figures
Figure 1: Kosher Salt Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Kosher Salt Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Kosher Salt Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Kosher Salt Market Revenue (Billion), by Source 2026 & 2034
Figure 5: North America Kosher Salt Market Revenue Share (%), by Source 2026 & 2034
Figure 6: North America Kosher Salt Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Kosher Salt Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Kosher Salt Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America Kosher Salt Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Kosher Salt Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Kosher Salt Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Kosher Salt Market Revenue (Billion), by Packaging Type 2026 & 2034
Figure 13: North America Kosher Salt Market Revenue Share (%), by Packaging Type 2026 & 2034
Figure 14: North America Kosher Salt Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Kosher Salt Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Kosher Salt Market Revenue (Billion), by Product Type 2026 & 2034
Europe Kosher Salt Market Revenue Share (%), by Product Type 2026 & 2034
List of Tables
Table 1: Kosher Salt Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Kosher Salt Market Revenue Billion Forecast, by Source 2020 & 2034
Table 3: Kosher Salt Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Kosher Salt Market Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Kosher Salt Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Kosher Salt Market Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 7: Kosher Salt Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Kosher Salt Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Kosher Salt Market Revenue Billion Forecast, by Source 2020 & 2034
Table 10: North America Kosher Salt Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Kosher Salt Market Revenue Billion Forecast, by End User 2020 & 2034
Table 12: North America Kosher Salt Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 13: North America Kosher Salt Market Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 14: North America Kosher Salt Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Kosher Salt Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Kosher Salt Market Revenue (Billion) Forecast, by Application 2020 & 2034
Mexico Kosher Salt Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Kosher Salt Market in 2025?
The global Kosher Salt Market was valued at approximately USD 1.35 Billion in 2025. Independent estimates cluster between USD 1.31 and 1.39 billion for the base year, with narrower branded-only definitions producing lower figures near USD 0.48 billion.
2. What is the Kosher Salt Market growth rate?
The market is projected to grow at a 6.5% CAGR from 2026 to 2032, reaching USD 2.10 Billion. More aggressive forecasts cite up to 7.8% through 2034, reflecting differing category boundaries.
3. Which region dominates kosher salt demand?
North America leads with roughly 41% of global revenue, supported by extensive foodservice procurement and established domestic manufacturing. Europe follows at about 25%, with Asia-Pacific at 22% and growing fastest.
4. What is the largest kosher salt product segment?
Flake kosher salt leads with approximately 48% of revenue, valued near USD 648 million in 2025. Its distinctive crystal structure supports professional cooking, finishing and food processing applications where controlled seasoning matters.
5. Who are the leading kosher salt suppliers?
Key suppliers include Cargill's Diamond Crystal brand, Morton Salt, SaltWorks, True Salt, K+S Windsor Salt and Jacobsen Salt Co. Competition centers on proprietary crystallization technology, distribution scale and private-label manufacturing flexibility.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain: raw salt producers and brine/rock extraction operators, specialized kosher-certified crystallization facilities, contract blenders and flavored-salt formulators, and global foodservice and retail distributors. Decision-maker designations included VP of Sourcing, Heads of R&D and Product Development, Technical Directors overseeing crystallization, and Commercial Operations Leads managing distributor relationships. Each interview captured capacity, specification requirements, pricing bands and switching behavior.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
35%
R&D & Product Development Heads
30%
Technical & Crystallization Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Salt Producers & Extraction Operators
40%
Kosher-Certified Crystallization Facilities
25%
Blenders & Flavored Salt Formulators
20%
Distributors & Foodservice Suppliers
15%
Secondary Benchmarking & Public Trade Validation
Findings were cross-validated against UN Comtrade and WTO salt trade flows, US ITC and Eurostat tariff classifications, corporate annual filings and investor presentations, patent records covering crystallization processes, and recognized standards bodies including Codex Alimentarius and kosher certification authorities. Publicly listed retail and wholesale prices were used to triangulate positioning rather than to establish total revenue.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. Top-down allocation used macroeconomic food-manufacturing and foodservice indicators to distribute category value by segment and geography. Bottom-up modeling aggregated manufacturer capacity, observed product pricing and end-use consumption volumes. Divergence between the two approaches was reconciled at the segment level to avoid double counting across product, application and channel dimensions.


 Kosher Salt Market