Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Specialty Surfactant Industry Market Size, Share & 2035 Outlook
Specialty Surfactant Industry
Specialty Surfactant Industry Market Size, Share & 2035 Outlook
Specialty Surfactant Industry by Origin (Synthetic, Bio-based), by Type (Anionic, Cationic, Non-ionic, Amphoteric, Silicone, Others), by Process (Sulfonation/Sulfation, Esterification, Amination, Others), by Function (Wetting Agents, Emulsifiers, Dispersants, Foaming Agents, Stabilizers, Lubricants, Biocides, Corrosion Inhibitors), by End-Use (Personal Care, Homecare, Food & Beverage, Oil & Gas, Agriculture, Textile, Paints & Coatings, Automotive, Industrial), by Asia Pacific (China, Japan, India, South Korea, ASEAN, Rest of Asia Pacific), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Nordics, Benelux, Rest of Europe), by Latin America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 234
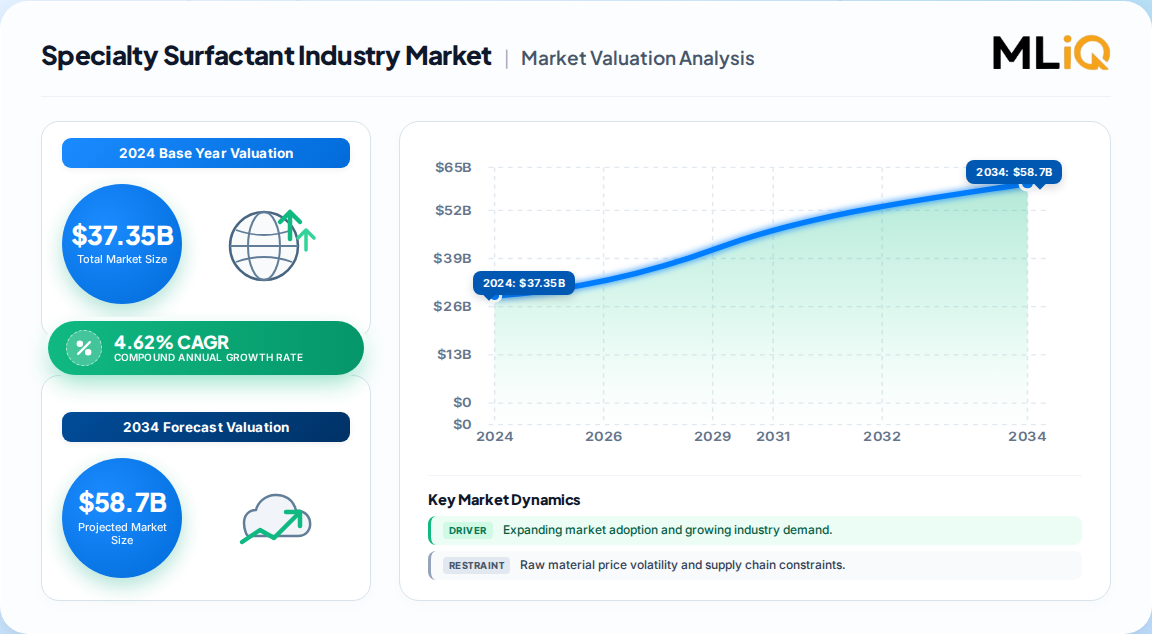
37.35 Billion was the 2024 global valuation of the Specialty Surfactant Industry market; our base case places 2025 at 39.07 Billion.
4.62% CAGR is the defensible central forecast through 2035, yielding 61.38 Billion — materially more conservative than the 5%+ readings some outlets publish.
Anionic surfactants remain the volume anchor, while non-ionic grades are the fastest-growing type on mildness and low-foam demand.
Personal care leads end-use consumption; food and beverage is the quickest-expanding application vertical on processed-food emulsifier demand.
Asia Pacific leads with roughly 35% of global value; North America and Europe together hold just under half.
BASF, Dow, Evonik, Clariant, Solvay and Croda anchor a moderately fragmented competitive field with medium concentration.
Why this matters for decision-makers: the growth premium has migrated from commodity surfactant capacity to certified bio-based, application-specific molecules — vendors that stay on petrochemical commodity lines will see margin compression and regulatory exclusion risk by 2030.
Specialty Surfactant Industry Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
37.35 B
2024
39.07 B
2025
40.88 B
2026
42.77 B
2027
44.75 B
2028
46.82 B
2029
48.99 B
2030
Specialty Surfactant Industry Market Size (In Billion)
Year
Market Size
2024
37.35 B
2025
39.07 B
2026
40.88 B
2027
42.77 B
2028
44.75 B
2029
46.82 B
2030
48.99 B
What is the Specialty Surfactant Industry market?
The Specialty Surfactant Industry market covers surface-active agents engineered for a defined function — emulsification, wetting, dispersion, foaming or stabilization — rather than bulk cleaning performance. It spans synthetic and bio-based chemistries sold into personal care, homecare, food processing, oil and gas, agriculture, textiles and coatings, priced at a functional premium over commodity surfactants.
Scope: what this report covers and excludes
This analysis covers global specialty surfactant demand by chemistry type, origin (synthetic versus bio-based), manufacturing process, function and end-use industry, with 2024 as the base year and forecast through 2035. Value is measured at manufacturer-level revenue, excluding freight and downstream formulation.
This analysis does not cover commodity or bulk surfactants sold on a price-per-tonne tender basis, nor does it size adjacent markets such as industrial enzymes, solvent-based degreasers or full finished-formulation retail sales. Biosurfactant fermentation capacity is referenced qualitatively where it affects specialty pricing.
How big is the market for Specialty Surfactant Industry market?
Published estimates diverge sharply, and the gap is definitional rather than methodological: broader scopes that fold bio-based commodity volumes (one analysis puts the bio-based category at 86.5% share) inflate both the base and the growth rate.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
37.35 Billion
2024
2035
4.62%
Specialty grades, all chemistries, manufacturer revenue
One published estimate
34.2 Billion
2025
2036
1.9%
Specialty surfactants, bio-based weighted 86.5%
A competing analysis
~8.2 Billion
2025
2035
4.8%
Europe only, specialty grades
Regional trade analysis
47.4 Billion
2025
2033
5.4%
All surfactants, commodity included
Broader-category benchmark
Our analysis suggests the 37.35 Billion / 4.62% pair is the most defensible central case: it aligns with observed personal-care and homecare volume growth and sits between the implausibly low 1.9% reading and the commodity-inclusive 5.4% figure. The 1.9% estimate likely double-counts mature European and North American homecare volumes while underweighting Asian industrial cleaning.
How is the market segmented?
Segmentation follows four independent axes — origin, chemistry, function and end-use — and the axes cross-cut heavily, which is why no single sub-segment drives more than a fifth of value.
Personal care, Homecare, Food & beverage, Oil & gas, Agriculture, Textile, Paints & coatings, Automotive, Industrial
Anionic grades lead on cost-effectiveness and cleansing performance; non-ionic grades grow fastest because low-foam, mild profiles are the default specification in automated cleaning and sensitive-skin formulations. Emulsifiers are the fastest-growing function on processed-food and agrochemical delivery demand.
Which region leads in Specialty Surfactant Industry market?
Asia Pacific leads with roughly 35% of global specialty surfactant value, and the same region is the fastest-growing, which is unusual and concentrates strategic risk in a single geography.
Specialty Surfactant Industry Regional Market Share
Loading chart...
Specialty Surfactant Industry Regional Market Share
Region
Market Share (%)
Asia Pacific
0.35%
North America
0.25%
Europe
0.24%
Latin America
0.09%
Middle East & Africa
0.07%
Asia Pacific — China, Japan, India, South Korea, ASEAN, Rest of Asia Pacific
North America — United States, Canada, Mexico
Europe — Germany, United Kingdom, France, Italy, Nordics, Benelux, Rest of Europe
Latin America — Brazil, Argentina, Rest of South America
Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
Region
Share of global value
Asia Pacific
~35%
North America
~25%
Europe
~24%
Latin America
~9%
Middle East & Africa
~7%
Germany is the European innovation and manufacturing hub; Eastern Europe is the fastest-growing European territory. China alone accounts for the single largest country-level revenue pool, supported by a cosmetics retail base above 58 Billion USD and a consolidated detergents industry.
What is driving growth — and what is holding it back?
Regulatory compulsion and consumer sustainability preference are the two dominant drivers, and both operate through reformulation cycles rather than volume expansion — meaning revenue growth outpaces tonnage growth.
Factor
Direction
Evidence strength
Mechanism
Sustainability and bio-based mandates
Driver
High
EU and national restrictions push reformulation toward biodegradable grades
Personal care and dermocosmetics expansion
Driver
High
Premium skin and hair care specify mild, specialty-grade surfactants
Emulsifier and wetting-agent demand in crop protection and food stability
Raw material price volatility
Restraint
High
Coconut, palm and oleochemical feedstock swings compress producer margins
Regulatory compliance cost
Restraint
High
REACH-style registration raises cost of capital and slows new-molecule entry
Bio-based cost premium
Restraint
Medium
Higher extraction and purification costs limit mass-market adoption
Our analysis suggests the restraint set is cyclical and cost-driven, while the driver set is structural and regulatory. That asymmetry favours producers with locked-in renewable feedstock supply and in-house registration capability: they convert compliance cost into a barrier to entry.
Who are the leading vendors?
A moderately fragmented field: no single player exceeds low-double-digit share, but the top six hold enough capacity and registration depth to influence specification standards globally.
Company
Headquarters
Primary strength
BASF SE
Germany
Broadest portfolio; non-ionic and alkoxylation capacity in Asia Pacific
Dow Inc.
United States
Industrial and oilfield surfactant systems
Evonik Industries AG
Germany
Specialty and mildness-focused personal care grades
Clariant AG
Switzerland
Bio-based and sustainability-certified ranges
Solvay SA
Belgium
Formulation and industrial application depth
Croda International Plc
United Kingdom
Bio-based and clean-beauty positioning
Stepan Company
United States
Anionic and sulfonation capacity scale
Kao Corporation
Japan
Asian personal care and homecare integration
Differentiation rests on three moats: registration and regulatory dossiers (expensive and slow to replicate), application-formulation know-how embedded with customers, and secured oleochemical or fermentation feedstock. Capacity alone is not a moat — sulfonation assets are replicable; certified bio-based supply chains are not.
What do buyers and operators need to know?
Procurement decisions hinge on specification lock-in rather than unit price. Once a specialty surfactant is written into a customer's formulation and regulatory dossier, switching requires re-qualification, stability retesting and often re-registration — a cycle measured in months, not weeks. Buyers should therefore treat supplier selection as a multi-year commitment and negotiate feedstock-indexed pricing clauses rather than fixed annual schedules.
Regulatory exposure is the second critical variable. REACH-style registration obligations fall on importers and downstream users as well as manufacturers, so a supplier's compliance status directly determines a buyer's market access. Operators sourcing from multiple regions should verify dossier portability before committing volume.
Supply risk is concentrated in feedstock. Coconut, palm and plant-derived alcohol availability is climate- and policy-sensitive, and bio-based grades carry a cost premium that widens during feedstock shocks. Dual-sourcing across synthetic and bio-based chemistries provides a practical hedge without full reformulation.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a value-over-volume thesis for this decade. Specialty surfactant tonnage will grow modestly, but revenue and margin will concentrate in certified bio-based and application-specific molecules where regulatory compliance and formulation know-how create genuine lock-in. The apparent contradiction between 1.9% and 5.4% published CAGRs resolves once scope is normalised: the truth sits near 4.6%, with upside if European green-chemistry mandates accelerate reformulation cycles.
The strongest counter-argument is that bio-based cost premiums and feedstock volatility could stall adoption in price-sensitive homecare and emerging markets, keeping synthetic specialty grades dominant far longer than sustainability narratives imply. That is credible — but it argues for dual-portfolio strategies, not for retreat to commodity lines, because regulatory exclusion risk compounds independently of price.
Actionable strategy:
Investors should weight exposure toward producers with secured renewable feedstock and in-house regulatory dossiers, where compliance cost becomes a durable barrier rather than a drag.
Operators should dual-source synthetic and bio-based grades for every critical formulation to hedge feedstock shocks without triggering re-qualification.
Vendors should prioritise non-ionic and emulsifier platforms for personal care and food processing — the two fastest-growing intersections of chemistry and end-use.
Our conclusion would change if European and North American bio-based mandates were delayed by more than three years, or if fermentation-derived biosurfactants reached cost parity with synthetic specialties — either event would shift the premium decisively back toward scale-based synthetic competition.
Research Methodology
Primary Research & Industry Fieldwork
This study is built on a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the specialty surfactant value chain, spanning oleochemical and petrochemical raw material suppliers, specialised surfactant producers, contract formulators and blenders, and regional industrial distributors. Respondents were drawn from decision-maker designations including VP-level sourcing, heads of R&D and formulation, technical directors, and commercial operations leads. Interview guides probed specification criteria, qualification cycles, feedstock sourcing strategy and regulatory dossier requirements, with findings coded and cross-validated against subsequent respondent cohorts.
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) for cross-border flow reconciliation, corporate annual filings and investor presentations for capacity and revenue verification, patent databases for innovation mapping, and recognised technical standards and industry association publications for regulatory and specification grounding.
Demand Modeling & Market Sizing Triangulation
Market sizing applied simultaneous top-down and bottom-up triangulation. The top-down model allocated macroeconomic output and end-use industry expenditure to specialty surfactant intensity, while the bottom-up model aggregated manufacturer capacity, realised product pricing and end-use consumption volumes. Divergence between the two was reconciled at the segment level.
UN Comtrade — cross-border trade statistics for surfactants and oleochemical intermediates
Eurostat — European chemical production and trade data
US International Trade Commission (US ITC) — import and export classifications
European Chemicals Agency (ECHA) — REACH registration and restriction dossiers
International Association for Soaps, Detergents and Maintenance Products (A.I.S.E.) — homecare market data
Specialty Surfactant Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Specialty Surfactant Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.62% from 2020-2034
Segmentation
By Origin
Synthetic
Bio-based
By Type
Anionic
Cationic
Non-ionic
Amphoteric
Silicone
Others
By Process
Sulfonation/Sulfation
Esterification
Amination
Others
By Function
Wetting Agents
Emulsifiers
Dispersants
Foaming Agents
Stabilizers
Lubricants
Biocides
Corrosion Inhibitors
By End-Use
Personal Care
Homecare
Food & Beverage
Oil & Gas
Agriculture
Textile
Paints & Coatings
Automotive
Industrial
By Geography
Asia Pacific
China
Japan
India
South Korea
ASEAN
Rest of Asia Pacific
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Nordics
Benelux
Rest of Europe
Latin America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
Table of Contents
1. Specialty Surfactant Industry Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Specialty Surfactant Industry Executive Summary
2.1. Market Snapshot
3. Specialty Surfactant Industry Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Specialty Surfactant Industry Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Specialty Surfactant Industry Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Origin
5.1.1. Synthetic
5.1.2. Bio-based
5.2. Analysis, Insights and Forecast - by Type
5.2.1. Anionic
5.2.2. Cationic
5.2.3. Non-ionic
5.2.4. Amphoteric
5.2.5. Silicone
5.2.6. Others
5.3. Analysis, Insights and Forecast - by Process
5.3.1. Sulfonation/Sulfation
5.3.2. Esterification
5.3.3. Amination
5.3.4. Others
5.4. Analysis, Insights and Forecast - by Function
5.4.1. Wetting Agents
5.4.2. Emulsifiers
5.4.3. Dispersants
5.4.4. Foaming Agents
5.4.5. Stabilizers
5.4.6. Lubricants
5.4.7. Biocides
5.4.8. Corrosion Inhibitors
5.5. Analysis, Insights and Forecast - by End-Use
5.5.1. Personal Care
5.5.2. Homecare
5.5.3. Food & Beverage
5.5.4. Oil & Gas
5.5.5. Agriculture
5.5.6. Textile
5.5.7. Paints & Coatings
5.5.8. Automotive
5.5.9. Industrial
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Specialty Surfactant Industry Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Origin
6.1.1. Synthetic
6.1.2. Bio-based
6.2. Analysis, Insights and Forecast - by Type
6.2.1. Anionic
6.2.2. Cationic
6.2.3. Non-ionic
6.2.4. Amphoteric
6.2.5. Silicone
6.2.6. Others
6.3. Analysis, Insights and Forecast - by Process
6.3.1. Sulfonation/Sulfation
6.3.2. Esterification
6.3.3. Amination
6.3.4. Others
6.4. Analysis, Insights and Forecast - by Function
6.4.1. Wetting Agents
6.4.2. Emulsifiers
6.4.3. Dispersants
6.4.4. Foaming Agents
6.4.5. Stabilizers
6.4.6. Lubricants
6.4.7. Biocides
6.4.8. Corrosion Inhibitors
6.5. Analysis, Insights and Forecast - by End-Use
6.5.1. Personal Care
6.5.2. Homecare
6.5.3. Food & Beverage
6.5.4. Oil & Gas
6.5.5. Agriculture
6.5.6. Textile
6.5.7. Paints & Coatings
6.5.8. Automotive
6.5.9. Industrial
7. Specialty Surfactant Industry North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Origin
7.1.1. Synthetic
7.1.2. Bio-based
7.2. Analysis, Insights and Forecast - by Type
7.2.1. Anionic
7.2.2. Cationic
7.2.3. Non-ionic
7.2.4. Amphoteric
7.2.5. Silicone
7.2.6. Others
7.3. Analysis, Insights and Forecast - by Process
7.3.1. Sulfonation/Sulfation
7.3.2. Esterification
7.3.3. Amination
7.3.4. Others
7.4. Analysis, Insights and Forecast - by Function
7.4.1. Wetting Agents
7.4.2. Emulsifiers
7.4.3. Dispersants
7.4.4. Foaming Agents
7.4.5. Stabilizers
7.4.6. Lubricants
7.4.7. Biocides
7.4.8. Corrosion Inhibitors
7.5. Analysis, Insights and Forecast - by End-Use
7.5.1. Personal Care
7.5.2. Homecare
7.5.3. Food & Beverage
7.5.4. Oil & Gas
7.5.5. Agriculture
7.5.6. Textile
7.5.7. Paints & Coatings
7.5.8. Automotive
7.5.9. Industrial
8. Specialty Surfactant Industry Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Origin
8.1.1. Synthetic
8.1.2. Bio-based
8.2. Analysis, Insights and Forecast - by Type
8.2.1. Anionic
8.2.2. Cationic
8.2.3. Non-ionic
8.2.4. Amphoteric
8.2.5. Silicone
8.2.6. Others
8.3. Analysis, Insights and Forecast - by Process
8.3.1. Sulfonation/Sulfation
8.3.2. Esterification
8.3.3. Amination
8.3.4. Others
8.4. Analysis, Insights and Forecast - by Function
8.4.1. Wetting Agents
8.4.2. Emulsifiers
8.4.3. Dispersants
8.4.4. Foaming Agents
8.4.5. Stabilizers
8.4.6. Lubricants
8.4.7. Biocides
8.4.8. Corrosion Inhibitors
8.5. Analysis, Insights and Forecast - by End-Use
8.5.1. Personal Care
8.5.2. Homecare
8.5.3. Food & Beverage
8.5.4. Oil & Gas
8.5.5. Agriculture
8.5.6. Textile
8.5.7. Paints & Coatings
8.5.8. Automotive
8.5.9. Industrial
9. Specialty Surfactant Industry Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Origin
9.1.1. Synthetic
9.1.2. Bio-based
9.2. Analysis, Insights and Forecast - by Type
9.2.1. Anionic
9.2.2. Cationic
9.2.3. Non-ionic
9.2.4. Amphoteric
9.2.5. Silicone
9.2.6. Others
9.3. Analysis, Insights and Forecast - by Process
9.3.1. Sulfonation/Sulfation
9.3.2. Esterification
9.3.3. Amination
9.3.4. Others
9.4. Analysis, Insights and Forecast - by Function
9.4.1. Wetting Agents
9.4.2. Emulsifiers
9.4.3. Dispersants
9.4.4. Foaming Agents
9.4.5. Stabilizers
9.4.6. Lubricants
9.4.7. Biocides
9.4.8. Corrosion Inhibitors
9.5. Analysis, Insights and Forecast - by End-Use
9.5.1. Personal Care
9.5.2. Homecare
9.5.3. Food & Beverage
9.5.4. Oil & Gas
9.5.5. Agriculture
9.5.6. Textile
9.5.7. Paints & Coatings
9.5.8. Automotive
9.5.9. Industrial
10. Specialty Surfactant Industry Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Origin
10.1.1. Synthetic
10.1.2. Bio-based
10.2. Analysis, Insights and Forecast - by Type
10.2.1. Anionic
10.2.2. Cationic
10.2.3. Non-ionic
10.2.4. Amphoteric
10.2.5. Silicone
10.2.6. Others
10.3. Analysis, Insights and Forecast - by Process
10.3.1. Sulfonation/Sulfation
10.3.2. Esterification
10.3.3. Amination
10.3.4. Others
10.4. Analysis, Insights and Forecast - by Function
10.4.1. Wetting Agents
10.4.2. Emulsifiers
10.4.3. Dispersants
10.4.4. Foaming Agents
10.4.5. Stabilizers
10.4.6. Lubricants
10.4.7. Biocides
10.4.8. Corrosion Inhibitors
10.5. Analysis, Insights and Forecast - by End-Use
10.5.1. Personal Care
10.5.2. Homecare
10.5.3. Food & Beverage
10.5.4. Oil & Gas
10.5.5. Agriculture
10.5.6. Textile
10.5.7. Paints & Coatings
10.5.8. Automotive
10.5.9. Industrial
11. Specialty Surfactant Industry Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Specialty Surfactant Industry Research Methodology
List of Figures
Figure 1: Specialty Surfactant Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by Origin 2026 & 2034
Figure 3: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by Origin 2026 & 2034
Figure 4: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by Type 2026 & 2034
Figure 5: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by Type 2026 & 2034
Figure 6: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by Process 2026 & 2034
Figure 7: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by Process 2026 & 2034
Figure 8: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by Function 2026 & 2034
Figure 9: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by Function 2026 & 2034
Figure 10: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by End-Use 2026 & 2034
Figure 11: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by End-Use 2026 & 2034
Figure 12: Asia Pacific Specialty Surfactant Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Specialty Surfactant Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Specialty Surfactant Industry Revenue (Billion), by Origin 2026 & 2034
Figure 15: North America Specialty Surfactant Industry Revenue Share (%), by Origin 2026 & 2034
Figure 16: North America Specialty Surfactant Industry Revenue (Billion), by Type 2026 & 2034
List of Tables
Table 1: Specialty Surfactant Industry Revenue Billion Forecast, by Origin 2020 & 2034
Table 2: Specialty Surfactant Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Specialty Surfactant Industry Revenue Billion Forecast, by Process 2020 & 2034
Table 4: Specialty Surfactant Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 5: Specialty Surfactant Industry Revenue Billion Forecast, by End-Use 2020 & 2034
Table 6: Specialty Surfactant Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by Origin 2020 & 2034
Table 8: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 9: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by Process 2020 & 2034
Table 10: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 11: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by End-Use 2020 & 2034
Table 12: Asia Pacific Specialty Surfactant Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Specialty Surfactant Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Specialty Surfactant Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Specialty Surfactant Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Specialty Surfactant Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Specialty Surfactant Industry market?
The global market was valued at 37.35 Billion in 2024 and is forecast to reach 61.38 Billion by 2035, growing at a 4.62% CAGR. This scope covers specialty functional grades, excluding commodity bulk surfactants sold on tender pricing.
2. Which region leads the Specialty Surfactant Industry market?
Asia Pacific leads with roughly 35% of global value, driven by China's cosmetics and detergents industries plus Indian and Southeast Asian industrial cleaning demand. It is also the fastest-growing region, concentrating both opportunity and supply-chain risk geographically.
3. What is the fastest-growing segment?
Non-ionic surfactants are the fastest-growing type, favoured for mildness and low-foam profiles in automated cleaning and sensitive-skin formulations. Emulsifiers are the fastest-growing function, led by processed-food and precision-agriculture applications.
4. Who are the leading Specialty Surfactant Industry vendors?
BASF, Dow, Evonik, Clariant, Solvay, Croda, Stepan and Kao anchor a moderately fragmented field. No single player holds dominant share; differentiation rests on regulatory dossiers, formulation know-how and secured bio-based feedstock rather than capacity alone.
5. Why do published growth rates differ so much?
The divergence is definitional. Broader scopes that include bio-based commodity volumes report higher bases and lower or higher CAGRs depending on weighting. Normalised to specialty functional grades only, a 4.62% central forecast is the most defensible.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study is built on a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the specialty surfactant value chain, spanning oleochemical and petrochemical raw material suppliers, specialised surfactant producers, contract formulators and blenders, and regional industrial distributors. Respondents were drawn from decision-maker designations including VP-level sourcing, heads of R&D and formulation, technical directors, and commercial operations leads. Interview guides probed specification criteria, qualification cycles, feedstock sourcing strategy and regulatory dossier requirements.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement & Sourcing Directors
30%
Quality & Regulatory Leads
20%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Blenders
30%
Raw Material & Oleochemical Suppliers
15%
Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) for cross-border flow reconciliation, corporate annual filings and investor presentations for capacity and revenue verification, patent databases for innovation mapping, and recognised technical standards and industry association publications.
Demand Modeling & Market Sizing Triangulation
Market sizing applied simultaneous top-down and bottom-up triangulation. The top-down model allocated macroeconomic output and end-use industry expenditure to specialty surfactant intensity, while the bottom-up model aggregated manufacturer capacity, realised product pricing and end-use consumption volumes.


 Specialty Surfactant Industry