 Malaysia Passenger Vehicles Lubricants Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Malaysia Passenger Vehicles Lubricants Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 174.0 M |
| 2026 | 177.0 M |
| 2027 | 180.0 M |
| 2028 | 182.0 M |
| 2029 | 185.0 M |
| 2030 | 188.0 M |

The Malaysia passenger vehicles lubricants market covers the volume of engine oils, transmission fluids, brake fluids and greases consumed by cars and light passenger vehicles — both factory-fill and aftermarket service — measured in liters. It is a service-driven, replacement-cycle market tied to the national car parc, workshop density and certification compliance.
This report covers passenger-car and light-passenger-vehicle lubricants in Malaysia across engine oil, automatic and manual transmission fluids, brake fluids and automotive greases, split by synthetic, semi-synthetic and mineral grades and by sales channel (OEM service, quick-lube chains, independent workshops, retail). This analysis does not cover commercial-vehicle lubricants, two-wheeler oils, industrial or marine lubricants, base-oil refining economics, or EV battery thermal fluids as a standalone segment.
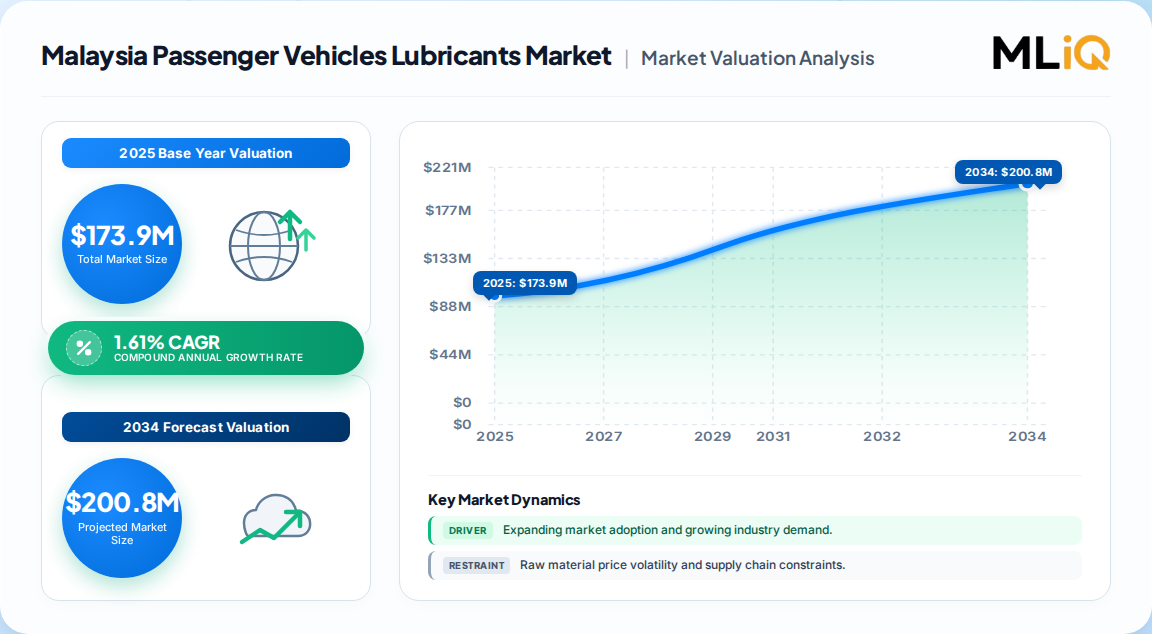
The most defensible read is roughly 174 million liters in 2025, derived from a 299.67-million-liter total automotive lubricants base and a 57.12% passenger-vehicle share, growing toward 188 million liters by 2031. The table below shows how published framings differ.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 299.67 million liters (total automotive) | 2025 | 2031 | 1.61% | All vehicle types, all lubricant products | One published industry estimate |
| 173.9 million liters (passenger vehicles) | 2025 | 2031 | 1.61% | PV share derived at 57.12% of total | Our derivation from published split |
| 304.49 million liters (total, 2026 base) | 2026 | 2031 | 1.61% | All vehicle types, 2026 base year | One published industry estimate |
Our analysis treats the derived passenger-vehicle figure as most defensible because it is internally consistent with the stated vehicle-type share. The higher total-market figure is not a contradiction — it simply includes commercial vehicles and two-wheelers, which grow at a faster 1.88% and reduce the passenger-vehicle contribution to incremental growth over time.
Segmentation is product-led, with engine oil the anchor and transmission fluids the fastest-moving niche as automatic and dual-clutch drivetrains penetrate the car parc.
| Parent segment | Children | 2025 signal |
|---|---|---|
| Product type | Engine oil, automatic transmission fluid, manual transmission fluid, brake fluid, automotive grease | Engine oil ~55.26% of automotive volume; ATF fastest at 1.82% CAGR |
| Grade / technology | Fully synthetic, semi-synthetic, mineral | Synthetics gaining share post-diesel-subsidy reform |
| Sales channel | OEM service centres, quick-lube chains, independent workshops, retail | Quick-lube chains expanding fastest |
| Vehicle powertrain | ICE, hybrid, plug-in hybrid, battery electric | HEV/BEV only 2–3% of 2024 sales but policy-targeted to 15% by 2030 |
Callout: Engine oil alone represents more liters than every other passenger-vehicle lubricant category combined — but transmission and low-viscosity synthetic grades carry the pricing upside.
The Klang Valley leads, accounting for roughly 38% of national passenger-vehicle lubricant consumption, followed by Johor and Penang, reflecting car-parc density, workshop concentration and average income.
| Region | Market Share (%) |
|---|---|
| Klang Valley | 0.38% |
| Johor | 0.18% |
| Penang | 0.14% |
| Perak | 0.09% |
| Sabah & Sarawak | 0.11% |
| Other States | 0.1% |
Demand concentration matters for route-to-market. Quick-lube chains and OEM service networks cluster where vehicle density is highest, so national coverage claims from suppliers overstate effective reach. Secondary cities in Johor and Penang are the clearest white space for organized formats.
Parc growth and premiumization drive volume and value, while electrification and extended drain intervals cap the upside. The net effect is a low-growth, high-mix-shift market.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising vehicle parc and motorization | Driver | High | 202,245 units registered Jan–Mar 2024, up 5% YoY |
| Quick-lube and OEM service expansion | Driver | High | PETRONAS AutoExpert targeting 100 outlets |
| Low-viscosity synthetics post-subsidy reform | Driver | High | Diesel subsidy removal lifted fuel-economy focus |
| Mandatory engine-oil certification | Driver | High | Trade Descriptions Order enforced from Oct 2025 |
| HEV/BEV penetration | Restraint | Medium | 2–3% of 2024 sales; 15% target by 2030 |
| Drain-interval stretching | Restraint | Medium | Cost pressure on fleets |
| Grey and illicit oils | Restraint | Medium | Undercuts branded players in rural channels |
Balance of evidence: The premiumization driver is stronger than the volume driver. Litre growth of 1.61% understates the revenue opportunity because synthetics and ATF carry materially higher value per litre. The certification order is the pivotal swing factor — it structurally advantages large, traceable brands at the expense of small blenders.
The field is moderately concentrated, led by PETRONAS Lubricants International, Shell, BP, Chevron and ExxonMobil, with domestic blenders contesting the value tier.
| Company | Positioning | Key moat |
|---|---|---|
| PETRONAS Lubricants International | Domestic leader | Group III supply, AutoExpert network, national brand |
| Shell plc | Premium international | Brand trust, synthetic portfolio |
| BP p.l.c. | Premium international | Global OEM approvals, distribution |
| Chevron Corporation | Mainstream and premium | Additive and formulation depth |
| ExxonMobil Corporation | Premium synthetic | Technology leadership, OEM ties |
| Domestic blenders | Value tier | Cost, local reach, ETRO+ Group III access |
Our analysis suggests the certification order is a moat-widener for incumbents. Smaller blenders face testing and traceability costs that large players already absorb, accelerating consolidation through the formal channel. Differentiation increasingly rests on OEM approval lists and quick-lube partnerships rather than price.
Procurement decisions in this market hinge on four things: certified supply, OEM specification compliance, channel access and switching cost. Buyers should demand SIRIM QAS certification and tamper-evident packaging from every supplier — non-compliance carries fines up to MYR 200,000 per corporate offence and exposes operators to reputational risk.
Switching costs are rising. OEM warranty terms and quick-lube chain procurement standards increasingly lock in exact-spec products, which narrows the pool of qualified suppliers. Fleet operators should model total cost of ownership rather than per-litre price, because extended drain intervals and fuel-economy gains from 0W-20 and 5W-30 synthetics can offset a higher sticker price. Procurement risk is concentrated in rural and independent-workshop channels, where grey and counterfeit oils remain a live threat despite enforcement. Buyers should audit distributor traceability and prefer suppliers with domestic Group III access, which buffers against import-price volatility.
The balance of evidence favors a value-over-volume strategy in Malaysia's passenger-vehicle lubricant market. The 1.61% volume CAGR is close to the national car-parc replacement rate, so incremental litre gains will be marginal. The real opportunity lies in mix: shifting buyers from mineral 15W-40 to synthetic 0W-20 and 5W-30 grades, and capturing the 1.82% ATF growth as automatic drivetrains spread. Our analysis suggests revenue could grow at roughly twice the volume rate if premiumization holds.
The strongest counter-argument is that HEV/BEV adoption, targeted at 15% of sales by 2030, could compress engine-oil volumes faster than the base case assumes. That risk is real but back-loaded — EVs are still only 2–3% of 2024 sales, and the car parc turns over slowly. The certification order is the nearer-term disruptor, and it favors incumbents.
Actionable strategy:
What would change our conclusion: a faster-than-expected EV share trajectory (above 8% by 2028) or a relaxation of the certification order would shift value back toward price-led competition. Precise sub-segment forecasting by grade and channel is beyond this overview and requires the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 1.61% from 2020-2034 |
| Segmentation |
|
Roughly 173.9 million liters in 2025, derived from the 299.67-million-liter total automotive lubricants base and the 57.12% passenger-vehicle share. It is projected to reach about 188.4 million liters by 2031.
About 1.61% CAGR from 2026 to 2031, roughly in line with national car-parc growth, with value growth outpacing volume as synthetic and low-viscosity grades gain share.
Engine oil leads with roughly 55% of automotive lubricant volume. Automatic transmission fluid is the fastest-growing product category at about 1.82% CAGR through 2031.
PETRONAS Lubricants International leads domestically, alongside Shell, BP, Chevron and ExxonMobil. Domestic blenders contest the value tier, facing rising certification costs.
Rising vehicle registrations, quick-lube chain expansion, the shift to low-viscosity synthetics after diesel-subsidy reform, and the mandatory engine-oil certification order curbing counterfeits.
Rising HEV and BEV penetration compresses engine-oil volumes, while cost-driven drain-interval stretching and grey-market oils undercut branded players, particularly in rural channels.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis follows a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the passenger-vehicle lubricant value chain, including base-oil and additive suppliers, specialized formulators and blenders, OEM service-network operators, and national distributors. Interviewees included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads at quick-lube chains. These interviews validated volume estimates, channel pricing and certification compliance behaviour across Klang Valley, Johor and secondary cities.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Base-Oil & Additive Suppliers | 30% |
| Specialized Formulators & Blenders | 35% |
| OEM Service & Quick-Lube Operators | 20% |
| National Distributors & Retailers | 15% |
We benchmarked findings against official multilateral trade data from UN Comtrade (HS Chapter 27 and 38 lubricant flows), WTO tariff schedules, and national customs records for Malaysia. Corporate annual filings, investor presentations from listed lubricant producers, patent databases, and technical standards from API, ILSAC and SIRIM QAS were used to validate specification cycles and certification timelines. Regulatory analysis drew on Malaysia's Trade Descriptions Order and fuel-subsidy reform records.
We ran simultaneous Top-Down (macroeconomic car-parc and segment allocation) and Bottom-Up (blender capacity, product pricing, end-use consumption) models. The two were reconciled against trade-flow data to isolate passenger-vehicle lubricant volume and forecast value mix shifts by grade.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value and volume for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | State-level share breakdown | Cross-border trade flow and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |