 Technology Trends in Lubricants (Mineral, Synthetic, and Bio-based) MarketTechnology Trends in Lubricants (Mineral, Synthetic, and Bio-based) Market

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Technology Trends in Lubricants (Mineral, Synthetic, and Bio-based) Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 181.1 B |
| 2026 | 189.4 B |
| 2027 | 198.1 B |
| 2028 | 207.2 B |
| 2029 | 216.8 B |
| 2030 | 226.7 B |
| 2031 | 237.2 B |

The technology trends in lubricants market refers to the evolution of formulation, base-oil processing, additive chemistry, and application-specific engineering across mineral, synthetic, and bio-based lubricants. It covers product development shifts toward longer-drain, energy-efficient, and biodegradable fluids used in automotive, industrial, marine, and power generation applications globally.
This analysis covers the global lubricants market segmented by base oil (mineral, synthetic, bio-based), product type (engine oils, hydraulic fluids, greases, metalworking fluids, process oils, and others), and end-use industry (automotive, industrial, marine, aviation, power generation). It quantifies market size, forecasts 2026–2034, and profiles leading vendors. This analysis does not cover additive-only chemical markets, base-oil refinery feedstock markets, or lubricant packaging and dispensing equipment.
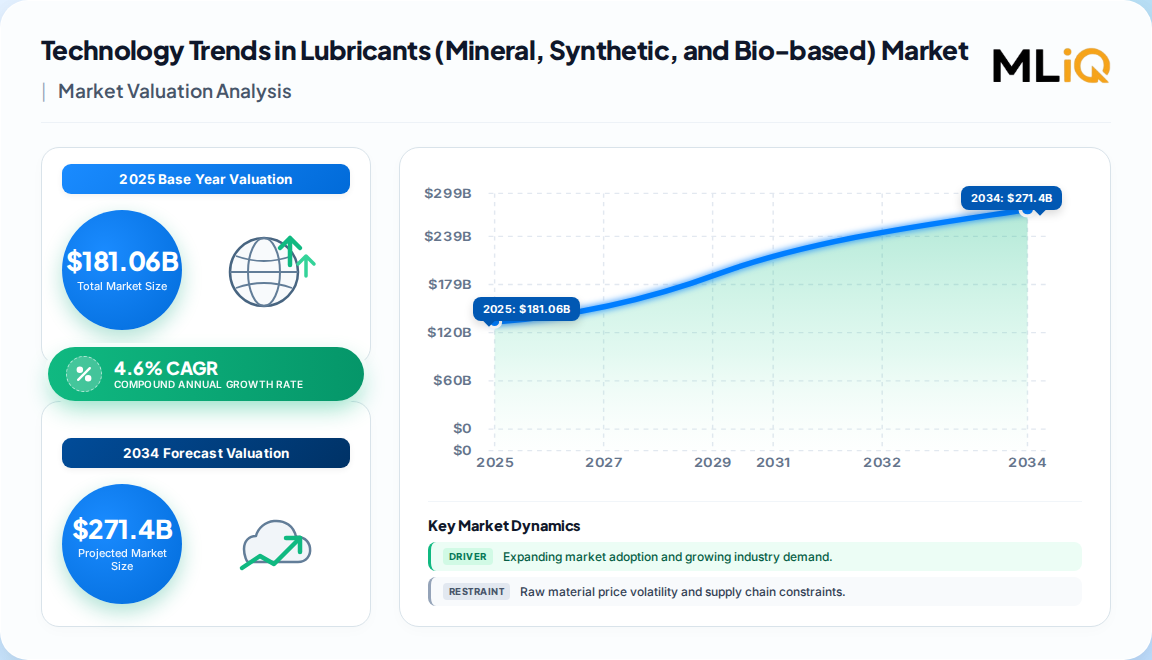
The global lubricants market is estimated at US$ 181.06 Billion in 2025 and projected to reach US$ 271.48 Billion by 2034, at a 4.6% CAGR. Estimates vary by scope and segment inclusion, as shown below.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| US$ 181.06 Billion | 2025 | 2034 | 4.6% | Total lubricants, all base oils, global | One published estimate |
| US$ 79.50 Billion | 2026 | 2035 | 3.48% | Industrial lubricants only, global | A competing analysis |
| US$ 2.50 Billion | 2025 | 2034 | 3.1% | Bio-lubricants only, global | Another published estimate |
| US$ 3.21 Billion | 2025 | 2034 | 7.16% | Bio-based lubricants only, global | A third published estimate |
The US$ 181.06 Billion figure is the most defensible total-market benchmark because it explicitly includes automotive, industrial, marine, and aviation end-uses across all three base-oil types. The industrial-only figure (US$ 79.50 Billion) is consistent once automotive is excluded. The wide spread in bio-lubricant estimates (US$ 2.50 Billion vs US$ 3.21 Billion) reflects differing definitions of synthetic esters and PAG inclusion, implying buyers should validate feedstock and product scope before comparing vendor claims.
The market is segmented by base oil, product type, and end-use industry. Base oil is the primary technology axis, with mineral, synthetic, and bio-based formulations driving distinct performance and pricing profiles.
| Parent Segment | Children |
|---|---|
| By Base Oil | Mineral Oil, Synthetic Oil, Bio-based Oil |
| By Product Type | Hydraulic Fluids, Engine Oils, Driveline Lubricants, Metalworking Fluids, Grease, Process Oils, Coolants, Transformer Oils, Others |
| By End-Use Industry | Automotive (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Others), Building & Construction, Power Generation, Mining & Metallurgy, Food Processing, Oil & Gas, Marine, Aviation, Others |
Asia Pacific leads the global lubricants market with approximately 27.85% share in 2025, followed by Europe at 23.50% and North America at 20.20%. Asia Pacific is also the fastest-growing region at a 5.4% CAGR, supported by manufacturing expansion in China, India, and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.24% |
| Asia-Pacific | 0.4% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
North America's share is anchored by mature automotive fleets, industrial automation, and premium synthetic adoption. Europe's lead in bio-based lubricants (36.80% regional share in a separate bio-based estimate) reflects EU Ecolabel and Green Deal mandates. Asia Pacific's growth is volume-led, with India's wind energy target of 140 GW by 2030 creating structural demand for biodegradable industrial fluids.
Growth is driven by vehicle fleet expansion, industrial automation, and tightening environmental regulations, while high synthetic and bio-based price premiums and feedstock volatility restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Vehicle fleet and commercial transportation expansion | Driver | High | Increases engine oil, driveline, and grease demand across aftermarket and first-fill |
| Industrial automation and equipment reliability requirements | Driver | High | Raises demand for long-drain, high-performance hydraulic and process oils |
| Stringent environmental regulations (EPA VGP, EU Ecolabel) | Driver | High | Mandates EALs in marine, forestry, and water-adjacent operations |
| ESG and corporate decarbonization commitments | Driver | Medium | Drives Scope 3 reduction and bio-based procurement |
| Price premium of synthetic and bio-based vs mineral (20–40%) | Restraint | High | Limits adoption in price-sensitive industrial segments |
| Feedstock volatility and competition from renewable diesel/SAF | Restraint | Medium | Raises bio-based input costs and extends procurement timelines |
| EV drivetrain fluid requirements | Opportunity | Medium | Creates new demand for thermal fluids, e-drive fluids, and specialty greases |
| AI-enabled formulation and predictive maintenance | Opportunity | Medium | Improves product reproducibility and enables condition-based service models |
The balance of evidence favors continued volume expansion in mineral and synthetic lubricants, with bio-based formulations growing from a small base at nearly twice the market rate. The key second-order effect is margin migration: as bio-based and synthetic share rises, integrated producers with feedstock control and OEM approvals will capture disproportionate value, while undifferentiated mineral blenders face compression.
The lubricants market is led by integrated oil majors and specialized formulators, with Shell, ExxonMobil, TotalEnergies, Chevron, and BP controlling the broadest global portfolios, while FUCHS and Valvoline differentiate on specialty formulations and technical services.
| Company | Portfolio Strength | Technology Focus |
|---|---|---|
| Shell plc | Global integrated, broad base-oil and additive capability | Synthetic, EV fluids, circularity |
| ExxonMobil Corporation | Global scale, premium synthetic brands | Long-drain synthetic, industrial reliability |
| TotalEnergies SE | Integrated refining and bio-feedstock partnerships | Bio-based, renewable feedstock |
| Chevron Corporation | Integrated base-oil and finished lubricants | Synthetic, marine, industrial |
| BP p.l.c. | Global brand and distribution | Synthetic, automotive aftermarket |
| FUCHS SE | Specialty formulations and technical services | Bio-based EALs (PLANTO), metalworking |
| Valvoline Inc. | Automotive aftermarket focus | Synthetic, consumer and installer channels |
Differentiation is shifting from base-oil access to formulation expertise, OEM approvals, and sustainability credentials. FUCHS's PLANTO biodegradable series and TotalEnergies' Avril feedstock agreement illustrate how bio-based supply-chain control is becoming a competitive moat. Integrated majors retain cost advantages but face slower specialty innovation cycles than focused formulators.
Buyers should prioritize OEM approvals, life-cycle cost, and regulatory compliance over headline price. Bio-based and synthetic formulations carry 20–40% premiums, but extended drain intervals, reduced maintenance, and EAL compliance cost avoidance often deliver lower total cost of ownership. Switching costs are material in marine, forestry, and offshore operations where re-certification and equipment compatibility testing are required. Procurement risk is concentrated in feedstock volatility, particularly for bio-based products exposed to renewable diesel and SAF competition for vegetable oils. Supply continuity and regional blending capacity are increasingly important selection criteria, and buyers should require documented biodegradability and toxicity data aligned with EPA VGP and EU Ecolabel standards.
The balance of evidence favors a portfolio shift toward synthetic and bio-based formulations, not a wholesale replacement of mineral oils. Mineral lubricants will retain majority volume through 2034, but their share of value and margin will erode as regulation and OEM specifications favor higher-performance, lower-environmental-impact products. The strongest counter-argument is that price-sensitive emerging markets will sustain mineral demand longer than forecast, particularly in India, Southeast Asia, and Africa where cost dominates procurement. This divergence implies a two-speed market: premium regulated regions adopting bio-based EALs rapidly, and volume markets continuing mineral-led growth.
Our analysis suggests the most defensible strategic position is a hybrid portfolio with regionalized formulation and feedstock sourcing. Vendors with bio-based feedstock partnerships, such as TotalEnergies' Avril agreement, and specialty formulators with OEM approvals, such as FUCHS, are best positioned to capture margin migration. Integrated majors must accelerate specialty innovation or risk ceding high-value segments to focused competitors.
Actionable Strategy:
What would change this conclusion: a sustained collapse in vegetable oil feedstock prices or a regulatory rollback of EAL mandates would narrow the bio-based premium and slow adoption, favoring mineral and synthetic incumbents. Conversely, accelerated EV adoption could reduce engine oil volume faster than forecast, shifting value toward thermal and drivetrain fluids.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.6% from 2020-2034 |
| Segmentation |
|
The global lubricants market was valued at US$ 181.06 Billion in 2025, spanning mineral, synthetic, and bio-based base oils across automotive, industrial, marine, and aviation applications.
The market is projected to grow at a 4.6% CAGR from 2026 to 2034, reaching US$ 271.48 Billion by 2034, driven by fleet expansion, industrial automation, and formulation upgrades.
Asia Pacific leads with approximately 27.85% share in 2025, followed by Europe at 23.50% and North America at 20.20%. Asia Pacific is also the fastest-growing region at a 5.4% CAGR.
Key trends include synthetic and bio-based formulation growth, longer drain intervals, EV drivetrain fluids, AI-enabled formulation, and blockchain-enabled supply chain traceability for bio-based feedstocks.
Leading companies include Shell, ExxonMobil, TotalEnergies, Chevron, BP, FUCHS SE, and Valvoline, competing on portfolio breadth, OEM approvals, and sustainability credentials.
Stringent environmental regulations such as EPA VGP and EU Ecolabel, corporate decarbonization commitments, and improved formulation performance are driving bio-based lubricant adoption, despite 20–40% price premiums.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the lubricants value chain, including base-oil and additive suppliers, specialty formulators and blenders, contract manufacturers, and global industrial distributors. Decision-makers interviewed include VP-level sourcing executives, Heads of R&D and formulation, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, technology, and market strategy perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Base Oil & Additive Suppliers | 40% |
| Specialty Formulators & Blenders | 35% |
| Distributors & Traders | 25% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards and industry associations. These sources are used to cross-check volume flows, pricing trends, and technology adoption benchmarks.
We apply simultaneous top-down and bottom-up modeling. Top-down allocation uses macroeconomic and industry segment data to size demand by end-use and region. Bottom-up modeling uses manufacturer capacity, product pricing, and end-use consumption data. The two approaches are triangulated to produce a validated base-year market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |