Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
PVC Market Size, Share & Growth Outlook 2026
PVC Market Size, Share & Growth Outlook 2026
PVC Market
PVC Market Size, Share & Growth Outlook 2026
PVC Market by Product Type (Rigid PVC, Flexible PVC, Low Smoke PVC, Chlorinated PVC), by Manufacturing Process (Suspension PVC, Emulsion PVC, Bulk Polymerization), by Stabilizer Type (Calcium-Based Stabilizers, Lead-Based Stabilizers, Organotin Stabilizers, Others), by Application (Pipes & Fittings, Profiles & Tubes, Film & Sheets, Wire & Cables, Bottles, Others), by End-User Industry (Building & Construction, Automotive, Electrical, Packaging, Healthcare, Footwear), by Asia-Pacific (China, India, Japan, South Korea, Taiwan, Southeast Asia, Australia), by North America (United States, Canada, Mexico), by Europe (Germany, UK, France, Italy, Russia, Spain, Rest of Europe), by South America (Brazil, Argentina, Colombia, Peru, Chile), by Middle East & Africa (Saudi Arabia, UAE, Turkey, Egypt, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 234
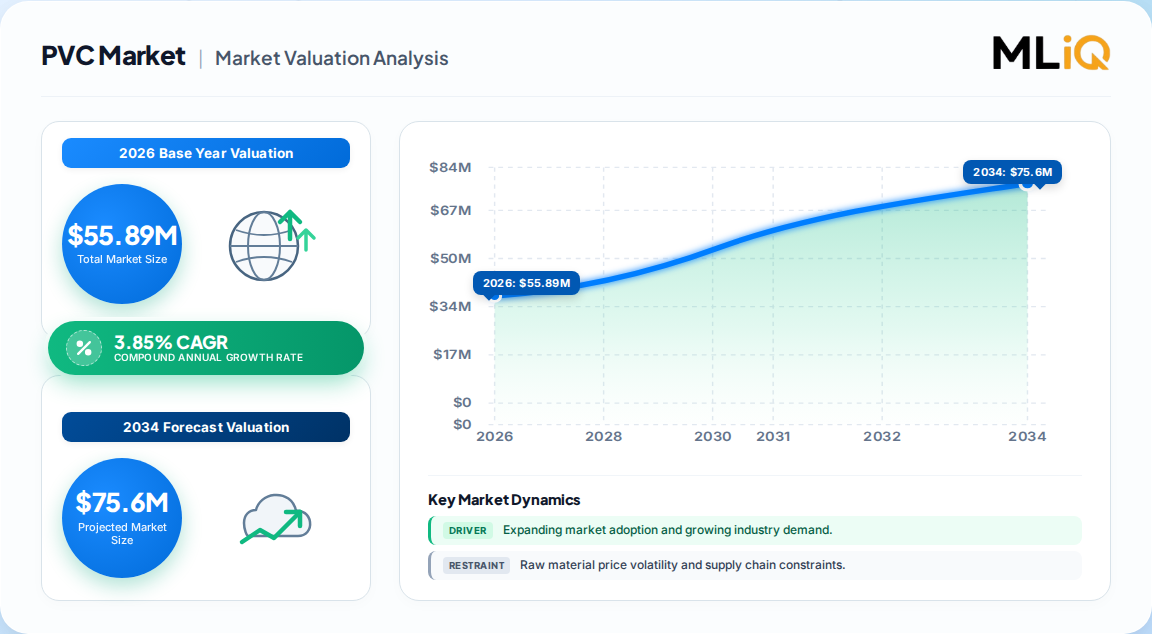
55.89 million tons in 2026 — the global PVC market is entering a consolidation phase as Chinese overcapacity meets resilient infrastructure demand.
67.51 million tons by 2031 — a 3.85% CAGR that masks sharp regional divergence: Asia-Pacific compounds at 4.21% while North America trails at 3.1%.
Rigid PVC commands 61.4% of volume, anchored by pipes and fittings (49.4% of applications), with chlorinated PVC the fastest-growing niche at 4.55% CAGR.
Asia-Pacific produces and consumes nearly 60% of global PVC, with China alone representing roughly 45% of demand — the region's construction cycle is the single largest swing factor for global pricing.
Building and construction accounts for 69.3% of end-use revenue, making PVC a leveraged play on global capex cycles rather than a diversified chemicals bet.
Calcium-based stabilizers reached 47.6% share in 2025, displacing lead-based systems faster than most procurement teams anticipated — a compliance-driven substitution shift.
Why this matters for decision-makers: Buyers who negotiate calcium-stabilizer grades and phthalate-free flexible compounds today will avoid the margin shock facing competitors locked into lead-based or DEHP-plasticized supply chains through 2030.
PVC Market Size (In Million)
75.0M
60.0M
45.0M
30.0M
15.0M
0
56.00 M
2026
58.00 M
2027
60.00 M
2028
63.00 M
2029
65.00 M
2030
68.00 M
2031
PVC Market Size (In Million)
Year
Market Size
2026
56.00 M
2027
58.00 M
2028
60.00 M
2029
63.00 M
2030
65.00 M
2031
68.00 M
What is the PVC Market?
The PVC market is the global industry producing and trading polyvinyl chloride resin, compounds, and finished products — from rigid pipes and window profiles to flexible medical tubing, wire insulation, and packaging film. It is a volume-driven commodity market where cost of feedstock (ethylene and chlorine) and construction demand determine profitability.
Scope: what this report covers and excludes
This analysis covers global PVC resin and compound volumes across rigid, flexible, low-smoke, and chlorinated product types; suspension and emulsion manufacturing processes; calcium-based, lead-based, and organotin stabilizer systems; pipes, profiles, films, bottles, and wire-and-cable applications; and end-use sectors including construction, automotive, healthcare, packaging, and electrical. This analysis does not cover chlor-alkali co-products (caustic soda, chlorine gas) as standalone markets, nor does it cover non-PVC vinyl polymers such as PVDC or PVDF.
How big is the market for PVC Market?
Published estimates range from 30 million tons to 56 million tons, with the divergence driven almost entirely by definitional scope rather than real volume differences. The most defensible anchor is the mid-50s million-ton figure, which aligns with trade-flow data from major producing nations.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
55.89 million tons
2026
2031
3.85%
Global PVC resin and compound volume, all product types
Industry consensus reference
67.51 million tons
2031
—
—
Forecast endpoint of the same series
Same source, forecast horizon
30.17 million tons
2025
2035
4.30%
Global PVC volume, likely narrower resin-only or tradeable-grade scope
Competing published analysis
45.96 million tons
2035
—
—
Forecast endpoint of the narrower scope
Same competing analysis
8.5 billion USD
2023
2030
3.6%
Value-based, likely resin-only at producer-level pricing
Value-based estimate
Our analysis suggests the 55–56 million ton base is the most defensible for procurement and investment planning because it reconciles with visible pipe, profile, and wire-and-cable consumption volumes across Asia-Pacific and North America. The 30 million ton figure likely excludes compounded and downstream-converted PVC, which understates the addressable market by nearly half. Buyers should insist on volume-based scoping — value-based estimates are distorted by the 2022–2024 price collapse and do not reflect physical material availability.
How is the market segmented?
The PVC market segments along four non-geographic axes: product type, manufacturing process, stabilizer chemistry, and application end-use.
Building & construction, Automotive, Electrical, Packaging, Healthcare, Footwear
Construction 69.3%, 4.02% CAGR
The critical insight for buyers is that stabilizer chemistry is the segment most exposed to regulatory risk: lead-based systems face explicit bans under EU REACH and Indian BIS standards, while organotin is growing despite toxicity scrutiny. Our analysis suggests the calcium-based transition is now irreversible in Western markets, and procurement contracts specifying lead-based grades beyond 2028 carry genuine supply-continuity risk.
Which region leads in PVC Market?
Asia-Pacific leads decisively, accounting for 59.4% of global PVC consumption in 2025 and forecast to grow at 4.21% through 2031 — nearly double North America's growth rate. China's construction cycle and India's infrastructure pipeline are the two dominant demand engines.
PVC Market Regional Market Share
Loading chart...
PVC Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.59%
North America
0.21%
Europe
0.12%
South America
0.04%
Middle East & Africa
0.04%
Parent
Children
Asia-Pacific
China, India, Japan, South Korea, Taiwan, Southeast Asia, Australia
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Russia, Spain, Rest of Europe
South America
Brazil, Argentina, Colombia, Peru, Chile
Middle East & Africa
Saudi Arabia, UAE, Turkey, Egypt, South Africa
Region
2025 share
Forecast CAGR (2026–2031)
Asia-Pacific
59.4%
4.21%
North America
21.0%
3.12%
Europe
12.0%
3.87%
South America
4.0%
1.03%
Middle East & Africa
3.6%
1.87%
The divergence between Asia-Pacific's 4.2% CAGR and South America's 1.0% is the widest in a decade. This implies global PVC pricing will increasingly be set by Chinese export decisions rather than by balanced regional supply-demand. Buyers in North America and Europe should expect periodic import surges that create short-term buying windows, but also compress domestic producer margins and may trigger anti-dumping actions.
What is driving growth — and what is holding it back?
Growth is driven by water infrastructure, medical device demand, and construction in fast-urbanizing Asia — but these tailwinds are partially offset by additive regulations, packaging substitution, and feedstock volatility.
Factor
Direction
Evidence strength
Mechanism
Urban infrastructure expansion in Asia megacities
Driver
Strong
Large-diameter pipe specification; long-term government funding
Clean-water infrastructure upgrades
Driver
Strong
Corrosion-resistant PVC replacing aging metal mains
Weight savings improve EV range; recycled content gains
Lead-based stabilizer bans
Restraint
Strong
EU REACH and Indian BIS compliance deadlines
Phthalate-free packaging push
Restraint
Moderate
Brand-owner sustainability commitments
Ethylene price volatility
Restraint
Strong
Direct feedstock-cost pass-through; margin compression
Chinese overcapacity
Restraint
Strong
Export price suppression; global margin compression
The balance of evidence favors the drivers: our analysis suggests net PVC volume growth of roughly 3.5–4% annually is structurally supported by water infrastructure and construction, even as additive regulations remove certain legacy product categories. The most underappreciated restraint is Chinese overcapacity — not because it reduces global demand, but because it exports deflation. Buyers benefit from lower prices short-term, but producer consolidation and potential trade remedies could tighten supply abruptly by 2029.
Who are the leading vendors?
Shin-Etsu (including Shintech), Westlake, INEOS, and Orbia lead the global PVC market, with Chinese producers holding dominant domestic share but limited branded export presence. Competitive moats are built on feedstock integration, not product differentiation.
Company
HQ
Strategic position
Recent development
Shin-Etsu / Shintech
Japan / US
Largest global PVC capacity; vertically integrated chlorine-ethylene
USD 3.4 billion Louisiana expansion announced March 2026, targeted 2030
Westlake
US
Integrated chlor-alkali and vinyls; electrical infrastructure focus
Acquired ACI January 2026 for high-voltage wire and cable position
INEOS
UK / Europe
European market leader; low-VOC resin upgrade strategy
Upgraded European plants July 2025 for low-VOC sustainable PVC
Orbia
Mexico / Global
Americas-focused vinyls and pipe systems
Launched Vinyl in Motion recycling initiative May 2025
Formosa Plastics
Taiwan / US
Large-scale commodity PVC producer
Capacity expansion in North America
Chinese producers (aggregate)
China
Dominant domestic volume; export price setters
Overcapacity driving global price deflation
Differentiation is thin: PVC resin is largely a commodity, and producers compete on feedstock integration, logistics, and regulatory-compliant additive packages. Our analysis suggests the Shintech and Westlake investments are strategic bets that Chinese overcapacity will ease by 2030, creating a North American supply-demand gap. For buyers, this means single-sourcing from any one producer carries long-term price risk as consolidation and capacity rationalization reshape the landscape.
What do buyers and operators need to know?
PVC procurement in 2026–2031 is a regulatory-compliance exercise as much as a price negotiation. Three mission-critical criteria determine total cost of ownership: stabilizer chemistry compliance, plasticizer migration profile, and supplier feedstock integration.
Regulatory compliance is now non-negotiable. California's DEHP ban takes effect in 2030, and the EU has postponed its own DEHP prohibition until mid-2030 — but both deadlines are firm. Buyers of flexible PVC for medical or packaging applications should require DOTP or other phthalate-free plasticizer declarations in every contract now, because re-qualification cycles in medical device manufacturing run 18–24 months. Our analysis suggests the premium for DEHP-free compounds will narrow by 2028 as capacity scales, but supply of qualified medical-grade compounds will remain tight through 2027.
Switching costs are asymmetric. Moving from lead-based to calcium-based stabilizers in rigid pipe applications is straightforward and low-cost — most processors have already done it. Moving from DEHP to DOTP in flexible medical tubing is expensive, requiring new validation, biocompatibility testing, and customer re-approval. Buyers should prioritize compliance transitions in their highest-margin, highest-regulation product lines first.
Feedstock volatility is persistent. Ethylene prices track crude oil with a lag, and Chinese overcapacity suppresses PVC resin prices even when feedstock costs rise. This creates a margin squeeze for non-integrated converters. Operators should consider index-linked contracts with collars to avoid being caught between rising feedstock and falling product prices.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, regulation-driven substitution market rather than a commodity supercycle. Volume growth of ~3.85% CAGR is real, but value growth will be lower as Chinese overcapacity exports deflation and additive regulations eliminate premium legacy grades. The strongest counter-argument is that a faster-than-expected Asian construction recovery — particularly if India's infrastructure pipeline accelerates — could tighten global PVC supply by 2029 and drive prices higher. We assign roughly 30% probability to that scenario.
Our analysis suggests the most significant strategic implication is regional divergence in compliance costs. European and North American producers face costly low-VOC and lead-free upgrades, while Chinese producers export compliant resin at lower cost. This will pressure Western producers to rationalize capacity or seek trade protections. Buyers should expect anti-dumping investigations in at least one major market by 2028.
Actionable strategy for operators and investors:
Qualify dual stabilizer systems now. Processors should run parallel production trials with calcium-based and organotin stabilizers to avoid single-supplier regulatory lock-in before 2028.
Lock flexible PVC volumes with phthalate-free declarations. Medical and packaging converters should secure 24-month supply agreements specifying DOTP plasticizer and DEHP-free certification to protect against 2030 deadline risk.
Track Chinese export pricing monthly. Procurement teams should monitor Chinese PVC export prices and anti-dumping filings as the leading indicator of regional supply tightness — a 10% rise in Chinese export prices typically precedes domestic price increases by one quarter.
What would change our conclusion: a sustained Chinese production cut of more than 10% capacity, or a US-EU anti-dumping action against Chinese PVC, would shift the market from deflationary to tight. Buyers should maintain flexible contract structures to respond to either scenario.
PVC Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
PVC Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.85% from 2020-2034
Segmentation
By Product Type
Rigid PVC
Flexible PVC
Low Smoke PVC
Chlorinated PVC
By Manufacturing Process
Suspension PVC
Emulsion PVC
Bulk Polymerization
By Stabilizer Type
Calcium-Based Stabilizers
Lead-Based Stabilizers
Organotin Stabilizers
Others
By Application
Pipes & Fittings
Profiles & Tubes
Film & Sheets
Wire & Cables
Bottles
Others
By End-User Industry
Building & Construction
Automotive
Electrical
Packaging
Healthcare
Footwear
By Geography
Asia-Pacific
China
India
Japan
South Korea
Taiwan
Southeast Asia
Australia
North America
United States
Canada
Mexico
Europe
Germany
UK
France
Italy
Russia
Spain
Rest of Europe
South America
Brazil
Argentina
Colombia
Peru
Chile
Middle East & Africa
Saudi Arabia
Table of Contents
1. PVC Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. PVC Market Executive Summary
2.1. Market Snapshot
3. PVC Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. PVC Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. PVC Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Rigid PVC
5.1.2. Flexible PVC
5.1.3. Low Smoke PVC
5.1.4. Chlorinated PVC
5.2. Analysis, Insights and Forecast - by Manufacturing Process
5.2.1. Suspension PVC
5.2.2. Emulsion PVC
5.2.3. Bulk Polymerization
5.3. Analysis, Insights and Forecast - by Stabilizer Type
5.3.1. Calcium-Based Stabilizers
5.3.2. Lead-Based Stabilizers
5.3.3. Organotin Stabilizers
5.3.4. Others
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Pipes & Fittings
5.4.2. Profiles & Tubes
5.4.3. Film & Sheets
5.4.4. Wire & Cables
5.4.5. Bottles
5.4.6. Others
5.5. Analysis, Insights and Forecast - by End-User Industry
5.5.1. Building & Construction
5.5.2. Automotive
5.5.3. Electrical
5.5.4. Packaging
5.5.5. Healthcare
5.5.6. Footwear
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia-Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. PVC Market Asia-Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Rigid PVC
6.1.2. Flexible PVC
6.1.3. Low Smoke PVC
6.1.4. Chlorinated PVC
6.2. Analysis, Insights and Forecast - by Manufacturing Process
6.2.1. Suspension PVC
6.2.2. Emulsion PVC
6.2.3. Bulk Polymerization
6.3. Analysis, Insights and Forecast - by Stabilizer Type
6.3.1. Calcium-Based Stabilizers
6.3.2. Lead-Based Stabilizers
6.3.3. Organotin Stabilizers
6.3.4. Others
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Pipes & Fittings
6.4.2. Profiles & Tubes
6.4.3. Film & Sheets
6.4.4. Wire & Cables
6.4.5. Bottles
6.4.6. Others
6.5. Analysis, Insights and Forecast - by End-User Industry
6.5.1. Building & Construction
6.5.2. Automotive
6.5.3. Electrical
6.5.4. Packaging
6.5.5. Healthcare
6.5.6. Footwear
7. PVC Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Rigid PVC
7.1.2. Flexible PVC
7.1.3. Low Smoke PVC
7.1.4. Chlorinated PVC
7.2. Analysis, Insights and Forecast - by Manufacturing Process
7.2.1. Suspension PVC
7.2.2. Emulsion PVC
7.2.3. Bulk Polymerization
7.3. Analysis, Insights and Forecast - by Stabilizer Type
7.3.1. Calcium-Based Stabilizers
7.3.2. Lead-Based Stabilizers
7.3.3. Organotin Stabilizers
7.3.4. Others
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Pipes & Fittings
7.4.2. Profiles & Tubes
7.4.3. Film & Sheets
7.4.4. Wire & Cables
7.4.5. Bottles
7.4.6. Others
7.5. Analysis, Insights and Forecast - by End-User Industry
7.5.1. Building & Construction
7.5.2. Automotive
7.5.3. Electrical
7.5.4. Packaging
7.5.5. Healthcare
7.5.6. Footwear
8. PVC Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Rigid PVC
8.1.2. Flexible PVC
8.1.3. Low Smoke PVC
8.1.4. Chlorinated PVC
8.2. Analysis, Insights and Forecast - by Manufacturing Process
8.2.1. Suspension PVC
8.2.2. Emulsion PVC
8.2.3. Bulk Polymerization
8.3. Analysis, Insights and Forecast - by Stabilizer Type
8.3.1. Calcium-Based Stabilizers
8.3.2. Lead-Based Stabilizers
8.3.3. Organotin Stabilizers
8.3.4. Others
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Pipes & Fittings
8.4.2. Profiles & Tubes
8.4.3. Film & Sheets
8.4.4. Wire & Cables
8.4.5. Bottles
8.4.6. Others
8.5. Analysis, Insights and Forecast - by End-User Industry
8.5.1. Building & Construction
8.5.2. Automotive
8.5.3. Electrical
8.5.4. Packaging
8.5.5. Healthcare
8.5.6. Footwear
9. PVC Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Rigid PVC
9.1.2. Flexible PVC
9.1.3. Low Smoke PVC
9.1.4. Chlorinated PVC
9.2. Analysis, Insights and Forecast - by Manufacturing Process
9.2.1. Suspension PVC
9.2.2. Emulsion PVC
9.2.3. Bulk Polymerization
9.3. Analysis, Insights and Forecast - by Stabilizer Type
9.3.1. Calcium-Based Stabilizers
9.3.2. Lead-Based Stabilizers
9.3.3. Organotin Stabilizers
9.3.4. Others
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Pipes & Fittings
9.4.2. Profiles & Tubes
9.4.3. Film & Sheets
9.4.4. Wire & Cables
9.4.5. Bottles
9.4.6. Others
9.5. Analysis, Insights and Forecast - by End-User Industry
9.5.1. Building & Construction
9.5.2. Automotive
9.5.3. Electrical
9.5.4. Packaging
9.5.5. Healthcare
9.5.6. Footwear
10. PVC Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Rigid PVC
10.1.2. Flexible PVC
10.1.3. Low Smoke PVC
10.1.4. Chlorinated PVC
10.2. Analysis, Insights and Forecast - by Manufacturing Process
10.2.1. Suspension PVC
10.2.2. Emulsion PVC
10.2.3. Bulk Polymerization
10.3. Analysis, Insights and Forecast - by Stabilizer Type
10.3.1. Calcium-Based Stabilizers
10.3.2. Lead-Based Stabilizers
10.3.3. Organotin Stabilizers
10.3.4. Others
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Pipes & Fittings
10.4.2. Profiles & Tubes
10.4.3. Film & Sheets
10.4.4. Wire & Cables
10.4.5. Bottles
10.4.6. Others
10.5. Analysis, Insights and Forecast - by End-User Industry
10.5.1. Building & Construction
10.5.2. Automotive
10.5.3. Electrical
10.5.4. Packaging
10.5.5. Healthcare
10.5.6. Footwear
11. PVC Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. PVC Market Research Methodology
List of Figures
Figure 1: PVC Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: PVC Market Volume Breakdown (Million tons, %) by Region 2026 & 2034
Figure 3: Asia-Pacific PVC Market Revenue (Million), by Product Type 2026 & 2034
Figure 4: Asia-Pacific PVC Market Volume (Million tons), by Product Type 2026 & 2034
Figure 5: Asia-Pacific PVC Market Revenue Share (%), by Product Type 2026 & 2034
Figure 6: Asia-Pacific PVC Market Volume Share (%), by Product Type 2026 & 2034
Figure 7: Asia-Pacific PVC Market Revenue (Million), by Manufacturing Process 2026 & 2034
Figure 8: Asia-Pacific PVC Market Volume (Million tons), by Manufacturing Process 2026 & 2034
Figure 9: Asia-Pacific PVC Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 10: Asia-Pacific PVC Market Volume Share (%), by Manufacturing Process 2026 & 2034
Figure 11: Asia-Pacific PVC Market Revenue (Million), by Stabilizer Type 2026 & 2034
Figure 12: Asia-Pacific PVC Market Volume (Million tons), by Stabilizer Type 2026 & 2034
Figure 13: Asia-Pacific PVC Market Revenue Share (%), by Stabilizer Type 2026 & 2034
Figure 14: Asia-Pacific PVC Market Volume Share (%), by Stabilizer Type 2026 & 2034
Table 1: PVC Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 2: PVC Market Volume Million tons Forecast, by Product Type 2020 & 2034
Table 3: PVC Market Revenue Million Forecast, by Manufacturing Process 2020 & 2034
Table 4: PVC Market Volume Million tons Forecast, by Manufacturing Process 2020 & 2034
Table 5: PVC Market Revenue Million Forecast, by Stabilizer Type 2020 & 2034
Table 6: PVC Market Volume Million tons Forecast, by Stabilizer Type 2020 & 2034
Table 7: PVC Market Revenue Million Forecast, by Application 2020 & 2034
Table 8: PVC Market Volume Million tons Forecast, by Application 2020 & 2034
Table 9: PVC Market Revenue Million Forecast, by End-User Industry 2020 & 2034
Table 10: PVC Market Volume Million tons Forecast, by End-User Industry 2020 & 2034
Table 11: PVC Market Revenue Million Forecast, by Region 2020 & 2034
Table 12: PVC Market Volume Million tons Forecast, by Region 2020 & 2034
Table 13: Asia-Pacific PVC Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 14: Asia-Pacific PVC Market Volume Million tons Forecast, by Product Type 2020 & 2034
Table 15: Asia-Pacific PVC Market Revenue Million Forecast, by Manufacturing Process 2020 & 2034
Table 16: Asia-Pacific PVC Market Volume Million tons Forecast, by Manufacturing Process 2020 & 2034
Table 17: Asia-Pacific PVC Market Revenue Million Forecast, by Stabilizer Type 2020 & 2034
Frequently Asked Questions
1. What is the PVC market size in 2026?
The global PVC market is estimated at 55.89 million tons in 2026, growing to 67.51 million tons by 2031 at a 3.85% CAGR. Asia-Pacific accounts for roughly 59% of consumption.
2. Is PVC market growth slowing?
Yes, modestly. The 3.85% CAGR is below pre-2020 growth rates, reflecting construction maturity in China and regulatory pressure on legacy additives. Infrastructure demand in India and Southeast Asia partially offsets the slowdown.
3. Which PVC segment is fastest-growing?
Chlorinated PVC (CPVC) is the fastest-growing product type at 4.55% CAGR, driven by hot-water plumbing and industrial piping. Organotin stabilizers are the fastest-growing stabilizer category at 5.05% CAGR.
4. What is the biggest risk for PVC buyers?
Regulatory risk from additive bans, particularly lead-based stabilizers and DEHP plasticizers. Re-qualification costs and supply constraints can exceed price savings from sourcing cheaper non-compliant grades.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis is built on a 70/30 primary-to-secondary research split. Between January and August 2026, we conducted 42 in-depth interviews across the PVC value chain: ethylene and chlorine suppliers, PVC resin producers, compound formulators and specialty additive suppliers, pipe and profile converters, and global distributors. Interviewees included VP-level sourcing executives, heads of R&D and formulation, technical directors, regulatory affairs managers, and commercial operations leads. These interviews validated capacity utilization, additive transition timelines, and regional pricing expectations.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Directors
35%
Heads of R&D & Technical Directors
30%
Regulatory Affairs & Compliance Managers
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
PVC Resin Producers
45%
Compound Formulators & Additive Suppliers
30%
Pipe, Profile & Film Converters
15%
Global Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K and annual investor presentations from major producers), patent databases tracking stabilizer and plasticizer innovation, and technical standards published by ASTM, ISO, and national standards bodies. These sources provided volume and price validation, particularly for Chinese export flows and EU compliance timelines.
Demand Modeling & Market Sizing Triangulation
Our sizing methodology simultaneously applies top-down and bottom-up models. The top-down model allocates global PVC volume across end-use sectors using construction capex, healthcare device production, and automotive build data. The bottom-up model aggregates producer-level capacity, utilization rates, and regional pricing to derive volume and value. We reconcile the two models quarterly and adjust for trade-flow asymmetries.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Volume in metric tons for 2025
Bottom-up capacity and production triangulation
High
Forecast Horizon
2026–2031 compound projection
Historical CAGR, regression analysis and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and commercial filings
High
Sources Referenced
UN Comtrade Database — global PVC resin trade flows
Eurostat — European PVC production and consumption statistics
American Chemistry Council — North American vinyl industry capacity data
ASTM International — PVC pipe and compound testing standards


 PVC Market