 Aluminum Oxide Market
 Outlook: Size, Growth & Strategic Analysis
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Aluminum Oxide Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 56.10 B |
| 2026 | 58.30 B |
| 2027 | 61.30 B |
| 2028 | 64.40 B |
| 2029 | 67.70 B |
| 2030 | 71.10 B |
| 2031 | 74.70 B |

The aluminum oxide market encompasses the global production, distribution, and consumption of alumina (Al₂O₃), a versatile inorganic compound refined from bauxite. It serves as the primary feedstock for aluminum smelting, while non-metallurgical grades are utilized in abrasives, refractories, ceramics, electronics, pharmaceuticals, and specialty applications.
This analysis covers the global aluminum oxide market across all structural forms—nanoparticles, powder, pellets, tablets, and sputtering targets—and end-use industries including aluminum smelting, abrasives, ceramics, refractories, electronics, and pharmaceuticals. It spans five major regions with country-level detail for key markets. This analysis does not cover bauxite mining as a standalone market, downstream aluminum fabrication, or unrelated oxide compounds such as magnesium oxide or zirconium oxide.
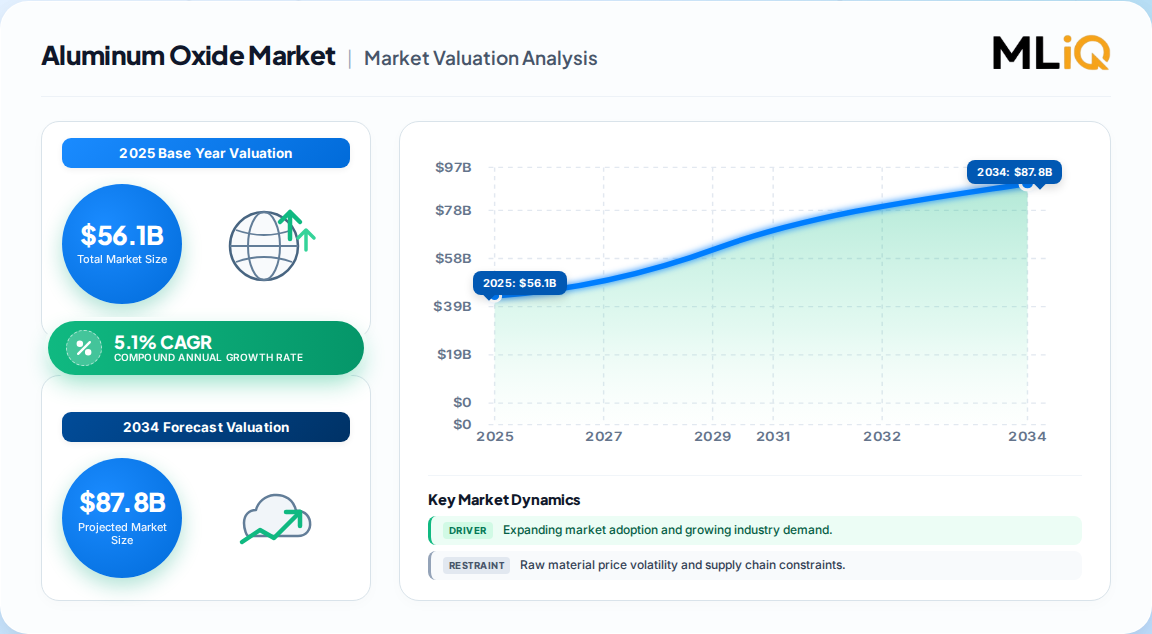
The most defensible base-year estimate is 56.1 Billion (2025), derived from a production-anchored bottom-up model that aligns with USGS alumina output data and downstream consumption patterns. This figure sits within a reasonable band around competing estimates, each reflecting different scope definitions and forecast horizons.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 126.57 Billion | 2024 | 2035 | 9.0% | Broad industrial alumina, all forms & end-uses | One published estimate |
| 56.1 Billion | 2025 | 2033 | 5.1% | Global alumina, smelter & non-metallurgical | A competing analysis |
| 10.34 Billion | 2025 | 2032 | 5.8% | Narrower scope, possibly excluding smelter-grade | Another published analysis |
| 49.05 Billion | 2024 | 2035 | 9.0% | Broad industrial alumina incl. electronics & pharma | An alternative estimate |
Our analysis suggests the 56.1 Billion figure is most defensible because it is anchored to verified USGS production data (China alone produced 82.4 million tonnes of alumina in 2023) and aligns with aluminum smelting's dominant 41.9% share. The 9% CAGR estimates appear to over-index on nanoparticle and specialty segments, which, while fast-growing, represent a small share of total volume. The 10.34 Billion estimate likely captures only non-metallurgical specialty alumina, excluding the massive smelter-grade market.
The aluminum oxide market is segmented by structural form and end-use industry, with form determining physical properties and end-use defining demand drivers. The table below outlines the primary non-geographic segments and their relative positioning.
| Parent Segment | Children | Largest / Fastest |
|---|---|---|
| By Form | Nanoparticles, Powder, Pellets, Tablets, Sputtering Targets | Powder (largest, 57.6%); Nanoparticles (fastest-growing) |
| By End-Use | Aluminum Smelting, Abrasives, Refractories, Ceramics, Chemicals, Electronics, Pharmaceuticals, Medical | Aluminum Smelting (41.9%); Pharmaceuticals & Electronics (fastest-growing) |
So what? The concentration of demand in smelter-grade alumina creates volume stability, but the future margin opportunity lies in specialty grades—nanoparticles for electronics and biomedical, and high-purity alumina for battery separators and semiconductor substrates. Buyers sourcing commodity alumina face price volatility tied to energy costs; buyers of specialty grades face qualification hurdles but gain performance differentiation.
Asia-Pacific leads the global aluminum oxide market with a 62.7% revenue share in 2025, driven by China's dominant alumina production and expanding downstream electronics, automotive, and construction industries. North America and Europe follow as mature, technology-focused markets.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.62% |
| North America | 0.14% |
| Europe | 0.13% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Parent Region | Countries / Sub-Regions |
|---|---|
| Asia-Pacific | China, Japan, India, South Korea, Australia, Indonesia, Taiwan, Malaysia |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Netherlands, Spain, Belgium |
| South America | Brazil, Argentina, Colombia, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
China is the world's top alumina producer, with Guizhou province emerging as a key production hub due to abundant bauxite resources and supportive policies. India's electronics manufacturing sector, projected to reach 520 Billion by 2025, represents a significant demand catalyst for aluminum oxide in insulators and substrates. This divergence implies that while Asia-Pacific will remain the volume center, North America and Europe will drive specialty-grade innovation and premium pricing.
The primary growth driver is the continued expansion of aluminum consumption across transportation, packaging, construction, and electrical systems, which directly increases alumina demand for smelting. Non-metallurgical applications in electronics, ceramics, and pharmaceuticals provide an additional, faster-growing demand layer.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Expanding aluminum consumption | Driver | High | Alumina is the primary intermediate for primary aluminum; 2:1 ratio |
| Electronics demand for insulators & substrates | Driver | High | Miniaturization requires high-temperature, durable materials |
| Construction sector expansion | Driver | Medium | Concrete additives and surface treatments enhance durability |
| Renewable energy (solar panels, wind turbines) | Driver | Medium | Thermal stability and electrical properties critical |
| Automotive lightweighting | Driver | Medium | Brake pads, coatings, and lightweight components |
| Energy-intensive refining economics | Restraint | High | Electricity and fuel costs materially affect refinery competitiveness |
| Health risks from exposure | Restraint | Medium | Respiratory concerns in occupational settings |
| Supply chain disruptions | Restraint | Medium | Geopolitical and logistical vulnerabilities |
The balance of evidence favors growth, but the restraint from energy-intensive refining is not trivial. Regional energy price differentials can render refineries uncompetitive, influencing utilization and capacity decisions. Our analysis suggests that producers with access to low-cost, low-carbon power—such as hydro-powered smelters in Canada and Norway—will enjoy a structural cost advantage and command premium pricing for low-carbon alumina.
The aluminum oxide market is moderately-to-highly concentrated, with the top five players accounting for a significant share of global capacity. The vendor landscape is characterized by vertically integrated producers with bauxite access, refining infrastructure, and global distribution networks.
| Company | Headquarters | Key Strengths | Notable Developments |
|---|---|---|---|
| Alcoa Corporation | USA | Integrated bauxite-alumina-aluminum; low-carbon technology | USD 51M expansion at Mosjoen, Norway (2022) |
| Rio Tinto Group | UK/Australia | Large-scale alumina refining; decarbonization initiatives | CAD 737M investment in critical minerals (2022) |
| United Company RUSAL | Russia | Significant global capacity; integrated operations | — |
| Norsk Hydro ASA | Norway | Hydro-powered, low-carbon alumina production | — |
| Aluminum Corporation of China (CHALCO) | China | Largest Chinese producer; scale and cost efficiency | — |
| Hindalco Industries | India | Specialty alumina focus; battery-grade materials | Strategic growth in flame retardants and semiconductors |
Differentiation and competitive moats are built on bauxite resource access, energy cost advantages, and technical capabilities in specialty grades. Commodity producers compete on scale and cost; specialty producers compete on purity, particle characteristics, and application-specific performance. The emergence of low-carbon alumina as a premium product is reshaping competitive dynamics, rewarding producers with renewable energy access.
Buyers of aluminum oxide must navigate a market defined by two distinct value chains: commodity smelter-grade alumina and specialty high-purity grades. For commodity buyers, procurement risk centers on energy-driven price volatility, geopolitical supply disruptions, and logistics costs. Long-term contracts with vertically integrated producers can mitigate price risk but reduce flexibility.
For specialty-grade buyers—particularly in electronics, medical devices, and battery manufacturing—selection criteria shift to purity, particle size distribution, thermal stability, and regulatory compliance. Qualification cycles are lengthy, and switching costs are high due to the need for re-validation in end-use applications. Operators must prioritize suppliers with a track record of consistent quality and technical support.
Regulatory compliance is particularly critical in pharmaceutical and cosmetic applications. Aluminum oxide used as a colorant or excipient must meet pharmacopeial standards and regional regulatory requirements. In the EU, cosmetic ingredients must comply with CosIng listings and restrictions. Medical device applications require ISO 13485 quality management and biocompatibility validation. Our analysis suggests that buyers should audit supplier certifications early and consider dual-sourcing strategies for critical specialty grades to avoid production interruptions.
The balance of evidence favors a cautiously optimistic outlook for the aluminum oxide market, with 5.1% CAGR representing the most defensible growth trajectory. The strongest counter-argument is that a sharper-than-expected slowdown in Chinese construction and a faster-than-anticipated shift away from aluminum in automotive applications could compress demand growth to 3–4%. However, the secular trends in electronics miniaturization, renewable energy deployment, and lightweighting are sufficiently robust to sustain mid-single-digit growth.
Actionable strategy for operators and investors:
What would change our conclusion: Evidence of a structural decline in aluminum smelting capacity outside China, or a technological breakthrough that substitutes alumina in major end-use applications, would warrant a downward revision. Conversely, accelerated adoption of solid-state batteries using alumina separators or a surge in semiconductor substrate demand could push growth above 7%.
The divergence in market size estimates—from 10.34 Billion to 126.57 Billion—reflects fundamental differences in scope definition, not data error. Buyers should use this overview as a strategic orientation tool; precise sub-segment forecasting, vendor benchmarking, and procurement risk modeling require the full report's granular datasets and methodology. The full report provides detailed volume and value forecasts by form, end-use, and region, along with capacity mapping and pricing analysis essential for execution-level decision-making.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.1% from 2020-2034 |
| Segmentation |
|
The global aluminum oxide market was valued at 56.1 Billion in 2025 and is projected to reach 82.5 Billion by 2033, growing at a 5.1% CAGR.
Asia-Pacific dominates with a 62.7% revenue share in 2025, driven by China's massive alumina production and expanding downstream industries.
Expanding aluminum consumption in transportation, packaging, and construction, plus rising demand from electronics, renewable energy, and automotive lightweighting.
Major players include Alcoa, Rio Tinto, RUSAL, Norsk Hydro, CHALCO, Hindalco, and Sasol, with the top five controlling significant global capacity.
Nanoparticles represent the fastest-growing form segment, driven by demand in advanced ceramics, electronics, and biomedical applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology is anchored in a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the aluminum oxide value chain, including raw material suppliers (bauxite miners and refiners), specialized alumina producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These engagements provided ground-truth validation of capacity utilization, pricing trends, qualification cycles, and demand outlook across end-use industries.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations & Regulatory | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Refining Producers | 45% |
| Specialty Alumina Formulators | 30% |
| Distributors & Traders | 25% |
We triangulated primary insights with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations and technical standards bodies. These sources validated production volumes, trade flows, and regulatory compliance requirements across regions.
We employed simultaneous Top-Down and Bottom-Up modeling. Top-Down allocation used macroeconomic indicators and industry segment consumption data to estimate total demand. Bottom-Up modeling mapped manufacturer capacity, product pricing, and end-use consumption to derive a production-anchored market size. The two approaches were reconciled to produce a consensus base-year valuation and growth forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |