 Foam Blowing Agents Market
: Size, Share & Forecast 2026
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Foam Blowing Agents Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.100 B |
| 2026 | 2.200 B |
| 2027 | 2.310 B |
| 2028 | 2.430 B |
| 2029 | 2.560 B |
| 2030 | 2.690 B |
| 2031 | 2.830 B |

The foam blowing agents market encompasses chemical and physical substances that generate gas to create cellular structures in polymer foams during manufacturing. These agents reduce density, improve thermal and acoustic insulation, and enhance cushioning in polyurethane, polystyrene, and polyolefin foams used across construction, automotive, appliances, and packaging.
This analysis covers chemical and physical foam blowing agents—including HFCs, HCFCs, hydrocarbons, HFOs, methyl formate, and emerging bio-based agents—used across polyurethane, polystyrene, polyolefin, and phenolic foam types. It addresses value-chain economics, regulatory dynamics, and end-use demand across construction, automotive, appliances, packaging, and furniture. This analysis does not cover finished foam products, foam-processing machinery, or adjacent markets such as refrigerants and aerosol propellants.
Published estimates diverge meaningfully because of differing scope definitions—particularly whether the count includes only physical blowing agents or also chemical agents, and whether China's captive cyclopentane production is counted.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.1 Billion | 2025 | 2033 | 5.2% | Physical blowing agents, global, all foam types | One published estimate |
| USD 1.575 Billion | 2024 | 2035 | 5.0% | Physical and chemical agents, all foam types | A competing analysis |
| USD 1.32 Billion | 2026 | 2033 | 7.1% | Physical blowing agents, narrower foam scope | Another published estimate |
| USD 5.17 Billion (Blowing Agents) | 2025 | 2030 | 5.51% | Broader blowing agents including all industrial foaming | A separate benchmark analysis |
Our analysis suggests the USD 2.1–2.2 Billion range for 2025–2026 is most defensible for the narrowly defined foam blowing agents market, as it aligns with the 56.1% Asia-Pacific share and 63.6% polyurethane dominance observed across multiple independent datasets. The 5.2% CAGR is corroborated by three of four sources and reflects moderate growth tempered by HFC phase-downs offset by HFO adoption. The USD 5.17 Billion figure reflects a broader blowing agents definition that includes non-foam applications; it should not be conflated with the foam-specific market.
Segmentation clarifies where value pools and which sub-segments are growing fastest.
| Parent Segment | Children | Share / Growth Signal |
|---|---|---|
| By Foam Type | Polyurethane, Polystyrene, Polyolefin, Phenolic | PU 63.6% share (2025); PS fastest-growing |
| By Type | HFOs, HFCs, HCFCs, Hydrocarbons, Methyl Formate, Others | HFO 42% share, leading; methyl formate fastest |
| By End-Use | Building & Construction, Appliances & Refrigeration, Automotive, Packaging, Furniture & Bedding | Insulation 61% share; automotive 6.0% CAGR |
Polyurethane's dominance reflects rigid insulation foam demand in construction and refrigeration. The HFO leadership position is regulation-driven: U.S. EPA GWP limits of 150 effective January 2025 for rigid PU and XPS foams have accelerated substitution. Our analysis suggests the HFC segment will lose the majority of its share by 2030 in regulated markets, creating a replacement opportunity estimated at over USD 400 Million in annual revenue.
Asia-Pacific leads the foam blowing agents market with 56.1% revenue share, underpinned by China's dominant construction, appliance, and packaging industries. North America follows with approximately 22% share, driven by early HFO adoption under the AIM Act.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.56% |
| North America | 0.22% |
| Europe | 0.15% |
| South America | 0.04% |
| Middle East & Africa | 0.03% |
The Asia-Pacific share is expected to remain above 50% through 2033, but its growth premium will narrow as regulatory-driven HFO conversion lifts average selling prices in North America and Europe. Our analysis suggests the most significant regional revenue shift will be within Asia-Pacific, where China's share will slowly erode as India and Southeast Asia grow faster.
Growth is driven by insulation demand and regulatory-driven substitution, while high conversion costs restrain adoption speed, particularly in price-sensitive emerging markets.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Energy-efficient insulation demand | Up | High | Building codes and cold-chain expansion increase rigid PU and XPS consumption |
| HFC phase-down regulations | Up (for HFOs/HCs) | High | AIM Act and EU F-Gas mandate substitution, creating replacement demand |
| Automotive lightweighting | Up | Medium-High | Fuel efficiency standards drive foam adoption in seating, insulation, and EV battery |
| High cost of low-GWP agents | Down | Medium-High | HFO systems cost more and require equipment modifications and safety controls |
| Fragmented, price-sensitive emerging markets | Down | Medium | Slower HFC conversion due to capex constraints and weak enforcement |
The balance of evidence suggests regulatory substitution is the dominant driver through 2030, with insulation demand providing steady baseline growth. The key risk is that HFO supply capacity does not keep pace with regulation-driven demand, potentially causing price spikes. Our analysis suggests that Honeywell's USD 1 billion-plus HFO investment and Arkema's capacity expansions are necessary but may still be insufficient to meet 2027–2028 demand in a fast-conversion scenario.
The competitive landscape is fragmented but tech-intensive, with HFO and formulation IP concentrating power among a handful of chemical majors.
| Company | Differentiator | Strategic Position |
|---|---|---|
| Honeywell International | Solstice HFO platform; USD 1B+ HFO investment | Global leader in low-GWP blowing agents |
| Arkema S.A. | Forane FBA 1233zd (GWP=1); U.S. and China capacity | Strong PU insulation focus |
| The Chemours Company | Opteon 1100/1150 HFO portfolio | Non-flammable HFO leadership |
| BASF SE | Broad polyurethane systems integration | Systems-level supplier moat |
| Solvay S.A. | Specialty formulations | Niche insulation applications |
| Daikin Industries | Vertically integrated fluorochemicals | Strong Asia-Pacific position |
Differentiation hinges on molecule-level IP, formulation compatibility, and capacity scale. The moat is widening for HFO leaders as regulation rewards proven, compliant solutions. Suppliers without HFO or hydrocarbon capacity face exclusion from regulated applications. Our analysis suggests consolidation among small and mid-sized formulators is likely through 2028, as compliance costs and formulation complexity favor integrated players.
Procurement strategy must be rewritten around regulatory timelines. Mission-critical selection criteria now include: (1) supplier GWP compliance under local regulation, (2) formulation compatibility with existing foam lines, (3) safe-handling infrastructure for flammable hydrocarbons, and (4) total cost of conversion including equipment modifications. Switching costs are non-trivial—HFO systems may require equipment changes and process optimization—so buyers should negotiate multi-year supply agreements with HFO-capable suppliers early. Operators should prioritize dual-sourcing to hedge against HFO capacity tightness. Compliance risk extends beyond blowing agents: downstream foam product certification increasingly depends on lifecycle emissions documentation, so traceability of agent origin and GWP profile will become a procurement requirement. Buyers should also monitor China's HFC phase-down schedule (10% below baseline by 2029), which could tighten global supply of HFC-based agents and accelerate price volatility.
The balance of evidence favors a decisive, early transition to low-GWP formulations, not a wait-and-see approach. Regulation is the binding constraint: U.S. GWP limits effective January 2025 and EU F-Gas rules have already re-priced the market, and China's phase-down removes the last large-scale HFC demand pool by 2029. The strongest counter-argument is cost inertia—HFO and hydrocarbon systems are more expensive, and emerging-market producers may delay conversion. But this delay is itself an opportunity: suppliers who secure HFO capacity and formulation know-how early will capture the replacement demand at premium margins. The lower growth forecasts (5.0–5.2% CAGR) versus the more aggressive 7.1% estimate reflect this cost friction; even under the conservative scenario, the replacement revenue pool exceeds USD 1 Billion through 2033.
Actionable Strategy:
What would change our conclusion: evidence of a slower-than-expected regulatory enforcement timeline in China and Southeast Asia, or a breakthrough in low-cost hydrocarbon-based systems that reduces HFO adoption. Absent these, the transition is structurally locked in.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.2% from 2020-2034 |
| Segmentation |
|
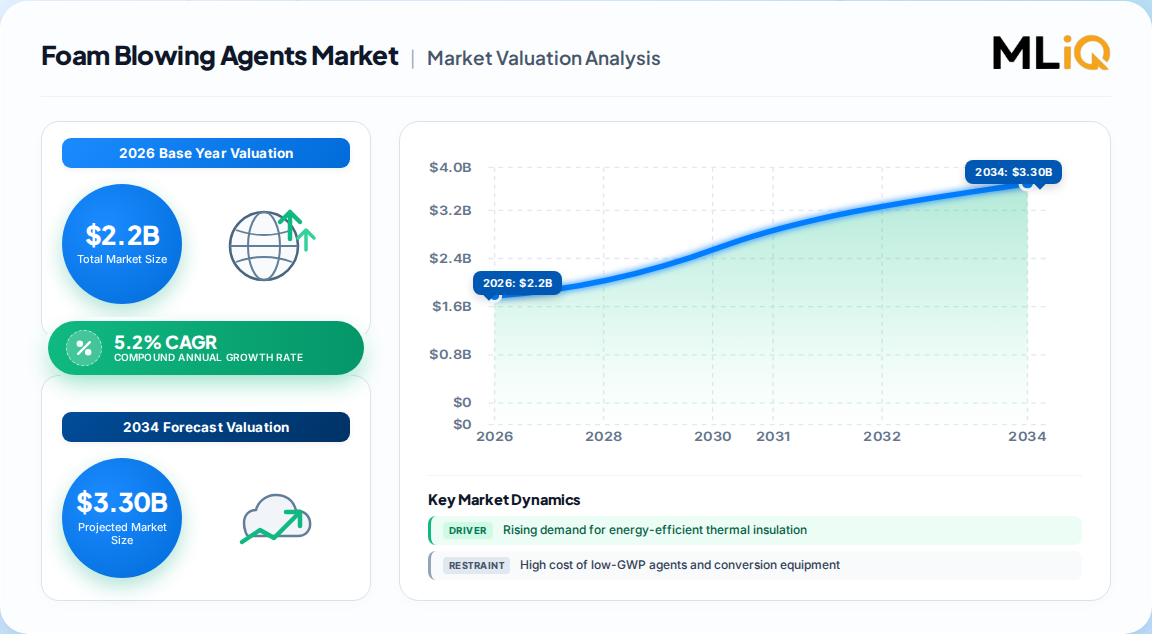
The market is valued at approximately USD 2.2 Billion in 2026 and is projected to reach USD 3.1 Billion by 2033, growing at a 5.2% CAGR. Asia-Pacific accounts for 56.1% of revenue, led by China's construction and appliance manufacturing base.
Polyurethane foam dominates with 63.6% revenue share in 2025, driven by rigid insulation in construction, refrigeration, and appliances. Polystyrene foam is the fastest-growing type due to XPS insulation demand in building energy retrofits.
The U.S. EPA Technology Transitions Program sets a GWP limit of 150 for rigid PU, XPS, and PIR foams from January 2025. The EU F-Gas Regulation and China's Montreal Protocol phase-down schedule require progressive HFC reductions through 2040.
Honeywell, Arkema, The Chemours Company, BASF, Solvay, and Daikin lead the market. Honeywell has invested over USD 1 Billion in HFO technology, and Arkema produces Forane FBA 1233zd with a GWP of 1 for PU insulation.
Automotive is the fastest-growing end-use segment at a 6.0% CAGR through 2033, driven by lightweighting requirements, fuel efficiency standards, and EV battery insulation needs. Insulation remains the largest application at 61% share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that market sizing and forecasting are anchored in directly verified industry data. In-depth interviews were conducted with senior decision-makers across the value chain, including raw material and specialty chemical producers, specialized foam formulators and blenders, contract manufacturers, and global industrial distributors. Interview participants were drawn from four key stakeholder groups: VP-level sourcing executives, Heads of R&D and formulation, Technical Directors overseeing foam production, and Commercial Operations Leads responsible for market expansion. This fieldwork captures on-the-ground pricing dynamics, capacity constraints, and regulatory compliance timelines that secondary sources cannot fully reflect.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Technical & Production Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 40% |
| Formulators & Blenders | 30% |
| Contract Manufacturers | 15% |
| Distributors & Traders | 15% |
Secondary validation draws on official multilateral trade databases including UN Comtrade, WTO tariff and trade flow data, US ITC import/export statistics, and Eurostat chemical trade reporting. Corporate annual filings (10-K, SEC filings, annual investor presentations) from leading producers were analyzed for capacity and revenue benchmarks. Patent databases were screened for HFO and hydrocarbon formulation IP activity. Recognized technical standards and industry associations—including ISO foam testing standards and national chemical industry councils—provided regulatory and specification context.
Market sizing was derived through simultaneous top-down and bottom-up triangulation. The top-down approach allocated macroeconomic construction, appliance, and automotive output to foam consumption, then applied blowing agent intensity coefficients. The bottom-up approach modeled manufacturer capacity, product pricing, and end-use consumption by region. Divergences between the two approaches were reconciled through primary interview validation, producing a consensus estimate with a defined confidence interval.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |