 Calcium Propionate Market
 Outlook 2026: Size, Share & CAGR
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Calcium Propionate Market

Khageshwar Rongkali
Senior Analyst

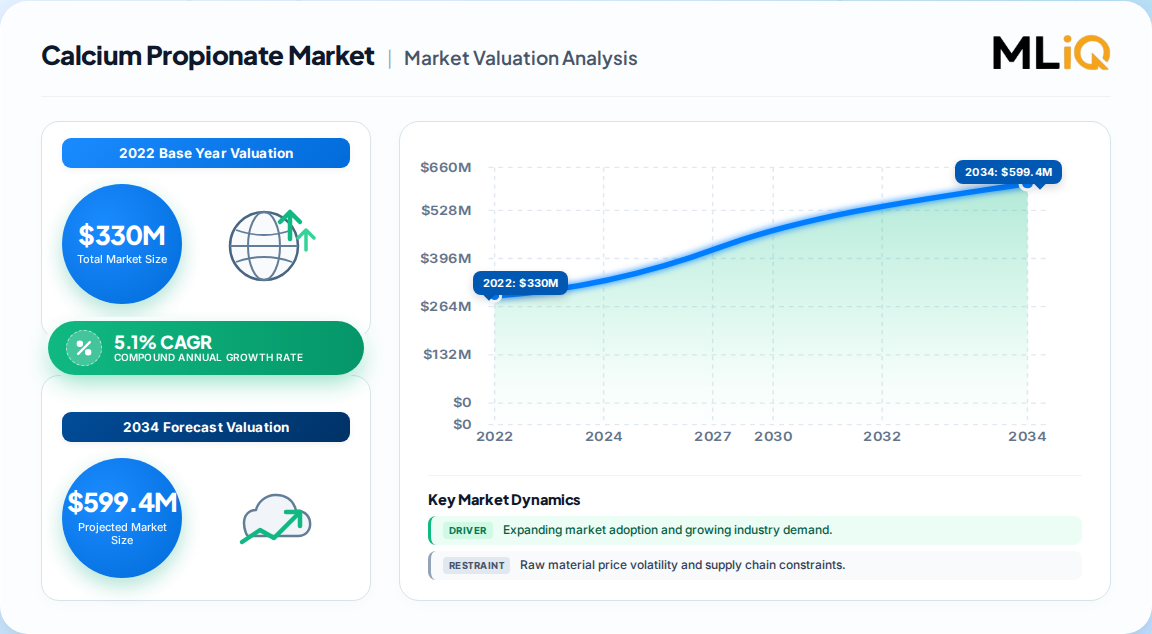
| Year | Market Size |
|---|---|
| 2022 | 330.0 M |
| 2023 | 347.0 M |
| 2024 | 365.0 M |
| 2025 | 383.0 M |
| 2026 | 403.0 M |
| 2027 | 423.0 M |
| 2028 | 445.0 M |

The calcium propionate market encompasses the global production, distribution, and consumption of the calcium salt of propionic acid (E282), used primarily as a mold inhibitor and shelf-life extender in bakery products, animal feed, and pharmaceutical excipients. The market serves food manufacturers, feed mills, and pharmaceutical formulators seeking cost-effective antimicrobial preservation.
This report covers the global calcium propionate market across all forms (dry powder, granular, liquid/suspension), grades (food, feed, pharmaceutical, industrial), and applications (food & beverage, animal feed, pharmaceutical, personal care). It analyzes demand across North America, Europe, Asia-Pacific, South America, and the Middle East & Africa.
This analysis does not cover adjacent preservative markets such as sodium benzoate, potassium sorbate, or natural fermentation-derived alternatives. It also excludes upstream propionic acid production economics and downstream bakery equipment markets.
Multiple published estimates place the 2022–2025 baseline between 323 Million and 410 Million, with forecast horizons converging on a 2031–2035 terminal value of 527–704 Million. The following table disaggregates these divergent estimates.
| Estimate Source | Base Year | Base Value | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|---|
| Estimate A | 2022 | 330 Million | 2032 | 5.1% | Global, all grades and forms | One published analysis |
| Estimate B | 2026 | 408 Million | 2031 | 5.23% | Global, value in USD | A competing analysis |
| Estimate C | 2025 | 410 Million | 2035 | 5.55% | Global, all applications | One published forecast |
| Estimate D | 2025 | 324 Million | 2034 | 5.69% | Global, all forms | A competing estimate |
Our analysis suggests the 330 Million (2022) baseline is the most defensible anchor because it aligns with the longest observable historical series and reflects a conservative definition excluding industrial-grade volumes. The higher 410 Million figure likely incorporates forward-year pricing premiums and expanded pharmaceutical-grade segmentation. Buyers should note that the 5.1–5.7% CAGR band is unusually tight for a commodity additive, implying consensus on volume-driven growth rather than pricing-led expansion. This convergence itself is a signal: the market is maturing, and differentiation will come from form-factor innovation and regional supply chain positioning, not from riding a high-growth wave.
The calcium propionate market is segmented by form, grade, and application, with dry powder dominating volume and food-grade capturing the majority of revenue.
| Parent Segment | Children | Key Insight |
|---|---|---|
| By Form | Dry (Powder, Granular), Liquid/Suspension | Dry holds 65% share; liquid growing fastest at 5.68% CAGR |
| By Grade | Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade | Food grade 71% share; pharma fastest at 6.24% CAGR |
| By Application | Food & Beverage (Bakery, Dairy, Processed Foods), Animal Feed, Pharmaceutical, Personal Care, Others | F&B leads at 62% share; feed growing at 5.89% CAGR |
The segmentation reveals a market in transition. The dry form's dominance reflects legacy batch-mixing infrastructure, but its share is eroding as high-throughput bakeries adopt automated liquid dosing. Similarly, food-grade's 71% revenue share masks the fact that pharmaceutical-grade growth at 6.24% CAGR will compress that share over time. For suppliers, this means capacity investments should be weighted toward liquid handling and high-purity crystallization, not incremental dry powder capacity.
North America leads the global calcium propionate market with 40.23% revenue share in 2025, driven by large-scale industrial bakery operations and long-standing FDA GRAS recognition.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.27% |
| Asia-Pacific | 0.28% |
| South America | 0.04% |
| Middle East & Africa | 0.03% |
| Region | 2025 Revenue Share | CAGR (2026–2031) |
|---|---|---|
| North America | 40.2% | 5.4% |
| Europe | 27.0% | 5.1% |
| Asia-Pacific | 28.5% | 6.0% |
| South America | 4.0% | 4.8% |
| Middle East & Africa | 3.0% | 4.5% |
The divergence between North America's share leadership and Asia-Pacific's growth leadership is the single most important regional dynamic. Our analysis suggests that North American incumbents face a maturing demand curve where volume growth barely outpaces GDP, while Asia-Pacific offers the only meaningful greenfield opportunity for capacity expansion. The GCC presents a niche but price-inelastic pocket due to extreme ambient temperatures and import dependence. Europe sits in the middle—regulatory stability supports baseline demand, but clean-label pressure is most acute there, creating a two-tier market where conventional and premium natural-preservative lines coexist.
Industrial packaged bakery expansion (+1.4% CAGR impact) and mycotoxin control in feed (+1.1%) are the strongest growth drivers, while clean-label reformulation pressure (-1.2%) is the most significant restraint.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Industrial packaged bakery expansion | Driver | High | New high-speed lines in Asia dose 0.1–0.4% of flour weight, translating capacity additions into contract volume |
| Mycotoxin and spoilage control in feed | Driver | High | 60–80% of global crops carry detectable mycotoxins; propionate suppresses mold during storage and pelleting |
| EU aquaculture approval renewal | Driver | Medium | EFSA renewal through 2034 reassures feed-mill investors in Norway, Scotland, Spain |
| Bio-based propionic acid routes | Driver | Medium | 35–40% carbon-intensity reduction versus petrochemical routes; 5–10% premium acceptance among multinationals |
| Clean-label reformulation pressure | Restraint | High | Consumers prefer minimal synthetic preservatives; premium segments trial fermented replacements |
| Feedstock price volatility | Restraint | Medium | Propylene and propionic acid price swings squeeze margins, acutely in Asia-Pacific and Europe |
| Substitution by cultured ingredients | Restraint | Low | Boutique bakeries trial natural alternatives, but cost and efficacy gaps limit mainstream adoption |
The balance of evidence favors sustained growth, but the composition of that growth is shifting. Our analysis suggests the clean-label restraint is not a volume killer but a price suppressor—it caps pricing power in premium Western markets while simultaneously creating a quality-differentiation opportunity for micro-encapsulated and bio-based variants. The feedstock volatility restraint disproportionately impacts smaller producers without backward integration, accelerating consolidation. The second-order effect is that the market will likely see fewer, larger suppliers with integrated propionic acid capacity, which in turn gives those suppliers greater leverage in contract negotiations with bakery chains.
The calcium propionate market is moderately concentrated, with Perstorp, Macco Organiques, ADDCON, Kerry Group, Kemin Industries, and Impextraco NV among the most frequently cited suppliers.
| Company | HQ / Key Facilities | Product Focus | Differentiation |
|---|---|---|---|
| Perstorp | Sweden; Castellanza expansion | Feed-grade, liquid suspensions | Integrated propionic acid capacity; aquafeed positioning |
| Macco Organiques | Czech Republic | Food-grade, pharmaceutical-grade | High-purity crystallization; European regulatory depth |
| ADDCON | Germany | Feed-grade preservatives | Feed-mill technical service network |
| Kerry Group | Ireland | Bakery blends (ProBake range) | Application formulation; high-heat stability variants |
| Kemin Industries | USA | Feed and food preservatives | Global distribution; mycotoxin binder portfolio |
| Impextraco NV | Belgium | Feed-grade, liquid dosing | Precision-dosing equipment integration |
Differentiation in this market is increasingly less about the molecule itself and more about the delivery system. Our analysis suggests that suppliers with integrated propionic acid capacity (Perstorp, Macco) hold structural cost advantages that will widen as feedstock volatility persists. Kerry's ProBake range exemplifies the application-formulation moat—selling a blend rather than a commodity salt commands premium pricing and creates switching costs. The weakest competitive position belongs to pure distributors without formulation capabilities; they face margin compression from both upstream integrated players and downstream bakery chains seeking direct supply relationships.
Buyers of calcium propionate face a market where regulatory compliance is table stakes but supply reliability and form-factor compatibility increasingly determine total cost of ownership. The FDA's GRAS listing under 21 CFR 184.1221 and the EU cap of 3,000 mg/kg in prepacked sliced bread establish clear usage boundaries, but enforcement varies by region—China's GB 2760-2024 now permits up to 2.5 g/kg in bread and pastries, a higher threshold that reflects the country's warmer supply chains.
Procurement risk is concentrated in feedstock volatility. Propionic acid prices track propylene, and buyers without long-term supply agreements are exposed to quarterly price swings. Switching costs are moderate for dry powder—multiple qualified suppliers exist—but rise sharply for liquid/suspension systems where dosing equipment is calibrated to specific viscosity and concentration profiles. Operators transitioning to automated liquid dosing should negotiate equipment-compatible supply agreements that lock in formulation specifications, not just volume.
Regulatory compliance is not static. The EU renewed propionic acid and its salts as feed additives through 2034, providing a decade of clarity, but pharmaceutical-grade buyers must monitor pharmacopeial monograph updates. Personal care applications face stricter labeling requirements in the EU, where E282 must be declared on ingredient lists. Our analysis suggests that the highest-risk procurement decision is single-sourcing food-grade powder from a supplier without integrated propionic acid capacity—the cost savings are illusory once feedstock volatility passes through.
The balance of evidence favors a constructive but selectively bullish outlook. The 5.1–5.7% CAGR consensus is reliable, but it masks a bifurcation: commodity food-grade powder is a low-margin, volume-driven business, while pharmaceutical-grade and liquid/suspension formats offer pricing power and stickier customer relationships. The strongest counter-argument is that clean-label pressure could accelerate faster than expected in North America and Europe, compressing the food-grade segment more severely than the 5.1% headline suggests. We acknowledge this risk but note that food-waste reduction targets provide a countervailing force—retailers extending date codes by two to three days have a direct financial incentive to maintain preservative use regardless of consumer sentiment.
Our analysis suggests three actionable strategic priorities for operators and investors:
What would change our conclusion? A faster-than-anticipated regulatory restriction on synthetic preservatives in the EU or a breakthrough in cost-competitive natural mold inhibitors would compress the food-grade segment below 4% CAGR. Conversely, a China-led acceleration in packaged bakery adoption beyond current OECD-FAO projections could push the global CAGR above 6%. We recommend monitoring GB 2760 enforcement data and EU clean-label legislative pipelines as the two leading indicators.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.1% from 2020-2034 |
| Segmentation |
|
The global calcium propionate market was valued at approximately 330 Million in 2022, with 2025 estimates ranging from 324 Million to 410 Million depending on scope definitions. Most published analyses converge on a 5.1–5.7% CAGR through the early 2030s.
North America leads with 40.23% revenue share, driven by industrial bakery and processed cheese production. Asia-Pacific is the fastest-growing region at 5.98% CAGR, supported by China's GB 2760-2024 standard and expanding packaged bakery capacity.
Industrial packaged bakery expansion (+1.4% CAGR impact) and mycotoxin control in animal feed (+1.1%) are the strongest drivers. Food-waste reduction targets and EU aquaculture feed approvals provide additional tailwinds across regions.
Perstorp, Macco Organiques, ADDCON, Kerry Group, Kemin Industries, and Impextraco NV are among the leading suppliers. Competition centers on integrated propionic acid capacity, application-specific formulation, and regional distribution depth.
Clean-label reformulation pressure (-1.2% CAGR impact) and feedstock price volatility (-0.8%) are the primary restraints. Smaller producers without backward integration face margin compression, accelerating market consolidation among integrated suppliers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the calcium propionate value chain, including raw material and propionic acid suppliers, specialized preservative producers, contract formulators and blenders, and global industrial distributors. Decision-maker designations interviewed included VP-level sourcing executives, Heads of R&D and formulation, Technical Directors overseeing bakery and feed applications, and Commercial Operations Leads managing regional supply agreements. Structured questionnaires captured capacity, pricing, and procurement criteria data, supplemented by semi-structured interviews to validate segmentation assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Formulation Heads | 30% |
| Technical & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Propionic Acid Producers | 40% |
| Specialized Preservative Formulators | 35% |
| Industrial Distributors & Traders | 25% |
Secondary research draws on UN Comtrade and Eurostat trade flow databases, US ITC import-export records, WTO tariff schedules, and corporate annual filings including 10-K disclosures and investor presentations from publicly listed chemical and food ingredient companies. Patent databases were screened for micro-encapsulation and bio-based propionic acid process innovations. Regulatory frameworks referenced include FDA 21 CFR 184.1221, EU food additive regulations for E282, and China's GB 2760-2024 standard, alongside Codex Alimentarius General Standard for Food Additives.
Market sizing was triangulated through simultaneous top-down and bottom-up approaches. The top-down model allocated macroeconomic food and feed industry output to the propionate preservative segment using historical penetration rates. The bottom-up model aggregated manufacturer capacity disclosures, product pricing surveys, and end-use consumption estimates across bakery, feed, and pharmaceutical channels. Divergences between the two models were reconciled through primary interview validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |