Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Rheology Modifiers Market by Type (Waterborne, Solvent-borne), by Nature (Organic, Inorganic), by Application (Adhesives & Sealants, Cement & Concrete, Cleaners & Disinfectants, Coolants, Rubber Products, Lubricants & Greases, Fermentation, Others), by End-Use Industry (Paints & Coatings, Inks, Personal Care & Cosmetics, Adhesives & Sealants, Textiles, Home Care, Pharmaceuticals, Construction, Pulp & Paper, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 350
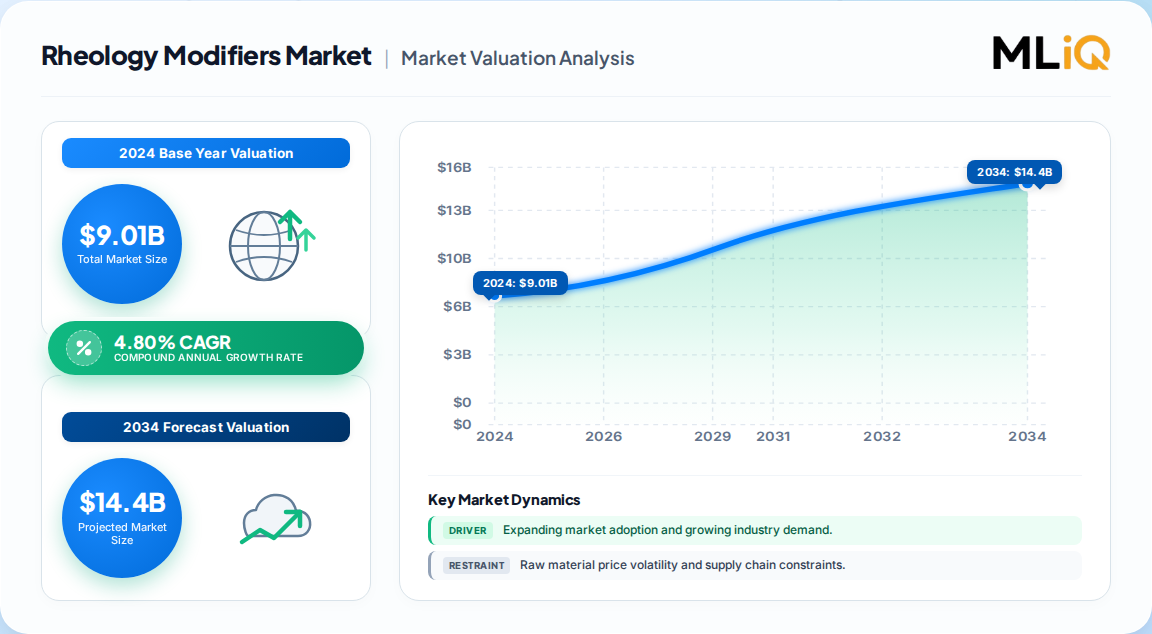
USD 9.01 Billion in 2024, the global Rheology Modifiers Market is forecast to reach USD 13.11 Billion by 2032, expanding at a 4.80% CAGR (2025–2032).
Asia-Pacific commands 35.3% of global value, driven by rapid industrialization in China, India, and Southeast Asia.
Organic modifiers dominate with 62.8% share, as formulators shift toward bio-based and associative thickeners.
Paints & coatings remain the largest end-use, contributing 35.7% of revenue in 2023.
Personal care & cosmetics is the fastest-growing end-use, propelled by premiumization and texture-led consumer demand.
Key vendors include BASF, Evonik, Dow, Clariant, Ashland, Arkema, and Elementis, operating in a fragmented market with sub-80% concentration.
Why this matters for decision-makers: Vendors must pivot toward waterborne, low-VOC rheology solutions to capture regulatory-driven demand and avoid margin compression from solvent-based legacy portfolios.
Rheology Modifiers Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.010 B
2024
9.440 B
2025
9.890 B
2026
10.37 B
2027
10.87 B
2028
11.39 B
2029
11.94 B
2030
Rheology Modifiers Market Size (In Billion)
Year
Market Size
2024
9.010 B
2025
9.440 B
2026
9.890 B
2027
10.37 B
2028
10.87 B
2029
11.39 B
2030
11.94 B
What is the Rheology Modifiers Market?
Rheology modifiers are specialty additives that control the viscosity, flow, and stability of liquid and semi-solid formulations. They are critical in paints, personal care, construction, adhesives, and oilfield fluids, enabling desirable application properties such as sag resistance, leveling, and pigment suspension without compromising shelf life.
Scope: what this report covers and excludes
This report covers the global Rheology Modifiers Market across organic and inorganic chemistries, waterborne and solvent-borne systems, and end-use industries including paints & coatings, personal care, adhesives, construction, and oil & gas. This analysis does not cover adjacent markets such as surfactants, dispersants, or defoamers except where they intersect with rheology control formulations.
How big is the market for Rheology Modifiers Market?
The global Rheology Modifiers Market was valued at USD 9.01 billion in 2024 and is projected to reach USD 13.11 billion by 2032, advancing at a 4.80% CAGR. Discrepancies in published estimates stem from differing base years, scope definitions, and currency normalization.
Our analysis suggests the USD 9.01 billion (2024) estimate is the most defensible because it incorporates a broader end-use scope and aligns with the post-pandemic recovery in construction and coatings demand. The 4.80% CAGR reflects balanced growth across mature and emerging regions, though upside exists if waterborne adoption accelerates faster than expected.
How is the market segmented?
The Rheology Modifiers Market is segmented by type, nature, functionality, form, distribution channel, application, and end-use industry. Organic modifiers hold the majority share, while waterborne systems are gaining traction due to environmental regulations.
Paints & Coatings, Inks, Personal Care & Cosmetics, Adhesives & Sealants, Textiles, Home Care, Pharmaceuticals, Construction, Pulp & Paper, Others
This segmentation highlights the breadth of application, with paints & coatings and personal care representing the highest-value segments. The synthetic associative thickener sub-segment is expected to outpace the broader organic category, reflecting formulator demand for precise viscosity control.
Which region leads in Rheology Modifiers Market?
Asia-Pacific leads the global Rheology Modifiers Market with a 35.3% share in 2024, driven by rapid industrialization, expanding construction activity, and rising paints & coatings consumption across China, India, and Southeast Asia. Europe follows as the second-largest and fastest-growing region, supported by stringent VOC regulations accelerating waterborne adoption.
Rheology Modifiers Market Regional Market Share
Loading chart...
Rheology Modifiers Market Regional Market Share
Region
Market Share (%)
North America
0.22%
Europe
0.24%
Asia-Pacific
0.4%
South America
0.08%
Middle East & Africa
0.06%
Region
Share (2024)
Asia-Pacific
35.3%
Europe
~24%
North America
~22%
South America
~8%
Middle East & Africa
~6%
Geography Tree:
Asia-Pacific
China
India
Japan
South Korea
Australia
Rest of Asia-Pacific
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
What is driving growth — and what is holding it back?
The primary growth driver is the shift toward waterborne and low-VOC coatings, which require advanced rheology modifiers for viscosity control, pigment suspension, and leveling. Expanding construction and infrastructure spending in emerging economies and premiumization in personal care are also significant demand catalysts.
Factor
Direction
Evidence Strength
Mechanism
Waterborne coatings adoption
Driver
High
Regulatory push for low-VOC formulations increases modifier demand
Construction & infrastructure growth
Driver
High
Paints, adhesives, and sealants consumption rises with building activity
Personal care premiumization
Driver
Medium
Texture and sensory claims drive use of associative thickeners
Shale gas & oilfield activity
Driver
Medium
Drilling fluids require rheology control for high-angle wells
Stringent environmental regulations
Restraint
High
Compliance costs and reformulation burdens limit certain chemistries
Raw material price volatility
Restraint
Medium
Margin pressure on formulators, especially smaller players
The balance of evidence favors robust growth, but regulatory and raw material risks are material. Our analysis suggests that vendors with bio-based and high-performance synthetic portfolios are best positioned to outgrow the market and mitigate compliance-driven headwinds.
Who are the leading vendors?
The market is fragmented, with key players collectively holding less than 80% share. BASF, Evonik, Dow, Clariant, Ashland, Arkema, Elementis, and Lubrizol are prominent, each leveraging distinct chemistries and application expertise.
Company
Headquarters
Product Focus
Differentiation
BASF SE
Germany
Broad organic & inorganic portfolio
Strong R&D and global distribution
Evonik Industries
Germany
Specialty additives for coatings & personal care
High-performance associative thickeners
Dow Inc.
USA
Cellulosics and synthetic rheology modifiers
Integration with coatings value chain
Clariant
Switzerland
Bio-based and natural modifiers
Sustainability-focused portfolio
Ashland
USA
Cellulosics and synthetic polymers
Strong personal care presence
Arkema
France
Specialty surfactants and thickeners
Technical service and formulation support
Elementis
UK
Organoclays and specialty additives
Leadership in inorganic rheology
Lubrizol
USA
Oilfield and industrial modifiers
Deep oil & gas application expertise
Competitive moats are built on formulation know-how, application-specific technical support, and regulatory compliance capabilities. Smaller players compete on price and regional service, but face rising compliance costs that favor scaled incumbents.
What do buyers and operators need to know?
Buyers must prioritize regulatory compliance, especially regarding VOC content and chemical safety, as non-compliant additives face market exclusion. Switching costs are moderate, driven by reformulation requirements and performance validation, so supplier selection should emphasize technical support and supply reliability. Procurement risks include raw material price volatility and logistics disruptions, particularly for cellulosic derivatives and specialty clays. Operators should evaluate total cost of ownership, including reformulation and testing expenses, rather than unit price alone. Sustainability credentials are increasingly a qualifying criterion, with bio-based and biodegradable modifiers commanding premium pricing but also reducing regulatory risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a positive outlook for the Rheology Modifiers Market, with a 4.80% CAGR representing a steady but not explosive trajectory. The strongest counter-argument is that regulatory constraints and raw material volatility could compress margins and slow adoption in price-sensitive emerging markets. However, the structural shift toward waterborne coatings and premium personal care is durable, and suppliers with compliant, high-performance portfolios should outperform.
Our analysis suggests that the market is bifurcating: commodity inorganic modifiers face price pressure, while specialty organic and associative thickeners enjoy pricing power. Vendors should accelerate investment in bio-based and low-VOC chemistries to capture regulatory-driven demand. Distributors and formulators must build technical service capabilities to support customers through reformulation cycles, as switching costs create stickiness but also require active support.
Actionable Strategy:
For investors: Target companies with a high proportion of waterborne-compatible and bio-based rheology modifiers, as these align with regulatory tailwinds and premium growth segments.
For operators: Diversify raw material sourcing and invest in application labs to reduce reformulation risk and capture customer share during compliance transitions.
For buyers: Engage early with suppliers that offer full regulatory documentation and technical support to minimize costly reformulation delays.
Evidence that would change our conclusion: a sharp decline in construction activity in Asia-Pacific, accelerated regulatory bans on key chemistries without viable substitutes, or a breakthrough in alternative viscosity-control technologies that reduces additive demand.
Rheology Modifiers Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Rheology Modifiers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.80% from 2020-2034
Segmentation
By Type
Waterborne
Solvent-borne
By Nature
Organic
Inorganic
By Application
Adhesives & Sealants
Cement & Concrete
Cleaners & Disinfectants
Coolants
Rubber Products
Lubricants & Greases
Fermentation
Others
By End-Use Industry
Paints & Coatings
Inks
Personal Care & Cosmetics
Adhesives & Sealants
Textiles
Home Care
Pharmaceuticals
Construction
Pulp & Paper
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Australia
Rest of Asia Pacific
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
Table of Contents
1. Rheology Modifiers Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Rheology Modifiers Market Executive Summary
2.1. Market Snapshot
3. Rheology Modifiers Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Rheology Modifiers Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Rheology Modifiers Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Waterborne
5.1.2. Solvent-borne
5.2. Analysis, Insights and Forecast - by Nature
5.2.1. Organic
5.2.2. Inorganic
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Adhesives & Sealants
5.3.2. Cement & Concrete
5.3.3. Cleaners & Disinfectants
5.3.4. Coolants
5.3.5. Rubber Products
5.3.6. Lubricants & Greases
5.3.7. Fermentation
5.3.8. Others
5.4. Analysis, Insights and Forecast - by End-Use Industry
5.4.1. Paints & Coatings
5.4.2. Inks
5.4.3. Personal Care & Cosmetics
5.4.4. Adhesives & Sealants
5.4.5. Textiles
5.4.6. Home Care
5.4.7. Pharmaceuticals
5.4.8. Construction
5.4.9. Pulp & Paper
5.4.10. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. Rheology Modifiers Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Waterborne
6.1.2. Solvent-borne
6.2. Analysis, Insights and Forecast - by Nature
6.2.1. Organic
6.2.2. Inorganic
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Adhesives & Sealants
6.3.2. Cement & Concrete
6.3.3. Cleaners & Disinfectants
6.3.4. Coolants
6.3.5. Rubber Products
6.3.6. Lubricants & Greases
6.3.7. Fermentation
6.3.8. Others
6.4. Analysis, Insights and Forecast - by End-Use Industry
6.4.1. Paints & Coatings
6.4.2. Inks
6.4.3. Personal Care & Cosmetics
6.4.4. Adhesives & Sealants
6.4.5. Textiles
6.4.6. Home Care
6.4.7. Pharmaceuticals
6.4.8. Construction
6.4.9. Pulp & Paper
6.4.10. Others
7. Rheology Modifiers Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Waterborne
7.1.2. Solvent-borne
7.2. Analysis, Insights and Forecast - by Nature
7.2.1. Organic
7.2.2. Inorganic
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Adhesives & Sealants
7.3.2. Cement & Concrete
7.3.3. Cleaners & Disinfectants
7.3.4. Coolants
7.3.5. Rubber Products
7.3.6. Lubricants & Greases
7.3.7. Fermentation
7.3.8. Others
7.4. Analysis, Insights and Forecast - by End-Use Industry
7.4.1. Paints & Coatings
7.4.2. Inks
7.4.3. Personal Care & Cosmetics
7.4.4. Adhesives & Sealants
7.4.5. Textiles
7.4.6. Home Care
7.4.7. Pharmaceuticals
7.4.8. Construction
7.4.9. Pulp & Paper
7.4.10. Others
8. Rheology Modifiers Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Waterborne
8.1.2. Solvent-borne
8.2. Analysis, Insights and Forecast - by Nature
8.2.1. Organic
8.2.2. Inorganic
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Adhesives & Sealants
8.3.2. Cement & Concrete
8.3.3. Cleaners & Disinfectants
8.3.4. Coolants
8.3.5. Rubber Products
8.3.6. Lubricants & Greases
8.3.7. Fermentation
8.3.8. Others
8.4. Analysis, Insights and Forecast - by End-Use Industry
8.4.1. Paints & Coatings
8.4.2. Inks
8.4.3. Personal Care & Cosmetics
8.4.4. Adhesives & Sealants
8.4.5. Textiles
8.4.6. Home Care
8.4.7. Pharmaceuticals
8.4.8. Construction
8.4.9. Pulp & Paper
8.4.10. Others
9. Rheology Modifiers Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Waterborne
9.1.2. Solvent-borne
9.2. Analysis, Insights and Forecast - by Nature
9.2.1. Organic
9.2.2. Inorganic
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Adhesives & Sealants
9.3.2. Cement & Concrete
9.3.3. Cleaners & Disinfectants
9.3.4. Coolants
9.3.5. Rubber Products
9.3.6. Lubricants & Greases
9.3.7. Fermentation
9.3.8. Others
9.4. Analysis, Insights and Forecast - by End-Use Industry
9.4.1. Paints & Coatings
9.4.2. Inks
9.4.3. Personal Care & Cosmetics
9.4.4. Adhesives & Sealants
9.4.5. Textiles
9.4.6. Home Care
9.4.7. Pharmaceuticals
9.4.8. Construction
9.4.9. Pulp & Paper
9.4.10. Others
10. Rheology Modifiers Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Waterborne
10.1.2. Solvent-borne
10.2. Analysis, Insights and Forecast - by Nature
10.2.1. Organic
10.2.2. Inorganic
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Adhesives & Sealants
10.3.2. Cement & Concrete
10.3.3. Cleaners & Disinfectants
10.3.4. Coolants
10.3.5. Rubber Products
10.3.6. Lubricants & Greases
10.3.7. Fermentation
10.3.8. Others
10.4. Analysis, Insights and Forecast - by End-Use Industry
Table 14: Europe Rheology Modifiers Market Revenue Billion Forecast, by Type 2020 & 2034
Table 15: Europe Rheology Modifiers Market Revenue Billion Forecast, by Nature 2020 & 2034
Table 16: Europe Rheology Modifiers Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the Rheology Modifiers Market?
The global Rheology Modifiers Market was valued at USD 9.01 billion in 2024 and is projected to reach USD 13.11 billion by 2032, growing at a 4.80% CAGR.
2. Which region dominates the Rheology Modifiers Market?
Asia-Pacific leads with a 35.3% share in 2024, driven by industrialization, construction growth, and rising paints and personal care demand in China and India.
3. What are the key drivers of the Rheology Modifiers Market?
Key drivers include the shift to waterborne low-VOC coatings, construction and infrastructure spending, personal care premiumization, and oilfield drilling activity.
4. Who are the major players in the Rheology Modifiers Market?
Major players include BASF, Evonik, Dow, Clariant, Ashland, Arkema, Elementis, and Lubrizol, operating in a fragmented market with sub-80% concentration.
5. What are the main challenges in the Rheology Modifiers Market?
Stringent environmental regulations and raw material price volatility are key restraints, increasing compliance costs and margin pressure, especially for smaller formulators.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary research split, ensuring that the Rheology Modifiers Market analysis is grounded in direct industry validation. In-depth interviews were conducted with key stakeholders across the value chain, including raw material suppliers (cellulosic and clay producers), specialty chemical producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing insights into procurement strategies, formulation trends, and regulatory challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
30%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers
30%
Specialty Chemical Producers
45%
Contract Formulators
15%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
We benchmark our findings against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations) and patent databases. We also consult recognized non-profit technical standards and industry associations to validate product specifications and market definitions, ensuring a robust and traceable data foundation.
Demand Modeling & Market Sizing Triangulation
Market sizing is performed through simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. This dual approach reconciles supply-side and demand-side estimates, producing a validated base-year market size and forecast horizon.


 Rheology Modifiers Market