Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Shotcrete Market Size, Share & Forecast to 2036
Shotcrete Market
Shotcrete Market Size, Share & Forecast to 2036
Shotcrete Market by Process (Wet Mix, Dry Mix, Self-Compacting), by Application (Underground Construction, Slope & Surface Protection, Repair Works, New Surface Structures, Others), by System (Robotic Spraying, Manual/Pneumatic, Mechanical Pumped), by Material (Portland Cement Based, Non-Portland Cement Based, Fiber Reinforced), by End Use (Construction, Mining, Water & Wastewater, Tunneling), by Europe (Germany, UK, France, Italy, Benelux), by Asia Pacific (China, India, Japan, South Korea, Australia), by North America (USA, Canada, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by Latin America (Brazil, Chile, Argentina) Forecast 2026-2034
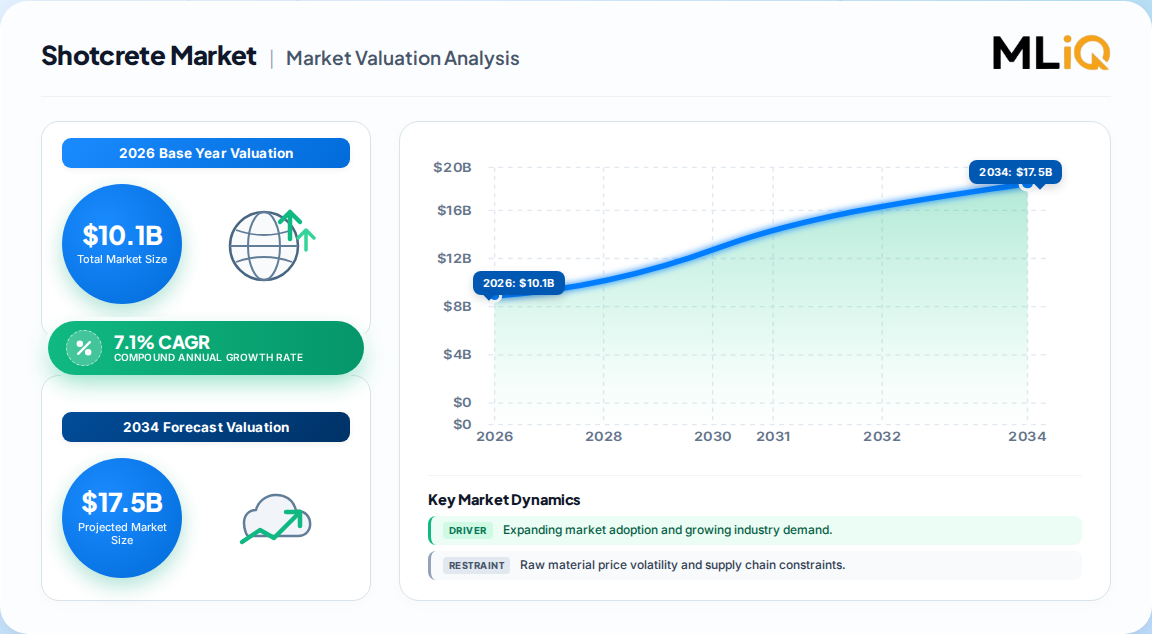
The global shotcrete market is valued at approximately 10.1 Billion in 2026, with a mid-case expansion path to roughly 18.4 Billion by 2036.
Consensus CAGR clusters in the 6.2% to 8.2% band; our blended mid-case of 7.1% reflects divergent base-year definitions rather than demand disagreement.
Wet-mix shotcrete leads process share at 55–60% of sales, favored on long tunnel and mine drives for steady output and lower rebound.
Europe is the largest regional market (about 34–35% revenue share), while Asia Pacific is the fastest-growing, led by Chinese and Indian tunnel programs.
Underground construction is the leading application at 34–39% share; slope and surface protection is the fastest-growing application.
Leading vendors include Sika AG, GCP Applied Technologies, LafargeHolcim, Cemex, BASF, Normet, Putzmeister and Quikrete.
Why this matters for decision-makers: Equipment capital and skilled-operator scarcity—not material demand—will decide who captures the 2030s tunneling cycle; vendors must bundle robotic systems with training and admixture supply to avoid margin compression.
Shotcrete Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.500 B
2025
10.10 B
2026
10.80 B
2027
11.60 B
2028
12.40 B
2029
13.30 B
2030
14.20 B
2031
Shotcrete Market Size (In Billion)
Year
Market Size
2025
9.500 B
2026
10.10 B
2027
10.80 B
2028
11.60 B
2029
12.40 B
2030
13.30 B
2031
14.20 B
What is the Shotcrete Market?
The shotcrete market covers the supply and application of concrete or mortar sprayed at high velocity onto prepared surfaces, without formwork. It spans wet-mix and dry-mix processes, fiber-reinforced formulations, and pneumatic, mechanical or robotic application, serving tunneling, mining, slope stabilization, repair and structural work.
Scope: what this report covers and excludes
This analysis covers global shotcrete materials, admixtures, application equipment and contractor services across wet-mix and dry-mix processes, new construction, underground works, repair and slope protection, with regional splits through 2036. This analysis does not cover conventional cast-in-place concrete, precast concrete products, refractory gunning for industrial furnaces, or 3D-printed concrete construction.
How big is the market for Shotcrete Market?
Published estimates converge on a roughly 10 Billion base in 2025–2026, but the spread from 7.2 Billion to 10.4 Billion reflects genuinely different definitions—process-only versus equipment-inclusive scopes. Buyers should anchor on the mid-case trajectory near 7% CAGR rather than any single headline number.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
63.79 Billion → 130.45 Billion
2024
2035
6.72%
Broad construction-materials envelope, all sprayed applications
One published estimate
9.6 Billion → 18.1 Billion
2025
2033
8.2%
Materials plus application services, wet and dry mix
A competing analysis
10.1 Billion → 18.4 Billion
2026
2036
6.2%
Materials-centric, heavy underground and mining weighting
A competing analysis
7.21 Billion → 14.32 Billion
2024
2034
7.10%
Narrow process-only material scope, excludes equipment
A competing analysis
Our analysis suggests the 10.1 Billion / 6.2% framing is the most defensible for procurement planning, because it aligns with disclosed tunnel completion volumes and equipment launch cadence. The 8.2% figure likely embeds service revenue and is vulnerable to double-counting at the contractor level.
How is the market segmented?
Shotcrete segments along four commercially meaningful axes: process, application, application system, and end use. Process choice drives equipment capital and material sourcing alike, making it the primary procurement decision.
Construction, Mining, Water & Wastewater, Tunneling
Wet mix wins on continuous drives where batching plants can match excavation pace. Dry mix retains a durable niche in pool construction, decorative rockwork and small-scale repair, and is growing faster off a small base because it demands less capital equipment.
Which region leads in Shotcrete Market?
Europe leads with roughly a third of global revenue, underpinned by an aging tunnel and transit network requiring rehabilitation, plus concentrated R&D capacity. Asia Pacific is the fastest-growing region, powered by record-length tunnel programs in China and India and expanding underground mining.
Shotcrete Market Regional Market Share
Loading chart...
Shotcrete Market Regional Market Share
Region
Market Share (%)
Europe
0.34%
Asia Pacific
0.29%
North America
0.22%
Middle East & Africa
0.08%
Latin America
0.07%
Europe — ~34% share; rehabilitation-led demand, Sika and BASF admixture capacity, strict durability standards
Germany, UK, France, Italy, Benelux
Asia Pacific — ~29% share, fastest growth; China (Tianshan Shengli, 22.13 km), India (100+ km of tunnels across 26 projects in 2024–25)
China, India, Japan, South Korea, Australia
North America — ~22% share; slower growth (~5.9% in the US) but high equipment and safety specification
USA, Canada, Mexico
Middle East & Africa — ~8% share; giga-project and mining-led
Saudi Arabia, UAE, South Africa
Latin America — ~7% share; mining-centric, Vale Carajas expansion cited at USD 12 billion
Brazil, Chile, Argentina
The divergence implies a two-speed market: European demand is replacement-driven and specification-led, while Asia Pacific demand is greenfield and volume-led. Vendors need separate pricing and service architectures for each.
What is driving growth — and what is holding it back?
Tunnel and mining investment is the dominant growth engine, reinforced by repair demand on aging infrastructure. Restraining forces are commercial and capability-based—equipment cost, skilled labor scarcity, and entrenched cast-concrete habits—rather than a shortage of underlying project demand.
Factor
Direction
Evidence Strength
Mechanism
Tunnel and underground programs
Growth
High
Wet-mix batching demand scales with continuous drives
Mining expansion and ground support
Growth
High
Robotic spraying moves crews from unstable faces
Infrastructure repair and rehabilitation
Growth
Medium-High
Aging European and North American assets
Robotic and digital application technology
Growth
Medium
Safety and rebound reduction justify capital
Skilled operator shortage
Restraint
High
Limits adoption pace, especially in the US
High equipment and plant capex
Restraint
High
Blocks small manufacturer entry
Cast-concrete competition on flat surfaces
Restraint
Medium
Superior finish and lower skill threshold
The balance favors demand, but the binding constraint is execution capacity. Our analysis suggests the industry's growth ceiling through 2030 is set less by order books than by how fast spray crews can be trained and robotic fleets deployed.
Who are the leading vendors?
The competitive field splits into materials and admixture majors (Sika, BASF, GCP, LafargeHolcim, Cemex) and equipment specialists (Normet, Putzmeister, Schwing Stetter), with regional players filling local supply gaps.
Company
Category
Primary Strength
Moat
Sika AG
Admixtures & materials
Accelerators, global plant network
Formulation IP and technical service
GCP Applied Technologies
Admixtures
Sprayed-concrete additives
Specification entrenchment
LafargeHolcim
Cement & aggregates
Integrated material supply
Vertical integration
Cemex
Cement & ready-mix
Regional supply depth
Logistics network
BASF
Construction chemicals
Admixture portfolio
R&D scale
Normet
Equipment
Spraymec wet-mix sprayers
Underground application expertise
Putzmeister Underground
Equipment
Robotic sprayers (Wetkret 2)
Narrow-section robotics reach
Quikrete
Packaged materials
Dry-mix distribution
Retail and dealer breadth
Moats are application-specific, not generic: admixture leaders defend through specification and technical service, while equipment leaders defend through safety performance and dealer support. Our analysis suggests the most durable position is the integrated one—bundling admixture supply with robotic equipment and operator training—which few players currently execute end-to-end.
What do buyers and operators need to know? (Decision Support)
Selection should be driven by rebound loss economics, not sticker price. Wet-mix systems carry higher upfront batching and pump capital, but on drives exceeding a few hundred meters the material savings and output consistency typically amortize the premium faster than dry-mix alternatives.
Procurement risk concentrates in three areas: skilled-operator availability, spare-parts lead times for robotic arms, and admixture compatibility with local cement chemistries. Buyers should contract for operator training and formulation trials before committing to fleet-scale orders.
Switching costs are meaningful. Once a contractor has standardized on a wet-mix batching plant and a specific accelerator chemistry, changing suppliers requires re-validating set times, strength gain and rebound rates—often across multiple project sites. Regulatory compliance is comparatively light at the product level but tightening on silica dust exposure and accelerator alkalinity, which increasingly favor enclosed robotic application over manual lances.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit-to-7% CAGR rather than the double-digit optimists' case, because equipment and labor constraints cap how quickly demand converts to revenue. The strongest counter-argument is that massive Asian tunnel pipelines could pull forward adoption faster than projected; however, even aggressive program counts imply a ramp measured in years, not quarters.
What the data really signals is a capability race, not a demand race. Vendors that only sell material will face price competition; vendors that sell the full spray system—chemistry, robotics, and trained crews—will capture disproportionate value. The European rehabilitation cycle adds a second, more predictable revenue lane that is frequently underestimated relative to headline tunneling.
Actionable strategy:
Integrate admixture and equipment offerings to lock in specification and defend margin against commodity material suppliers.
Invest in operator training programs as a commercial moat, since skilled-labor scarcity is the binding constraint in North America and Europe.
Prioritize Asia Pacific and European rehabilitation as the two highest-conviction growth lanes, with distinct pricing and service models.
What would change our conclusion: evidence of accelerated robotic deployment lowering the skilled-labor constraint, or a step-change in tunnel award volumes in India or China beyond announced pipelines, would justify upgrading the growth outlook. Conversely, sustained raw-material and accelerator price volatility would compress equipment-attached margins.
Shotcrete Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Shotcrete Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.1% from 2020-2034
Segmentation
By Process
Wet Mix
Dry Mix
Self-Compacting
By Application
Underground Construction
Slope & Surface Protection
Repair Works
New Surface Structures
Others
By System
Robotic Spraying
Manual/Pneumatic
Mechanical Pumped
By Material
Portland Cement Based
Non-Portland Cement Based
Fiber Reinforced
By End Use
Construction
Mining
Water & Wastewater
Tunneling
By Geography
Europe
Germany
UK
France
Italy
Benelux
Asia Pacific
China
India
Japan
South Korea
Australia
North America
USA
Canada
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Latin America
Brazil
Chile
Argentina
Table of Contents
1. Shotcrete Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Shotcrete Market Executive Summary
2.1. Market Snapshot
3. Shotcrete Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Shotcrete Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Shotcrete Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Process
5.1.1. Wet Mix
5.1.2. Dry Mix
5.1.3. Self-Compacting
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Underground Construction
5.2.2. Slope & Surface Protection
5.2.3. Repair Works
5.2.4. New Surface Structures
5.2.5. Others
5.3. Analysis, Insights and Forecast - by System
5.3.1. Robotic Spraying
5.3.2. Manual/Pneumatic
5.3.3. Mechanical Pumped
5.4. Analysis, Insights and Forecast - by Material
5.4.1. Portland Cement Based
5.4.2. Non-Portland Cement Based
5.4.3. Fiber Reinforced
5.5. Analysis, Insights and Forecast - by End Use
5.5.1. Construction
5.5.2. Mining
5.5.3. Water & Wastewater
5.5.4. Tunneling
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Europe
5.6.2. Asia Pacific
5.6.3. North America
5.6.4. Middle East & Africa
5.6.5. Latin America
6. Shotcrete Market Europe Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Process
6.1.1. Wet Mix
6.1.2. Dry Mix
6.1.3. Self-Compacting
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Underground Construction
6.2.2. Slope & Surface Protection
6.2.3. Repair Works
6.2.4. New Surface Structures
6.2.5. Others
6.3. Analysis, Insights and Forecast - by System
6.3.1. Robotic Spraying
6.3.2. Manual/Pneumatic
6.3.3. Mechanical Pumped
6.4. Analysis, Insights and Forecast - by Material
6.4.1. Portland Cement Based
6.4.2. Non-Portland Cement Based
6.4.3. Fiber Reinforced
6.5. Analysis, Insights and Forecast - by End Use
6.5.1. Construction
6.5.2. Mining
6.5.3. Water & Wastewater
6.5.4. Tunneling
7. Shotcrete Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Process
7.1.1. Wet Mix
7.1.2. Dry Mix
7.1.3. Self-Compacting
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Underground Construction
7.2.2. Slope & Surface Protection
7.2.3. Repair Works
7.2.4. New Surface Structures
7.2.5. Others
7.3. Analysis, Insights and Forecast - by System
7.3.1. Robotic Spraying
7.3.2. Manual/Pneumatic
7.3.3. Mechanical Pumped
7.4. Analysis, Insights and Forecast - by Material
7.4.1. Portland Cement Based
7.4.2. Non-Portland Cement Based
7.4.3. Fiber Reinforced
7.5. Analysis, Insights and Forecast - by End Use
7.5.1. Construction
7.5.2. Mining
7.5.3. Water & Wastewater
7.5.4. Tunneling
8. Shotcrete Market North America Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Process
8.1.1. Wet Mix
8.1.2. Dry Mix
8.1.3. Self-Compacting
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Underground Construction
8.2.2. Slope & Surface Protection
8.2.3. Repair Works
8.2.4. New Surface Structures
8.2.5. Others
8.3. Analysis, Insights and Forecast - by System
8.3.1. Robotic Spraying
8.3.2. Manual/Pneumatic
8.3.3. Mechanical Pumped
8.4. Analysis, Insights and Forecast - by Material
8.4.1. Portland Cement Based
8.4.2. Non-Portland Cement Based
8.4.3. Fiber Reinforced
8.5. Analysis, Insights and Forecast - by End Use
8.5.1. Construction
8.5.2. Mining
8.5.3. Water & Wastewater
8.5.4. Tunneling
9. Shotcrete Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Process
9.1.1. Wet Mix
9.1.2. Dry Mix
9.1.3. Self-Compacting
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Underground Construction
9.2.2. Slope & Surface Protection
9.2.3. Repair Works
9.2.4. New Surface Structures
9.2.5. Others
9.3. Analysis, Insights and Forecast - by System
9.3.1. Robotic Spraying
9.3.2. Manual/Pneumatic
9.3.3. Mechanical Pumped
9.4. Analysis, Insights and Forecast - by Material
9.4.1. Portland Cement Based
9.4.2. Non-Portland Cement Based
9.4.3. Fiber Reinforced
9.5. Analysis, Insights and Forecast - by End Use
9.5.1. Construction
9.5.2. Mining
9.5.3. Water & Wastewater
9.5.4. Tunneling
10. Shotcrete Market Latin America Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Process
10.1.1. Wet Mix
10.1.2. Dry Mix
10.1.3. Self-Compacting
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Underground Construction
10.2.2. Slope & Surface Protection
10.2.3. Repair Works
10.2.4. New Surface Structures
10.2.5. Others
10.3. Analysis, Insights and Forecast - by System
10.3.1. Robotic Spraying
10.3.2. Manual/Pneumatic
10.3.3. Mechanical Pumped
10.4. Analysis, Insights and Forecast - by Material
10.4.1. Portland Cement Based
10.4.2. Non-Portland Cement Based
10.4.3. Fiber Reinforced
10.5. Analysis, Insights and Forecast - by End Use
10.5.1. Construction
10.5.2. Mining
10.5.3. Water & Wastewater
10.5.4. Tunneling
11. Shotcrete Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Shotcrete Market Research Methodology
List of Figures
Figure 1: Shotcrete Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Europe Shotcrete Market Revenue (Billion), by Process 2026 & 2034
Figure 3: Europe Shotcrete Market Revenue Share (%), by Process 2026 & 2034
Figure 4: Europe Shotcrete Market Revenue (Billion), by Application 2026 & 2034
Figure 5: Europe Shotcrete Market Revenue Share (%), by Application 2026 & 2034
Figure 6: Europe Shotcrete Market Revenue (Billion), by System 2026 & 2034
Figure 7: Europe Shotcrete Market Revenue Share (%), by System 2026 & 2034
Figure 8: Europe Shotcrete Market Revenue (Billion), by Material 2026 & 2034
Figure 9: Europe Shotcrete Market Revenue Share (%), by Material 2026 & 2034
Figure 10: Europe Shotcrete Market Revenue (Billion), by End Use 2026 & 2034
Figure 11: Europe Shotcrete Market Revenue Share (%), by End Use 2026 & 2034
Figure 12: Europe Shotcrete Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Europe Shotcrete Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Asia Pacific Shotcrete Market Revenue (Billion), by Process 2026 & 2034
Figure 15: Asia Pacific Shotcrete Market Revenue Share (%), by Process 2026 & 2034
Figure 16: Asia Pacific Shotcrete Market Revenue (Billion), by Application 2026 & 2034
Figure 17: Asia Pacific Shotcrete Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Shotcrete Market Revenue Billion Forecast, by Process 2020 & 2034
The global shotcrete market is approximately 10.1 Billion in 2026. Published estimates range from 7.2 Billion to 10.4 Billion depending on whether equipment and services are included, with a mid-case path to about 18.4 Billion by 2036.
2. What is the shotcrete market growth rate?
Consensus CAGR sits between 6.2% and 8.2%, with our blended mid-case at roughly 7.1% through 2036. The spread reflects scope differences rather than disagreement on underlying tunnel, mining and repair demand.
3. Which process type leads the shotcrete market?
Wet-mix shotcrete leads with 55–60% of process share. It is preferred on long tunnel and mine drives because pre-mixed batching delivers steadier output and lower rebound loss than dry-mix application.
4. Which region dominates the shotcrete market?
Europe leads with about 34–35% revenue share, driven by rehabilitation of aging tunnels and transit infrastructure. Asia Pacific is the fastest-growing region, led by tunnel programs in China and India.
5. Who are the leading shotcrete companies?
Leading suppliers include Sika AG, GCP Applied Technologies, LafargeHolcim, Cemex, BASF, Normet, Putzmeister Underground and Quikrete, spanning admixtures, cement supply and robotic spraying equipment.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the shotcrete value chain with specialty admixture and cement producers, shotcrete equipment manufacturers, contract applicators and formulators, and regional distributors. Decision-maker participants included VP-level sourcing leads, heads of R&D and formulation, technical directors responsible for tunnel and mining specifications, and commercial operations leads managing fleet deployment. Interview programs are structured to capture both material purchasing behavior and equipment capital decision cycles.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Quality & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Admixture & Cement Producers
40%
Equipment Manufacturers
30%
Contract Applicators & Formulators
20%
Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases including UN Comtrade, WTO tariff and trade statistics, US ITC data and Eurostat construction and cement trade flows. Corporate annual filings, SEC 10-K disclosures and investor presentations provide capacity and revenue triangulation. Patent databases inform technology positioning in robotic spraying and admixture chemistry, while recognized technical standards and industry associations anchor specification requirements.
Demand Modeling & Market Sizing Triangulation
We run top-down and bottom-up models simultaneously. The top-down model allocates macroeconomic construction and mining output to sprayed-concrete intensity by region. The bottom-up model builds from manufacturer capacity, product pricing and end-use consumption by application. Divergence between the two is reconciled through segment-level checks and disclosed tunnel completion benchmarks.


 Shotcrete Market