 United Arab Emirates Protective Coatings Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 197

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 United Arab Emirates Protective Coatings Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 63.00 M |
| 2026 | 65.00 M |
| 2027 | 68.00 M |
| 2028 | 70.00 M |
| 2029 | 72.00 M |
| 2030 | 75.00 M |

The UAE protective coatings market covers formulations applied to steel, concrete, and industrial substrates to prevent corrosion, chemical attack, abrasion, and fire damage. It spans new-build and maintenance demand across oil and gas, infrastructure, power, and mining, measured in revenue (USD million) by technology, resin chemistry, and end-user industry.
This analysis covers protective and industrial maintenance coatings consumed in the United Arab Emirates across oil and gas, infrastructure, power, mining, and other industrial end uses, segmented by technology (solvent-borne, waterborne, powder, UV-cured) and resin type (epoxy, polyurethane, acrylic, alkyd, polyester, others). Marine newbuild coatings applied outside UAE yards, decorative architectural paints, automotive OEM coatings, and can coatings are excluded. This analysis does not cover adjacent markets such as construction chemicals, thermal insulation, or raw material supply.
Published estimates diverge sharply because "protective coatings" is defined differently across sources, from a narrow corrosion-protection core to a broad industrial coatings aggregate. The table below compares the available benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 63 million | 2025 (year-end) | 2028 | 3.5% | Pure protective coatings (corrosion, chemical, fire protection) | One published research estimate |
| USD 1.1 billion | 2025 | 2034 | 4.65% | All paints and coatings (decorative + protective + industrial) | A competing analysis |
| USD 601 million | 2025 | 2032 | 8.05% | Paints and coatings, narrower product basket | A competing analysis |
Our analysis treats the USD 63 million protective-coatings figure as the most defensible anchor for this specific scope, because the broader USD 601 million and USD 1.1 billion figures explicitly bundle decorative and automotive coatings. The wider benchmarks are nonetheless useful as a directional signal: the UAE coatings complex is growing faster than the protective sub-segment alone, which implies protective coatings are losing relative share to decorative and powder architectural demand. Buyers should anchor procurement budgets to the protective-only estimate but stress-test volume assumptions against the 4.65% aggregate CAGR.
Segmentation follows three non-geographic axes: end-user industry, technology platform, and resin chemistry. The structure matters because growth rates diverge materially between solvent-borne maintenance demand and powder new-build specification.
| Parent Segment | Children |
|---|---|
| End-user Industry | Oil and Gas; Infrastructure; Power; Mining; Other Industrial |
| Technology | Solvent-borne; Waterborne; Powder; UV-Cured |
| Resin Type | Epoxy; Polyurethane; Acrylic; Alkyd; Polyester; Others |
Abu Dhabi leads the UAE protective coatings market, reflecting the concentration of upstream oil and gas assets, refineries, and ADNOC-linked industrial projects, followed by Dubai's infrastructure and real estate pipeline.
Our analysis suggests Abu Dhabi's share is structurally protected by the capex cycle of ADNOC and its joint ventures, making it less cyclical than Dubai's construction-led demand. Sharjah's industrial base gives it a disproportionate share of mid-tier maintenance coatings volume relative to its economic size.
Growth is driven by sustained infrastructure spend and upstream oil and gas capex, while raw material price volatility is the principal drag on margins and project timing.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Federal infrastructure programme (USD 2.7 billion, 36 projects) | Driver | High | Direct steel and concrete protective specification |
| Oil and gas capex (ADNOC USD 658 million framework awards) | Driver | High | Corrosion and chemical-resistant coating demand |
| Road network expansion (e.g., USD 1.37 billion Dubai scheme) | Driver | Medium | Bridge, gantry, and structural steel coatings |
| Raw material price volatility | Restraint | High | Resin and solvent cost pass-through lag |
| Shift to low-VOC and powder systems | Opportunity | Medium | Reformulation and premium specification |
The balance of evidence favours the drivers through 2027: government-linked infrastructure spend is contractually committed, whereas raw material volatility compresses margins but rarely cancels projects. Our analysis suggests the restraint is therefore a profitability issue rather than a volume issue, which favours formulators with hedging capability and local blending capacity.
Leading vendors combine global technology portfolios with UAE manufacturing and specification relationships; the market is fragmented, so no single player controls pricing.
| Company | Positioning | Notable strength |
|---|---|---|
| Akzo Nobel N.V. | Global premium protective coatings | International specification and offshore/marine heritage |
| Jotun | Regional leader with UAE plants | Local R&D, humidity/UV-adapted systems |
| Nippon Paint Holdings | Global industrial coatings | Broad technology and distribution reach |
| Sigma Paints | Regional protective and marine | Gulf project familiarity |
| The Sherwin-Williams Company | Global protective and industrial | Heavy-duty and fire protection range |
| National Paints | UAE-based manufacturer | Vertically integrated Sharjah plant, cost position |
Differentiation rests on three moats: approved-product listings with ADNOC and municipal authorities, local manufacturing that shortens lead times and satisfies in-country value incentives, and technical service capability for inspection and warranty-backed systems. Our analysis suggests the in-country value programme is quietly shifting advantage toward local producers, which is a structural risk for imported premium brands.
Buyers should prioritise specification compliance over unit price: protective coating failures in UAE conditions typically trace to inadequate surface preparation and dry-film thickness control, not to resin chemistry itself. Procurement should therefore mandate third-party inspection, certified applicator qualification, and warranty terms tied to ISO 12944 corrosivity categories.
Switching costs are high in oil and gas because approved vendor lists and re-qualification testing are slow and expensive; operators rarely change protective coating suppliers mid-asset-life. Conversely, infrastructure contractors switch more readily, making that segment price-sensitive and vulnerable to low-cost imports. Regulatory compliance is tightening: federal climate legislation effective May 2025 and Dubai Municipality VOC limits increasingly favour waterborne and high-solids systems, so buyers should build low-VOC specifications into tenders now rather than retrofit later. Finally, maintenance backlog is an underappreciated demand pool; refinishing ageing steel across roads and utilities is less cyclical than new build.
The balance of evidence favours a modest, margin-constrained growth story rather than a volume boom. At 3.5% CAGR, the UAE protective coatings market rewards suppliers who win specification influence and local content credentials, not those chasing headline expansion. The strongest counter-argument is that infrastructure spend is lumpy and politically timed, so a single mega-project pause could turn 3.5% growth into flat volume for a year.
Our analysis suggests three durable shifts. First, powder and high-solids systems will outgrow solvent-borne demand as VOC rules tighten, creating premium pricing headroom. Second, in-country value incentives will progressively favour local formulators such as National Paints and Jotun's UAE operations over imported brands, particularly in government-funded infrastructure. Third, the fragmented structure means consolidation opportunities exist for buyers seeking installed capacity and approved-vendor listings.
The conclusion would change if ADNOC upstream capex slowed materially or if federal infrastructure disbursements were deferred beyond 2027.
| Region | Market Share (%) |
|---|---|
| Abu Dhabi | 0.46% |
| Dubai | 0.31% |
| Sharjah | 0.13% |
| Northern Emirates | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.5% from 2020-2034 |
| Segmentation |
|
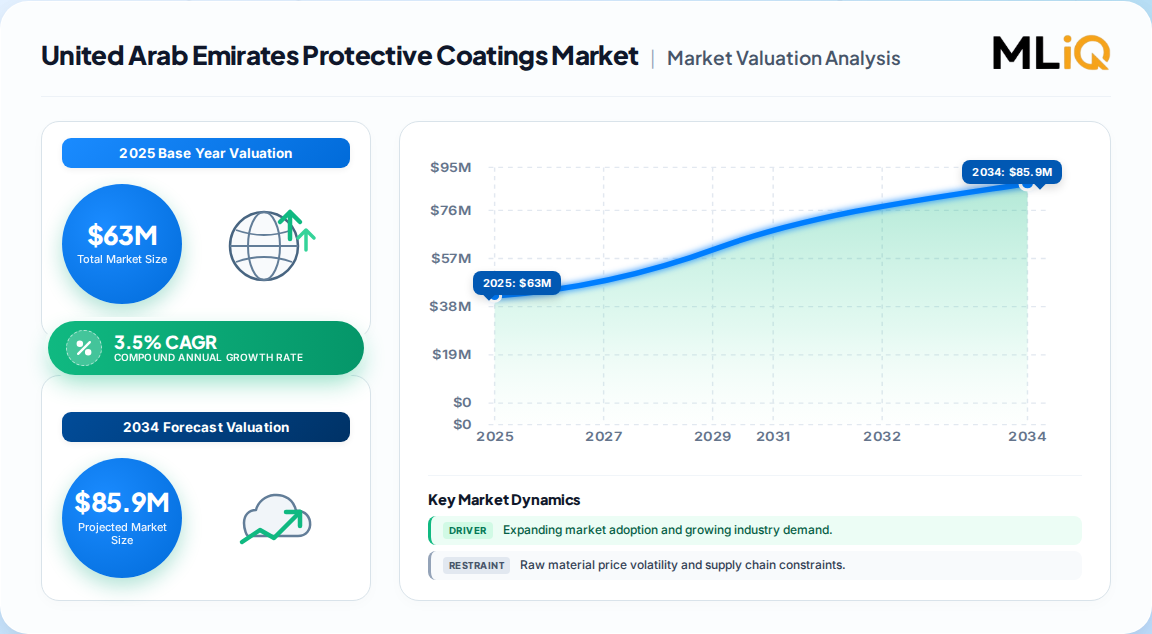
The UAE protective coatings market was valued at approximately USD 63 million at year-end 2025. Broader paints and coatings estimates reach USD 1.1 billion, but those include decorative and automotive segments outside the protective scope.
The market is projected to grow at a CAGR of 3.5% through 2030. Growth is led by infrastructure and oil and gas demand, with powder coatings offering the strongest incremental opportunity as VOC rules tighten.
Infrastructure dominates the end-user segment, driven by federal road, bridge, and government building programmes. Oil and gas is the second major demand pool, anchored by ADNOC upstream and refining capex.
Akzo Nobel, Jotun, Nippon Paint Holdings, Sigma Paints, and Sherwin-Williams are the leading players, alongside UAE-based National Paints. The market is fragmented, with no single vendor controlling pricing.
The UAE's high UV, humidity, and salt-laden coastal air accelerate steel and concrete corrosion, making protective coatings essential for asset integrity, safety compliance, and extending the service life of industrial and infrastructure assets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split, prioritising direct industry verification over published benchmarks. In-depth interviews were conducted across the value chain with raw material and specialty resin suppliers, specialised protective coating producers, contract formulators and blenders, and regional industrial distributors. Within these organisations we engaged decision-makers including VP-level Sourcing leads, Heads of R&D and formulation, Technical Directors responsible for specification and warranty, and Commercial Operations Leads managing Gulf project pipelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Specialty Resin Producers | 40% |
| Protective Coating Formulators | 35% |
| Distributors & Project Suppliers | 25% |
Secondary validation draws on official multilateral trade databases including UN Comtrade and WTO statistics, national customs records, corporate annual filings and investor presentations, patent databases for coating chemistry innovation, and recognised technical standards bodies and industry associations active in corrosion protection and coatings performance.
We run simultaneous top-down allocation from macroeconomic and construction/industrial output data and bottom-up modeling from manufacturer capacity, product pricing, and end-use consumption intensity. Divergences between the two approaches are reconciled through segment-level elasticity assumptions and project pipeline verification.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Emirate-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |