 Unsaturated Polyester Resins Market
 Size, Trends & Forecast
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Unsaturated Polyester Resins Market

Khageshwar Rongkali
Senior Analyst

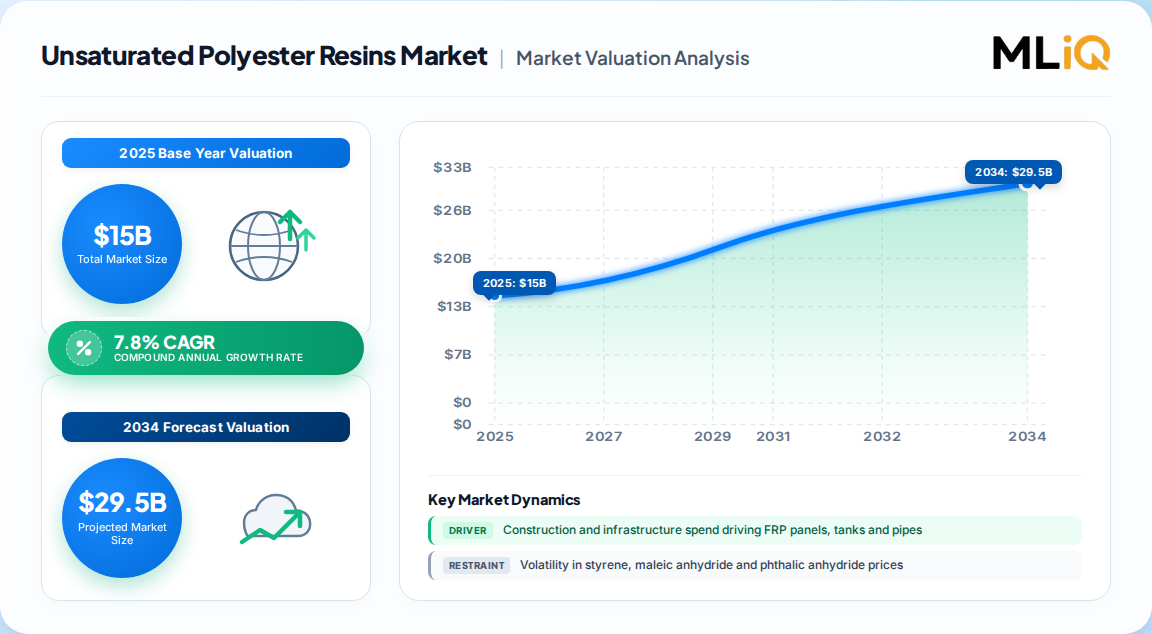
| Year | Market Size |
|---|---|
| 2024 | 13.90 B |
| 2025 | 15.00 B |
| 2026 | 16.20 B |
| 2027 | 17.40 B |
| 2028 | 18.80 B |
| 2029 | 20.30 B |
| 2030 | 21.90 B |

Unsaturated polyester resins (UPR) are thermosetting polymers formed by polycondensation of unsaturated dibasic acids with diols, dissolved in styrene and cured by peroxide initiators. They deliver high strength-to-weight ratio, corrosion resistance, and ease of processing at low cost, making them the workhorse matrix for glass-fiber-reinforced plastics in construction, marine, transportation, and tanks and pipes.
This report covers global demand for orthophthalic, isophthalic, DCPD-modified and other unsaturated polyester resins in liquid and solid form, across heat, room-temperature and UV curing, sold to building and construction, fiberglass-reinforced plastics, marine, tanks and pipes, and transportation end uses. The analysis does not cover epoxy, vinyl ester, phenolic or thermoplastic composite matrices, nor downstream composite part fabrication or gelcoat and pigment paste markets.
Published estimates diverge sharply because of differing base years, scope definitions and unit assumptions. The table below compares the most defensible benchmarks.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 15.0 billion | 2025 | 2033 | 7.8% | Global UPR, all products and forms, end-use segmented | Consensus synthesis of published benchmarks |
| USD 12.90 billion | 2026 | 2035 | 7.49% | Global UPR, 2026 base, type/form/curing segmented | Aggregated industry estimate A |
| USD 15.8 billion | 2026 | 2033 | 8.3% | Global UPR, product/end-use/form segmented | Aggregated industry estimate B |
| USD 15.21 billion | 2025 | 2035 | 2.84% | Global UPR, form/curing/unsaturation/application segmented | Aggregated industry estimate C |
The 7.8% central figure is most defensible for strategic planning: it reconciles the 7.49–8.3% cluster around construction and transportation demand, while the 2.84% outlier appears to embed a mature-market volume assumption that ignores Asia Pacific capacity additions. Our analysis suggests buyers should plan on a 7–8% nominal CAGR band, with downside risk tied to styrene and maleic anhydride price volatility rather than demand destruction.
Segmentation below follows non-geographic parents; each child maps to revenue or volume splits reported in the reference set.
| Parent | Children | Largest / fastest observation |
|---|---|---|
| By Product | Orthophthalic, Isophthalic, DCPD, Other | Orthophthalic ≈35–46% share; DCPD fastest at ≈8.9% CAGR |
| By Form | Liquid, Solid | Liquid ≈73–82% share; solid fastest in prepreg composites |
| By Curing | Room Temperature, Heat, UV | Room temperature ≈58%; UV fastest in rapid prototyping |
| By Application | Building & Construction, FRP, Marine, Tanks & Pipes, Transportation, Other | Building & Construction ≈26–42%; FRP largest by volume |
| By Degree of Unsaturation | High, Medium, Low | Medium ≈48% share; high preferred in marine |
The divergence in application shares (25.7% vs 42.3%) reflects whether FRP is counted as a separate end use or allocated to construction and tanks. Our analysis suggests the standalone-FRP convention is more useful for formulators, because it isolates the spray-up and hand lay-up demand pool where liquid orthophthalic dominates.
Asia Pacific leads with roughly 55% of global revenue, concentrated in China, India and Southeast Asia, where infrastructure build-out and automotive lightweighting absorb the majority of orthophthalic and DCPD grades.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.55% |
| North America | 0.15% |
| Europe | 0.15% |
| Latin America | 0.07% |
| Middle East & Africa | 0.08% |
Regional shares from the reference set range from 49.9% to 59.3% for Asia Pacific; we use 55% as the consensus midpoint. This implies Western producers face structurally lower volume growth and must compete on specialty isophthalic and low-VOC grades rather than commodity orthophthalic.
Construction and transportation lightweighting are the dominant demand drivers, while raw-material price volatility and styrene regulation are the principal restraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Construction and infrastructure spend | Driver | High | FRP panels, roofing, tanks and sanitary ware consume orthophthalic resin at scale |
| Automotive lightweighting and EVs | Driver | High | 30% weight reduction vs steel drives FRP exterior and battery enclosure parts |
| Marine and corrosion-resistant tanks | Driver | Medium | Isophthalic and DCPD grades preferred for hulls and chemical storage |
| Bio-based and low-VOC formulation | Driver | Medium | Regulatory and OEM sustainability mandates shift sourcing to eco-grades |
| Petrochemical feedstock volatility | Restraint | High | Styrene, maleic and phthalic anhydride swings compress formulator margins |
| Epoxy, vinyl ester and thermoplastic substitution | Restraint | Medium | Higher-performance or recyclable alternatives win premium applications |
| Quality and storage sensitivity | Restraint | Medium | Humidity, UV and heat degrade shelf life and brand trust |
The balance favors demand: construction and transportation together account for roughly half of consumption and are growing faster than substitution erodes commodity grades. The binding constraint is margin, not volume — styrene compliance costs will separate integrated producers from blenders.
The market is fragmented but consolidating, with integrated chemical majors and regional specialists competing on formulation breadth, local supply and sustainability credentials.
| Company | Headquarters | Strategic position | Notable signal |
|---|---|---|---|
| INEOS Composites | UK / global | Scale leader in UPR and gelcoats | Acquired by KPS Capital for EUR 1.7 billion, Dec 2024 |
| Polynt Group | Italy | Broad product and curing portfolio | European and Americas footprint |
| AOC Resins | Switzerland | Asia expansion and specialty grades | Nanjing, China production line, Aug 2024 |
| BASF SE | Germany | Integrated feedstock and formulation | Global distribution reach |
| Ashland / Hexion | USA | Performance composites focus | Marine and transportation niches |
| UPC Group, Scott Bader, Eternal, Satyen | Various | Regional specialists | Cost and service advantage in home markets |
Differentiation rests on formulation know-how (cure speed, toughness, low styrene), local supply reliability and certification support. Private-equity ownership of INEOS Composites signals margin discipline and likely portfolio pruning toward high-value grades, which our analysis suggests will cede commodity share to Asian producers.
Procurement should prioritize total cost of ownership over headline resin price: cure speed, wet-out and shrinkage determine scrap and rework rates that dwarf per-kilogram savings. Qualify at least two suppliers per grade family, because styrene allocation and freight volatility can create single-source exposure within a quarter.
Regulatory compliance is a gating criterion. Styrene emissions rules in Europe and North America increasingly require low-VOC or bio-based grades, and operators without formulation flexibility face retrofit costs. Switching costs are moderate — requalification of laminates typically takes four to eight weeks — but marine and pressure-vessel applications demand full re-certification, raising the effective barrier.
Operators should also track storage and shelf-life risk: improper temperature, humidity or UV exposure degrades resin and voids warranty claims. Inventory rotation discipline and supplier documentation of batch stability are low-cost protections against quality-driven margin loss.
The balance of evidence favors a 7–8% mid-case CAGR led by Asia Pacific construction and transportation, with orthophthalic and liquid grades remaining the volume backbone through 2033. The strongest counter-argument is the 2.84% low-case view: if Chinese property construction stays subdued and styrene compliance costs accelerate substitution by thermoplastics, growth could halve. We weight that scenario at roughly 20% probability, because infrastructure and EV demand outside China offset property weakness.
Our analysis suggests the strategic fault line is not demand but capability: integrated producers with feedstock access and low-VOC portfolios will capture margin, while merchant blenders face compression. The KPS acquisition of INEOS Composites reinforces this — private capital is positioning for consolidation, not volume growth.
Actionable strategy:
Evidence that would change this conclusion: a sustained sub-5% Asia Pacific construction CAGR, or a regulatory ban on styrene in major markets, would shift us toward the low case and favor specialty isophthalic and non-styrene technologies.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.8% from 2020-2034 |
| Segmentation |
|
The global market is estimated at USD 15.0 billion in 2025, with consensus forecasts reaching USD 27.5 billion by 2033 at a 7.8% CAGR. Published estimates range from 2.84% to 8.3% CAGR depending on base year and scope definitions.
Asia Pacific leads with roughly 55% of global revenue, driven by infrastructure and automotive demand in China and India. North America and Europe each hold about 15%, concentrated in pipes, tanks, marine and wind applications.
Building and construction, fiberglass-reinforced plastics, tanks and pipes, marine and transportation are the primary applications. Construction accounts for the largest share, while marine is the fastest-growing application segment.
Leading vendors include INEOS Composites (now KPS-owned), Polynt, AOC Resins, BASF, Ashland, Hexion, UPC Group, Scott Bader and regional specialists such as Satyen Polymers and Eternal Materials.
Construction infrastructure spend, automotive lightweighting and EV composites, and corrosion-resistant tanks and pipes are the main drivers. Bio-based and low-VOC formulation is an emerging driver tied to sustainability regulation.
Volatile styrene and anhydride feedstock prices compress margins, while environmental rules on VOC emissions raise compliance costs. Epoxy, vinyl ester and thermoplastic composites also substitute in premium applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study relies on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and chemical producers, specialized UPR formulators and blenders, contract manufacturers, and global industrial distributors. Decision-maker designations interviewed include VP-level Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement economics, formulation performance and channel dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 35% |
| Technical Directors | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 40% |
| Specialized Formulators & Blenders | 35% |
| Contract Manufacturers | 15% |
| Distributors & Traders | 10% |
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized technical standards and industry associations. No competitor market-research publications were used as validation sources.
We ran simultaneous top-down (macroeconomic and end-use segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption) models. Divergences were reconciled at the grade and region level to produce a single base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |