 Bulgaria Commercial Vehicles Lubricants Market
 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 197

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Bulgaria Commercial Vehicles Lubricants Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 7.000 M |
| 2026 | 7.000 M |
| 2027 | 7.000 M |
| 2028 | 7.000 M |
| 2029 | 7.000 M |
| 2030 | 8.000 M |

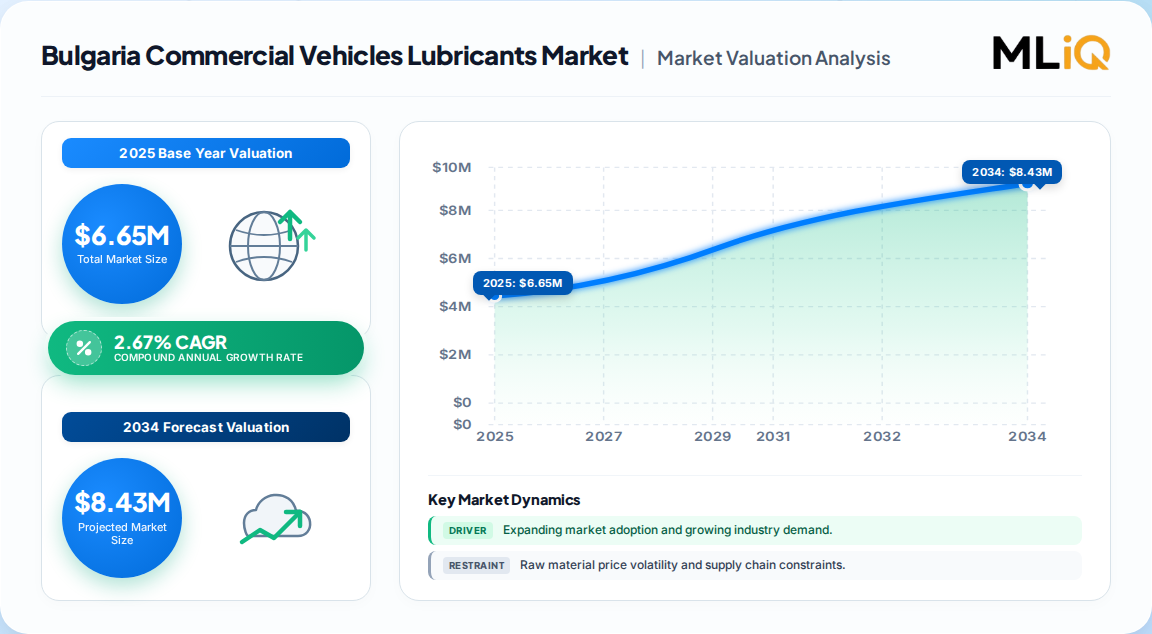
The Bulgaria Commercial Vehicles Lubricants Market covers engine oils, greases, hydraulic fluids and transmission & gear oils consumed by trucks, buses and vans across Bulgaria. It is measured in liters and shaped by long-haul freight intensity, an aging fleet and EU emission rules. In 2025, it stood at 6.65 million liters.
This report sizes and forecasts commercial-vehicle lubricants in Bulgaria by product type — engine oils, greases, hydraulic fluids, and transmission & gear oils — across LCV and M&HCV applications and OEM versus replacement channels. Volume is measured in liters over 2019–2030. It does not cover passenger-vehicle lubricants, two-wheeler lubricants, industrial lubricants, base-oil trading, or EV charging infrastructure.
The most defensible 2025 figure is 6.65 million liters, reaching 7.59 million liters by 2030. Two published estimates diverge on the surrounding automotive category, but only one directly sizes the CV lubricants segment — our analysis treats the CV-specific figure as the anchor and the broader automotive data as directional context.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 6.65 million liters → 7.59 million liters | 2025 | 2030 | 2.67% | Bulgaria CV lubricants, four product types | One published industry estimate |
| 30.73 million liters → 35.8 million liters | 2026 | 2031 | 3.12% | Bulgaria all automotive lubricants | A competing analysis |
| 6.47 million liters | 2024 | 2025 | n/a | Bulgaria CV lubricants historical base | Same CV-specific source |
The CV-specific series is internally consistent: 2024 at 6.47 million liters rising to 6.65 million in 2025 implies roughly 2.8% growth, close to the stated 2.67% CAGR. This divergence implies the CV segment is growing more slowly than passenger-vehicle lubricants because CV registration growth has cooled and service intervals are lengthening. Buyers should plan for low-single-digit volume growth, not a freight-led surge.
Engine oils are the volume anchor, while transmission and gear oils carry the fastest growth. The table below isolates non-geographic segmentation only.
| Parent segment | Children | Analytical note |
|---|---|---|
| By Product Type | Engine Oils, Greases, Hydraulic Fluids, Transmission & Gear Oils | Engine oils dominate on drain frequency; transmission & gear oils fastest-growing |
| By Vehicle Type | Light Commercial Vehicles, Medium & Heavy Commercial Vehicles | M&HCV drives premium heavy-duty engine oil demand |
| By Sales Channel | OEM Fill, Replacement / Aftermarket | Replacement dominates volume; OEM sets approval specifications |
Our analysis suggests the product mix is shifting modestly toward transmission and gear oils as post-2020 fleet renewal introduces newer gearboxes and automated manual transmissions requiring specialist friction modifiers. Engine oil remains the profit pool, but its share erodes slowly.
Sofia-Central leads because it concentrates the national freight dispatch base, warehouse hubs and the largest multi-brand workshop network. The nested tree below reflects corridor-driven consumption rather than administrative population.
| Region | Market Share (%) |
|---|---|
| Sofia-Central | 0.34% |
| South-Central | 0.22% |
| Southeast | 0.18% |
| Northeast | 0.15% |
| Northwest | 0.11% |
| Sub-region | Estimated share |
|---|---|
| Sofia-Central | 34% |
| South-Central | 22% |
| Southeast | 18% |
| Northeast | 15% |
| Northwest | 11% |
This distribution implies that route-to-market investment should follow the freight corridor, not regional GDP. A vendor underweight in Sofia-Central and South-Central is structurally disadvantaged in premium heavy-duty engine oils.
Freight intensity along the EU–Balkan corridor is the dominant positive force, adding roughly 1.2 percentage points to baseline growth. Counterweights — electrification, counterfeit imports and a shrinking two-wheeler parc — trim volume but do not reverse it.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Post-COVID EU–Balkan freight boom | Driver | High | Heavy trucks average ~129,500 km/year, raising drain frequency and fill volumes |
| Aging fleet and longer drain intervals | Driver | Medium | Older engines consume more top-up oil; synthetics raise volume per service |
| Euro 7 low-viscosity compliance | Driver | Medium | 0W-20/0W-30 adoption requires additive-rich formulations and OEM re-approval |
| Online DIY and gray-channel pricing | Driver | Low | Wider access to branded products, but margin pressure |
| BEV adoption in Sofia and Plovdiv | Restraint | Medium | Displaces engine oil demand in urban bus and van fleets |
| Counterfeit lubricants via gray imports | Restraint | Medium | Erodes branded volume in border and price-sensitive regions |
| Shrinking two-wheeler parc | Restraint | Low | Marginal effect on CV volumes |
The balance of evidence favors modest growth with mix upgrade. The critical second-order effect: Euro 7 forces reformulation and re-approval costs onto suppliers, which favors the consolidated top five and squeezes smaller blenders. Volume growth of 2.67% will not fund that re-tooling for sub-scale players, accelerating consolidation.
The market is fairly consolidated: the top five companies hold 88.63% of volume, and all five combine global approval portfolios with local distribution reach.
| Company | Positioning | Moat |
|---|---|---|
| Chevron Corporation | Global full-line supplier | OEM approvals and heavy-duty diesel credibility |
| ExxonMobil Corporation | Global full-line supplier | Brand strength and fleet contracts |
| Prista Oil | Domestic producer | Local blending, cost position and regional distribution |
| Royal Dutch Shell Plc | Global full-line supplier | Premium fleet positioning and Euro 7-ready portfolio |
| TotalEnergies | Global full-line supplier | Lubricant R&D and cross-border supply |
Our analysis suggests Prista Oil is the structural disruptor: domestic blending gives it a landed-cost advantage in price-sensitive replacement channels, while the four global players compete on OEM approval depth. The moat that matters most is documented Euro 7 and ACEA compliance — specification access, not marketing, determines fleet wins.
Fleet procurement in Bulgaria hinges on three criteria: OEM approval coverage, documented compatibility with after-treatment systems, and total cost per kilometer rather than per liter. Extended-drain synthetics reduce workshop visits but raise per-service volume and require strict oil-analysis discipline.
Procurement risk is concentrated in counterfeit and gray-import exposure, particularly in border regions. Buyers should demand traceable batch documentation and supplier certification. Switching costs rise with Euro 7 because a mis-specified low-viscosity oil can jeopardize warranty and emissions compliance, making re-approval a genuine barrier.
Operators should also model the electrification overlay: urban bus and van fleets in Sofia and Plovdiv are the first to shift to e-fluids, so conventional engine-oil volumes will migrate toward long-haul heavy-duty applications.
The balance of evidence favors a defend-and-upgrade strategy, not expansion. The Bulgaria CV lubricants market grows at 2.67% — below the 3.12% broader automotive rate — and 88.63% of volume sits with five players. The strongest counter-argument is a freight-led upside surprise: if EU–Balkan corridor volumes accelerate, heavy-duty drain frequency could push growth above 3%, but current registration trends do not support that base case.
Actionable strategy:
The conclusion would change if Bulgarian CV registrations return to 4%+ annual growth or if corridor freight volumes accelerate materially. Precise sub-segment forecasting by viscosity grade and OEM approval requires the full report's modeling.
The market stood at 6.65 million liters in 2025 and is forecast to reach 7.59 million liters by 2030 at a 2.67% CAGR. Engine oils are the largest product type, and the top five vendors hold 88.63% of volume.
Engine oils dominate because they require higher volumes and shorter drain intervals than greases, hydraulic fluids, or transmission and gear oils. They remain the profit anchor even as transmission and gear oils post the fastest growth following post-2020 fleet renewal.
Chevron Corporation, ExxonMobil Corporation, Prista Oil, Royal Dutch Shell Plc and TotalEnergies are the leading vendors, collectively holding 88.63% of volume. Prista Oil competes on domestic blending cost, while the global four compete on OEM approval depth and fleet contracts.
(See final section above.)
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.67% from 2020-2034 |
| Segmentation |
|
The market was estimated at 6.65 million liters in 2025. It is forecast to reach 7.59 million liters by 2030, growing at a 2.67% CAGR over the 2025–2030 period, driven by freight activity and an aging commercial fleet.
Engine oils are the largest product type because commercial vehicles require higher engine-oil volumes and shorter drain intervals than other lubricants. Transmission and gear oils are the fastest-growing segment as post-2020 fleet renewal introduces newer gearbox technologies.
Chevron Corporation, ExxonMobil Corporation, Prista Oil, Royal Dutch Shell Plc and TotalEnergies are the major players, holding 88.63% of the market. Prista Oil benefits from domestic blending, while global players lead on OEM approvals and fleet contracts.
Freight intensity along the EU–Balkan corridor is the main driver, with heavy trucks averaging around 129,500 km per year. An aging fleet, longer drain intervals and Euro 7 low-viscosity compliance also support volume and value growth.
BEV adoption in Sofia and Plovdiv, counterfeit lubricants via gray imports, and a shrinking two-wheeler parc restrain growth. Longer drain intervals from synthetic technology also reduce the annual volume of oil required per vehicle.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research follows a 70/30 primary-to-secondary split. We conducted in-depth interviews across the value chain with raw-material and base-oil suppliers, specialized lubricant blenders, contract formulators, and national distributors. Decision-maker designations included VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. Interviews examined drain-interval trends, OEM approval pipelines, and channel economics in Bulgaria's freight corridors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Base-Oil Suppliers | 30% |
| Specialized Blenders & Formulators | 40% |
| National Distributors & Traders | 30% |
We triangulated interview data against official multilateral databases — UN Comtrade, Eurostat, WTO and US ITC — alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and technical standards from ACEA, API and ISO. National statistics from Bulgaria's National Statistical Institute and the Bulgarian Industrial Association provided trade-flow validation for mineral fuel and lubricant categories.
We ran simultaneous Top-Down allocation from macroeconomic and freight-activity indicators and Bottom-Up modeling of blender capacity, product pricing and end-use consumption by vehicle class. The two approaches were reconciled at the product-type and channel level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Liters for 2025 | Bottom-up production & consumption triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Sub-regional share breakdown | Freight-corridor flow & workshop-density analysis | High |
| Competitive Landscape | Leading vendors | Annual reports, capacity mapping & filings | High |