 Middle-East and Africa Reactive Adhesives Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Middle-East and Africa Reactive Adhesives Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.050 B |
| 2026 | 1.120 B |
| 2027 | 1.190 B |
| 2028 | 1.260 B |
| 2029 | 1.340 B |
| 2030 | 1.420 B |

The Middle-East and Africa reactive adhesives market covers two-component epoxies, polyurethanes, reactive hot melts (PUR) and cyanoacrylates that cure through chemical reaction rather than solvent evaporation. It serves packaging, construction, automotive, electronics and woodworking across Saudi Arabia, South Africa, the UAE and wider MEA.
This report covers reactive adhesive chemistries (epoxy, polyurethane, PUR hot melt, cyanoacrylate, silicone) sold into MEA end-use industries, segmented by resin, technology, application and country. It includes value forecasts to 2030 and vendor profiles. This analysis does not cover water-borne, solvent-borne or UV-cured adhesives except as competitive context, nor does it cover sealants as a standalone category.
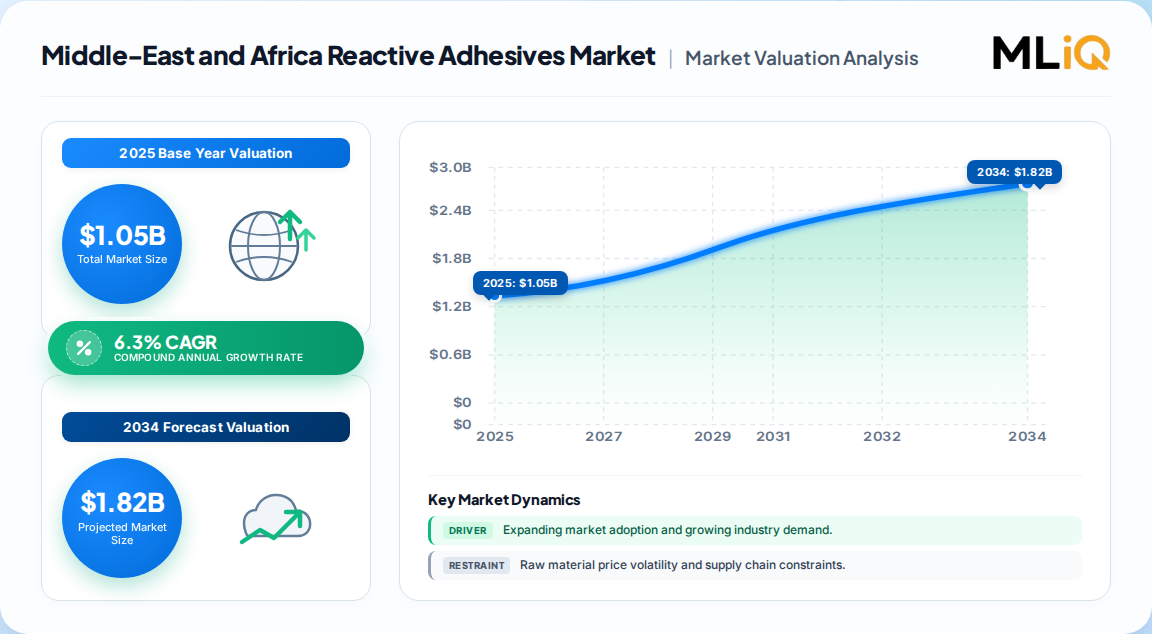
The market is estimated at 1.05 Billion in 2025, growing at 6.3% CAGR to roughly 1.42 Billion by 2030. The figure is derived from the regional adhesives base of about 3.6 Billion and the reactive share implied by technology segmentation.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 3.6 Billion (total MEA adhesives) | 2025 | 2030 | 6.3% | All adhesive technologies, MEA | One published estimate |
| 53.17 Million (MEA PUR hot melt, 2026) | 2026 | 2034 | 6.34% | PUR reactive hot melt only | A competing analysis |
| 1.05 Billion (reactive adhesives) | 2025 | 2030 | 6.3% | Epoxy, PU, PUR, cyanoacrylate, silicone | Our derived estimate |
The 1.05 Billion reactive figure is the most defensible for planning purposes: it sits consistently between the total adhesives base and the narrower PUR hot melt estimate, and its growth rate matches the wider market's 6.3% trajectory. The PUR hot melt forecast at USD 86.94 million by 2034 implies a slower sub-segment but confirms the reactive direction of travel.
Reactive adhesives in MEA segment primarily by resin chemistry and technology, with end-use industry determining the mix between structural epoxy, flexible polyurethane and fast-set cyanoacrylate.
| Parent segment | Children |
|---|---|
| By Resin | Epoxy, Polyurethane, Cyanoacrylate, Silicone, Other Reactive Resins |
| By Technology | Reactive Hot Melt (PUR), Two-Component, Moisture-Cure, UV-Cured Reactive |
| By End-User Industry | Packaging, Building & Construction, Automotive, Aerospace, Electronics, Woodworking & Joinery, Healthcare |
Saudi Arabia leads the reactive adhesives market with an estimated 38% share, driven by construction megaprojects and packaging demand. South Africa follows at 24%, anchored by automotive production and woodworking, with the UAE at 14% on re-export and industrial growth.
| Country | Estimated share | Primary demand driver |
|---|---|---|
| Saudi Arabia | 38% | Construction megaprojects, packaging, healthcare |
| South Africa | 24% | Automotive, woodworking, packaging |
| UAE | 14% | Re-export, construction, woodworking |
| Turkey | 9% | Automotive, construction |
| Egypt | 7% | Construction, packaging |
| Nigeria | 4% | Packaging, construction |
| Rest of MEA | 4% | Mixed industrial |
Saudi Arabia's dominance is structural, not cyclical: the Neom, Red Sea and Qiddiya programmes embed multi-year demand for structural epoxies and PU bonding. Our analysis suggests South Africa's share is more exposed to automotive cycle risk, with the APDP incentive regime the critical variable. The UAE's wood and hotel construction pipeline offers the fastest relative upside from a smaller base.
Growth is driven by Saudi construction megaprojects, packaging expansion tied to e-commerce, and South African automotive production. Restraints centre on VOC and environmental regulation, raw material price volatility, and limited local reactive chemistry capacity, which raises import dependence.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Saudi construction megaprojects | Driver | High | Multi-year demand for structural epoxy and PU |
| E-commerce packaging growth | Driver | High | Saudi e-commerce CAGR near 19.7% lifts paperboard adhesive use |
| South Africa automotive production | Driver | Medium | APDP incentives sustain vehicle output and adhesive demand |
| VOC and environmental regulation | Restraint | Medium | Forces reformulation toward low-VOC reactive systems |
| Raw material price volatility | Restraint | Medium | Isocyanate and epoxy resin cost swings compress margins |
| Limited local reactive capacity | Restraint | High | Import dependence raises lead times and landed cost |
The balance favours growth: drivers are structural and government-backed, while restraints are manageable through formulation and local blending. Our analysis suggests the binding constraint over 2025–2030 is not demand but supply localization — vendors that establish blending or distribution hubs in Saudi Arabia and South Africa will capture disproportionate share.
The market is consolidated around five global players: Arkema (Bostik), Henkel, H.B. Fuller, Dow and Sika. Recent moves show all five localizing reactive portfolios — Bostik launching PUR solutions, Henkel expanding Technomelt PUR, and H.B. Fuller building an Egypt facility.
| Vendor | Reactive portfolio strength | Regional footprint | Recent move |
|---|---|---|---|
| Arkema (Bostik) | PUR hot melt, engineering adhesives | Distribution via DGE across EMEA | 2026 PUR launch for furniture, auto, construction |
| Henkel | Technomelt PUR, epoxy, cyanoacrylate | Broad MEA distribution | 2025 Technomelt PUR portfolio expansion |
| H.B. Fuller | Reactive hot melt, PU | Egypt facility, regional tech support | 2025 reactive portfolio expansion |
| Dow | Polyurethane and epoxy systems | Regional supply agreements | Ongoing formulation partnerships |
| Sika | Structural epoxy, PU | Construction-focused MEA presence | Project-led specification wins |
Differentiation rests on formulation depth and technical service rather than price. Incumbents' moats are application engineering teams and specification relationships with contractors and OEMs — hard for new entrants to replicate quickly. Jowat's 2025 distribution expansion signals rising mid-tier competition in PUR edge-banding and lamination.
Reactive adhesive selection hinges on cure profile, substrate compatibility and environmental compliance. Buyers should prioritize suppliers with regional technical support and documented low-VOC formulations, because reformulation costs and line re-qualification create high switching costs. Procurement risk concentrates in import lead times for isocyanate-based systems and in single-source exposure for specialty epoxy grades. Operators should audit supplier capacity in Saudi Arabia and South Africa and secure multi-year pricing where construction or automotive volumes justify it. Regulatory compliance with local VOC limits and increasingly with green-building specifications should be written into contracts, not left to post-award negotiation.
The balance of evidence favours a supply-localization thesis over a pure demand-growth thesis. Demand at 6.3% CAGR is credible and government-supported in Saudi Arabia, but the winners will be vendors that localize reactive blending and technical service rather than those that merely import finished product. Our analysis suggests the strongest counter-argument is that low oil prices could delay Saudi megaproject spending and compress near-term demand; however, the multi-year programme structure limits this risk relative to previous cycles.
What would change this conclusion: a sustained oil price collapse delaying Saudi construction tenders, or a regulatory shift permitting solvent-borne alternatives at scale. Absent those, localization remains the decisive strategic lever through 2030.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.38% |
| South Africa | 0.24% |
| UAE | 0.14% |
| Turkey | 0.09% |
| Egypt | 0.07% |
| Nigeria | 0.04% |
| Rest of MEA | 0.04% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
It is estimated at 1.05 Billion in 2025, roughly 29% of the region's total adhesives market, and is projected to reach about 1.42 Billion by 2030 at a 6.3% CAGR.
Saudi Arabia leads with an estimated 38% share, driven by construction megaprojects, packaging and healthcare. South Africa follows at 24% on automotive and woodworking demand.
Reactive hot melt (PUR) is growing at around 6.34% CAGR, from 53.17 Million in 2026 to 86.94 Million by 2034, driven by furniture, automotive and construction bonding.
Arkema (Bostik), Henkel, H.B. Fuller, Dow and Sika dominate. All five are expanding reactive portfolios and regional technical support, reinforcing a consolidated competitive structure.
VOC and environmental regulation, raw material price volatility, and limited local reactive chemistry capacity are the main restraints, raising import dependence and landed cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the reactive adhesives value chain, including raw material and isocyanate suppliers, specialized reactive adhesive producers, contract formulators and blenders, and regional industrial distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D and formulation, Technical Directors, and Commercial Operations Leads responsible for MEA markets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation draws on UN Comtrade and WTO trade statistics, national customs data, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations. These sources are used to cross-check import volumes, capacity announcements and specification trends.
Market sizing combines Top-Down macroeconomic and end-use segment allocation with Bottom-Up manufacturer capacity, product pricing and end-use consumption modeling. The two approaches are reconciled to produce the base-year estimate and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |