Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Packaging Printing Market by Printing Technology (Flexography, Rotogravure, Offset Lithography, Digital, Hybrid), by Ink Type (Solvent-based, Water-based, UV-curable, Bio-based), by Packaging Type (Labels, Flexible Packaging, Corrugated, Folding Cartons, Rigid Containers, Metal Cans), by End-Use (Food & Beverage, Pharmaceutical & Healthcare, Personal Care & Cosmetics, Industrial, Others), by Asia Pacific (China, Japan, India, South Korea, Indonesia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Poland), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
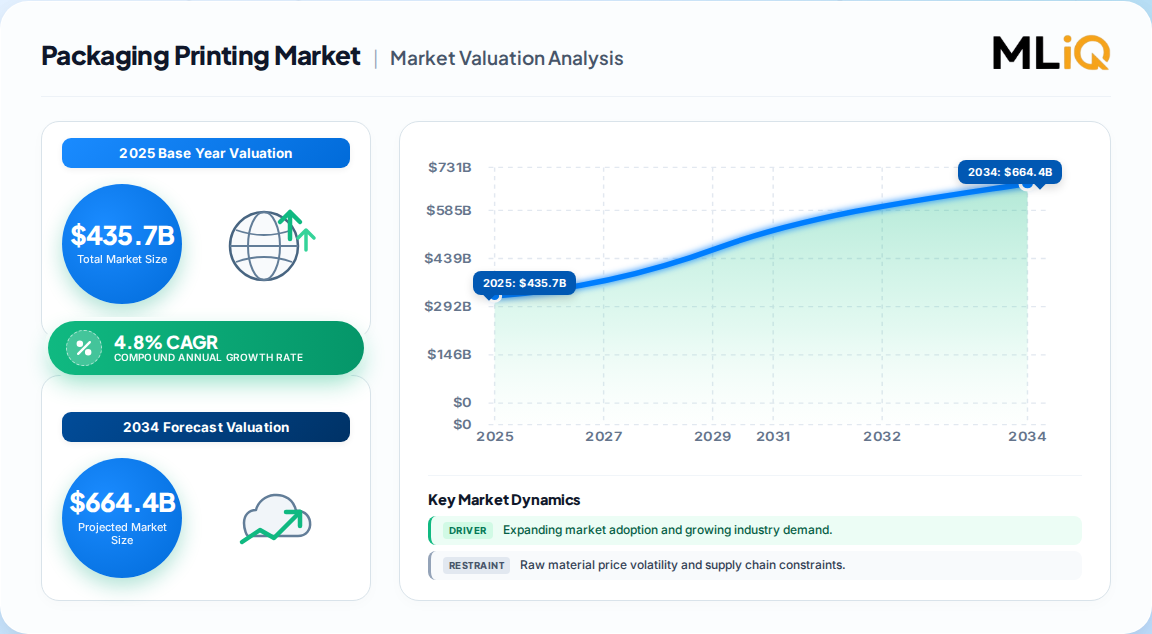
435.7 Billion USD — the global packaging printing market size in 2025, with a base-case forecast of 690.6 Billion USD by 2035 at a 4.8% CAGR (2026–2035).
Flexography remains the volume anchor, commanding roughly 36% of print value, while digital is the fastest-growing technology at a double-digit CAGR off a small base.
Asia-Pacific leads with approximately 41% of global value, ahead of North America (~22%) and Europe (~21%); Middle East & Africa is the fastest-growing region.
Food & beverage is the largest end-use (~35–41% depending on definition), with pharmaceuticals the fastest-growing application (~6.9% CAGR) on serialization mandates.
Labels and flexible packaging lead product formats (~31% and ~28% respectively); flexible pouches grow fastest within packaging type.
Amcor plc leads with >13% share; the top five converters (Amcor, Avery Dennison, CCL Industries, DS Smith, International Paper) hold ~44% between them.
Why this matters for decision-makers: growth is no longer won on press capacity alone — the compounding value pool is information-rich, regulation-compliant print (serialized pharma, e-commerce corrugated, traceability), so converters who cannot link artwork, variable-data, and inline verification will see margin compression against hybridized competitors.
Packaging Printing Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
435.7 B
2025
452.5 B
2026
474.2 B
2027
497.0 B
2028
520.8 B
2029
545.8 B
2030
572.0 B
2031
Packaging Printing Market Size (In Billion)
Year
Market Size
2025
435.7 B
2026
452.5 B
2027
474.2 B
2028
497.0 B
2029
520.8 B
2030
545.8 B
2031
572.0 B
What is the Packaging Printing Market?
The packaging printing market covers the commercial printing of primary and secondary packaging — labels, cartons, flexible films, corrugated boxes, and metal/plastic containers — using flexography, gravure, offset lithography, digital, and hybrid technologies. It is the value of ink-on-substrate work delivered to brand owners and converters, not the price of the packaging material itself. In 2025 it was worth roughly 435.7 billion USD globally.
Scope: what this report covers and excludes
This report covers global print value for packaging applications across food, beverage, pharmaceutical, personal care, and industrial end-uses, split by printing technology, ink type, packaging type, and geography. It measures the value of printing services and consumables conversion, not downstream packaged-goods revenue. This analysis does not cover packaging-converting machinery capex, pure label-converting equipment sales, or non-print decoration such as in-mold labeling tooling.
How big is the market for Packaging Printing Market?
Published estimates disagree by an order of magnitude — one houses the market in the hundreds of billions, another near a single-digit billion. That spread is a definitional artifact, not genuine volatility, and buyers should anchor on the billions-scale series. See the comparison below.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
435.7 Billion
2025
2035
4.8%
Global print value, all technologies and packaging formats
One published estimate
437.78 Billion
2025
2031
7.9%
Global print value, slightly broader ink/carton coverage
Competing analysis
548.89 Billion
2025
2032
4.5%
Broader definition including some printed media
Alternative house estimate
443.1 Million
2025
2033
10.4%
Narrow subset, apparently labels-only reporting base
One published estimate
Our analysis suggests the 435–470 billion band is the most defensible base, because it reconciles with independent trade benchmarks: flexographic and gravure printing alone were placed near 347.6 billion in 2025, and digital print for packaging near 22.0 billion. The 443.1 million "market" figure is a reporting-base error — a valid label sub-segment scaled as if global. The low-to-mid single-digit CAGR range (4.5–4.8%) is also more consistent with mature volume growth plus a modest premiumization mix shift than with the 7.9–10.4% outliers.
How is the market segmented?
Segmentation is best read on four non-geographic axes — technology, ink chemistry, packaging format, and end-use — because value pools and growth rates diverge sharply across each. Flexography and solvent inks dominate current value; digital and UV-curable inks carry the growth.
Labels, Flexible Packaging, Corrugated, Folding Cartons, Rigid Containers, Metal Cans
Labels ~30.6%
Flexible pouches ~8.8% CAGR
By End-Use
Food & Beverage, Pharmaceutical & Healthcare, Personal Care & Cosmetics, Industrial, Others
Food & Beverage ~29–41%
Pharmaceuticals ~6.9% CAGR
Which region leads in Packaging Printing Market?
Asia-Pacific leads the global packaging printing market, holding roughly 41% of value in 2025 on the back of Chinese e-commerce volumes, Indian FMCG expansion, and low-cost conversion capacity. North America and Europe follow in a near tie, with the Middle East & Africa the fastest-growing region from a small base.
Packaging Printing Market Regional Market Share
Loading chart...
Packaging Printing Market Regional Market Share
Region
Market Share (%)
North America
0.22%
Europe
0.21%
Asia-Pacific
0.41%
South America
0.08%
Middle East & Africa
0.08%
Global
Asia-Pacific (~41%)
China, India, Japan, South Korea, Indonesia
North America (~22%)
United States, Canada, Mexico
Europe (~21%)
Germany, UK, France, Italy, Poland
South America (~8%)
Brazil, Argentina, Colombia
Middle East & Africa (~8%)
Saudi Arabia, UAE, South Africa
Region
Share (2025)
Growth posture
Asia-Pacific
41%
Volume leader; fastest large-region growth
North America
22%
Mature; on-demand micro-factory shift
Europe
21%
Regulation-led; PPWR compliance premium
South America
8%
Near-shoring beneficiary
Middle East & Africa
8%
Fastest CAGR (~9.2%), sovereign investment
What is driving growth — and what is holding it back?
Growth is driven by e-commerce volume, SKU proliferation, regulatory labeling, and premiumization, and restrained by input-cost volatility and digital-equipment capex. The net effect is a moderate 4.8% CAGR with a widening gap between volume and information-rich print.
Factor
Direction
Evidence strength
Mechanism
E-commerce packaging volumes
Driver
Strong
+~2.1pp; corrugated and flexible print demand
Regulatory labeling & serialization
Driver
Strong
+~0.9–1.8pp; pharma serialization, PPWR on-pack info
SKU proliferation / short runs
Driver
Strong
+~0.8pp; shifts mix toward digital and hybrid
Premiumization
Driver
Moderate
+~0.7pp; gravure and HD flexo in cosmetics/beverage
Sustainable ink transition
Driver / cost
Moderate
+~0.6pp demand; raises per-kg ink cost
Raw-material price volatility
Restraint
Moderate
-~0.5pp; resin, pigment, substrate procurement
Digital/hybrid equipment capex
Restraint
Moderate
-~0.3pp; barriers for small converters
The balance favors incumbents with capital to automate, but the composition of growth is shifting. Our analysis suggests the compliance-driven floor (serialized pharma, mandatory labeling) gives the market unusual recession resilience — brand-led graphics can be deferred, but regulated print cannot, which is why the 4.8% base case is more defensible than either the pessimist or optimist tails.
Who are the leading vendors?
Amcor plc leads with over 13% share, and the top five converters together hold about 43.6% of global value. The competitive set is medium-concentration: no single vendor exceeds pricing power, but the leaders combine substrate breadth, color management, and regulatory qualification that smaller converters cannot easily replicate.
Company
Approx. position
Strategic differentiator
Amcor plc
Leader, >13% share
Global scale, recyclable and healthcare packaging
Avery Dennison
Top 5
Label science and RFID-enabled smart labels
CCL Industries
Top 5
Label and specialty printing depth
DS Smith
Top 5
Corrugated and e-commerce packaging
International Paper
Top 5
Fiber-based industrial and consumer board
Mondi Group
Challenger
Fiber-based portfolio and digital print capability
Smurfit WestRock
Challenger
Corrugated scale and integrated conversion
The real moat is workflow integration, not press capacity: leaders are wiring artwork control, color management, and inline verification into a single qualified process, which raises switching costs for regulated brand owners.
What do buyers and operators need to know?
Procurement decisions should be weighted toward qualification and compliance, not headline print price. In pharmaceutical and food applications, an on-pack code that fails verification is a production-critical failure, so converters must evidence inline barcode inspection, color consistency, and substrate compatibility in the tender, not after award. Regulatory churn — notably the EU Packaging and Packaging Waste Regulation entering application in 2026 — is rewiring on-pack information requirements, so buyers should lock in vendors who can absorb artwork changes without re-qualification delays.
Switching costs are asymmetric. Moving a stable long-run job from gravure to flexo is straightforward; moving a serialized pharma pack to a new converter triggers revalidation, regulatory notification, and code-verification proof — often months of effort. Conversely, high-capex digital and hybrid equipment creates lock-in risk for small converters who may struggle to finance upgrades. The practical implication: buyers should negotiate change-control provisions and versioning SLAs, while operators should prioritize workforce and workflow readiness over press count. Precise sub-segment capex economics and country-level qualification timelines sit outside this executive summary.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the 4.8% base case with a compliance floor and a digital growth tail, not the double-digit or sub-5% tails. The strongest counter-argument is that digital substitution could accelerate faster than expected — if hybrid lines remove changeover costs at scale, conventional volume could erode quicker than the base case assumes. That is a real risk, but the 2025 evidence (digital still ~22 billion against ~348 billion conventional) suggests hybridization, not replacement, is the near-term path.
Actionable strategy for investors and operators:
Converters: prioritize hybrid flexo-digital lines and inline verification to capture serialized pharma and e-commerce corrugated work, where price pressure is lowest.
Brand owners: tender print contracts on qualification speed and versioning SLAs, not unit price, to protect against regulatory artwork churn.
Equipment and ink suppliers: bundle color management and compliance workflows with hardware to defend margin against commoditizing press sales.
What would change our conclusion: a sustained digital CAGR above 15% combined with falling hybrid capex would justify a more aggressive substitution thesis, and could pull the base-case CAGR above 6%. Absent that, the market rewards execution on compliance and workflow, not capacity.
Packaging Printing Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Packaging Printing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.8% from 2020-2034
Segmentation
By Printing Technology
Flexography
Rotogravure
Offset Lithography
Digital
Hybrid
By Ink Type
Solvent-based
Water-based
UV-curable
Bio-based
By Packaging Type
Labels
Flexible Packaging
Corrugated
Folding Cartons
Rigid Containers
Metal Cans
By End-Use
Food & Beverage
Pharmaceutical & Healthcare
Personal Care & Cosmetics
Industrial
Others
By Geography
Asia Pacific
China
Japan
India
South Korea
Indonesia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Poland
South America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Packaging Printing Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Packaging Printing Market Executive Summary
2.1. Market Snapshot
3. Packaging Printing Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Packaging Printing Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Packaging Printing Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Printing Technology
5.1.1. Flexography
5.1.2. Rotogravure
5.1.3. Offset Lithography
5.1.4. Digital
5.1.5. Hybrid
5.2. Analysis, Insights and Forecast - by Ink Type
5.2.1. Solvent-based
5.2.2. Water-based
5.2.3. UV-curable
5.2.4. Bio-based
5.3. Analysis, Insights and Forecast - by Packaging Type
5.3.1. Labels
5.3.2. Flexible Packaging
5.3.3. Corrugated
5.3.4. Folding Cartons
5.3.5. Rigid Containers
5.3.6. Metal Cans
5.4. Analysis, Insights and Forecast - by End-Use
5.4.1. Food & Beverage
5.4.2. Pharmaceutical & Healthcare
5.4.3. Personal Care & Cosmetics
5.4.4. Industrial
5.4.5. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. South America
5.5.5. Middle East & Africa
6. Packaging Printing Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Printing Technology
6.1.1. Flexography
6.1.2. Rotogravure
6.1.3. Offset Lithography
6.1.4. Digital
6.1.5. Hybrid
6.2. Analysis, Insights and Forecast - by Ink Type
6.2.1. Solvent-based
6.2.2. Water-based
6.2.3. UV-curable
6.2.4. Bio-based
6.3. Analysis, Insights and Forecast - by Packaging Type
6.3.1. Labels
6.3.2. Flexible Packaging
6.3.3. Corrugated
6.3.4. Folding Cartons
6.3.5. Rigid Containers
6.3.6. Metal Cans
6.4. Analysis, Insights and Forecast - by End-Use
6.4.1. Food & Beverage
6.4.2. Pharmaceutical & Healthcare
6.4.3. Personal Care & Cosmetics
6.4.4. Industrial
6.4.5. Others
7. Packaging Printing Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Printing Technology
7.1.1. Flexography
7.1.2. Rotogravure
7.1.3. Offset Lithography
7.1.4. Digital
7.1.5. Hybrid
7.2. Analysis, Insights and Forecast - by Ink Type
7.2.1. Solvent-based
7.2.2. Water-based
7.2.3. UV-curable
7.2.4. Bio-based
7.3. Analysis, Insights and Forecast - by Packaging Type
7.3.1. Labels
7.3.2. Flexible Packaging
7.3.3. Corrugated
7.3.4. Folding Cartons
7.3.5. Rigid Containers
7.3.6. Metal Cans
7.4. Analysis, Insights and Forecast - by End-Use
7.4.1. Food & Beverage
7.4.2. Pharmaceutical & Healthcare
7.4.3. Personal Care & Cosmetics
7.4.4. Industrial
7.4.5. Others
8. Packaging Printing Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Printing Technology
8.1.1. Flexography
8.1.2. Rotogravure
8.1.3. Offset Lithography
8.1.4. Digital
8.1.5. Hybrid
8.2. Analysis, Insights and Forecast - by Ink Type
8.2.1. Solvent-based
8.2.2. Water-based
8.2.3. UV-curable
8.2.4. Bio-based
8.3. Analysis, Insights and Forecast - by Packaging Type
8.3.1. Labels
8.3.2. Flexible Packaging
8.3.3. Corrugated
8.3.4. Folding Cartons
8.3.5. Rigid Containers
8.3.6. Metal Cans
8.4. Analysis, Insights and Forecast - by End-Use
8.4.1. Food & Beverage
8.4.2. Pharmaceutical & Healthcare
8.4.3. Personal Care & Cosmetics
8.4.4. Industrial
8.4.5. Others
9. Packaging Printing Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Printing Technology
9.1.1. Flexography
9.1.2. Rotogravure
9.1.3. Offset Lithography
9.1.4. Digital
9.1.5. Hybrid
9.2. Analysis, Insights and Forecast - by Ink Type
9.2.1. Solvent-based
9.2.2. Water-based
9.2.3. UV-curable
9.2.4. Bio-based
9.3. Analysis, Insights and Forecast - by Packaging Type
9.3.1. Labels
9.3.2. Flexible Packaging
9.3.3. Corrugated
9.3.4. Folding Cartons
9.3.5. Rigid Containers
9.3.6. Metal Cans
9.4. Analysis, Insights and Forecast - by End-Use
9.4.1. Food & Beverage
9.4.2. Pharmaceutical & Healthcare
9.4.3. Personal Care & Cosmetics
9.4.4. Industrial
9.4.5. Others
10. Packaging Printing Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Printing Technology
10.1.1. Flexography
10.1.2. Rotogravure
10.1.3. Offset Lithography
10.1.4. Digital
10.1.5. Hybrid
10.2. Analysis, Insights and Forecast - by Ink Type
10.2.1. Solvent-based
10.2.2. Water-based
10.2.3. UV-curable
10.2.4. Bio-based
10.3. Analysis, Insights and Forecast - by Packaging Type
10.3.1. Labels
10.3.2. Flexible Packaging
10.3.3. Corrugated
10.3.4. Folding Cartons
10.3.5. Rigid Containers
10.3.6. Metal Cans
10.4. Analysis, Insights and Forecast - by End-Use
Table 5: Packaging Printing Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Asia Pacific Packaging Printing Market Revenue Billion Forecast, by Printing Technology 2020 & 2034
Table 7: Asia Pacific Packaging Printing Market Revenue Billion Forecast, by Ink Type 2020 & 2034
Table 8: Asia Pacific Packaging Printing Market Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 9: Asia Pacific Packaging Printing Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 10: Asia Pacific Packaging Printing Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: China Packaging Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Japan Packaging Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: India Packaging Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: South Korea Packaging Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Indonesia Packaging Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: North America Packaging Printing Market Revenue Billion Forecast, by Printing Technology 2020 & 2034
Frequently Asked Questions
1. How big is the packaging printing market in 2025?
The global packaging printing market was valued at approximately 435.7 billion USD in 2025. Estimates vary by definition, but trade benchmarks for flexographic and gravure printing support the hundreds-of-billions scale rather than narrower reporting bases.
2. What is the packaging printing market growth rate?
The market is forecast to grow at about 4.8% CAGR between 2026 and 2035, reaching roughly 690.6 billion USD by 2035. Digital printing grows faster at double digits but from a small base, so the blended rate stays moderate.
3. Which printing technology dominates packaging printing?
Flexography remains the largest technology by value, with roughly 36% share in 2025, because it combines throughput with broad ink and substrate options. Digital printing is the fastest-growing but still a comparatively small share of total print value.
4. Which region leads the packaging printing market?
Asia-Pacific leads with approximately 41% of global value, driven by Chinese e-commerce and Indian FMCG expansion. The Middle East & Africa is the fastest-growing region, and North America and Europe follow in a near tie.
5. Who are the leading companies in packaging printing?
Amcor plc leads with over 13% share in 2025. The top five — Amcor, Avery Dennison, CCL Industries, DS Smith, and International Paper — collectively hold about 43.6% of the market, indicating medium concentration.
6. What is driving the packaging printing market?
E-commerce packaging volumes are the strongest driver, followed by regulatory labeling and serialization, SKU proliferation, and premiumization. Sustainability requirements also reshape ink and substrate choice, though they raise per-unit costs.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This analysis rests on a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews with stakeholders across the packaging printing value chain: ink and substrate suppliers, specialized converters and printers, hybrid equipment integrators, and global distribution partners. Interviewees were drawn from decision-maker roles including VP of Sourcing, Heads of R&D and Print Technology, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives on qualification, changeover economics, and compliance.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement VPs
35%
R&D & Print Technology Heads
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ink & Substrate Suppliers
40%
Specialized Converters & Printers
35%
Hybrid Equipment Integrators
15%
Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral databases — UN Comtrade, WTO trade statistics, US ITC, and Eurostat — alongside corporate annual filings (10-K and investor presentations), patent databases, and recognized non-profit technical standards and industry associations. These sources anchor volume, trade-flow, and capacity assumptions without reliance on any competitor research publisher.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic and industry-segment output to print value using consumption shares; the bottom-up path models manufacturer capacity, product pricing, and end-use consumption. Divergences are reconciled at the technology-format matrix level.


 Packaging Printing Market