 Spain Passenger Vehicles Lubricants Industry
 market 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 197


Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Spain Passenger Vehicles Lubricants Industry
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 83.00 M |
| 2025 | 85.00 M |
| 2026 | 87.00 M |
| 2027 | 89.00 M |
| 2028 | 91.00 M |
| 2029 | 93.00 M |
| 2030 | 95.00 M |

The Spain Passenger Vehicles Lubricants Industry market measures the volume of finished lubricants consumed by passenger cars in Spain, segmented into engine oils, greases, hydraulic fluids, and transmission and gear oils. It captures workshop servicing, aftermarket top-ups, and light-vehicle maintenance demand across the national vehicle parc.
This analysis covers finished lubricant volumes for passenger cars registered and serviced in Spain, segmented by product type: engine oils, greases, hydraulic fluids, and transmission and gear oils. It addresses both the aftermarket and workshop channels. This analysis does not cover commercial vehicle lubricants, industrial oils, marine lubricants, base-oil trading, or raw additive supply.
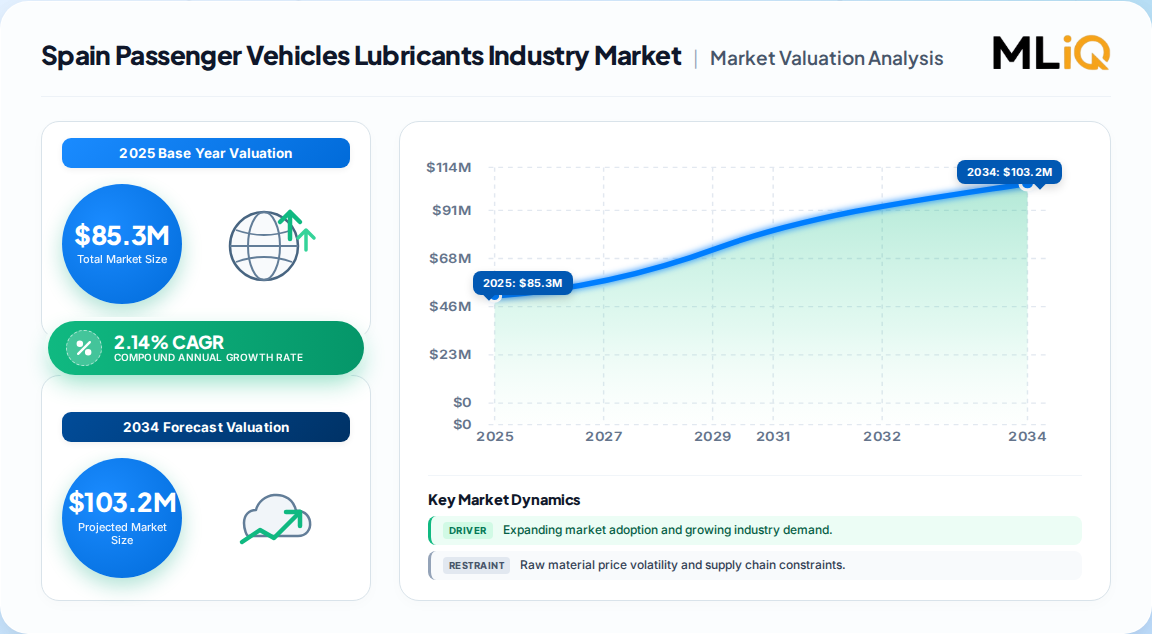
One published estimate places the market at 85.30 million liters in 2025, rising to 94.82 million liters by 2030 at a 2.14% CAGR. A second estimate for 2024 puts volume at 83.47 million liters, which is consistent with the same trajectory once the 2025 recovery is applied.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 85.30 million liters | 2025 | 2030 (94.82 million liters) | 2.14% | Passenger vehicle lubricants by volume, Spain | One published estimate |
| 83.47 million liters | 2024 | Historical | n/a | Passenger vehicle lubricants by volume, Spain | Same publisher, prior-year base |
The two figures are internally consistent: 83.47 million liters in 2024 lifting to 85.30 million liters in 2025 implies roughly 2.2% year-on-year growth, exactly in line with the forecast CAGR. Our analysis suggests the 85.30 million liter base is the most defensible planning anchor because it aligns with the stated horizon and the observed post-pandemic recovery path. Any higher figure would require either a materially larger active parc or shorter drain intervals than the published service data supports.
The market is segmented by product type, with engine oils dominant by volume and hydraulic fluids the fastest-growing segment. Transmission and gear oils and greases complete the product mix, with demand concentrated in workshop servicing and scheduled maintenance.
| Parent segment | Children | Volume role |
|---|---|---|
| Product Type | Engine Oils, Greases, Hydraulic Fluids, Transmission & Gear Oils | Engine oils largest; hydraulic fluids fastest-growing |
Engine oils carry the largest volume because every passenger car requires a full fill and periodic drain, and the segment serves high-temperature, high-pressure engine applications. Greases and transmission and gear oils are lower-volume but higher-margin, tied to scheduled servicing and drivetrain maintenance. Our analysis suggests the fastest growth in hydraulic fluids reflects trade and light-commercial spillover rather than a structural shift in passenger-car demand.
Catalonia leads regional demand and distribution, combining automotive production, port-linked commerce, and high distributor density. Madrid and Andalusia follow, reflecting vehicle density and workshop concentration.
| Region | Market Share (%) |
|---|---|
| Catalonia | 0.22% |
| Madrid | 0.18% |
| Andalusia | 0.16% |
| Valencia | 0.12% |
| Basque Country | 0.08% |
| Galicia | 0.07% |
| Castile and León | 0.09% |
| Rest of Spain | 0.08% |
Catalonia's role extends beyond consumption: it acts as a distribution hub for northern and eastern Spain, supporting shorter delivery routes and higher technical-sales activity. Our analysis suggests regional share is more a function of distribution economics than of vehicle parc alone, which is why a distributor's Catalonia position matters disproportionately to national volume.
Growth is driven by an aging vehicle parc, workshop servicing demand, and a rebound in passenger vehicle sales after 2020. Restraints include electrification, longer drain intervals, and a still-fragile new-car market.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Aging parc and servicing | Driver | High | Older cars require more frequent maintenance and top-ups |
| Passenger vehicle sales recovery | Driver | Medium | Supports new fills and aftermarket demand |
| Trade and logistics activity | Driver | Medium | Supports hydraulic fluid demand |
| Electrification | Restraint | Medium | Reduces engine-oil intensity per vehicle |
| Longer drain intervals | Restraint | High | Lowers liters per vehicle per year |
| Synthetic premiumization | Mixed | High | Lowers volume but raises value per liter |
The balance favors moderate volume growth, not expansion. Our analysis suggests the 2.14% CAGR is best read as a mix effect: the parc still needs servicing, but each vehicle consumes slightly less oil per year. That divergence implies volume-led strategies will underperform value-led strategies over the forecast period.
The market is fairly consolidated, with the top five vendors holding 81.69% of volume. BP (Castrol), CEPSA, ExxonMobil, Repsol, and Shell anchor the competitive landscape, alongside specialists such as FUCHS, TotalEnergies, Eni, Chevron, and Galp.
| Vendor | Position | Differentiation focus |
|---|---|---|
| BP (Castrol) | Top five | Brand strength, OEM approvals, workshop programs |
| CEPSA | Top five | Domestic refining integration, Iberian distribution |
| ExxonMobil | Top five | Synthetic technology, global OEM relationships |
| Repsol | Top five | Domestic brand loyalty, retail and workshop reach |
| Shell | Top five | Premium synthetics, global technical backing |
| FUCHS, TotalEnergies, Eni, Chevron, Galp | Challengers | Niche approvals, OEM tie-ups, regional coverage |
Differentiation rests on OEM approvals, workshop loyalty programs, and distribution reach rather than price alone. Our analysis suggests the moat is approval-based: first-fill and recommendation agreements with Stellantis-linked brands and other OEMs create recurring aftermarket pull that challengers cannot easily replicate.
Buyers should prioritize OEM approvals and specification compliance over headline price, because a non-approved lubricant can void warranty coverage and damage modern engines. Procurement risk is concentrated in base-oil cost volatility and in distributor concentration in Catalonia and Madrid. Switching costs are moderate for bulk buyers but high for workshops locked into branded service programs. Regulatory compliance with Euro 6-era emissions and low-viscosity requirements is non-negotiable for fleet and workshop operators.
The balance of evidence favors a value-led strategy over a volume-led one. Volume CAGR of 2.14% is modest and partly structural, constrained by electrification and longer drain intervals. Suppliers that compete on liters will face margin compression; those that compete on approvals, synthetics, and workshop control will capture the value growth implied by premiumization.
The strongest counter-argument is that a faster-than-expected recovery in new-car sales could lift aftermarket volume above forecast, particularly if the parc ages further before electrification scales. That is plausible but not sufficient to change the direction of the mix shift.
Evidence that would change this conclusion: a sustained rise in average drain intervals reversing, or a policy-driven acceleration in hybrid servicing demand that lifts engine-oil volumes above the 2.14% path.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.14% from 2020-2034 |
| Segmentation |
|
The market is estimated at 85.30 million liters in 2025 and is forecast to reach 94.82 million liters by 2030, growing at a 2.14% CAGR over the period.
BP (Castrol), CEPSA, ExxonMobil, Repsol, and Shell are the leading vendors, with the top five holding 81.69% of volume. FUCHS, TotalEnergies, Eni, Chevron, and Galp are notable challengers.
Engine oils are the largest segment by volume, driven by high fill requirements and short drain intervals. Hydraulic fluids are the fastest-growing segment over the forecast period.
An aging vehicle parc, workshop servicing demand, and a recovery in passenger vehicle sales drive growth. Electrification and longer drain intervals restrain volume expansion.
Catalonia leads regional demand and distribution, supported by automotive production and port-linked commerce. Madrid and Andalusia follow, reflecting vehicle density and workshop concentration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the passenger vehicle lubricants value chain, including base-oil and additive suppliers, specialized lubricant formulators, contract blenders, national distributors, and workshop-chain operators. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. Fieldwork focused on drain-interval behavior, OEM approval pathways, and distributor economics in Catalonia and Madrid.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Base-Oil & Additive Suppliers | 30% |
| Specialized Formulators & Blenders | 40% |
| National Distributors | 20% |
| Workshop Chains & Aftermarket Operators | 10% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, Eurostat), corporate annual filings and investor presentations (10-K and equivalent), patent databases for formulation trends, and recognized technical standards and industry associations. These sources were used to cross-check volume trajectories, pricing, and channel structure rather than to substitute for primary evidence.
We triangulate simultaneously through a top-down route, allocating macroeconomic and automotive-segment demand to Spain, and a bottom-up route, modeling manufacturer capacity, product pricing, and end-use consumption. Divergences between the two routes are reconciled against workshop servicing data and parc-age distributions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in liters for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |