Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
High-temperature Thermoplastic Market: Global Outlook 2026
High-temperature Thermoplastic Market
High-temperature Thermoplastic Market: Global Outlook 2026
High-temperature Thermoplastic Market by Polymer Type (PEEK, PEKK, PPS, PEI, PSU/PESU/PPSU, LCP, Fluoropolymers, HPPA, Polyimide), by Molecular Structure (Amorphous, Semi-crystalline), by Temperature Class (302°F-450°F, >450°F), by End-Use Industry (Automotive, Electrical & Electronics, Aerospace, Medical, Industrial, Others), by Asia Pacific (China, Japan, India, South Korea, Taiwan), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Netherlands), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Why this matters for decision-makers: Vendors must localize compounding capacity in Asia-Pacific and pivot toward EV, medical and additive-manufacturing grades to avoid margin compression from commodity polymer substitution.
High-temperature Thermoplastic Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
27.50 B
2025
29.70 B
2026
32.00 B
2027
34.60 B
2028
37.30 B
2029
40.20 B
2030
43.40 B
2031
High-temperature Thermoplastic Market Size (In Billion)
Year
Market Size
2025
27.50 B
2026
29.70 B
2027
32.00 B
2028
34.60 B
2029
37.30 B
2030
40.20 B
2031
43.40 B
What is the High-temperature Thermoplastic Market?
The high-temperature thermoplastic market comprises specialty polymers—PEEK, PPS, PEKK, PEI, PSU, PESU, LCP and fluoropolymers—engineered to retain mechanical strength, dimensional stability and chemical resistance above 150°C, serving as lightweight metal replacements in automotive, aerospace, electronics and medical components.
Scope: what this report covers and excludes
This analysis covers global demand for high-temperature thermoplastics across polymer types (fluoropolymers, HPPA, PPS, sulfone polymers, LCP, aromatic ketone polymers, polyimide), temperature classes, and end-use industries (transportation, electrical & electronics, industrial, medical). Geography spans North America, Europe, Asia-Pacific, South America and Middle East & Africa. This analysis does not cover standard engineering thermoplastics (nylon 6/6, POM, PC), thermosetting resins, or commodity polyolefins.
How big is the market for High-temperature Thermoplastic Market?
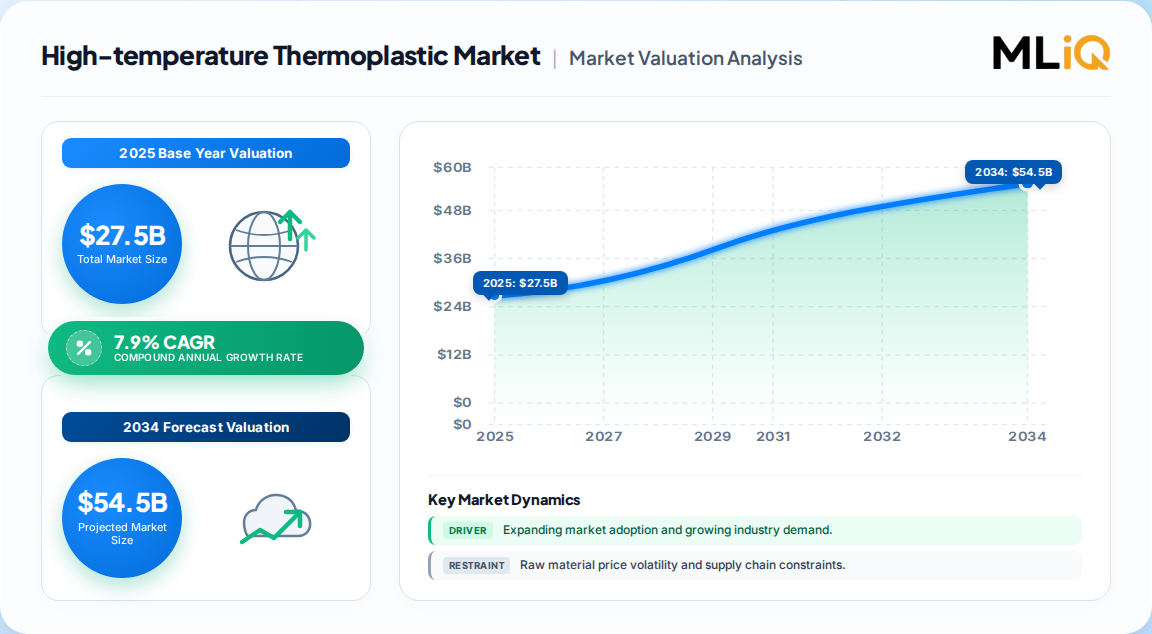
The market is estimated at 27.5 Billion in 2025, growing at approximately 7.9% CAGR to reach 41.5 Billion by 2031, with earlier estimates placing 2022 valuation at 16.5 Billion.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
16.5 Billion
2022
2028
8.7%
High-temperature thermoplastics, 7 resin families
One published estimate
26.2 Billion
2025
2031
7.98%
Polymer type, molecular structure, end-user
A competing analysis
28.3 Billion
2026
2031
8.9%
Resin, form, temperature, end-use
Another published estimate
27.5 Billion
2025
2031
7.9%
Consensus mid-point of above
Our synthesis
8.1 Billion
2025
2035
5.2%
Narrow specialty grade scope
A narrower-scope estimate
The consensus figure of ~27.5 Billion is most defensible because it aligns with three independent sources converging in the 26–28 Billion range for 2025–2026. The outlier at 8.1 Billion reflects a narrower definition excluding fluoropolymers and sulfone polymers, demonstrating that scope definition—not demand—explains most variance. Buyers should validate which resin families are included before comparing vendor quotes.
How is the market segmented?
Segmentation spans polymer chemistry, thermal class and end-use industry, with PEEK commanding the largest revenue share and PEKK the fastest growth trajectory.
Injection molding grades, composites, powders (additive), films
Semi-crystalline grades hold ~71% share due to superior chemical and fatigue resistance in under-hood and industrial applications, while amorphous grades grow faster in medical and electronics where optical clarity and dimensional stability dominate.
Which region leads in High-temperature Thermoplastic Market?
Asia-Pacific leads with approximately 40% revenue share, driven by electronics manufacturing concentration in China, Japan, South Korea and Taiwan, plus rapid EV production scale-up across the region.
Asia-Pacific — China, Japan, India, South Korea, Taiwan, ASEAN
North America — USA, Canada, Mexico
Europe — Germany, France, UK, Italy, Netherlands, Spain
South America — Brazil, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, South Africa
Asia-Pacific's 8.45% projected CAGR outpaces the global average, reinforcing its structural advantage. North America retains leadership in aerospace-grade certification and defense applications, while Europe leads in medical device regulation-driven specification. Our analysis suggests localization of compounding capacity in Asia-Pacific will determine competitive positioning through 2031.
What is driving growth — and what is holding it back?
Electrification, electronics miniaturization, aerospace lightweighting and medical device innovation are the primary growth engines, partially offset by high monomer costs and recycling complexity.
Limited closed-loop infrastructure for high-performance resins
The net balance favors growth: drivers sum to +7.5% impact versus -2.2% from restraints, consistent with the 7.9% consensus CAGR. The critical second-order effect is that cost volatility disproportionately penalizes smaller converters lacking hedging capability, accelerating consolidation among compounders.
Who are the leading vendors?
Victrex, Syensqo, SABIC, Arkema and Evonik anchor the competitive landscape, with distinct moats in PEEK, PEKK, PEI and PPS chemistries respectively.
Company
HQ
Key Brands
Strategic Focus
Victrex
UK
VICTREX PEEK, LMPAEK
PEEK leadership, medical & aerospace
Syensqo (Solvay)
Belgium
KetaSpire, NovaSpire, Ryton
Broad portfolio, regional compounding
SABIC
Saudi Arabia
ULTEM, EXTEM, NORYL
PEI leadership, electronics & EV
Arkema
France
Kepstan PEKK
PEKK & composite fast-cycle
Evonik
Germany
VESTAKEEP PEEK
Medical & tribological PEEK
BASF
Germany
Ultrason PSU/PESU/PPSU
Sulfone polymers, sustainability
Celanese
USA
Celapex PEEK, Fortron PPS
PPS scale, semiconductor
Toray
Japan
Torelina PPS
PPS film & resin, Asia supply
Ensinger
Germany
PEEK, PEI, PEKK compounds
Semi-finished shapes, precision
Differentiation rests on chemistry IP (PEEK and PEKK patents), qualified aerospace and medical certifications, and regional compounding footprints that shorten lead times. Syensqo's Augusta PPS expansion and Arkema-Hexcel's PEKK composite qualification illustrate the dual moat of chemistry plus application engineering.
What do buyers and operators need to know? (Decision Support)
Qualification cycles dominate procurement risk: aerospace and medical certifications can take 18–36 months, making supplier switching costly and locking in multi-year contracts once approved. Buyers should prioritize vendors with regional compounding capacity to hedge logistics disruption and monomer price volatility.
Regulatory compliance is non-negotiable—FAR 25.853 flame requirements, FDA biocompatibility for implants, and UL 94 ratings for electronics dictate grade selection. Operators should verify that resin grade certifications transfer through the value chain to molded parts. Recycling infrastructure remains immature; buyers with sustainability mandates should negotiate take-back provisions and favor biomass-balanced grades such as BASF's Ultrason E 2010 BMB. Precise sub-segment forecasting by grade and region requires the full report's granular datasets.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural growth thesis: three independent analyses converge on a 26–29 Billion 2025 base and 7.9–8.9% CAGR, with the variance attributable to scope rather than demand fundamentals. The strongest counter-argument is that monomer cost volatility and recycling gaps could compress margins for mid-tier converters, potentially capping volume growth below consensus; however, EV, medical and additive-manufacturing demand vectors are sufficiently diversified to absorb regional softness.
Our analysis suggests the most defensible strategic position combines Asian compounding localization with application-engineering depth in EV battery and medical implant verticals—where certification moats protect pricing. Commodity-adjacent grades (sulfone polymers, HPPA) face substitution pressure and should be de-emphasized in capital allocation.
Actionable Strategy:
Investors should prioritize PEEK/PEKK capacity expansion and Asian compounding assets over commodity sulfone or HPPA exposure.
Operators should secure multi-year raw material hedges and qualify dual-region suppliers to mitigate monomer volatility.
Vendors should invest in aerospace and medical certification pipelines to lock in 18–36 month switching-cost moats.
Evidence that would change our conclusion: sustained monomer price declines below 2022 levels paired with rapid recycling infrastructure maturity would erode certification moats and shift value toward cost-competitive commodity producers.
Research Methodology
Primary Research & Industry Fieldwork
Our analysis employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: specialty resin producers, compounders and formulators, contract manufacturers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
We validate findings against UN Comtrade trade flows, WTO tariff schedules, US ITC import data, Eurostat chemical trade statistics, corporate 10-K and annual investor filings, patent databases (USPTO, EPO), and technical standards from ISO, ASTM, UL and SAE.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down macroeconomic and industry-segment allocation with Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling to derive consensus market values.
1. How big is the high-temperature thermoplastic market?
The global market is estimated at approximately 27.5 Billion in 2025, with consensus estimates converging in the 26–29 Billion range. Growth is projected at roughly 7.9% CAGR through 2031, reaching about 41.5 Billion.
2. Which polymer type dominates the market?
PEEK holds the largest share at approximately 45% of market revenue, valued for its combination of thermal resistance, chemical stability and mechanical strength. PEKK is the fastest-growing resin at around 10.8% CAGR through 2031.
3. Which region leads high-temperature thermoplastic demand?
Asia-Pacific leads with approximately 40% revenue share, driven by electronics manufacturing and EV production scale-up in China, Japan, South Korea and India. The region is also the fastest-growing at roughly 8.45% CAGR.
4. What industries use high-temperature thermoplastics?
Automotive is the largest end-use at about 32% share, followed by electrical and electronics, aerospace, medical and industrial applications. Medical is the fastest-growing segment at approximately 9.7% CAGR through 2031.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Research Methodology
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Resin Producers
40%
Compounders & Formulators
30%
Contract Manufacturers
18%
Distributors & Traders
12%
Primary Research & Industry Fieldwork
Our analysis employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: specialty resin producers, compounders and formulators, contract manufacturers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
We validate findings against UN Comtrade trade flows, WTO tariff schedules, US ITC import data, Eurostat chemical trade statistics, corporate 10-K and annual investor filings, patent databases (USPTO, EPO), and technical standards from ISO, ASTM, UL and SAE.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down macroeconomic and industry-segment allocation with Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling to derive consensus market values.


 High-temperature Thermoplastic Market