Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Solvents Market Size, Share & Forecast to 2031
Solvents Market Size, Share & Forecast to 2031
Solvents Market
Solvents Market Size, Share & Forecast to 2031
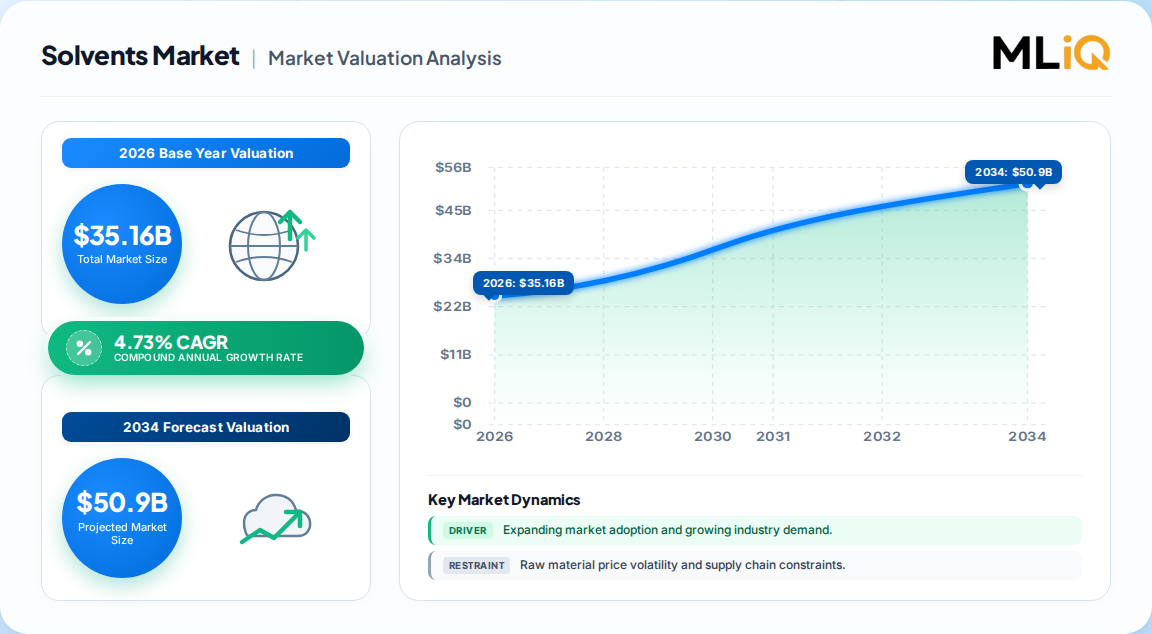
Solvents Market by Source (Bio-Based Solvents, Petrochemical-Based Solvents), by Type (Oxygenated Solvents, Hydrocarbon Solvents, Halogenated Solvents), by Application (Paints and Coatings, Adhesives, Pharmaceuticals, Cleaning, Printing Inks, Others), by Asia Pacific (China, Japan, India, South Korea, Vietnam, Rest of APAC), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
USD 35.16 billion in 2026, the global solvents market is forecast to reach USD 44.30 billion by 2031 at a 4.73% CAGR (2026–2031), per the consensus estimate.
Petrochemical-based grades held 84.23% of 2025 volume, yet bio-based solvents are the fastest-growing source segment at an 8.13% CAGR.
Oxygenated solvents dominated type share at 65.78% in 2025, forecast to grow at 4.97% through 2031 on coatings and pharmaceutical demand.
Paints and coatings generated 49.22% of 2025 revenue; pharmaceuticals is the fastest-growing application at a 5.04% CAGR.
Asia-Pacific led with 42.35% share in 2025 and is the fastest-growing region at a 5.21% CAGR, followed by North America and Europe.
Leading vendors include Dow, BASF, ExxonMobil, Shell, Eastman Chemical and Solvay, alongside bio-solvent specialists ADM, Cargill and Solvay.
Why this matters for decision-makers: Suppliers tethered to commodity hydrocarbon blends face structural margin erosion; capital and R&D must pivot toward low-VOC oxygenates, bio-routes and closed-loop recovery to capture premium pricing.
Solvents Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
33.57 B
2025
35.16 B
2026
36.82 B
2027
38.56 B
2028
40.39 B
2029
42.30 B
2030
44.30 B
2031
Solvents Market Size (In Billion)
Year
Market Size
2025
33.57 B
2026
35.16 B
2027
36.82 B
2028
38.56 B
2029
40.39 B
2030
42.30 B
2031
44.30 B
What is the Solvents Market?
The solvents market covers liquid chemical substances—oxygenated, hydrocarbon and halogenated—that dissolve, dilute or extract other materials across paints and coatings, adhesives, pharmaceuticals, cleaning and chemical synthesis. It spans petrochemical and bio-based feedstocks, with demand shaped by VOC regulation, industrial output and drug manufacturing intensity.
Scope: what this report covers and excludes
This analysis covers the global solvents market by source (bio-based vs petrochemical), type (oxygenated, hydrocarbon, halogenated) and application (paints and coatings, adhesives, pharmaceuticals, cleaning, inks and others), across five regions. This analysis does not cover solvent-recovery equipment manufacturing, specialty reagent-grade lab solvents below industrial scale, or adjacent markets such as plasticizers and lubricants.
How big is the market for Solvents Market?
Estimates converge on a mid-USD-30-billion base, but definitions diverge sharply on whether bio-solvents are counted inside the total or as an adjacent segment—a distinction that materially changes the CAGR and the addressable opportunity.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 35.16 B → 44.30 B
2026
2031
4.73%
Full solvents market incl. bio-based, value terms
One published estimate
USD 5.86 B → 11.33 B
2026
2035
7.6%
Green and bio-based solvents only
A competing analysis
USD 4.00 B → 5.88 B
2023
2033
3.93%
Bio-solvents as a standalone product market
A third published estimate
Our analysis suggests the USD 35.16 billion figure is the most defensible full-market anchor because it reconciles petrochemical dominance (84%) with a fast-growing bio-slice that sits inside the total. The standalone bio-solvent valuations are not contradictory—they reflect narrower definitions and different base years. Buyers should treat the full-market series as the strategic denominator and the bio sub-series as the growth engine.
How is the market segmented?
Segmentation hinges on three axes—source, type and application—with oxygenated grades and coatings dominating revenue while bio-based and pharmaceutical segments set the pace of growth.
This structure implies a barbell strategy: defend volume in commodity oxygenated and hydrocarbon grades while seeding bio-based and high-purity pharma niches where pricing power is strongest.
Which region leads in Solvents Market?
Asia-Pacific leads the global solvents market, capturing 42.35% of 2025 value and growing at a 5.21% CAGR—the fastest among regions—driven by Chinese VOC standards, Indian ethanol capacity and pharmaceutical manufacturing clusters.
Solvents Market Regional Market Share
Loading chart...
Solvents Market Regional Market Share
Region
Market Share (%)
Asia Pacific
0.42%
North America
0.24%
Europe
0.22%
South America
0.07%
Middle East & Africa
0.05%
Asia-Pacific — China, Japan, India, South Korea, Vietnam, Rest of APAC
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Rest of Europe
South America — Brazil, Argentina, Rest of South America
Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2025 share
Asia-Pacific
42%
North America
24%
Europe
22%
South America
7%
Middle East & Africa
5%
Our analysis suggests Asia-Pacific's lead is structural, not cyclical: integrated refinery capacity, low-cost ethanol and rising API output embed a cost advantage that Western producers cannot easily match on commodity grades.
What is driving growth — and what is holding it back?
Growth is anchored by coatings demand and pharmaceutical expansion in emerging Asia, while VOC regulation simultaneously suppresses hydrocarbon volume and accelerates substitution toward compliant oxygenates and bio-solvents.
Factor
Direction
Evidence strength
Mechanism
Paints & coatings demand
+
High
Architectural and industrial coatings absorb ~49% of output
Pharma manufacturing in APAC
+
High
India/China produce 38% of global APIs
Tightening VOC caps
+/-
High
Displaces hydrocarbons, lifts oxygenates and bio-grades
Solvent-based polymer recycling
+
Medium
Could absorb 200,000 t of solvents by 2031
AI closed-loop recovery
+
Medium
Cuts end-user opex, lowers net consumption
Bio-solvent price premium
−
High
10–15% premium slows commodity substitution
Feedstock price volatility
−
Medium
Naphtha and ethanol swings widen producer margins
The balance of evidence favors a volume-steady, mix-shifting market: total growth is modest at ~4.7%, but the composition is rotating meaningfully toward low-VOC and bio-based grades. That divergence—not headline size—is where margin opportunity sits.
Who are the leading vendors?
The competitive landscape is moderately concentrated, with integrated petrochemical majors dominating commodity volume and specialty and bio-solvent players capturing premium niches in coatings, pharma and electronics cleaning.
Company
Positioning
Strategic moat
Dow
Oxygenated & glycol ethers
Integrated feedstock, technical service
BASF
Broad portfolio, oxo-alcohols
Scale, global distribution
ExxonMobil
Hydrocarbons, recycling
Feedstock integration, Exxtend recycling
Shell
Hydrocarbon & oxygenated
Refinery integration
Eastman Chemical
Specialty esters, acetates
Formulation expertise
Solvay
Specialty & bio-based
Technical specialization
ADM
Bio-alcohols
Feedstock and ethanol capacity
Cargill
Bio-based intermediates
Agricultural value chain
Differentiation increasingly rests on credible bio-routes, validated quality systems for pharma-grade purity, and recovery-service models that embed suppliers in customer compliance workflows. Mid-tier producers reliant on spot naphtha face the widest cost swings and weakest pricing power.
What do buyers and operators need to know?
Selection criteria are shifting from price-per-tonne toward total compliance cost. Buyers must weigh VOC content, ICH Q3C residual-solvent compliance for pharma, and supplier capability to support reformulation as regulations tighten. Switching costs are highest in pharmaceutical and electronics applications, where requalification can take 12–24 months and demand validated purity data.
Procurement risk concentrates on feedstock volatility and regional supply concentration in Asia-Pacific. Operators should secure multi-year offtake with integrated suppliers and model dual-sourcing across petrochemical and bio-based routes to hedge both price and regulatory exposure. Smaller formulators face USD 0.5–2 million reformulation outlays, making technical-service partnerships a practical route to compliance without capital strain.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mix-shift strategy over volume expansion. At 4.73% overall CAGR, the total market offers limited organic upside; the real value is captured by suppliers who migrate portfolios toward low-VOC oxygenates, bio-alcohols and pharma-grade specialties where premiums of 10–15% persist. Integrated feedstock owners and credible bio-route producers hold the strongest position to defend margin through regulatory transitions.
The strongest counter-argument is that bio-solvent price premiums and performance gaps in high-solvency applications could cap substitution, keeping petrochemical grades dominant well past 2031. That is credible—84% petrochemical share will not invert quickly. But regulatory direction is one-way: U.S. methylene chloride restrictions, REACH NMP limits and Chinese VOC standards are structurally eroding the hydrocarbon base regardless of cost parity timing. Our analysis suggests the risk is not whether substitution happens, but whether incumbents reposition fast enough.
Actionable strategy:
Investors should overweight suppliers with integrated feedstock plus credible bio-routes, and underweight spot-naphtha-dependent mid-tier producers.
Operators should lock multi-year offtake and dual-source across petrochemical and bio-based grades to hedge price and regulatory risk.
Formulators should partner with technical-service-led suppliers to share reformulation costs ahead of tightening VOC caps.
Evidence that would change this conclusion: a sustained collapse in bio-feedstock premiums to near-parity, or a regulatory rollback on VOC limits, would materially slow the mix shift and re-favor commodity hydrocarbon incumbents.
Solvents Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Solvents Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.73% from 2020-2034
Segmentation
By Source
Bio-Based Solvents
Petrochemical-Based Solvents
By Type
Oxygenated Solvents
Hydrocarbon Solvents
Halogenated Solvents
By Application
Paints and Coatings
Adhesives
Pharmaceuticals
Cleaning
Printing Inks
Others
By Geography
Asia Pacific
China
Japan
India
South Korea
Vietnam
Rest of APAC
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Rest of Europe
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
Table of Contents
1. Solvents Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Solvents Market Executive Summary
2.1. Market Snapshot
3. Solvents Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Solvents Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Solvents Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Source
5.1.1. Bio-Based Solvents
5.1.2. Petrochemical-Based Solvents
5.2. Analysis, Insights and Forecast - by Type
5.2.1. Oxygenated Solvents
5.2.2. Hydrocarbon Solvents
5.2.3. Halogenated Solvents
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Paints and Coatings
5.3.2. Adhesives
5.3.3. Pharmaceuticals
5.3.4. Cleaning
5.3.5. Printing Inks
5.3.6. Others
5.4. Analysis, Insights and Forecast - by Region
5.4.1. Asia Pacific
5.4.2. North America
5.4.3. Europe
5.4.4. South America
5.4.5. Middle East & Africa
6. Solvents Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Source
6.1.1. Bio-Based Solvents
6.1.2. Petrochemical-Based Solvents
6.2. Analysis, Insights and Forecast - by Type
6.2.1. Oxygenated Solvents
6.2.2. Hydrocarbon Solvents
6.2.3. Halogenated Solvents
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Paints and Coatings
6.3.2. Adhesives
6.3.3. Pharmaceuticals
6.3.4. Cleaning
6.3.5. Printing Inks
6.3.6. Others
7. Solvents Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Source
7.1.1. Bio-Based Solvents
7.1.2. Petrochemical-Based Solvents
7.2. Analysis, Insights and Forecast - by Type
7.2.1. Oxygenated Solvents
7.2.2. Hydrocarbon Solvents
7.2.3. Halogenated Solvents
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Paints and Coatings
7.3.2. Adhesives
7.3.3. Pharmaceuticals
7.3.4. Cleaning
7.3.5. Printing Inks
7.3.6. Others
8. Solvents Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Source
8.1.1. Bio-Based Solvents
8.1.2. Petrochemical-Based Solvents
8.2. Analysis, Insights and Forecast - by Type
8.2.1. Oxygenated Solvents
8.2.2. Hydrocarbon Solvents
8.2.3. Halogenated Solvents
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Paints and Coatings
8.3.2. Adhesives
8.3.3. Pharmaceuticals
8.3.4. Cleaning
8.3.5. Printing Inks
8.3.6. Others
9. Solvents Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Source
9.1.1. Bio-Based Solvents
9.1.2. Petrochemical-Based Solvents
9.2. Analysis, Insights and Forecast - by Type
9.2.1. Oxygenated Solvents
9.2.2. Hydrocarbon Solvents
9.2.3. Halogenated Solvents
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Paints and Coatings
9.3.2. Adhesives
9.3.3. Pharmaceuticals
9.3.4. Cleaning
9.3.5. Printing Inks
9.3.6. Others
10. Solvents Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Source
10.1.1. Bio-Based Solvents
10.1.2. Petrochemical-Based Solvents
10.2. Analysis, Insights and Forecast - by Type
10.2.1. Oxygenated Solvents
10.2.2. Hydrocarbon Solvents
10.2.3. Halogenated Solvents
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Paints and Coatings
10.3.2. Adhesives
10.3.3. Pharmaceuticals
10.3.4. Cleaning
10.3.5. Printing Inks
10.3.6. Others
11. Solvents Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Solvents Market Research Methodology
List of Figures
Figure 1: Solvents Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Solvents Market Revenue (Billion), by Source 2026 & 2034
Figure 3: Asia Pacific Solvents Market Revenue Share (%), by Source 2026 & 2034
Figure 4: Asia Pacific Solvents Market Revenue (Billion), by Type 2026 & 2034
Figure 5: Asia Pacific Solvents Market Revenue Share (%), by Type 2026 & 2034
Figure 6: Asia Pacific Solvents Market Revenue (Billion), by Application 2026 & 2034
Figure 7: Asia Pacific Solvents Market Revenue Share (%), by Application 2026 & 2034
Figure 8: Asia Pacific Solvents Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Asia Pacific Solvents Market Revenue Share (%), by Country 2026 & 2034
Figure 10: North America Solvents Market Revenue (Billion), by Source 2026 & 2034
Figure 11: North America Solvents Market Revenue Share (%), by Source 2026 & 2034
Figure 12: North America Solvents Market Revenue (Billion), by Type 2026 & 2034
Figure 13: North America Solvents Market Revenue Share (%), by Type 2026 & 2034
Figure 14: North America Solvents Market Revenue (Billion), by Application 2026 & 2034
Figure 15: North America Solvents Market Revenue Share (%), by Application 2026 & 2034
Figure 16: North America Solvents Market Revenue (Billion), by Country 2026 & 2034
Figure 17: North America Solvents Market Revenue Share (%), by Country 2026 & 2034
Table 14: Rest of APAC Solvents Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: North America Solvents Market Revenue Billion Forecast, by Source 2020 & 2034
Table 16: North America Solvents Market Revenue Billion Forecast, by Type 2020 & 2034
Table 17: North America Solvents Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the solvents market?
The global solvents market is valued at USD 35.16 billion in 2026 and is forecast to reach USD 44.30 billion by 2031, growing at a 4.73% CAGR. Petrochemical-based grades dominate volume, while bio-based solvents drive the fastest growth.
2. What is the fastest-growing solvents segment?
Bio-based solvents are the fastest-growing source segment at an 8.13% CAGR, and pharmaceuticals is the fastest-growing application at 5.04%. Ethyl lactate leads bio-types at 8.9% CAGR, driven by electronics cleaning and pharma synthesis.
3. Which region leads the solvents market?
Asia-Pacific leads with 42.35% of 2025 value and is the fastest-growing region at a 5.21% CAGR, supported by Chinese VOC standards, Indian ethanol capacity and rapid pharmaceutical manufacturing expansion.
4. What is driving solvents market growth?
Coatings demand, accelerating pharmaceutical manufacturing in Asia-Pacific and tightening VOC caps that push substitution toward compliant oxygenates and bio-solvents are the primary growth drivers, alongside emerging solvent-based polymer recycling.
5. Who are the leading solvents market players?
Leading vendors include Dow, BASF, ExxonMobil, Shell, Eastman Chemical and Solvay, alongside bio-solvent specialists ADM and Cargill. Differentiation rests on feedstock integration, credible bio-routes and validated quality systems.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the solvents value chain, including raw material and feedstock suppliers, specialized solvent producers, contract formulators and blenders, and global distributors. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of R&D and formulation, Technical Directors, and Commercial Operations Leads, ensuring both supply-side capacity and demand-side procurement perspectives are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
38%
Procurement & Sourcing Directors
34%
Quality & Regulatory Leads
28%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
42%
Formulators & Blenders
33%
Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
Primary findings were benchmarked against official multilateral trade and standards databases—UN Comtrade, WTO, US ITC and Eurostat—alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations. This cross-validation anchors volume and pricing estimates in verifiable trade and disclosure data.
Demand Modeling & Market Sizing Triangulation
Market sizing uses simultaneous Top-Down and Bottom-Up triangulation. Top-down modeling allocates macroeconomic and industry-segment output to solvent consumption, while bottom-up modeling aggregates manufacturer capacity, product pricing and end-use consumption across coatings, pharma, cleaning and adhesives. Both approaches are reconciled against trade statistics and interview data.


 Solvents Market