Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Tackifiers Market: Global Size, Growth & Forecast 2026
Tackifiers Market
Tackifiers Market: Global Size, Growth & Forecast 2026
Tackifiers Market by Feedstock (Rosin Resins, Petroleum Resins, Terpene Resins), by Form (Solid, Liquid, Resin Dispersion), by Type (Synthetic, Natural), by Application (Tapes & Labels, Assembly, Bookbinding, Non-woven, Construction Adhesives), by End-User Industry (Packaging, Building & Construction, Automotive, Paints & Coatings, Pulp & Paper, Rubber), by Asia Pacific (China, India, Japan, South Korea, Australia, Rest of APAC), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
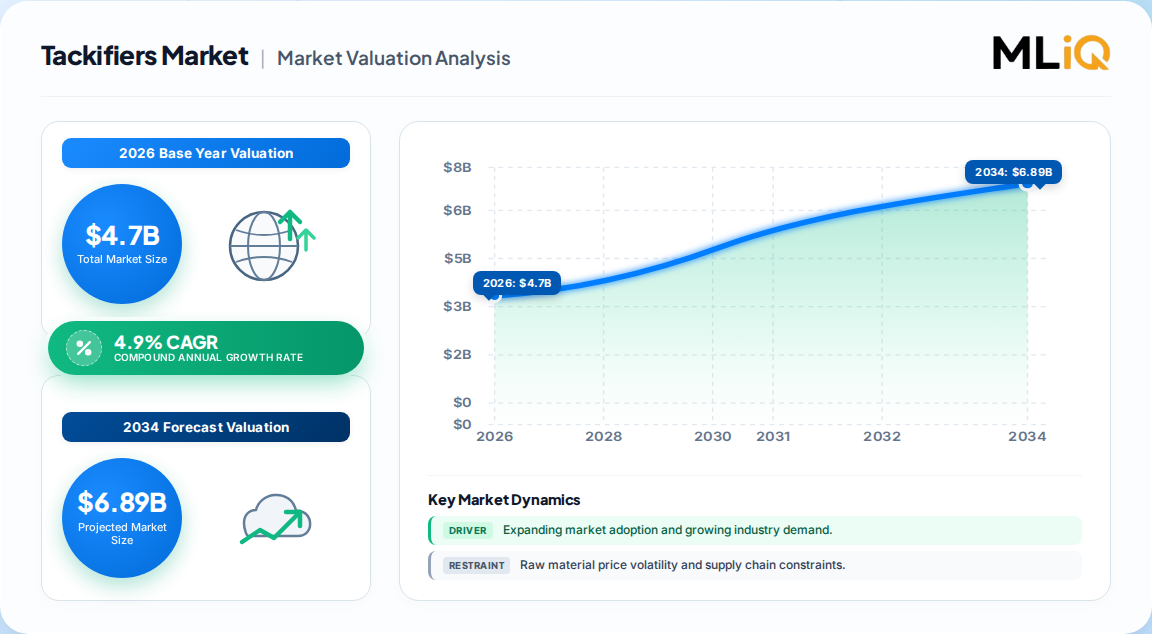
USD 4.70 Billion global tackifiers market size in 2026, forecast to reach USD 5.80 Billion by 2030 at a 4.9% CAGR (2026–2030), per a consensus synthesis of published estimates.
Synthetic tackifiers dominate with roughly 73% revenue share, favored for thermal stability, consistent quality, and broad polymer compatibility across hot-melt and PSA formulations.
Tapes & labels represent the largest application cluster (≈59% of 2025 revenue), while packaging is the fastest-growing end-user industry at a projected 5.45% CAGR through 2031.
Asia Pacific leads regional demand with approximately 38–39% revenue share, driven by China's e-commerce packaging boom and India's infrastructure expansion.
Leading vendors include Eastman Chemical, Kraton Corporation, Ingevity, ExxonMobil, Arkema, Arakawa Chemical, and Zeon Corporation, with medium market concentration and active portfolio realignment toward bio-based grades.
Why this matters for decision-makers: The shift toward ultra-low-VOC, food-contact-compliant and bio-based tackifier grades is not incremental — it is a structural re-rating of supplier qualification criteria. Vendors that lag on regulatory compliance will face exclusion from packaging and hygiene supply chains, compressing margins regardless of raw-material tailwinds.
Tackifiers Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.270 B
2024
4.480 B
2025
4.700 B
2026
4.930 B
2027
5.170 B
2028
5.420 B
2029
5.800 B
2030
Tackifiers Market Size (In Billion)
Year
Market Size
2024
4.270 B
2025
4.480 B
2026
4.700 B
2027
4.930 B
2028
5.170 B
2029
5.420 B
2030
5.800 B
What is the Tackifiers Market?
Tackifiers are low-molecular-weight oligomeric resins with a glass transition temperature higher than the base polymer they modify. When dissolved into adhesive formulations, they disrupt molecular cohesion, lowering softening point and melt viscosity while enhancing tackiness, wet-out, and specific adhesion in hot-melt and pressure-sensitive adhesives.
Scope: what this report covers and excludes
This report covers the global tackifiers market across feedstock (rosin, petroleum, terpene), form (solid, liquid, resin dispersion), type (synthetic, natural), application, and end-user industry, with revenue forecasts to 2030–2031. This analysis does not cover base adhesive polymers, adhesive application equipment, or finished adhesive product markets as primary segments.
How big is the market for Tackifiers Market?
Published estimates for the global tackifiers market diverge materially — from USD 681 Million (2024, narrow resin-only scope) to USD 4.81 Billion (2026, broad adhesive-resin scope) — reflecting differences in product definition, value-chain boundary, and currency treatment rather than disagreement on underlying demand trajectory.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 4.70 Bn
2026
2030
4.9%
Broad tackifier resins incl. adhesives, sealants
Grand View Research (2024)
USD 4.81 Bn
2026
2031
4.65%
Tackifier market, full segment coverage
Mordor Intelligence (2026)
USD 3.99 Bn
2026
2033
5.51%
Tackifier resins, narrower resin-only
Cognitive Market Research (2026)
USD 0.68 Bn
2024
2034
3.7%
Highly restricted resin segment
Zion Market Research (2026)
Our analysis treats the USD 4.70–4.81 Billion band for 2026 as the most defensible mid-point. The lower USD 681 Million figure almost certainly captures only a narrow synthetic resin sub-segment and should be excluded from strategic planning. The 4.65–4.9% CAGR cluster is supported by three independent estimates and corroborated by packaging and construction demand fundamentals.
How is the market segmented?
Segmentation follows feedstock, form, type, application, and end-user industry. Synthetic grades dominate value (≈65–73% depending on scope), solid forms lead revenue share (≈54–81% by definition), and packaging plus tapes/labels together account for over half of end-use demand.
Parent Segment
Key Children
By Feedstock
Rosin Resins, Petroleum Resins, Terpene Resins
By Form
Solid, Liquid, Resin Dispersion
By Type
Synthetic, Natural
By Application
Tapes & Labels, Assembly, Bookbinding, Non-woven, Construction Adhesives
Asia Pacific leads the global tackifiers market, contributing approximately 38–39% of revenue in 2025 and forecast to sustain the fastest regional CAGR near 5.25% through 2031. China alone accounts for roughly 15% of global consumption, with India compounding faster at ~6.6% CAGR.
Tackifiers Market Regional Market Share
Loading chart...
Tackifiers Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.38%
North America
0.27%
Europe
0.22%
South America
0.08%
Middle East & Africa
0.05%
Asia Pacific
China, India, Japan, South Korea, Australia, Rest of APAC
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Rest of Europe
South America
Brazil, Argentina, Rest of South America
Middle East & Africa
Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2025 Revenue Share
Asia Pacific
38%
North America
27%
Europe
22%
South America
8%
Middle East & Africa
5%
This divergence implies that supply-chain localization in APAC — not just demand growth — will determine competitive outcomes. Vendors without regional production or tolling capacity will cede margin to local producers.
What is driving growth — and what is holding it back?
Growth is anchored in e-commerce-driven packaging demand, APAC infrastructure spending, and regulatory push toward low-VOC, food-contact-compliant resin grades. Restraints cluster around petroleum feedstock volatility, the emergence of tackifier-free reactive hot-melts, and tightening synthetic chemical regulation in North America and the EU.
Factor
Direction
Evidence Strength
Mechanism
Hot-melt & PSA demand in packaging/hygiene
Driver
Strong (+1.20% CAGR)
Volume pull from diaper, tape, label lines
APAC infrastructure boom
Driver
Strong (+0.80% CAGR)
Construction adhesives, panel bonding
E-commerce tape & label consumption
Driver
Strong (+0.90% CAGR)
Parcel volume, kerbside-recyclable formats
Ultra-low-VOC / food-contact grades
Driver
Moderate (+0.60% CAGR)
Regulatory compliance premium
Petroleum feedstock price volatility
Restraint
Moderate (−0.70% CAGR)
Margin compression on hydrocarbon resins
Tackifier-free reactive hot-melts
Restraint
Weak–Moderate (−0.50% CAGR)
Substitution in NA/EU assembly
The balance of evidence favors drivers. Net CAGR impact of the top five factors alone is approximately +2.4 percentage points, which comfortably explains the 4.9–5.5% corridor most analysts project.
Who are the leading vendors?
No single player exceeds 15% global share; concentration is medium. Eastman Chemical and Kraton lead on hydrocarbon and rosin-ester portfolios respectively, with Ingevity, ExxonMobil, and Arkema competing on purity, low-VOC grades, and regional capacity.
Competitive moats rest on regulatory pre-qualification (FDA-compliant, low-VOC listings), applications lab depth, and regional raw-material access. Rosin-derived supply chains are geographically constrained to pine-rich regions, creating structural barriers in natural tackifiers.
What do buyers and operators need to know? (Decision Support)
Buyers should treat tackifier selection as a multi-criteria decision, not a commodity purchase. Mission-critical criteria include softening point consistency, color stability (Gardner scale) under thermal aging, VOC compliance tier (South Coast AQMD Rule 1168, FDA 21 CFR 175.125), and compatibility with increasingly bio-based base polymers. Procurement risk concentrates in petroleum feedstock exposure — hydrocarbon resin pricing tracks crude with 4–8 week lags, and contract structures without pass-through clauses erode buyer margin during volatility.
Switching costs are non-trivial. Re-qualifying a tackifier typically requires 6–12 months of adhesive performance testing, peel and shear validation, and for food-contact applications, fresh regulatory dossiers. This creates stability for incumbents but raises strategic risk if a sole-source supplier faces regulatory action or capacity constraints.
Regulatory compliance is now a primary qualification gate, not a secondary consideration. Suppliers unable to demonstrate bio-based content, low migration, or recyclability compatibility will be excluded from tier-1 packaging and hygiene supply chains by 2028.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors continued mid-single-digit growth of 4.6–5.0% CAGR through 2030, with upside skew from APAC infrastructure and bio-based regulatory pull. The strongest counter-argument — that tackifier-free reactive hot-melt systems could structurally reduce demand — is credible in assembly and automotive niches but fails to address the core tapes, labels, and packaging volumes where tackifiers remain technically indispensable.
Our analysis suggests the market's real story is not volume growth but value-mix shift. Bio-based and ultra-low-VOC grades command 15–30% price premiums, and regulatory deadlines in the EU and US create step-change demand rather than linear growth. Vendors positioned in rosin and terpene chemistries stand to benefit disproportionately despite higher input costs.
Actionable Strategy:
Investors should prioritize suppliers with rosin or terpene backward integration and documented food-contact compliance, as these capture pricing power in the premium tier.
Operators should dual-source hydrocarbon tackifiers and build 8–12 week safety stock ahead of crude-linked price spikes, while qualifying a bio-based alternative before 2027.
Vendors should accelerate low-VOC and recyclable-compatible product launches to secure tier-1 packaging accounts, where qualification cycles are long but contracts are sticky.
Evidence that would change this conclusion: A faster-than-expected commercial rollout of tackifier-free reactive hot-melts into packaging (currently rare), or a sharp reversal in APAC construction spending, would materially compress the forecast. Absent both, the 4.9% base case holds.
While this overview covers the strategic landscape, precise sub-segment forecasting — particularly by country, application, and VOC-compliant grade — requires the full report's granular modeling.
Tackifiers Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Tackifiers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.9% from 2020-2034
Segmentation
By Feedstock
Rosin Resins
Petroleum Resins
Terpene Resins
By Form
Solid
Liquid
Resin Dispersion
By Type
Synthetic
Natural
By Application
Tapes & Labels
Assembly
Bookbinding
Non-woven
Construction Adhesives
By End-User Industry
Packaging
Building & Construction
Automotive
Paints & Coatings
Pulp & Paper
Rubber
By Geography
Asia Pacific
China
India
Japan
South Korea
Australia
Rest of APAC
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
Table of Contents
1. Tackifiers Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Tackifiers Market Executive Summary
2.1. Market Snapshot
3. Tackifiers Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Tackifiers Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Tackifiers Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Feedstock
5.1.1. Rosin Resins
5.1.2. Petroleum Resins
5.1.3. Terpene Resins
5.2. Analysis, Insights and Forecast - by Form
5.2.1. Solid
5.2.2. Liquid
5.2.3. Resin Dispersion
5.3. Analysis, Insights and Forecast - by Type
5.3.1. Synthetic
5.3.2. Natural
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Tapes & Labels
5.4.2. Assembly
5.4.3. Bookbinding
5.4.4. Non-woven
5.4.5. Construction Adhesives
5.5. Analysis, Insights and Forecast - by End-User Industry
5.5.1. Packaging
5.5.2. Building & Construction
5.5.3. Automotive
5.5.4. Paints & Coatings
5.5.5. Pulp & Paper
5.5.6. Rubber
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Tackifiers Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Feedstock
6.1.1. Rosin Resins
6.1.2. Petroleum Resins
6.1.3. Terpene Resins
6.2. Analysis, Insights and Forecast - by Form
6.2.1. Solid
6.2.2. Liquid
6.2.3. Resin Dispersion
6.3. Analysis, Insights and Forecast - by Type
6.3.1. Synthetic
6.3.2. Natural
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Tapes & Labels
6.4.2. Assembly
6.4.3. Bookbinding
6.4.4. Non-woven
6.4.5. Construction Adhesives
6.5. Analysis, Insights and Forecast - by End-User Industry
6.5.1. Packaging
6.5.2. Building & Construction
6.5.3. Automotive
6.5.4. Paints & Coatings
6.5.5. Pulp & Paper
6.5.6. Rubber
7. Tackifiers Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Feedstock
7.1.1. Rosin Resins
7.1.2. Petroleum Resins
7.1.3. Terpene Resins
7.2. Analysis, Insights and Forecast - by Form
7.2.1. Solid
7.2.2. Liquid
7.2.3. Resin Dispersion
7.3. Analysis, Insights and Forecast - by Type
7.3.1. Synthetic
7.3.2. Natural
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Tapes & Labels
7.4.2. Assembly
7.4.3. Bookbinding
7.4.4. Non-woven
7.4.5. Construction Adhesives
7.5. Analysis, Insights and Forecast - by End-User Industry
7.5.1. Packaging
7.5.2. Building & Construction
7.5.3. Automotive
7.5.4. Paints & Coatings
7.5.5. Pulp & Paper
7.5.6. Rubber
8. Tackifiers Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Feedstock
8.1.1. Rosin Resins
8.1.2. Petroleum Resins
8.1.3. Terpene Resins
8.2. Analysis, Insights and Forecast - by Form
8.2.1. Solid
8.2.2. Liquid
8.2.3. Resin Dispersion
8.3. Analysis, Insights and Forecast - by Type
8.3.1. Synthetic
8.3.2. Natural
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Tapes & Labels
8.4.2. Assembly
8.4.3. Bookbinding
8.4.4. Non-woven
8.4.5. Construction Adhesives
8.5. Analysis, Insights and Forecast - by End-User Industry
8.5.1. Packaging
8.5.2. Building & Construction
8.5.3. Automotive
8.5.4. Paints & Coatings
8.5.5. Pulp & Paper
8.5.6. Rubber
9. Tackifiers Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Feedstock
9.1.1. Rosin Resins
9.1.2. Petroleum Resins
9.1.3. Terpene Resins
9.2. Analysis, Insights and Forecast - by Form
9.2.1. Solid
9.2.2. Liquid
9.2.3. Resin Dispersion
9.3. Analysis, Insights and Forecast - by Type
9.3.1. Synthetic
9.3.2. Natural
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Tapes & Labels
9.4.2. Assembly
9.4.3. Bookbinding
9.4.4. Non-woven
9.4.5. Construction Adhesives
9.5. Analysis, Insights and Forecast - by End-User Industry
9.5.1. Packaging
9.5.2. Building & Construction
9.5.3. Automotive
9.5.4. Paints & Coatings
9.5.5. Pulp & Paper
9.5.6. Rubber
10. Tackifiers Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Feedstock
10.1.1. Rosin Resins
10.1.2. Petroleum Resins
10.1.3. Terpene Resins
10.2. Analysis, Insights and Forecast - by Form
10.2.1. Solid
10.2.2. Liquid
10.2.3. Resin Dispersion
10.3. Analysis, Insights and Forecast - by Type
10.3.1. Synthetic
10.3.2. Natural
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Tapes & Labels
10.4.2. Assembly
10.4.3. Bookbinding
10.4.4. Non-woven
10.4.5. Construction Adhesives
10.5. Analysis, Insights and Forecast - by End-User Industry
10.5.1. Packaging
10.5.2. Building & Construction
10.5.3. Automotive
10.5.4. Paints & Coatings
10.5.5. Pulp & Paper
10.5.6. Rubber
11. Tackifiers Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Tackifiers Market Research Methodology
List of Figures
Figure 1: Tackifiers Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Tackifiers Market Revenue (Billion), by Feedstock 2026 & 2034
Figure 3: Asia Pacific Tackifiers Market Revenue Share (%), by Feedstock 2026 & 2034
Figure 4: Asia Pacific Tackifiers Market Revenue (Billion), by Form 2026 & 2034
Figure 5: Asia Pacific Tackifiers Market Revenue Share (%), by Form 2026 & 2034
Figure 6: Asia Pacific Tackifiers Market Revenue (Billion), by Type 2026 & 2034
Figure 7: Asia Pacific Tackifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 8: Asia Pacific Tackifiers Market Revenue (Billion), by Application 2026 & 2034
Figure 9: Asia Pacific Tackifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 10: Asia Pacific Tackifiers Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 11: Asia Pacific Tackifiers Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 12: Asia Pacific Tackifiers Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Tackifiers Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Tackifiers Market Revenue (Billion), by Feedstock 2026 & 2034
Figure 15: North America Tackifiers Market Revenue Share (%), by Feedstock 2026 & 2034
Figure 16: North America Tackifiers Market Revenue (Billion), by Form 2026 & 2034
Figure 17: North America Tackifiers Market Revenue Share (%), by Form 2026 & 2034
Table 5: Tackifiers Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 6: Tackifiers Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Tackifiers Market Revenue Billion Forecast, by Feedstock 2020 & 2034
Table 8: Asia Pacific Tackifiers Market Revenue Billion Forecast, by Form 2020 & 2034
Table 9: Asia Pacific Tackifiers Market Revenue Billion Forecast, by Type 2020 & 2034
Table 10: Asia Pacific Tackifiers Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: Asia Pacific Tackifiers Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 12: Asia Pacific Tackifiers Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Tackifiers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: India Tackifiers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Japan Tackifiers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Tackifiers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Australia Tackifiers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the global tackifiers market?
The global tackifiers market is estimated at approximately USD 4.70–4.81 Billion in 2026, depending on scope definition, with a consensus forecast of USD 5.80 Billion by 2030 at a 4.9% CAGR.
2. Which region dominates tackifier consumption?
Asia Pacific leads with roughly 38–39% of global revenue, driven by China's packaging boom and India's construction expansion. It is also the fastest-growing region at ~5.25% CAGR through 2031.
3. What are the main types of tackifiers?
Tackifiers fall into three feedstocks: petroleum resins (largest, ~65%), rosin resins (fastest-growing at ~4.95% CAGR), and terpene resins. By type, synthetic grades hold ~65–73% share while natural grades grow faster.
4. What is driving tackifier market growth?
Key drivers include e-commerce packaging demand, APAC infrastructure spending, hygiene product consumption, and regulatory-driven adoption of ultra-low-VOC, food-contact-compliant resin grades in North America and Europe.
5. Who are the leading tackifier manufacturers?
Leading vendors include Eastman Chemical, Kraton Corporation, Ingevity, ExxonMobil, Arkema, Arakawa Chemical, and Zeon Corporation. Market concentration is medium, with no single player exceeding 15% global share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research team applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews across the tackifier value chain, including raw material suppliers (rosin, terpene, and C5/C9 feedstock producers), specialized tackifier manufacturers, contract formulators, and global specialty chemical distributors. Interviewees were drawn from senior decision-making roles — VP of Sourcing, Heads of Adhesive R&D, Technical Directors, and Commercial Operations Leads — ensuring that both technical performance and commercial reality are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
38%
Procurement & Sourcing Leads
32%
Commercial Operations Leads
18%
Regulatory Affairs Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Feedstock Suppliers
30%
Specialized Tackifier Producers
40%
Contract Formulators & Blenders
18%
Global Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
Secondary benchmarking draws on official multilateral and national databases, including UN Comtrade for resin trade flows, US ITC and Eurostat for import/export volumes, SEC 10-K filings and investor presentations from publicly listed producers, patent databases for innovation tracking, and recognized technical standards bodies (ASTM, ISO, and the Pressure Sensitive Tape Council). No proprietary third-party market research is used as a primary validation source.
Demand Modeling & Market Sizing Triangulation
We triangulate market size through simultaneous Top-Down and Bottom-Up approaches. Top-down modeling allocates macroeconomic adhesive and sealant demand by industry segment and region, while bottom-up modeling aggregates manufacturer capacity, realized pricing, and end-use consumption by application. Divergence between the two is reconciled at the segment level.


 Tackifiers Market