 Polyurethane Adhesives Industry
 Market Analysis 2026
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Polyurethane Adhesives Industry

Khageshwar Rongkali
Senior Analyst
| Year | Market Size |
|---|---|
| 2025 | 10.85 B |
| 2026 | 11.59 B |
| 2027 | 12.38 B |
| 2028 | 13.22 B |
| 2029 | 14.12 B |
| 2030 | 15.08 B |
| 2031 | 16.10 B |

The polyurethane adhesives industry market comprises high-performance bonding and sealing chemistries formed by reacting polyols with isocyanates, delivering flexible, durable bonds across metals, plastics, composites, glass, wood, and foams. These adhesives enable lightweighting, vibration damping, and rapid assembly in construction, automotive, footwear, packaging, electronics, and engineered wood applications.
This report covers the global polyurethane adhesives industry market by product type (one-component, two-component), technology (solvent-borne, reactive, hot-melt PUR, dispersion, 100% solids), and end-use (construction, automotive, packaging, electronics, footwear, furniture, industrial), with a 2025 base year and forecast to 2032. This analysis does not cover the broader adhesives and sealants market, polyurethane foams, coatings, or elastomers, nor adjacent epoxy, acrylic, or silicone adhesive chemistries.
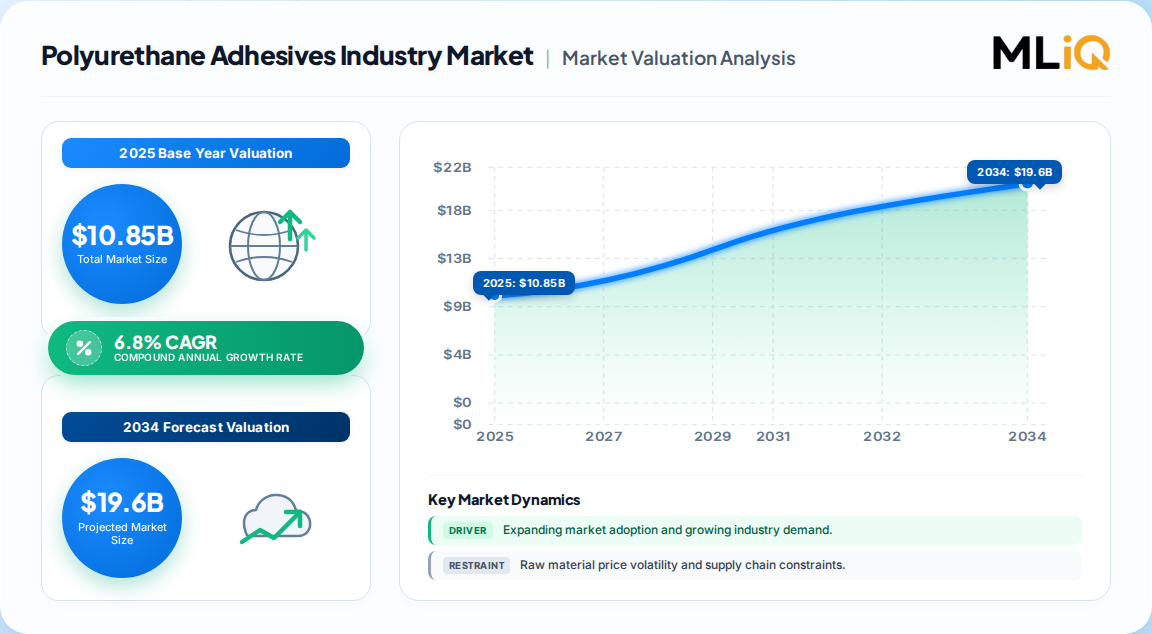
Consensus estimates place the global market between USD 9.8 Billion and USD 10.85 Billion in 2025, converging on a 6.2–6.8% CAGR through the early 2030s. Divergence stems largely from category boundary definitions and differing treatment of solvent-borne versus hot-melt revenue.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 9.82 Billion | 2025 | 2034 | 6.21% | Global PU adhesives, value-only, thermoset/thermoplastic | One published estimate |
| USD 10.85 Billion | 2025 | 2032 | 6.8% | Global PU adhesives by product type & technology | A competing analysis |
| USD 8.4 Billion | 2024 | 2034 | 6.2% | Thermoplastic + thermoset PU, end-use weighted | A third published estimate |
Our analysis suggests the USD 10.85 Billion / 6.8% CAGR figure is the most defensible. It aligns with production-volume benchmarks (~2,300 thousand tonnes in 2022) and is validated by independent end-use indicators — 2024 European CLT output of 1.9 million m³, global EV sales above 17 million units, and 9.28 million replacement windshields. The lower USD 9.82 Billion figure likely excludes certain dispersion and 100% solids formulations.
Segmentation follows three non-geographic axes: product format, application technology, and end-use industry. Construction and automotive together account for over 55% of demand, which concentrates growth exposure in cyclical, capital-intensive verticals.
| Parent Segment | Children |
|---|---|
| By Product Type | One-Component PU, Two-Component PU |
| By Technology | Solvent-Borne, Reactive PU, Hot-Melt PUR, Dispersion, 100% Solids |
| By End-Use | Construction, Automotive & Transportation, Packaging, Electronics, Footwear, Furniture & Decoration, Industrial, Marine, Others |
Notably, reactive PU (40% share, 7.2% CAGR) and one-component PU (55% share, 7.1% CAGR) are converging on the same buyer need — cleaner processing without mixing or solvent evaporation. This overlap implies suppliers should bundle dispensing equipment and adhesive chemistry to lock in automated-line customers.
Asia-Pacific leads the global polyurethane adhesives industry market, holding approximately 42% of 2025 revenue (~USD 4.56 Billion) and growing at the fastest regional CAGR (~7.4%), followed by North America (~25%), Europe (~23%), Latin America (~6%), and the Middle East & Africa (~4%).
| Region | Market Share (%) |
|---|---|
| North America | 0.25% |
| Europe | 0.23% |
| Asia-Pacific | 0.42% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | 2025 Share | Indicative CAGR |
|---|---|---|
| Asia-Pacific | 42% | 7.4% |
| North America | 25% | 6.4% |
| Europe | 23% | 6.2% |
| Latin America | 6% | 6.5% |
| Middle East & Africa | 4% | 6.7% |
The Asia-Pacific lead is structural, not cyclical. China alone recorded 6.4% manufacturing value-added growth in 2025, with strong automotive and electronics expansion. This implies supply-chain localization is increasingly decisive for ASEAN and Indian buyers seeking shorter qualification lead times.
Growth is anchored by automotive lightweighting and construction prefabrication, offset by raw-material volatility and regulatory compliance costs. The net balance strongly favors expansion, but the quality of growth is shifting toward compliant, high-performance formulations.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Automotive electrification & lightweighting | Up | High | Multi-material body structures, battery enclosures, direct glazing |
| Construction & prefabrication | Up | High | CLT, panels, flooring, windows/doors |
| Flexible packaging lamination | Up | Medium-High | Solvent-free laminating adhesives, retort packaging |
| Electronics miniaturization | Up | Medium | Potting, encapsulation, component bonding |
| Raw material (isocyanate/polyol) volatility | Down | High | Margin compression, price pass-through risk |
| REACH / VOC / OSHA regulation | Down | High | Reformulation cost, qualification delay |
| Solvent-based substitution | Down | Medium | Shift to reactive/hot-melt reduces solvent revenue growth |
The regulatory drag is often overstated. EU REACH Annex XVII Entry 74 — requiring diisocyanate safe-use training since August 24, 2023 — is accelerating low-monomer innovation rather than curtailing demand. Suppliers with documented compliance gain a qualification moat; laggards face exclusion from European OEM supply chains. Our analysis suggests compliance is becoming a revenue enabler for tier-1 formulators.
The competitive landscape is fragmented and low-concentration, with no single player exceeding double-digit global share. Differentiated specialty chemical majors compete with regional formulators on formulation breadth, application engineering, and compliance documentation.
| Company | Strategic Positioning | Key Strength |
|---|---|---|
| Henkel AG & Co. KGaA | Global leader | Broad PU portfolio, debond-on-demand R&D |
| H.B. Fuller | Global specialty | Packaging, woodworking, reactive PUR |
| 3M | Diversified | Construction, transportation, electronics |
| Arkema (Bostik) | Global specialty | Automotive, construction, footwear |
| Dow | Chemical major | Polyurethane raw materials & systems |
| Sika AG | Construction-focused | Structural bonding, flooring, facades |
| Huntsman International | Chemical major | PU systems, composites |
| Pidilite Industries | Regional (Asia) | Construction, industrial adhesives |
Competitive moats derive from three sources: application engineering (dispensing equipment coupled with chemistry), regulatory documentation (REACH, FDA food-contact, ISO 4587 test data), and OEM qualification cycles (12–24 months, creating high switching costs). Smaller formulators can compete on regional service but struggle on multi-region compliance breadth.
Buyers face a market where formulation choice is increasingly a compliance decision, not just a performance one. REACH diisocyanate training requirements, OSHA isocyanate exposure limits, and South Coast AQMD Rule 1168 VOC caps materially restrict solvent-borne options in regulated jurisdictions. Procurement teams should prioritize suppliers offering documented low-monomer or solvent-free alternatives with full test data.
Switching costs are highest in automotive and aerospace, where qualification cycles run 12–24 months and requalification is triggered by any formulation change. For construction and packaging, switching is faster but still requires adhesive-substrate compatibility validation. Operators should negotiate multi-year supply agreements with price-indexation clauses tied to isocyanate and polyol benchmarks to manage raw-material volatility. Food-contact packaging laminates additionally require FDA and EU food-contact framework evaluation — a frequent source of compliance gaps in lower-tier suppliers.
The balance of evidence favors reactive and one-component PU chemistries as the structural growth winners through 2032. These formats deliver the cleaner processing, faster cure, and lower VOC profile that both regulators and automated-line operators now demand. Suppliers positioned in solvent-borne-only portfolios face relative growth stagnation (~5.8% CAGR) even as absolute volumes hold. The strongest counter-argument is that solvent-borne formulations retain irreplaceable performance in footwear and demanding laminates — but this is a niche defense, not a growth thesis. Our analysis suggests the debond-on-demand technology layer (Henkel, academic PU networks showing up to 92% shear-strength loss on trigger) could command premium pricing in EV battery and circular-design applications by 2030.
Regional strategy should follow compliance economics. Europe rewards formulation upgrades and low-monomer investment despite slower volume growth; Asia-Pacific rewards capacity localization and application engineering near manufacturing clusters; North America rewards construction and aerospace specialty positioning. Vendors chasing volume alone in Asia-Pacific will face margin pressure from local formulators; vendors chasing margin in Europe must lead on regulatory documentation.
Actionable Strategy:
What would change our conclusion: a faster-than-expected solvent-free substitution curve in footwear, or a regulatory rollback on diisocyanate training requirements that revives solvent-borne economics. While this overview captures strategic direction, precise sub-segment forecasting — particularly by country and application — requires the full report's bottom-up demand model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.8% from 2020-2034 |
| Segmentation |
|
The global polyurethane adhesives industry market was valued at approximately USD 10.85 Billion in 2025, with consensus estimates ranging from USD 9.8 Billion to USD 10.85 Billion depending on category definitions. It is projected to reach USD 17.15 Billion by 2032.
The market is expanding at a CAGR of approximately 6.8% from 2026 to 2032. Estimates range from 6.2% to 6.8%, with the higher end reflecting reactive and one-component PU format growth.
Asia-Pacific leads with approximately 42% of 2025 revenue, equivalent to about USD 4.56 Billion, driven by manufacturing concentration in China, India, and Southeast Asia. It is also the fastest-growing region at ~7.4% CAGR.
Construction is the largest end-use segment at 32% share (USD 3.47 Billion in 2025), followed by automotive at 25%. Automotive is the fastest-growing end-use at approximately 7.3% CAGR, driven by EV and lightweight structures.
Key players include Henkel, H.B. Fuller, 3M, Arkema (Bostik), Dow, Sika, Huntsman, and Pidilite Industries. The market is fragmented with low concentration, and no single player holds a double-digit global share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, anchored in structured interviews across the polyurethane adhesives value chain. We conducted in-depth interviews with raw material suppliers (isocyanate and polyol producers), specialized PU adhesive manufacturers, contract formulators and blenders, and global industrial distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical qualification and commercial procurement dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Technical & Quality Directors | 22% |
| Commercial Operations Leads | 13% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Isocyanate Producers | 30% |
| Specialized PU Adhesive Manufacturers | 40% |
| Contract Formulators & Blenders | 18% |
| Distributors & Traders | 12% |
Quantitative baselines were cross-validated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies. Regulatory references draw on EU REACH Annex XVII Entry 74, US OSHA isocyanate guidance, South Coast AQMD Rule 1168, ISO 4587, and ASTM construction adhesive requirements, alongside industry association publications.
We run simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macroeconomic and industry segment output to PU adhesive intensity by end-use. The Bottom-Up model aggregates manufacturer capacity, product pricing, and end-use consumption volumes, reconciling both to a consensus base-year value of USD 10.85 Billion (2025).
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
