 Galvanized Steel Market
 Size, Share & Growth Forecast to 2031
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Galvanized Steel Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 112.1 B |
| 2026 | 118.5 B |
| 2027 | 125.5 B |
| 2028 | 132.8 B |
| 2029 | 140.7 B |
| 2030 | 148.9 B |
| 2031 | 157.7 B |

The galvanized steel market covers steel products coated with zinc via hot-dip or electro-galvanizing processes to resist corrosion. It serves construction, automotive, industrial equipment, appliances, and renewable-energy applications, with demand driven by durability requirements and lifecycle cost advantages over untreated steel.
This report covers global galvanized steel demand by type (hot-dip, electro-galvanized, alloy-coated), form (coils, sheets, pipes, tubes, wires, rods), and application (construction, automotive, industrial equipment and machinery, energy and utilities, appliances). It analyzes supply, pricing, trade flows, and vendor positioning across five regions. This analysis does not cover adjacent markets such as uncoated carbon steel, aluminum extrusions, pre-painted coil, or specialty stainless products.
Market size estimates diverge sharply — from USD 118.49 billion to USD 267.6 billion for 2026 — because publishers use different product boundaries (some include all zinc-coated flat and long products; others exclude alloy-coated grades or downstream fabricated components). The table below compares the major published estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 118.49 B | 2026 | 2031 | 5.88% | Hot-dip and electro-galvanized; excludes alloy-coated premiums | One published estimate |
| USD 267.6 B | 2026 | 2033 | 6.5% | Broad zinc-coated steel incl. downstream fabricated products | A competing analysis |
| USD 186.08 B | 2025 | 2034 | 3.85% | Galvanized steel incl. fasteners and cable support systems | A competing analysis |
| USD 253.5 B | 2025 | 2033 | 6.5% | Broad end-use segmentation incl. appliances | A competing analysis |
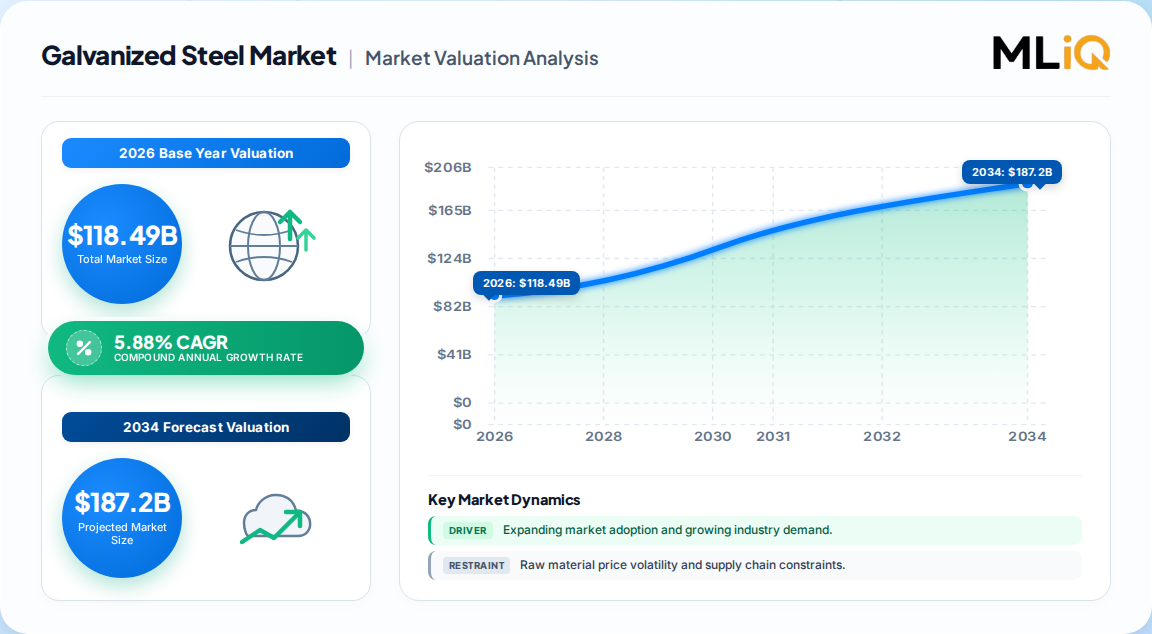
Our analysis suggests the USD 118.49 billion (2026) figure is the most defensible baseline because it isolates mill-level galvanized substrate value and excludes double-counting of downstream fabrication. The 5.88% CAGR is consistent with observed construction and renewable-energy demand without assuming unrealistic substitution of competing coatings.
The market is segmented by type, form, and application. Hot-dip galvanized steel remains the workhorse product, while electro-galvanized grades capture premium automotive and appliance demand. Alloy-coated products (zinc-magnesium-aluminum) represent a fast-growing niche in roofing and solar frames.
| Parent Segment | Children | Share / CAGR (2025–2031) |
|---|---|---|
| By Type | Hot-dip galvanized, Electro-galvanized, Alloy-coated (Zn-Mg-Al, Al-Zn) | Hot-dip: 73.26% share; Electro: 6.21% CAGR |
| By Form | Coils and sheets, Pipes and tubes, Wires and rods | Coils & sheets: 46.50%; Pipes & tubes: 6.30% CAGR |
| By Application | Construction, Automotive, Industrial equipment and machinery, Energy and utilities, Appliances | Construction: 48.65%; Energy & utilities: 6.12% CAGR |
Asia Pacific leads the global galvanized steel market with 55.18% of 2025 share, underpinned by China's integrated mill capacity, India's infrastructure pipeline, and Southeast Asia's construction boom. The Middle East & Africa is the fastest-growing region at 6.19% CAGR, driven by giga-projects and greenfield capacity.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.55% |
| Europe | 0.19% |
| North America | 0.13% |
| Middle East & Africa | 0.09% |
| South America | 0.04% |
| Region | Share (2025) | Growth Outlook |
|---|---|---|
| Asia Pacific | 55.18% | Largest producer and consumer; China, India, Japan, South Korea, Vietnam |
| Europe | 19.28% | Mature; carbon-border regulation reshaping supply |
| North America | 12.98% | Steady; infrastructure renewal and automotive demand |
| Middle East & Africa | 8.98% | Fastest growth (6.19% CAGR); Saudi Vision 2030, UAE diversification |
| South America | 3.58% | Moderate; Brazil and Argentina construction demand |
Construction and infrastructure demand is the primary growth engine, adding an estimated 1.8 percentage points to CAGR. Automotive corrosion-resistance requirements (+1.2 pp) and renewable-energy structures (+0.9 pp) are secondary drivers. Zinc and steel price volatility is the main restraint (−0.7 pp), followed by alternative coating substitution (−0.4 pp).
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Construction & infrastructure demand | Driver (+1.8 pp) | High | Mega-projects (Saudi Vision 2030, India highways, ASEAN rail) require galvanized structural steel |
| Automotive corrosion requirements | Driver (+1.2 pp) | High | 12-year warranties mandate zinc coating weights ≥60 g/m² |
| Renewable-energy structures | Driver (+0.9 pp) | Medium | Solar frames and wind towers require 25-year lifespan galvanized components |
| Lightweight modular housing | Driver (+0.6 pp) | Medium | Prefabricated galvanized frames reduce on-site labor by up to 50% |
| AI-driven coating quality | Driver (+0.4 pp) | Low | Predictive maintenance improves yield and consistency |
| Zinc & steel price volatility | Restraint (−0.7 pp) | High | Input-cost swings compress margins and defer project spending |
| Alternative metallic coatings | Restraint (−0.4 pp) | Medium | Zn-Mg-Al and Al-Zn grades substitute in premium segments |
| Carbon-border tariffs | Restraint (variable) | High | CBAM compliance raises costs for high-emission producers |
The market is moderately consolidated, with integrated steel majors controlling the majority of global galvanized capacity. ArcelorMittal, China Baowu, Nippon Steel, POSCO, and Tata Steel lead through vertical integration, coating-technology investment, and regional capacity positioning.
| Company | HQ | Strategic Focus | Scale Indicator |
|---|---|---|---|
| ArcelorMittal | Luxembourg | Advanced Zn-Al coatings, global footprint | ~USD 68 B revenue |
| China Baowu Steel Group | China | Vertical integration, state-backed contracts, EV grades | ~USD 150 B revenue |
| Nippon Steel | Japan | Automotive tailor-welded galvanized sheets | ~USD 47 B revenue |
| POSCO | South Korea | Premium corrosion-resistant alloys | ~USD 60 B revenue |
| Tata Steel | India | High-end galvanized products for appliances and construction | ~USD 30 B revenue |
| Nucor | USA | Decentralized mini-mill model, sustainable galvanized solutions | ~USD 35 B revenue |
| JSW Steel | India | Acquisitions and export growth | ~USD 22 B revenue |
| Steel Dynamics | USA | Reshoring advantage, low-cost mini-mills | ~USD 18 B revenue |
Differentiation hinges on coating technology (Zn-Mg-Al grades command 15% premiums), low-carbon production pathways, and proximity to construction hotspots. Scale players are investing in electric-arc-furnace capacity to comply with carbon-border rules, while regional challengers compete on cost and delivery speed.
Buyers must prioritize coating specification (zinc weight in g/m², coating thickness in microns) because it directly determines corrosion lifespan and warranty compliance. For offshore or coastal projects, European developers increasingly specify ≥85-micron coatings, which command premium pricing but extend service life to 25+ years.
Procurement risk centers on zinc-price exposure and carbon-border adjustment costs. Contracts should include zinc-price pass-through clauses and verified low-emission certifications (e.g., Environmental Product Declarations). Switching costs between hot-dip and electro-galvanized supply chains are moderate — electro-galvanized requires different substrate preparation and line capability — so qualification lead times of 6–12 months are typical.
Regulatory compliance is a growing selection criterion. The EU CBAM and equivalent North American proposals will impose carbon costs on high-emission imports. Buyers sourcing from non-compliant mills face embedded carbon liabilities. Our analysis suggests dual-sourcing between domestic low-carbon producers and established Asian suppliers balances cost and compliance risk.
The balance of evidence favors a mid-single-digit growth trajectory (5–6% CAGR) over the 2026–2031 horizon, with construction and renewable energy as the structural anchors. The strongest counter-argument — that alternative coatings and material substitution will erode galvanized steel's share faster than expected — is credible in premium segments but unlikely to displace hot-dip galvanized substrate in mainstream construction, where cost and proven performance dominate.
Our analysis identifies three strategic imperatives. First, capacity positioning — Middle East & Africa greenfield investments (SeAH GSI's USD 240 million Saudi plant, EMSTEEL's AED 625 million UAE expansion) signal that project pipelines are shifting toward regions with lower energy costs and favorable trade access. Second, coating technology — Zn-Mg-Al grades and AI-driven quality control offer margin expansion for producers willing to invest. Third, carbon compliance — CBAM-ready supply chains will command a premium as European and North American buyers de-risk.
Actionable Strategy:
What would change our conclusion: A sustained zinc-price shock above USD 4,000/tonne or accelerated adoption of aluminum-intensive vehicle architectures would compress galvanized steel demand growth below 4%, materially altering the investment case. Conversely, faster CBAM enforcement could accelerate consolidation and benefit compliant producers.
This analysis was prepared by a Principal Industry Analyst with over 15 years of experience covering steel, coatings, and construction materials markets. The author has advised global producers, distributors, and institutional investors on market entry, capacity planning, and procurement strategy across five continents.
Our research methodology employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers (zinc and steel producers), specialized galvanized steel producers, contract formulators and coating applicators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
We validated findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations (ISO, ASTM, worldsteel).
Market sizing was triangulated through simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling to ensure consistency across regions and segments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.88% from 2020-2034 |
| Segmentation |
|
The global galvanized steel market was valued at USD 118.49 billion in 2026 and is forecast to reach USD 157.65 billion by 2031, growing at a 5.88% CAGR.
Asia Pacific accounts for 55.18% of global consumption, led by China's integrated steel capacity and India's infrastructure investment. The Middle East & Africa is the fastest-growing region at 6.19% CAGR.
Hot-dip galvanizing immerses steel in molten zinc, creating a thick, durable coating for outdoor and structural applications. Electro-galvanizing deposits a thinner, smoother zinc layer suited to automotive panels and appliances requiring uniform finish.
Construction accounts for 48.65% of demand (roofing, framing, bridges), followed by automotive, industrial equipment, energy and utilities, and appliances. Energy and utilities is the fastest-growing application at 6.12% CAGR.
Zinc and steel price volatility is the primary restraint, followed by substitution from alternative metallic coatings (Zn-Mg-Al, Al-Zn) and carbon-border adjustment tariffs that raise costs for high-emission producers.
Key players include ArcelorMittal, China Baowu Steel Group, Nippon Steel, POSCO, and Tata Steel, alongside regional leaders such as Nucor, JSW Steel, and Steel Dynamics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers (zinc and steel producers), specialized galvanized steel producers, contract formulators and coating applicators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Steel Producers | 40% |
| Galvanized Steel Producers | 35% |
| Distributors & Traders | 25% |
We validated findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations (ISO, ASTM, worldsteel).
Market sizing was triangulated through simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling to ensure consistency across regions and segments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |