Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Kaolin Market Size, Forecast & Industry Outlook 2026
Kaolin Market
Kaolin Market Size, Forecast & Industry Outlook 2026
Kaolin Market by Form (Processed Kaolin, Crude/Unprocessed Kaolin), by Grade (Hydrous Kaolin, Calcined Kaolin, Delaminated Kaolin, Surface-treated and Other Grades), by Application (Ceramics, Paper, Paints and Coatings, Cement, Refractories, Plastics, Rubber, Fiberglass, Cosmetics, Pharmaceuticals and Medical), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Poland), by Asia Pacific (China, India, Japan, South Korea), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, Turkey, South Africa) Forecast 2026-2034
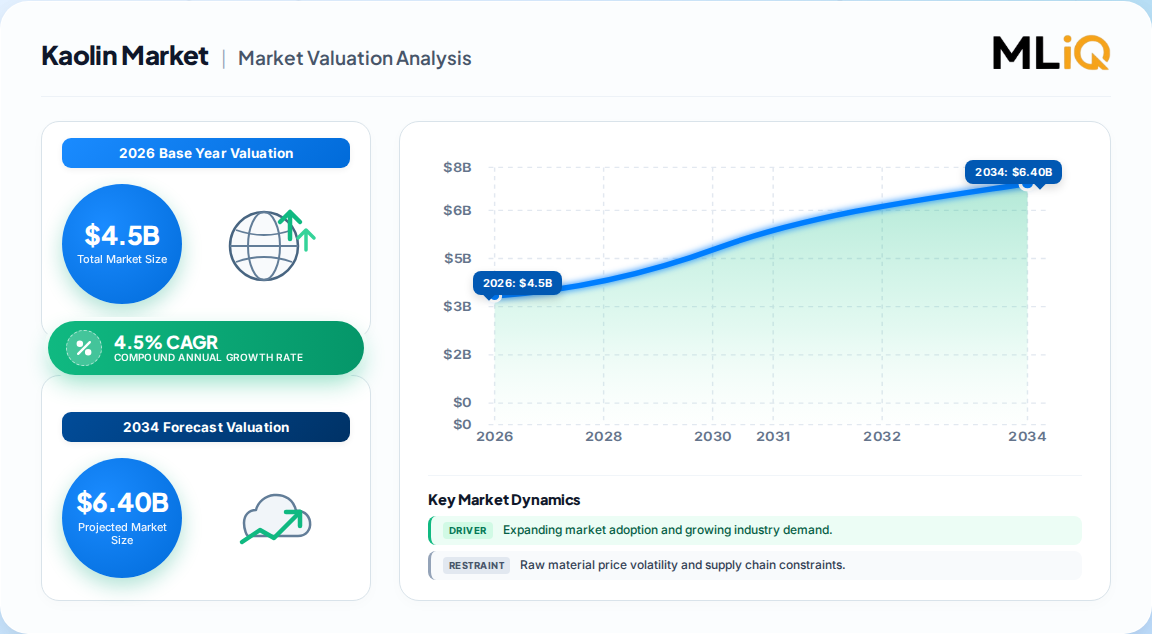
USD 4.5 billion in 2026, the global kaolin market expands to roughly USD 8.2 billion by 2035, implying a mid-single-digit compound trajectory.
Published CAGRs cluster between 3.7% and 4.6%, a spread that reflects differing treatment of calcined grades and cement-linked volumes, not genuine demand disagreement.
Ceramics is the largest application at roughly 37% of value, having overtaken paper as tile and sanitaryware capacity moved decisively to Asia.
Asia-Pacific commands about 47% of global value and grows fastest (~5.3% CAGR); North America holds ~22%, Europe ~20% under carbon-cost pressure.
Calcined kaolin is the premium growth engine, penetrating architectural coatings and lithium-ion separator coatings at 5%+ annual rates.
Leading producers include Imerys, KaMin/CADAM, Sibelco, Quarzwerke, Ashapura Group, EICL and 20 Microns.
Why this matters for decision-makers: value is migrating from washed filler grades to high-brightness calcined capacity, so capital allocation to beneficiation and calcination — not mine volume — will determine margin leadership through 2035.
Kaolin Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.300 B
2025
4.500 B
2026
4.700 B
2027
4.910 B
2028
5.140 B
2029
5.370 B
2030
5.610 B
2031
Kaolin Market Size (In Billion)
Year
Market Size
2025
4.300 B
2026
4.500 B
2027
4.700 B
2028
4.910 B
2029
5.140 B
2030
5.370 B
2031
5.610 B
What is the Kaolin Market?
The kaolin market covers the mining, beneficiation and calcination of kaolinitic clays, sold as hydrous, calcined or delaminated grades for paper, ceramics, paints and coatings, plastics, rubber, fiberglass, cement and pharmaceuticals. Value is increasingly set by brightness, iron content and particle engineering rather than raw tonnage.
Scope: what this report covers and excludes
This analysis covers processed and crude kaolin across hydrous, calcined, delaminated and surface-treated grades, segmented by application and region, with 2025 as base year and forecasts to 2035. This analysis does not cover halloysite, metakaolin sold purely as a cement substitute, bentonite, calcium carbonate, talc, or general industrial minerals used as competing extenders.
How big is the market for Kaolin Market?
Estimates converge on a base of roughly USD 4.3–5.5 billion in 2025–2026, with the divergence driven mainly by whether cement-linked and crude volumes are included and which grade mix is weighted.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 4.3B → 5.8B
2025
2033
3.7%
Application-led, paper-heavy weighting
One published estimate
USD 5.24B → 8.2B
2025
2035
4.58%
Form, grade and application; includes cement
A competing analysis
USD 5.48B (2026)
2026
2035
4.58%
Same series, forward base year
A competing analysis
USD 4.1B → 6.1B
2024
2034
4.0%
Grade-led with calcined dominance
A competing analysis
Our analysis suggests the 4.3–4.6% band is the most defensible planning range. The lower 3.7% figure leans on paper, where structural graphic-paper decline is real; the higher figures capture calcined premiumisation and cement pozzolan demand that paper-centric models understate. Buyers should budget at 4.2% and stress-test at 3.5%.
How is the market segmented?
The market segments by form, grade and application, with grade the strongest value driver because calcination multiplies realized price several-fold over crude clay.
Parent
Children
By Form
Processed kaolin, Crude/unprocessed kaolin
By Grade
Hydrous, Calcined, Delaminated, Surface-treated and other grades
By Application
Ceramics, Paper, Paints and coatings, Cement, Refractories, Plastics, Rubber, Fiberglass, Cosmetics, Pharmaceuticals and medical
Processed kaolin held roughly 65% of 2025 value, while crude grows faster as emerging producers pursue backward integration. Hydrous remains the volume backbone (~52%), but calcined is where pricing power sits.
Which region leads in Kaolin Market?
Asia-Pacific leads with approximately 47% of global value, anchored by Chinese and Indian tile and sanitaryware clusters, and grows fastest at roughly 5.3% annually.
Kaolin Market Regional Market Share
Loading chart...
Kaolin Market Regional Market Share
Region
Market Share (%)
North America
0.22%
Europe
0.2%
Asia-Pacific
0.47%
Latin America
0.06%
Middle East & Africa
0.05%
Asia-Pacific — China, India, Japan, South Korea, Southeast Asia
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Poland
Latin America — Brazil, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, Turkey, South Africa
Region
Share (2025)
Growth posture
Asia-Pacific
~47%
Fastest, tile-led
North America
~22%
Stable, low-cost calcination gas
Europe
~20%
Subdued, carbon-cost exposed
Latin America
~6%
Moderate, infrastructure-led
Middle East & Africa
~5%
Emerging, construction-led
India's Morbi cluster alone absorbs over 4 million tonnes annually, making it the single largest demand node. North America's Georgia belt remains the cost benchmark for soft-rock clay, while Europe's disadvantage is energy, not resource.
What is driving growth — and what is holding it back?
Growth is driven by Asian tile capacity, titanium dioxide substitution in coatings, and battery separator coating adoption; it is restrained by graphic paper decline, calcination energy inflation and ground calcium carbonate substitution.
Recycled fibre and digital media erode filler demand
Energy cost inflation
Down
Strong
Calcination at 1,000–1,100°C is gas-intensive
GCC/PCC substitution
Down
Moderate
Cost-competitive in paper and plastics fillers
The balance favors growth, but the composition is shifting. Volume gains are commoditising at the crude end while value concentrates in calcined and surface-treated grades. The implication: producers without calcination capacity will grow tonnage and lose margin simultaneously.
Who are the leading vendors?
Imerys leads on global scale and grade breadth, with KaMin/CADAM dominant in North American hydrous clay, Sibelco and Quarzwerke strong in Europe, and Ashapura, EICL and 20 Microns driving Asian processing capacity.
Company
Positioning
Notable strength
Imerys
Global leader, diversified grades
Portfolio breadth, life sciences and filtration
KaMin / CADAM
North America and Brazil
Georgia belt resource, hydrous speciality
Sibelco
Europe and global distribution
Industrial minerals breadth
Quarzwerke
European speciality
Processing and technical service
Ashapura Group
Asia and Middle East
Bleaching earth and clay integration
EICL / 20 Microns
India processing
190,000–280,000 t added capacity by 2027
Differentiation rests on resource quality, calcination energy cost and qualification cycles rather than brand. Private-equity recapitalisation of mineral assets has accelerated debottlenecking but also raised expectations of margin discipline.
What do buyers and operators need to know?
Qualification is the real switching cost. Replacing a kaolin grade in a paint, paper coating or ceramic body requires reformulation and re-validation, typically 3–9 months, and 18–30 months in battery separator coatings. Buyers should therefore contract on brightness and iron specification stability, not headline price.
Supply risk is concentrated geographically. Single-origin dependence on the Georgia belt or Brazilian crude leaves buyers exposed to freight, permitting and energy shocks. Dual-sourcing across at least two continents is now standard practice among tier-one formulators.
Regulatory exposure is rising. Mining permits, water use and land rehabilitation increasingly determine project timelines, while EU carbon pricing flows through calcination costs. Operators should model carbon cost per tonne into grade economics before committing capital.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a premiumisation thesis over a volume thesis. Base-case growth of ~4.2% understates the value shift toward calcined and surface-treated grades, where pricing and qualification barriers protect margins. The strongest counter-argument is that titanium dioxide substitution and battery coating adoption are recipe changes that could plateau or reverse if TiO2 prices fall sharply, compressing extender demand faster than expected.
Our second-order read is that the crude-to-processed price spread near 3.1x will narrow as new beneficiation capacity in India and the US Gulf comes online by 2027. That does not erode the market — it compresses the advantage of merchant upgraders while rewarding integrated producers with captive feedstock and low-cost calcination energy.
Investors: prioritise calcination capacity and energy contracts in North America and India; treat pure crude mining exposure as a value trap.
Producers: lock multi-year supply agreements in battery-grade separator and barrier packaging niches before qualification cycles close.
Buyers: dual-source across regions and specify brightness and Fe₂O₃ tolerances, not generic grade names.
The evidence that would change our conclusion: a sustained TiO2 price collapse below USD 2,500/tonne, or a slowdown in Indian tile commissioning below 200 million m² annually.
Kaolin Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Kaolin Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.5% from 2020-2034
Segmentation
By Form
Processed Kaolin
Crude/Unprocessed Kaolin
By Grade
Hydrous Kaolin
Calcined Kaolin
Delaminated Kaolin
Surface-treated and Other Grades
By Application
Ceramics
Paper
Paints and Coatings
Cement
Refractories
Plastics
Rubber
Fiberglass
Cosmetics
Pharmaceuticals and Medical
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Poland
Asia Pacific
China
India
Japan
South Korea
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
Turkey
South Africa
Table of Contents
1. Kaolin Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Kaolin Market Executive Summary
2.1. Market Snapshot
3. Kaolin Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Kaolin Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Kaolin Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Form
5.1.1. Processed Kaolin
5.1.2. Crude/Unprocessed Kaolin
5.2. Analysis, Insights and Forecast - by Grade
5.2.1. Hydrous Kaolin
5.2.2. Calcined Kaolin
5.2.3. Delaminated Kaolin
5.2.4. Surface-treated and Other Grades
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Ceramics
5.3.2. Paper
5.3.3. Paints and Coatings
5.3.4. Cement
5.3.5. Refractories
5.3.6. Plastics
5.3.7. Rubber
5.3.8. Fiberglass
5.3.9. Cosmetics
5.3.10. Pharmaceuticals and Medical
5.4. Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. Kaolin Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Form
6.1.1. Processed Kaolin
6.1.2. Crude/Unprocessed Kaolin
6.2. Analysis, Insights and Forecast - by Grade
6.2.1. Hydrous Kaolin
6.2.2. Calcined Kaolin
6.2.3. Delaminated Kaolin
6.2.4. Surface-treated and Other Grades
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Ceramics
6.3.2. Paper
6.3.3. Paints and Coatings
6.3.4. Cement
6.3.5. Refractories
6.3.6. Plastics
6.3.7. Rubber
6.3.8. Fiberglass
6.3.9. Cosmetics
6.3.10. Pharmaceuticals and Medical
7. Kaolin Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Form
7.1.1. Processed Kaolin
7.1.2. Crude/Unprocessed Kaolin
7.2. Analysis, Insights and Forecast - by Grade
7.2.1. Hydrous Kaolin
7.2.2. Calcined Kaolin
7.2.3. Delaminated Kaolin
7.2.4. Surface-treated and Other Grades
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Ceramics
7.3.2. Paper
7.3.3. Paints and Coatings
7.3.4. Cement
7.3.5. Refractories
7.3.6. Plastics
7.3.7. Rubber
7.3.8. Fiberglass
7.3.9. Cosmetics
7.3.10. Pharmaceuticals and Medical
8. Kaolin Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Form
8.1.1. Processed Kaolin
8.1.2. Crude/Unprocessed Kaolin
8.2. Analysis, Insights and Forecast - by Grade
8.2.1. Hydrous Kaolin
8.2.2. Calcined Kaolin
8.2.3. Delaminated Kaolin
8.2.4. Surface-treated and Other Grades
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Ceramics
8.3.2. Paper
8.3.3. Paints and Coatings
8.3.4. Cement
8.3.5. Refractories
8.3.6. Plastics
8.3.7. Rubber
8.3.8. Fiberglass
8.3.9. Cosmetics
8.3.10. Pharmaceuticals and Medical
9. Kaolin Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Form
9.1.1. Processed Kaolin
9.1.2. Crude/Unprocessed Kaolin
9.2. Analysis, Insights and Forecast - by Grade
9.2.1. Hydrous Kaolin
9.2.2. Calcined Kaolin
9.2.3. Delaminated Kaolin
9.2.4. Surface-treated and Other Grades
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Ceramics
9.3.2. Paper
9.3.3. Paints and Coatings
9.3.4. Cement
9.3.5. Refractories
9.3.6. Plastics
9.3.7. Rubber
9.3.8. Fiberglass
9.3.9. Cosmetics
9.3.10. Pharmaceuticals and Medical
10. Kaolin Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Form
10.1.1. Processed Kaolin
10.1.2. Crude/Unprocessed Kaolin
10.2. Analysis, Insights and Forecast - by Grade
10.2.1. Hydrous Kaolin
10.2.2. Calcined Kaolin
10.2.3. Delaminated Kaolin
10.2.4. Surface-treated and Other Grades
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Ceramics
10.3.2. Paper
10.3.3. Paints and Coatings
10.3.4. Cement
10.3.5. Refractories
10.3.6. Plastics
10.3.7. Rubber
10.3.8. Fiberglass
10.3.9. Cosmetics
10.3.10. Pharmaceuticals and Medical
11. Kaolin Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Kaolin Market Research Methodology
List of Figures
Figure 1: Kaolin Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Kaolin Market Revenue (Billion), by Form 2026 & 2034
Figure 3: North America Kaolin Market Revenue Share (%), by Form 2026 & 2034
Figure 4: North America Kaolin Market Revenue (Billion), by Grade 2026 & 2034
Figure 5: North America Kaolin Market Revenue Share (%), by Grade 2026 & 2034
Figure 6: North America Kaolin Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Kaolin Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Kaolin Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Kaolin Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Kaolin Market Revenue (Billion), by Form 2026 & 2034
Figure 11: Europe Kaolin Market Revenue Share (%), by Form 2026 & 2034
Figure 12: Europe Kaolin Market Revenue (Billion), by Grade 2026 & 2034
Figure 13: Europe Kaolin Market Revenue Share (%), by Grade 2026 & 2034
Figure 14: Europe Kaolin Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Kaolin Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Kaolin Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Kaolin Market Revenue Share (%), by Country 2026 & 2034
Asia Pacific Kaolin Market Revenue (Billion), by Form 2026 & 2034
List of Tables
Table 1: Kaolin Market Revenue Billion Forecast, by Form 2020 & 2034
Table 17: UK Kaolin Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How large is the kaolin market in 2026?
The global kaolin market is valued at approximately USD 4.5 billion in 2026, with published estimates ranging from USD 4.3 billion to USD 5.5 billion depending on whether cement-linked and crude volumes are included.
2. What is the kaolin market growth rate?
Forecast CAGRs cluster between 3.7% and 4.6% through the early 2030s. A planning range of roughly 4.2% is defensible, with the higher end capturing calcined premiumisation and battery separator demand.
3. Which application consumes the most kaolin?
Ceramics is now the largest application at roughly 37% of value, driven by vitrified tile and sanitaryware capacity in India and China. Paper remains significant at around a third but is structurally declining in graphic grades.
4. Which region dominates kaolin demand?
Asia-Pacific holds approximately 47% of global value and grows fastest at about 5.3% annually. North America and Europe follow at roughly 22% and 20% respectively, with Europe constrained by calcination energy costs.
5. Who are the leading kaolin producers?
Key producers include Imerys, KaMin/CADAM, Sibelco, Quarzwerke Group, Ashapura Group, EICL and 20 Microns. Differentiation rests on resource quality, calcination energy cost and end-use qualification depth.
6. What is driving kaolin demand growth?
Three forces dominate: Asian tile and sanitaryware capacity build-out, titanium dioxide substitution in architectural coatings, and calcined kaolin adoption in lithium-ion battery separator coatings.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with kaolin miners and raw clay suppliers, specialised calcined-grade producers, contract formulators and blenders, and global industrial distributors. Decision-maker designations interviewed include VP-level Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both demand-side specification behaviour and supply-side capacity economics are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
35%
R&D & Technical Directors
30%
Commercial Operations Leads
22%
Quality & Regulatory Managers
13%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Kaolin Miners & Raw Clay Suppliers
32%
Calcined & Speciality Grade Producers
38%
Formulators & Blenders
18%
Global Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
We validate against UN Comtrade and WTO flows for HS 2507, US ITC and Eurostat trade statistics, company annual filings and investor presentations, patent databases tracking calcination and surface-treatment innovation, and technical standards from recognised industry associations.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic and industry segment allocation runs simultaneously with bottom-up manufacturer capacity, grade-weighted pricing and end-use consumption modelling. Divergences between the two approaches are reconciled at the application-region level before headline values are finalised.


 Kaolin Market