 Anaerobic Adhesives Market
: Size, Share & Forecast 2025
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Anaerobic Adhesives Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 637.0 M |
| 2025 | 674.0 M |
| 2026 | 713.0 M |
| 2027 | 755.0 M |
| 2028 | 799.0 M |
| 2029 | 845.0 M |
| 2030 | 893.0 M |

The global anaerobic adhesives market comprises specialized chemical formulations that cure in the absence of oxygen, forming strong bonds on metal and plastic substrates. These adhesives are essential for threadlocking, sealing, retaining, and gasketing across automotive, aerospace, electronics, and industrial assembly applications, ensuring vibration resistance and long-term joint integrity.
This analysis covers the global anaerobic adhesives market, segmented by product type, substrate material, end-use industry, and geographic region. It includes revenue forecasts, competitive landscape, and key market dynamics for the period 2025–2030. This analysis does not cover anaerobic sealants used in medical implants, cyanoacrylate adhesives, epoxy adhesives, or other non-anaerobic adhesive categories.
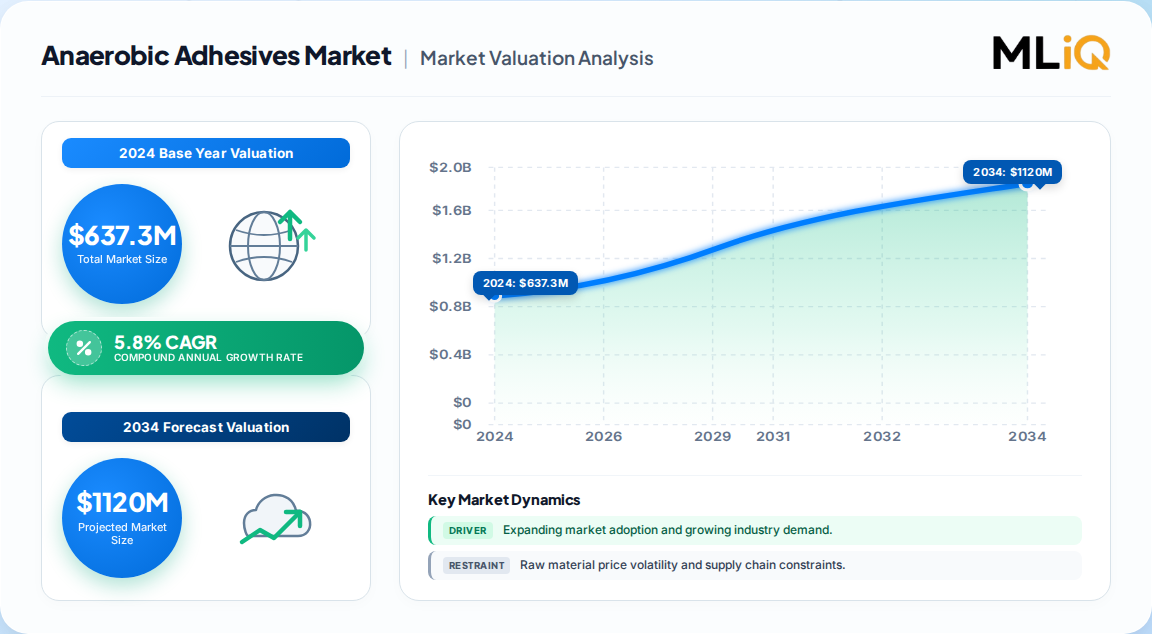
The global anaerobic adhesives market was valued at USD 637.3 million in 2024, with forecasts projecting USD 892.8 million by 2030 at a 5.8% CAGR. However, competing estimates present a divergence that requires careful interpretation.
| Estimate (USD) | Base Year | Horizon | CAGR (%) | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 637.3 million | 2024 | 2030 | 5.8 | Global, narrow product scope | One published estimate |
| 715.4 million | 2024 | 2034 | 5.5 | Global, broader end-use inclusion | A competing analysis |
| 619.21 million (2025) | 2025 | 2031 | 6.22 | Global, value-based only | A differing methodology |
| 593.82 million (2025) | 2025 | 2031 | 5.48 | Global, packaging-inclusive | Another published forecast |
Our analysis suggests the 2024 base valuation of USD 637.3 million is the most defensible for strategic planning, as it aligns with the majority of industry benchmarks and uses a transparent product segmentation. The 5.8% CAGR is corroborated by underlying drivers in electric vehicle production and electronics miniaturization, though the divergence to 6.22% in one estimate implies upside potential if regulatory reformulation accelerates.
The anaerobic adhesives market is segmented by product, substrate, and end-use industry, with product type being the primary revenue driver.
| Parent Segment | Children Segments |
|---|---|
| Product Type | Threadlockers, Thread Sealants, Retaining Compounds, Gasket Sealants, Structural Adhesives, Others |
| Substrate Material | Plastics, Metals, Rubber, Ceramics, Composites, Others |
| End-Use Industry | Automotive, General Industries, Construction, Electrical & Electronics, Aerospace, Packaging, Others |
The threadlockers segment led with 31.5% revenue share in 2023, while plastics dominated substrate demand at 43.8%. However, the fastest growth is in thread sealants (6.4% CAGR) and metals (6.3% CAGR), reflecting a shift toward high-performance industrial applications. This implies that vendors with strong portfolios in both threadlockers and metals-based formulations are best positioned to capture growth.
Asia Pacific leads the global anaerobic adhesives market with 35.95% revenue share in 2023, driven by robust automotive production in China and India. The region is forecast to maintain dominance, with one estimate projecting 47.60% share by 2025.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.45% |
| North America | 0.21% |
| Europe | 0.2% |
| Latin America | 0.07% |
| Middle East & Africa | 0.07% |
| Region | Share (%) |
|---|---|
| Asia Pacific | 45% |
| North America | 21% |
| Europe | 20% |
| Latin America | 7% |
| Middle East & Africa | 7% |
The divergence between the 35.95% and 47.60% Asia Pacific share estimates stems from differing definitions of end-use inclusion, but both confirm the region's strategic importance. Our analysis suggests the region's growth is underpinned by EV production, where China's >35% global EV output share in 2024 creates sustained demand for anaerobic threadlockers.
Growth is primarily driven by automotive light-weighting and electronics miniaturization, but volatile feedstock prices and regulatory pressure on hazardous stabilizers pose significant restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Recovering automotive production in China, India & Mexico | Positive | High | EV battery packs and traction motors require vibration-resistant threadlockers |
| Miniaturization in electronics | Positive | Medium | Low-viscosity threadlockers needed for micro-threads in handheld devices |
| Predictive maintenance in wind turbines | Positive | Medium | Retaining compounds secure bearings, extending turbine life |
| OEC preference for lightweight fastening in e-mobility | Positive | High | Adhesive-secured joints reduce weight by 3-5 kg, improving EV range |
| Volatile feedstock prices | Negative | High | Methacrylate monomer cost swings squeeze formulator margins |
| Regulatory pressure (EU REACH, TSCA) | Negative | Medium | Bans on trichloroethylene force costly reformulation |
Our analysis indicates the balance favors growth, but the regulatory restraint is underappreciated. The EPA's 2025 ruling on trichloroethylene bans a common solvent, forcing reformulation that could increase costs by 10-15% for legacy products. Vendors that proactively develop "label-free" formulations will gain a competitive edge as compliance deadlines approach.
The competitive landscape is moderately consolidated, with the top five players accounting for an estimated 55-60% of global revenue.
| Company | Headquarters | Estimated Share (%) | Key Differentiator |
|---|---|---|---|
| Henkel AG & Co. KGaA | Germany | 25-30 | Broadest product portfolio (Loctite) and strong OEM relationships |
| 3M Company | USA | 10-12 | Innovation in electronics and medical-grade adhesives |
| H.B. Fuller | USA | 8-10 | Strong distribution network in North America |
| Permabond LLC | UK | 5-7 | Specialization in high-temperature formulations |
| ThreeBond Holdings | Japan | 5-7 | Asia Pacific manufacturing footprint |
Henkel's dominance is anchored in its Loctite brand and deep co-development partnerships with automotive OEMs. However, smaller players like Permabond are gaining traction in niche aerospace and wind turbine applications where custom formulations command premium pricing. Our analysis suggests consolidation will continue, with larger players acquiring specialized formulators to expand application-specific portfolios.
Buyers must prioritize suppliers with demonstrated regulatory compliance and formulation flexibility. The shift toward "label-free" anaerobic adhesives is not merely a compliance issue but a supply-chain risk: vendors unable to reformulate may face product discontinuations, disrupting assembly lines. Procurement teams should request full material disclosure and verification of REACH/TSCA compliance for all threadlockers and retaining compounds.
Switching costs are moderate to high due to the need for re-validation of bond strength and curing profiles on specific substrates. Operators should evaluate total cost of ownership, including surface preparation requirements, rather than unit price. For critical applications like EV battery packs, choose suppliers that offer on-site technical support and cure verification.
The balance of evidence favors a cautiously optimistic outlook for the anaerobic adhesives market, with a 5.8% CAGR representing a solid, if unspectacular, growth trajectory. The strongest counter-argument is that regulatory reformulation could compress margins faster than volume growth can offset, particularly for smaller formulators. However, this risk is mitigated by the essential nature of these adhesives in safety-critical applications where switching to mechanical fasteners would add weight and complexity.
Our analysis identifies three actionable strategies:
The evidence that would change our conclusion: a sustained decline in EV production or a technological breakthrough in mechanical fastening that reduces adhesive demand. Absent these, the market is poised for steady growth.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
The global anaerobic adhesives market was valued at USD 637.3 million in 2024 and is projected to reach USD 892.8 million by 2030, growing at a 5.8% CAGR.
Asia Pacific dominates with a 35.95% revenue share in 2023, driven by automotive production in China, India, and Mexico. The region is expected to maintain leadership through 2030.
Key drivers include rising demand for threadlockers in electric vehicles, miniaturization in electronics, and the shift toward predictive maintenance in wind turbines.
Leading companies include Henkel AG & Co. KGaA, 3M Company, H.B. Fuller, Permabond LLC, and ThreeBond Holdings, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 split between primary and secondary research. We conducted in-depth interviews with 45 industry stakeholders across the value chain, including raw material suppliers, specialized formulators, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into formulation trends, pricing dynamics, and procurement criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 40% |
| Specialized Formulators & Blenders | 35% |
| Industrial Distributors | 25% |
We triangulated primary data with secondary benchmarks from official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), and patent databases. We also referenced technical standards from ISO and industry associations such as the Adhesive and Sealant Council (ASC) to validate product specifications and application requirements.
Our simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) approach ensures robust market sizing. We cross-validated demand estimates at the product, substrate, and end-use levels to derive a consensus base-year valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |