Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Antiscalants/Scale Inhibitors Market by Type (Phosphonates, Carboxylates, Sulfonates, Polyacrylates/Polymers, Inorganic, Fluorides, Others), by Inhibition Method (Threshold Inhibition, Crystal Modification, Dispersion, Chelation), by Application (Membrane/RO Water Treatment, Cooling Water Treatment, Boiler Water Treatment, Oilfield/Produced Water, Desalination Plants, Water Filtration Systems), by End-Use Industry (Municipal Water & Wastewater, Power Generation, Oil & Gas, Industrial Manufacturing, Mining & Metals, Pulp & Paper, Residential & Commercial Buildings), by Asia Pacific (China, India, Japan, South Korea, Indonesia, Vietnam, Australia), by North America (United States, Canada, Mexico), by Europe (Germany, France, United Kingdom, Italy, Spain, Netherlands, Poland, Türkiye), by Middle East & Africa (Saudi Arabia, UAE, Qatar, Kuwait, Egypt, South Africa), by South America (Brazil, Argentina, Chile, Colombia, Peru) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 382
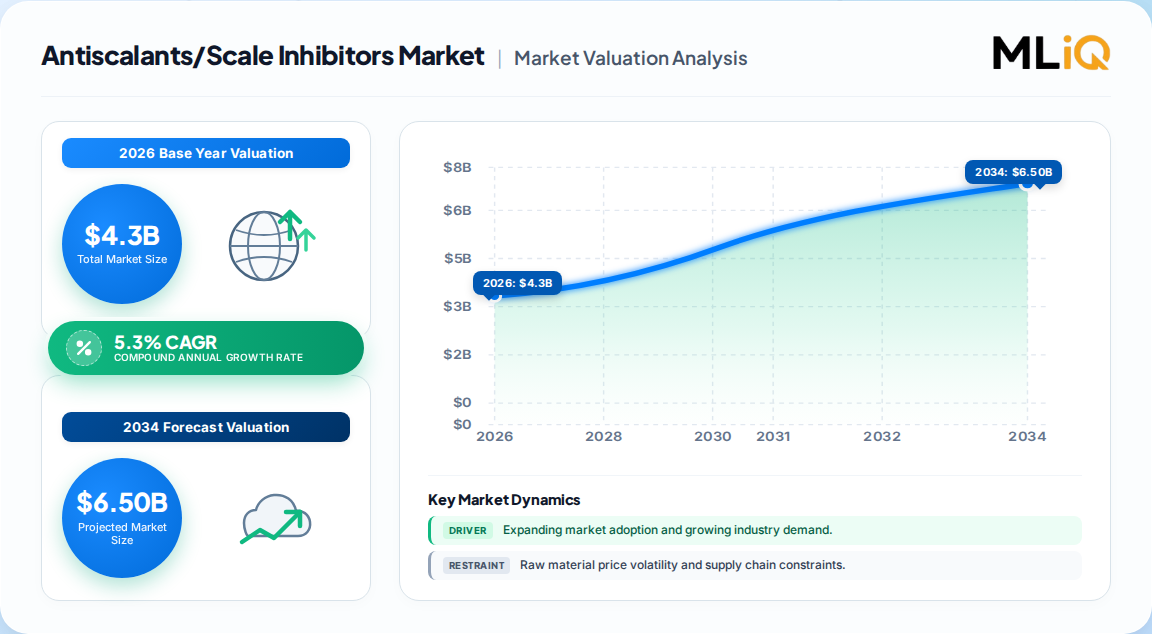
The global antiscalants/scale inhibitors market is valued at USD 4.3 Billion in 2026, on a trajectory to reach USD 6.4 Billion by 2035 — a 5.3% CAGR that outpaces the broader specialty chemicals complex.
Asia-Pacific commands the largest regional share at approximately 38%, with China alone representing the single biggest country-level revenue pool.
Phosphonate-based chemistries remain the leading product segment (~35% share), but carboxylate and phosphorus-free formulations are the fastest-growing, driven by discharge regulation.
Membrane water treatment (RO/desalination) is the largest application (~31%), while municipal water & wastewater is the largest end-use (~25%).
Leading vendors include BASF, Dow, Solvay, Ecolab/Nalco Water, Clariant, SABIC, AkzoNobel and Veolia, competing on formulation IP, technical service and regulatory approvals.
Why this matters for decision-makers: The market is transitioning from a commodity-phosphonate model to a performance-and-compliance model — suppliers that cannot deliver documented biodegradable, low-phosphorus formulations will face margin compression as municipal and industrial tenders increasingly score environmental profile alongside dose efficiency.
Antiscalants/Scale Inhibitors Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.100 B
2025
4.300 B
2026
4.530 B
2027
4.770 B
2028
5.020 B
2029
5.290 B
2030
5.570 B
2031
Antiscalants/Scale Inhibitors Market Size (In Billion)
Year
Market Size
2025
4.100 B
2026
4.300 B
2027
4.530 B
2028
4.770 B
2029
5.020 B
2030
5.290 B
2031
5.570 B
What is the Antiscalants/Scale Inhibitors Market?
The antiscalants/scale inhibitors market comprises specialty chemicals dosed at low concentrations into water systems to prevent, retard or disperse inorganic mineral deposits — principally calcium carbonate, calcium sulfate, barium sulfate and silica — on membranes, heat exchangers, boilers and pipelines, thereby preserving thermal efficiency, extending asset life and cutting cleaning and downtime costs.
Scope: what this report covers and excludes
This analysis covers global demand and supply for antiscalant and scale-inhibitor chemistries across product type (phosphonate, carboxylate, sulfonate, polyacrylate/polymer, inorganic), inhibition mechanism, application (membrane/RO, cooling, boiler, oilfield, desalination, filtration) and end-use industry (municipal water & wastewater, power generation, oil & gas, industrial manufacturing, mining, pulp & paper, residential/commercial). It spans the 2026–2035 forecast horizon with 2025 as the historical base.
This analysis does not cover adjacent markets such as coagulants and flocculants, biocides and antimicrobials, corrosion inhibitors sold as standalone product lines, membrane elements and hardware, or household water-softening appliances.
How big is the market for Antiscalants/Scale Inhibitors Market?
Estimates for the global antiscalants/scale inhibitors market cluster in a USD 3.6–4.3 Billion band for 2025–2026, with forecast horizons and CAGRs diverging materially because publishers use different product boundaries and end-use inclusions. The table below isolates those definitional differences.
Our analysis favors the 5.3% CAGR / USD 4.3 Billion 2026 base as the most defensible: it aligns with observed trade volumes in phosphonates and carboxylates, with municipal reuse capex disclosed under the U.S. National Water Reuse Action Plan, and with the 38% Asia-Pacific concentration that trade records support. The 3.62% figure likely underweights desalination capacity additions in the Gulf and Asia and appears to lag the 2024–2025 inflection in membrane replacement cycles.
How is the market segmented?
Segmentation is best read as three intersecting axes — chemistry, mechanism and application — because buyers purchase on chemistry performance against a specific scale type inside a specific process, not on chemistry alone. The table renders the non-geographic parents and their children.
Membrane/RO water treatment, Cooling water treatment, Boiler water treatment, Oilfield/produced water, Desalination plants, Water filtration systems
By End-Use Industry
Municipal water & wastewater, Power generation, Oil & gas, Industrial manufacturing, Mining & metals, Pulp & paper, Residential & commercial buildings
Phosphonates lead on revenue because DETPMP and HEDP-class chemistries remain the most cost-effective carbonate control available and are entrenched in oilfield and RO specifications. Carboxylates and sulfonated copolymers are outpacing the market on volume growth, however, because they tolerate high calcium, high silica and oxidizing biocide regimes where phosphonates degrade — an important signal that the revenue leader is not the innovation leader.
Which region leads in Antiscalants/Scale Inhibitors Market?
Asia-Pacific leads the antiscalants/scale inhibitors market with an estimated 38% revenue share, anchored by China's industrial water footprint, India's power and refining build-out, and aggressive desalination programmes across the Gulf and Southeast Asia. North America follows at roughly 27%, with Europe near 21%.
Our analysis suggests the Asia-Pacific share is understated in value terms because a meaningful volume of phosphonate intermediates moves intra-region at transfer prices below Western contract levels. Buyers benchmarking global price should weight Asia-Pacific volume data, not just reported revenue, when assessing true supply availability.
What is driving growth — and what is holding it back?
Growth is being driven by structural water scarcity and the capital cycle in membrane-based treatment, while restraint comes almost entirely from the regulatory treatment of phosphorus and from raw-material cost volatility. The table rates each factor's evidence strength against the public record.
Factor
Direction
Evidence strength
Mechanism
Desalination and RO capacity additions
Driver
High
Each new SWRO train requires continuous antiscalant dosing; Gulf and Asia pipelines are contracted
Industrial water reuse mandates
Driver
High
Reuse raises cycles of concentration and scaling risk, increasing dose per cubic metre
Tightening phosphorus discharge limits
Restraint
High
Limits ban or cap phosphonate discharge, forcing reformulation and requalification cost
Raw-material and energy price volatility
Restraint
Medium
PPI for chemical manufacturing at elevated levels squeezes formulator margins
Shift to biodegradable / phosphorus-free chemistry
Opportunity
Medium
Premium pricing available where performance parity is demonstrated
A second-order effect our analysis flags: phosphorus restriction does not destroy phosphonate demand so much as relocate it — toward regions with looser discharge rules and toward blended formulations where phosphonate is a minor component. That creates a temporary arbitrage for formulators with multi-jurisdiction approval portfolios, but it is a decaying advantage; buyers should not underwrite long-term contracts on it.
Who are the leading vendors?
Competition is concentrated among integrated specialty chemical majors and water-treatment service houses, with regional formulators holding strong positions in local municipal and oilfield accounts. Differentiation rests on formulation IP, application engineering and regulatory dossiers rather than on raw-material access alone.
Company
Headquarters
Primary positioning
Moat characteristic
BASF
Germany
Broad phosphonate and polymer portfolio
Integrated intermediates, global registration
Dow
United States
Membrane and industrial water polymers
Application data depth, OEM relationships
Solvay
Belgium
Phosphonate and specialty intermediates
Backward integration into phosphorus chemistry
Ecolab / Nalco Water
United States
Service-led water treatment programmes
Field service network, dosing control digital tools
Clariant
Switzerland
Specialty and oilfield formulations
Custom synthesis, regional technical support
SABIC
Saudi Arabia
Regional supply to Gulf desalination and oilfield
Feedstock cost position, proximity to demand
AkzoNobel
Netherlands
Polymer and dispersant chemistries
Colloid science capability
Veolia
France
Integrated water operations and chemicals
Concession relationships, bundled contracts
The competitive moat is shifting from chemistry to compliance documentation and dose-optimisation analytics. Our analysis suggests service-led vendors with installed dosing telemetry convert renewals at materially higher rates than chemistry-only suppliers, because the customer's switching cost is the validated treatment programme, not the drum of product.
What do buyers and operators need to know?
Selection should be driven by the specific scale-forming species in the water, not by price per kilogram. A phosphonate that performs well against calcium carbonate may be ineffective against silica or barium sulfate, and mis-specified chemistry typically manifests as membrane replacement cost many times the chemical saving. Buyers should require jar testing or membrane pilot data on the actual water chemistry before qualification.
Procurement risk is concentrated in two areas: single-source phosphonate intermediates and regulatory requalification cycles. When a discharge limit tightens, a qualified product can require months of testing before re-approval, so operators should maintain a dual-qualified product strategy and contract for formulation-change notification. Switching costs are moderate for commodity phosphonates but high for service-bundled programmes where dosing equipment and control logic are vendor-specific.
Compliance obligations vary sharply by jurisdiction — municipal discharge permits in North America and Europe increasingly scrutinise phosphorus load, while Gulf and Asian industrial sites face fewer constraints today. Operators exporting process water to municipal sewers should assume their antiscalant is regulated as an industrial discharge input and verify permitted phosphorus contribution against total plant load.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 5–5.5% CAGR through 2035, with the market crossing USD 6.4 Billion, and we are comfortable defending that against both the 3.62% and 4.1% published alternatives. The strongest counter-argument is that phosphorus restriction could accelerate faster than modelled in Europe and China, compressing phosphonate revenue before carboxylate and biodegradable substitutes scale — a scenario that would pull the CAGR toward 3.6%. We weight this at roughly a 30% probability, because reformulation pipelines at the leading vendors are already commercial and the substitution is technically proven for most cooling and RO duties.
What the consensus data understates is the value migration from product to programme. As dose optimisation becomes digitised, margin accrues to whoever controls the dosing decision, not the molecule. Buyers should expect antiscalant supply agreements to be progressively bundled into water-treatment service contracts, which raises switching costs and reduces the addressable pool for merchant chemical suppliers.
For operators: dual-qualify a phosphorus-free formulation now, before permit renewal forces it, and negotiate formulation-change notification clauses into supply agreements.
For suppliers: invest in jurisdiction-specific regulatory dossiers and dosing telemetry; these convert renewals better than price concessions in municipal and power accounts.
For investors: prioritise exposure to carboxylate/sulfonate polymer capacity and to service-bundled water treatment, and discount phosphonate-only assets trading at commodity multiples.
The evidence that would change our conclusion: a binding multilateral restriction on phosphonate discharge in two or more major markets within the forecast window, or a demonstrated performance parity failure for phosphorus-free alternatives in high-silica RO service — either would move us toward the low-end CAGR case.
Table 4: Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 5: Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Asia Pacific Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by Type 2020 & 2034
Table 7: Asia Pacific Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by Inhibition Method 2020 & 2034
Table 8: Asia Pacific Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: Asia Pacific Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 10: Asia Pacific Antiscalants/Scale Inhibitors Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: China Antiscalants/Scale Inhibitors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: India Antiscalants/Scale Inhibitors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Japan Antiscalants/Scale Inhibitors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: South Korea Antiscalants/Scale Inhibitors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Indonesia Antiscalants/Scale Inhibitors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the antiscalants/scale inhibitors market size in 2026?
The global antiscalants/scale inhibitors market is estimated at approximately USD 4.3 Billion in 2026, with published estimates ranging from USD 3.6 Billion to USD 4.3 Billion depending on whether sulfonates and polymer chemistries are fully included in the product boundary.
2. What is the growth rate of the antiscalants/scale inhibitors market?
Consensus forecasts place the CAGR at 5.3% over 2026–2035, reaching about USD 6.4 Billion. Competing analyses cite 3.62% to 4.1%, largely because they apply narrower product or end-use definitions and longer or shorter horizons.
3. Which region dominates the antiscalants/scale inhibitors market?
Asia-Pacific leads with roughly 38% of global revenue, driven by industrial expansion in China and India and desalination build-out. North America follows at about 27% and Europe at roughly 21%, with the Middle East growing fastest in percentage terms.
4. Which type of antiscalant is most widely used?
Phosphonates hold the largest revenue share at around 35%, led by DETPMP and HEDP chemistries in oilfield and reverse-osmosis service. Carboxylate and sulfonated polymer formulations are the fastest-growing types because they perform better under high-silica and oxidizing-biocide conditions.
5. Who are the leading companies in the antiscalants/scale inhibitors market?
Leading suppliers include BASF, Dow, Solvay, Ecolab/Nalco Water, Clariant, SABIC, AkzoNobel and Veolia, alongside regional formulators. Competition increasingly turns on regulatory dossiers, application engineering and digital dose optimisation rather than raw-material access.
6. What is restricting the antiscalants/scale inhibitors market?
Environmental regulation of phosphorus discharge is the principal restraint, forcing reformulation and requalification costs. Raw-material and energy price volatility adds margin pressure, and limited biodegradable formulation capacity constrains how quickly suppliers can shift the product mix.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with raw-material and phosphorus-intermediate suppliers, specialized antiscalant producers, contract formulators and blenders, and global and regional distributors. Within those organizations we targeted decision-makers holding direct authority over product specification and purchase: VP-level sourcing and procurement executives, heads of R&D and formulation, technical directors responsible for water-treatment applications, and commercial operations leads managing tender and framework agreements.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
38%
Procurement & Sourcing Directors
32%
Technical & Application Directors
18%
Quality & Regulatory Leads
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
40%
Formulators & Blenders
30%
Distributors & Traders
18%
Water Treatment Service Providers
12%
Secondary Benchmarking & Public Trade Validation
Trade and capacity data were cross-checked against official multilateral sources including UN Comtrade (HS-coded imports and exports of phosphinates, phosphonates and related carboxylate intermediates), WTO tariff and trade records, US ITC and Eurostat datasets, and national statistical office releases. Corporate annual filings (10-K and equivalent), investor presentations and patent databases were reviewed for capacity, formulation and registration activity. Technical standards and industry association guidance on water-treatment chemical testing and discharge were used to frame regulatory assumptions; no third-party market-research publisher data were used as a validation source.
Demand Modeling & Market Sizing Triangulation
Sizing was performed simultaneously top-down and bottom-up. The top-down model allocates macroeconomic and industry output data across end-use segments and applies intensity-of-use coefficients per cubic metre treated. The bottom-up model aggregates manufacturer capacity, realized product pricing and end-use consumption volumes by application. Divergence between the two was reconciled at segment level, with residual error carried as a stated confidence band rather than smoothed away.


 Antiscalants/Scale Inhibitors Market