 Europe Pest Control Services Market
 2026
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Europe Pest Control Services Market

Khageshwar Rongkali
Senior Analyst

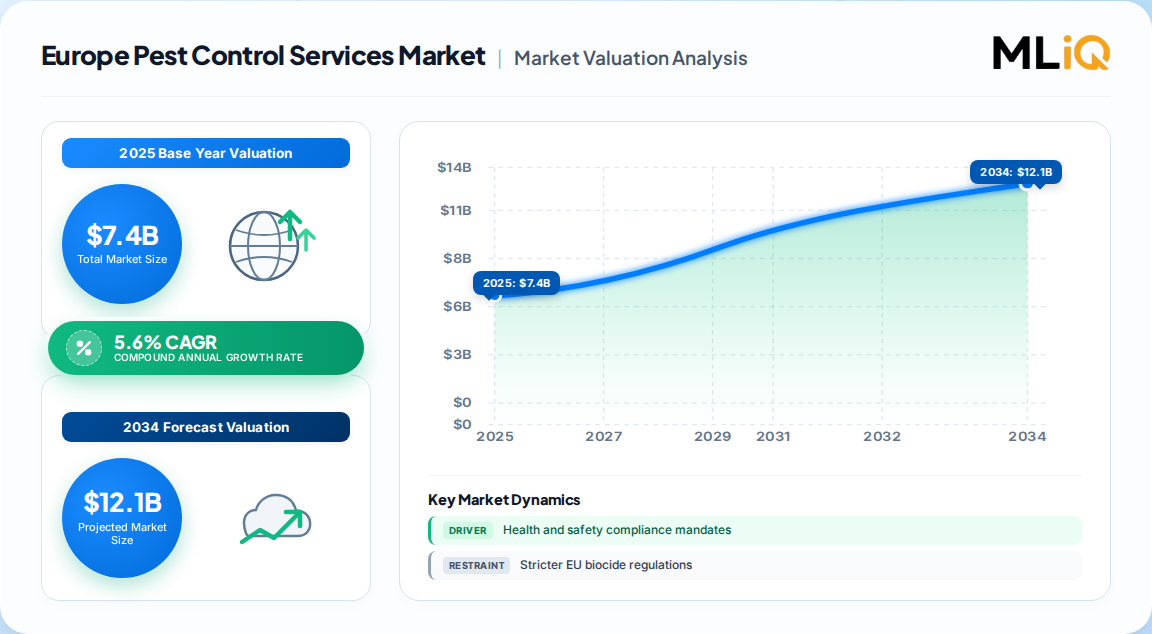
| Year | Market Size |
|---|---|
| 2025 | 7.400 B |
| 2026 | 7.800 B |
| 2027 | 8.200 B |
| 2028 | 8.700 B |
| 2029 | 9.200 B |
| 2030 | 9.700 B |
| 2031 | 10.10 B |

This market covers professional services and consumables used to detect, prevent and eliminate insects, rodents, termites and other pests in residential, commercial, agricultural and industrial settings across Europe. It spans chemical, mechanical and biological methods, increasingly delivered under Integrated Pest Management (IPM) frameworks governed by EU biocide rules.
The analysis covers pest control services and the chemical, mechanical and biological products consumed in service delivery across 30+ European countries, segmented by pest type, control type and end-use application. It addresses commercial, residential, agricultural and industrial demand.
This analysis does not cover agricultural crop-protection pesticides sold directly to farmers, veterinary parasiticides, or public-health mosquito abatement programs funded outside commercial pest control contracts.
The Europe pest control services market sits in a USD 7.0–7.5 Billion range for 2025 depending on the scope of chemical products included. The consensus trajectory points to roughly USD 11 Billion by the mid-2030s, but spread between estimates is wide enough to affect procurement and investment timing.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 11.7 Billion | 2025 (USD 6.9B) | 2034 | 5.74% | Services + control products, all applications | One published estimate |
| USD 10.81 Billion | 2025 (USD 6.96B) | 2034 | 5.01% | Services + products, commercial-weighted | A competing analysis |
| ~USD 7.31 Billion | 2026 (base) | 2034 | 5.01% | Services-led, EU-27 + UK + EFTA | A competing analysis |
| Global services context: USD 27.1B (2026) | 2026 | 2030 | 6.3% | Global pest control services, all regions | A competing analysis |
Our analysis suggests the 5.0–5.7% CAGR band is the most defensible planning range. The higher USD 11.7 Billion terminal figure assumes continued biocide substitution without service-price deflation; the lower USD 10.81 Billion is more conservative on Eastern European pricing. We use ~5.6% CAGR as the mid-point for planning—aggressive enough to reflect commercial compliance demand, conservative enough to survive ongoing active-substance phase-outs.
The market segments on three non-geographic axes: pest type, control method and end-use application. Insects dominate volume; commercial applications dominate value; chemical control dominates revenue but biological is the growth engine.
| Parent Segment | Children | Dominant Sub-segment | Fastest-growing |
|---|---|---|---|
| Pest Type | Insects, Termites, Rodents, Others | Insects | Rodents (~7% CAGR) |
| Control Type | Chemical, Mechanical, Biological, Others | Chemical | Biological (~9% CAGR) |
| Application | Commercial, Residential, Agriculture, Industrial, Others | Commercial | Residential (~8% CAGR) |
Insects hold the largest pest-type share due to bed bug resurgence and cockroach vector concerns in dense cities. Commercial demand anchors on zero-tolerance hygiene law in food and hospitality, while residential growth reflects rising homeowner awareness of vector-borne disease and property damage.
Germany leads European pest control spend, followed by France and the UK, with Eastern European markets expanding fastest from a smaller base. Country-level differences in biocide enforcement and food-safety inspection intensity explain most of the variance in per-capita spend.
Germany's lead reflects industrial and food-processing compliance density. France benefits from dense urban housing stock and high hospitality penetration. The UK market is shaped by post-Brexit regulatory divergence and strict food-safety inspection regimes. Eastern Europe is the fastest-growing bloc, though service maturity and price points remain below Western levels.
Growth is driven by regulatory compliance, urbanization and rising vector-borne disease risk, while restraints center on biocide phase-outs, labor shortages and pest resistance. Net effect: structural volume growth with margin pressure on chemically intensive treatments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| EU health & safety regulation (HACCP, BPR) | Positive | High | Mandates certified professional service in food, hospitality, healthcare |
| Urbanization & density (~75% urban) | Positive | High | Increases infestation spread via shared infrastructure |
| Vector-borne disease awareness (West Nile, Lyme) | Positive | Medium-High | Drives residential and municipal demand |
| Digital/IPM adoption | Positive | Medium | Improves service efficiency and recurring contract models |
| Biocide active-substance phase-outs | Negative | High | Narrows approved chemical toolkit, raises R&D cost |
| Labor shortages & technician costs | Negative | Medium | Constrains service expansion, inflates wage bill |
| Pesticide resistance in urban pests | Negative | Medium | Complicates treatment protocols, increases call-backs |
Bolded implication: Regulation is simultaneously the largest growth driver and the largest cost risk. Firms that treat compliance capability as a moat—rather than a burden—will out-earn peers. The balance of evidence favors continued mid-single-digit growth, but with consolidation pressure on smaller operators unable to fund biocide re-registration and technician training.
The European market is moderately consolidated at the top, with Rentokil Initial and Anticimex leading service delivery, Rollins/Orkin active in cross-border accounts, and BASF, Bayer and Syngenta supplying active substances and formulations. Mid-market regional players remain significant in country-level residential work.
| Company | Primary Position | Differentiation |
|---|---|---|
| Rentokil Initial | Pan-European services leader | Scale, brand, digital pest monitoring (PestConnect) |
| Anticimex | Nordic-rooted, pan-European | Smart traps, subscription models, strong residential base |
| Rollins / Orkin | Global with European footprint | Franchise and commercial account depth |
| Ecolab | Commercial hygiene + pest | Integrated food-safety and hygiene bundle |
| Pelsis Group | Products and equipment | Manufacturing breadth, distributor relationships |
| BASF / Bayer | Active substances and formulations | R&D, regulatory registration capability |
Our analysis suggests the durable moat is not chemical access but service density and data. Firms with connected-device fleets generate proprietary pest-activity data that improves route efficiency and pricing power. Product manufacturers face biocide re-registration costs that favor scale, pushing further consolidation among smaller formulators.
Buyers should prioritize certified compliance capability over unit price. In commercial food and hospitality settings, a single pest incident can trigger inspection failure, closure order or reputational damage that dwarfs the service contract value. Evaluate vendors on BPR-compliant product portfolios, documented IPM protocols and audit-ready reporting.
Switching costs are moderately high in commercial contracts because of site-specific treatment history, sensor placement and staff training. Procurement should therefore negotiate multi-year agreements with performance KPIs (incident rate, response time) rather than headcount-based pricing. Residential buyers face low switching costs and are increasingly price-sensitive, which favors subscription bundling.
Regulatory risk is concentrated in chemical dependency. Operators relying on a narrow set of active substances face reformulation costs and service disruption if approvals lapse. Buyers should ask vendors to disclose their contingency plans for active-substance withdrawal.
The balance of evidence favors a constructive mid-single-digit growth outlook for European pest control services, but the winners will be defined by mix shift rather than headline volume. Regulation is compressing the chemical toolkit while simultaneously mandating professional service—a combination that advantages scale players with registration and training infrastructure.
The strongest counter-argument is that Eastern European price compression and residential DIY substitution could cap blended growth below 5%. This is plausible in low-regulation residential segments, but commercial compliance demand is relatively inelastic and should anchor the forecast.
Actionable strategy:
Evidence that would change our conclusion: a faster-than-expected EU active-substance ban cycle removing a major share of approved chemicals within three years, or a sustained slowdown in commercial food-safety enforcement, would push growth toward the low end of the 5% band.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with active-substance suppliers, specialist formulators, pest-control service operators, equipment manufacturers and national distributors. Decision-maker designations interviewed included VP Sourcing, Heads of Technical/R&D, Commercial Operations Leads and Quality & Regulatory Managers.
Secondary validation drew on Eurostat trade and consumption data, UN Comtrade chemical and equipment flows, EU Biocidal Products Regulation registration records, corporate annual filings and investor presentations, patent databases, and technical standards from CEPA and national pest-control associations.
Market sizing combined top-down macroeconomic allocation (construction, food service, healthcare and household formation) with bottom-up modeling of service-operator revenue, product pricing and end-use consumption. Divergences between methods were reconciled through segment-level elasticity assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up revenue triangulation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | Country and sub-regional share | Trade flow and consumption analysis | High |
| Competitive Landscape | Leading service and product players | Annual reports, capacity mapping, filings | High |
We hold a constructive but selective view: the European pest control services market will grow at roughly 5.6% CAGR through 2034, but value will accrue disproportionately to operators with digital, IPM-linked recurring contracts and to manufacturers with biocide registration scale. Buyers should treat compliance capability—not price—as the primary selection criterion; operators should treat data as the moat; investors should underweight chemical-only exposure.
| Region | Market Share (%) |
|---|---|
| Western Europe | 0.38% |
| Southern Europe | 0.24% |
| Northern Europe | 0.21% |
| Eastern Europe | 0.12% |
| Rest of Europe | 0.05% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.6% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately USD 7.4 Billion in 2025, based on consensus estimates ranging from USD 6.9 to 7.5 Billion. It is forecast to reach roughly USD 11 Billion by 2034, growing at a mid-single-digit CAGR.
Published estimates cluster between 5.0% and 5.7% CAGR for 2026–2034. We use approximately 5.6% as the planning mid-point, reflecting commercial compliance demand offsetting biocide regulatory pressure.
Germany leads country-level spend, driven by industrial and food-processing compliance intensity. France and the UK follow, with Eastern European markets expanding fastest from a lower base.
Biological control is the fastest-growing control type at roughly 9% CAGR, while residential application grows at around 8%. Insects remain the largest pest type; rodents are the fastest-growing pest segment.
Rentokil Initial and Anticimex lead service delivery, with Rollins/Orkin and Ecolab active in commercial accounts. BASF, Bayer and Syngenta supply active substances, and Pelsis Group supplies equipment and products.
The Biocidal Products Regulation restricts approved active substances, raising reformulation costs and favoring scale players. Simultaneously, HACCP and hygiene rules mandate certified professional service in food, hospitality and healthcare, supporting steady demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial & Operations Leads | 35% |
| Technical & R&D Directors | 30% |
| Quality & Regulatory Managers | 22% |
| Procurement & Sourcing Heads | 13% |
| Company Type | Representation (%) |
|---|---|
| Pest Control Service Operators | 40% |
| Active-Substance & Product Manufacturers | 30% |
| Equipment & Digital Monitoring Providers | 18% |
| National Distributors & Traders | 12% |