Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Industrial Gas Market Hits USD 24.6B by 2033 at 8.5% CAGR
Industrial Gas Market
Industrial Gas Market Hits USD 24.6B by 2033 at 8.5% CAGR
Industrial Gas Market by Product Type (Nitrogen, Oxygen, Carbon dioxide, Hydrogen, Helium, Argon, Ammonia, Methane, Propane, Butane, Other Product Types), by End-user Industry (Chemical Processing and Refining, Electronics, Food and Beverage, Oil and Gas, Metal Manufacturing and Fabrication, Medical and Pharmaceutical, Automotive and Transportation, Energy and Power, Other End-user Industries), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 11, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Industrial Gas Market
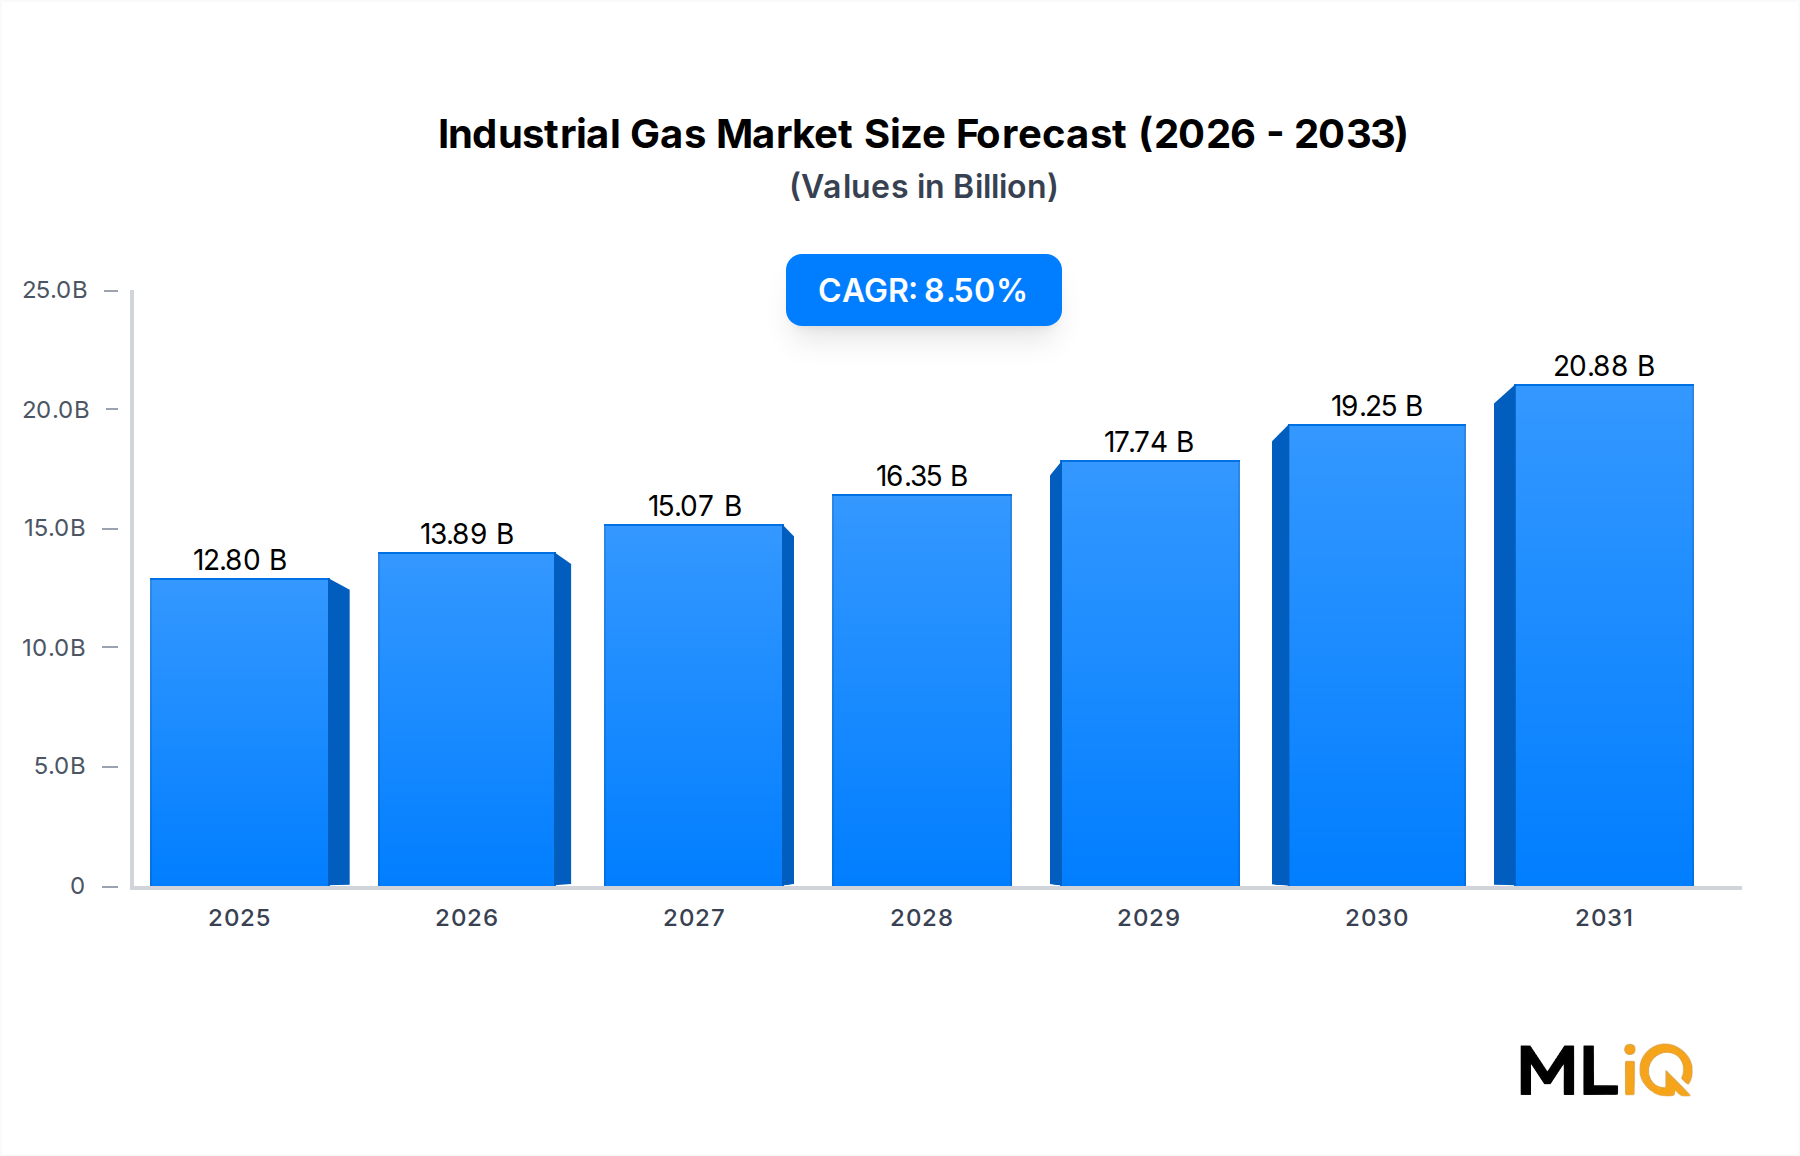
The Industrial Gas Market exits 2025 at USD 12.8 billion and reaches USD 24.6 billion by 2033, equal to a 8.5% CAGR. Nitrogen and oxygen together account for roughly 55% of global value, and both are supplied mainly through multi-year on-site or bulk contracts rather than spot channels. That contract structure explains why revenue growth lags volume recovery in downturns and why supplier margins move less than merchant pricing headlines imply.
Industrial Gas Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
12.80 B
2025
13.89 B
2026
15.07 B
2027
16.35 B
2028
17.74 B
2029
19.25 B
2030
20.88 B
2031
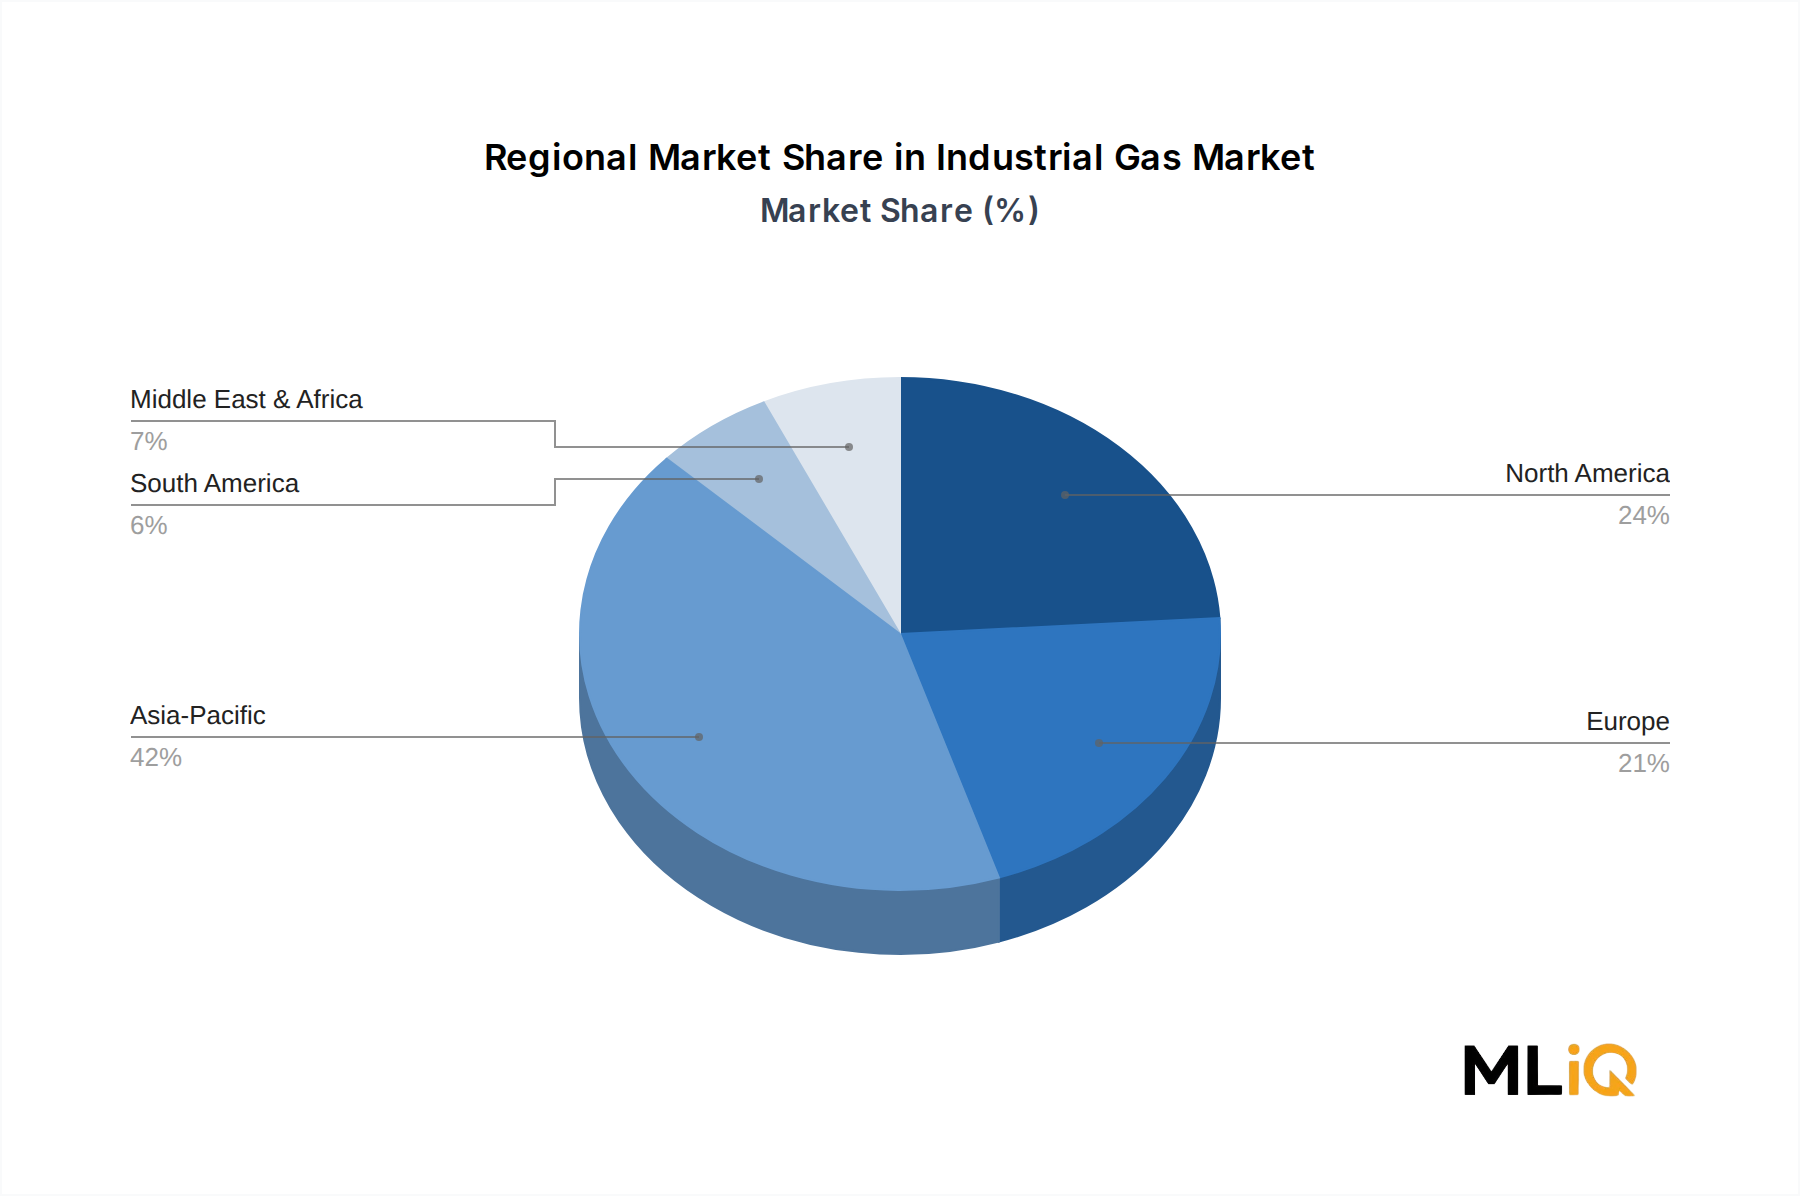
Asia-Pacific holds 42.0% of global value, anchored by Chinese and Indian steel, chemical and semiconductor capacity. North America contributes 24.0% and Europe 21.0%, where growth depends on replacement, efficiency and decarbonization-linked gas demand rather than new tonnage. Suppliers serving the Specialty Chemicals Market compete on purity guarantees, delivery reliability and analytical documentation rather than on headline price.
Three Forces Reshaping Demand
Medical and pharmaceutical gas: oxygen and high-purity nitrogen volumes track hospital capacity and biologics manufacturing; medical oxygen is a regulated drug in most jurisdictions, which raises qualification barriers.
Electronics fabrication: each new 300mm wafer fab adds high-purity nitrogen, argon and hydrogen demand across purge, carrier and annealing steps.
Energy transition chemistry: hydrogen for refining and ammonia, plus recovered CO2 for food, beverage and enhanced oil recovery.
What Constrains the Upside
Environmental permitting and CO2 sourcing rules lengthen project lead times.
Helium supply remains concentrated across a small set of producing nations, keeping spot pricing volatile.
Air separation is electricity-intensive, with power at 60-70% of variable cost, so regional electricity prices set plant economics directly.
Segment Deep-Dive: Nitrogen Dominance in Industrial Gas Market
Segment Analysis Matrix
Segment
CAGR (2025-2033)
Market Share (2025)
Key Demand Driver
Nitrogen
7.6%
31%
Inerting, blanketing, electronics purging
Oxygen
8.1%
24%
Steelmaking, medical oxygen, gasification
Hydrogen
10.8%
14%
Refining desulfurization, ammonia, mobility
Carbon Dioxide
7.0%
9%
Food chilling, beverage carbonation, oil recovery
Argon, Helium and others
8.9%
22%
Welding shielding, electronics purge, MRI cooling
Why Nitrogen Anchors the Value Pool
The Nitrogen Gas Market is the single largest value pool at 31% of global revenue and grows at 7.6%, slightly below the market average because its volumes are tied to mature steel and chemical assets. Volume, not price, drives this segment: nitrogen is recovered as a by-product of oxygen separation, so incremental tonnage carries low marginal cost once a plant is running.
On-site plants serving refineries and ammonia complexes dominate volume.
Electronics-grade nitrogen commands a 2-4x price premium over standard industrial grade.
Purity certification, not production, is the true differentiator at the top of the grade ladder.
Oxygen and Hydrogen Sub-Segment Dynamics
The Oxygen Gas Market generates 24% of revenue and grows at 8.1%, supported by steel decarbonization trials, gasification projects and hospital oxygen demand that settled above pre-2020 baselines. Hydrogen is the fastest-growing product line at 10.8%, with demand split between refinery desulfurization, ammonia synthesis and early mobility infrastructure. Most hydrogen volume today is captive, produced on-site rather than purchased as merchant gas, which caps third-party revenue even as headline demand rises.
Carbon Dioxide, Argon and Specialty Grades
The Carbon Dioxide Gas Market holds 9% of value, shaped by food chilling, beverage carbonation and enhanced oil recovery, and constrained by the fact that merchant CO2 is a by-product of ammonia and ethanol production. Argon, helium and other grades represent 22% combined, with argon tied to air separation output and helium tied to a narrow set of natural gas fields. The Electronic Specialty Gas Market operates under stricter specification regimes, where qualification cycles of 12-18 months protect incumbent suppliers.
Margin Pressure Points
Long-term contracts index electricity and natural gas input costs, limiting gross margin expansion even when volumes rise.
Cylinder, Dewar and trailer logistics absorb 15-20% of delivered cost for packaged gas, squeezing small distributors.
Helium price volatility transmits directly to electronics and medical imaging customers with limited substitution options.
Primary Market Drivers & Growth Restraints in Industrial Gas Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Rising demand for alternative energy sources, including hydrogen for refining, ammonia and power
High
Long term
Driver
Growth in frozen and stored food logistics requiring food-grade nitrogen and CO2
Medium
Short term
Driver
Expanding healthcare demand for oxygen, nitric oxide blends and medical-grade nitrogen
High
Short term
Driver
Electronics fab construction and the adjacent Electronic Specialty Gas Market build-out
High
Medium term
Driver
Metals and fabrication demand for argon shielding gas and oxygen cutting gas
Medium
Short term
Restraint
Environmental regulation of CO2 sourcing, emissions reporting and flaring
Medium
Long term
Restraint
Safety compliance costs for cryogenic storage, cylinder handling and transport
Medium
Short term
Restraint
Helium supply concentration and spot price volatility
High
Short term
Driver Economics
The Hydrogen Gas Market is expanding at 10.8%, the fastest product line in the forecast, because refineries and ammonia producers face tightening sulfur and carbon specifications. The Medical Gas Market grows on a different mechanism: hospital capacity additions and biologics manufacturing lift oxygen and nitrogen volumes, while dual-source qualification requirements raise switching costs and stabilize supplier revenue.
Healthcare demand is regulation-driven and largely recession-resistant.
The Food Grade Gas Market depends on liquid nitrogen freezing and CO2 chilling, which scale with cold-chain investment in Asia-Pacific and Latin America.
Energy transition projects create multi-year order visibility but require capital commitment before revenue starts.
Restraint Mechanics
Permitting for new air separation and CO2 purification capacity can add 18-36 months to project schedules, and food-grade CO2 requires documented source verification. Safety compliance on cylinder handling and cryogenic transport favors operators with established HSE systems. Helium remains the least flexible input, with supply concentrated across Qatar, the United States, Algeria and Russia.
Competitive Ecosystem & Key Vendor Profiles: Industrial Gas Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Linde PLC
Global on-site plant network and engineering depth
Refining, chemicals, electronics, healthcare
Leader
Air Liquide
Healthcare gas integration and hydrogen project pipeline
Hospitals, industrials, energy
Leader
Air Products and Chemicals Inc
Large-scale hydrogen and gasification project delivery
Energy, refining, metals
Leader
Nippon Sanso Holdings Corporation
Electronics specialty gas and Asian regional density
Semiconductor fabs, electronics
Challenger
Messer Group GmbH
European and Chinese industrial gas distribution
Metals, food, fabrication
Challenger
Iwatani Corporation
Helium sourcing plus US bulk liquid expansion
Electronics, healthcare, food
Challenger
Yingde Gases Group
Cost-competitive Chinese on-site supply
Steel, chemicals, glass
Niche
SOL SPA
Regional packaged gas and specialty blends
Laboratories, medical, food
Niche
Linde PLC: Operates the broadest installed base in the global Air Separation Unit Market and monetizes it through long-term take-or-pay contracts with refining and chemical customers.
Air Liquide: Combines medical gas distribution with hydrogen and carbon capture project development, giving it two independent growth engines.
Air Products and Chemicals Inc: Positions around very large hydrogen and gasification complexes, where capital scale and execution become the decisive competitive variables.
Nippon Sanso Holdings Corporation: Concentrates on electronics-grade gases in Japan, South Korea and Taiwan, where qualification cycles protect margins.
Messer Group GmbH: Competes on regional density and packaged gas logistics rather than on global scale.
Iwatani Corporation: Helium sourcing and the Aspen Air US acquisition underpin its North American bulk liquid entry.
Yingde Gases Group: Targets Chinese industrial clusters with on-site generation priced against grid electricity.
SOL SPA: Serves specialty, medical and laboratory customers with blended and high-purity products.
Strategic Milestones & Recent Developments in Industrial Gas Market
Latest Strategic Moves
Date
Company
Event Type
Impact
April 2023
Nippon Gases Italia and Enel Green Power Italia
Partnership
Builds food-grade CO2 recovery from geothermal fluids at Piancastagnaio, Siena
January 2023
Iwatani Corporation of America and Aspen Air US, LLC
M&A
Adds US bulk liquid capacity and a distribution footprint in industrial gases
Ongoing
Linde PLC, Air Liquide, Air Products and Chemicals Inc
Contract and portfolio
Long-term on-site and low-carbon supply agreements with refining, chemical and electronics customers
Chronological Detail
January 2023: Iwatani Corporation of America, a wholly owned subsidiary of Iwatani Corporation, acquired Aspen Air US, LLC, a bulk liquid industrial gas manufacturer and distributor. The deal marked Iwatani's entry into the United States industrial gases sector and reflects a strategy of buying established distribution rather than building it.
April 2023: Nippon Gases Operations, a division of Nippon Gases Italia, signed an agreement with Enel Green Power Italia to construct a plant that reuses, purifies and liquefies naturally occurring CO2 from geothermal fluids at the Piancastagnaio power plants in the province of Siena. The output is designated for food use, and the investment is part of a broader Italian program to raise production capacity and shorten distance to customers.
Subsequent period: The two moves define the current playbook, where CO2 recovery and bulk liquid distribution assets are acquired or partnered for, and where decarbonized supply contracts replace greenfield merchant capacity as the primary growth route.
Regional Market Analysis & Growth Corridors for Industrial Gas Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Asia-Pacific
9.4%
USD 5.3 billion
Steel, chemicals, semiconductor fabs
Moderate to high
North America
7.6%
USD 3.1 billion
Refining, healthcare, hydrogen hubs
High
Europe
6.9%
USD 2.7 billion
Decarbonization, medical, specialty grades
Very high
Middle East & Africa
9.1%
USD 0.9 billion
Refinery, petrochemical and metals complexes
Medium
South America
8.2%
USD 0.8 billion
Mining, food processing, medical oxygen
Medium
Fastest-Growing Corridors
Asia-Pacific grows at 9.4%, with China and India supplying most incremental tonnage; ASEAN adds electronics and food-linked demand.
Middle East and Africa grows at 9.1%, where GCC refinery and petrochemical projects bundle on-site gas supply into larger industrial complexes.
South America grows at 8.2%, driven by mining, food processing and medical oxygen in interior regions with thin distribution coverage.
Most Mature Markets
Europe grows at 6.9%, the slowest region, because steel and chemical capacity is largely set and regulation raises the cost of new capacity.
North America grows at 7.6%, with demand shifting toward hydrogen hubs, healthcare and electronics reshoring rather than bulk metals.
The gap between the 9.4% Asia-Pacific expansion and the 6.9% European rate reflects where new industrial capacity is being built, not where gas consumption per unit of output is highest. Europe still commands premium pricing for specialty and medical grades, and that pricing power is the region's main defense against flat volumes.
Sustainability, ESG & Decarbonization Pressures on Industrial Gas Market
Pressure
Mechanism
Timeline
Who Absorbs Cost
Electricity decarbonization
Renewable PPAs and green tariffs for air separation
Short to medium term
Suppliers, partly indexed to customers
CO2 sourcing rules
Source verification and food-grade certification
Short term
CO2 producers and distributors
Hydrogen carbon intensity
Lifecycle emissions thresholds in refining and ammonia
Medium to long term
Project developers and offtakers
Investor ESG criteria
Scope 1 and 2 disclosure requirements
Short term
Listed majors
Decarbonization changes input choices before it changes product mix. Power purchase agreements for air separation plants lower both Scope 2 emissions and long-run electricity exposure, and CO2 recovery from industrial and geothermal sources converts a waste stream into certified food-grade product. The Carbon Dioxide Gas Market is therefore shifting from by-product supply toward deliberately sourced and documented supply, which raises qualification cost but also raises barriers to entry.
Buyers in chemicals and refining increasingly request lifecycle carbon data in tender documents.
Hydrogen contracts in Europe and North America now include carbon intensity thresholds, favoring electrolytic or capture-equipped supply.
Helium and argon production carry little direct emissions burden, so ESG pressure concentrates on power sourcing and transport fleets.
Pricing Dynamics, Cost Structures & Margin Pressure in Industrial Gas Market
Cost Component
Share of Delivered Cost
Trend
Margin Lever
Electricity
35-45% (air separation)
Rising with grid prices
Renewable PPAs, load shifting
Natural gas feedstock
20-30% (hydrogen, SMR)
Volatile
Capture, electrolysis transition
Distribution and logistics
15-20% (packaged gas)
Rising with labor and fuel
Route density, tank telemetry
Labor and maintenance
10-15%
Stable to rising
Automation, remote monitoring
Cylinders and packaging
5-8%
Cyclical with steel
Asset pooling, reuse programs
Average selling prices diverge sharply by channel. On-site and pipeline nitrogen and oxygen are priced under contracts that index electricity and are renegotiated on multi-year cycles, so effective price changes lag spot energy moves by 6-12 months. Packaged and specialty grades carry wider spreads, but the Electronic Specialty Gas Market and medical channels require documentation and qualification that consume part of that spread.
Suppliers with captive power or long-term renewable contracts hold the strongest margin position at 8.5% market growth.
Merchant CO2 pricing remains exposed to ammonia and ethanol plant outages, which can tighten regional supply within weeks.
Helium retains the widest pricing volatility of any product line, with limited demand destruction because medical imaging and semiconductor users have few substitutes.
Aggregating distribution routes and tank telemetry typically removes 3-6 percentage points of packaged gas logistics cost, the single most actionable margin lever for regional distributors.
Industrial Gas Market Segmentation
1. Product Type
1.1. Nitrogen
1.2. Oxygen
1.3. Carbon dioxide
1.4. Hydrogen
1.5. Helium
1.6. Argon
1.7. Ammonia
1.8. Methane
1.9. Propane
1.10. Butane
1.11. Other Product Types
2. End-user Industry
2.1. Chemical Processing and Refining
2.2. Electronics
2.3. Food and Beverage
2.4. Oil and Gas
2.5. Metal Manufacturing and Fabrication
2.6. Medical and Pharmaceutical
2.7. Automotive and Transportation
2.8. Energy and Power
2.9. Other End-user Industries
Industrial Gas Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Industrial Gas Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.5% from 2020-2034
Segmentation
By Product Type
Nitrogen
Oxygen
Carbon dioxide
Hydrogen
Helium
Argon
Ammonia
Methane
Propane
Butane
Other Product Types
By End-user Industry
Chemical Processing and Refining
Electronics
Food and Beverage
Oil and Gas
Metal Manufacturing and Fabrication
Medical and Pharmaceutical
Automotive and Transportation
Energy and Power
Other End-user Industries
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Nitrogen
5.1.2. Oxygen
5.1.3. Carbon dioxide
5.1.4. Hydrogen
5.1.5. Helium
5.1.6. Argon
5.1.7. Ammonia
5.1.8. Methane
5.1.9. Propane
5.1.10. Butane
5.1.11. Other Product Types
5.2. Market Analysis, Insights and Forecast - by End-user Industry
5.2.1. Chemical Processing and Refining
5.2.2. Electronics
5.2.3. Food and Beverage
5.2.4. Oil and Gas
5.2.5. Metal Manufacturing and Fabrication
5.2.6. Medical and Pharmaceutical
5.2.7. Automotive and Transportation
5.2.8. Energy and Power
5.2.9. Other End-user Industries
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Nitrogen
6.1.2. Oxygen
6.1.3. Carbon dioxide
6.1.4. Hydrogen
6.1.5. Helium
6.1.6. Argon
6.1.7. Ammonia
6.1.8. Methane
6.1.9. Propane
6.1.10. Butane
6.1.11. Other Product Types
6.2. Market Analysis, Insights and Forecast - by End-user Industry
6.2.1. Chemical Processing and Refining
6.2.2. Electronics
6.2.3. Food and Beverage
6.2.4. Oil and Gas
6.2.5. Metal Manufacturing and Fabrication
6.2.6. Medical and Pharmaceutical
6.2.7. Automotive and Transportation
6.2.8. Energy and Power
6.2.9. Other End-user Industries
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Nitrogen
7.1.2. Oxygen
7.1.3. Carbon dioxide
7.1.4. Hydrogen
7.1.5. Helium
7.1.6. Argon
7.1.7. Ammonia
7.1.8. Methane
7.1.9. Propane
7.1.10. Butane
7.1.11. Other Product Types
7.2. Market Analysis, Insights and Forecast - by End-user Industry
7.2.1. Chemical Processing and Refining
7.2.2. Electronics
7.2.3. Food and Beverage
7.2.4. Oil and Gas
7.2.5. Metal Manufacturing and Fabrication
7.2.6. Medical and Pharmaceutical
7.2.7. Automotive and Transportation
7.2.8. Energy and Power
7.2.9. Other End-user Industries
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Nitrogen
8.1.2. Oxygen
8.1.3. Carbon dioxide
8.1.4. Hydrogen
8.1.5. Helium
8.1.6. Argon
8.1.7. Ammonia
8.1.8. Methane
8.1.9. Propane
8.1.10. Butane
8.1.11. Other Product Types
8.2. Market Analysis, Insights and Forecast - by End-user Industry
8.2.1. Chemical Processing and Refining
8.2.2. Electronics
8.2.3. Food and Beverage
8.2.4. Oil and Gas
8.2.5. Metal Manufacturing and Fabrication
8.2.6. Medical and Pharmaceutical
8.2.7. Automotive and Transportation
8.2.8. Energy and Power
8.2.9. Other End-user Industries
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Nitrogen
9.1.2. Oxygen
9.1.3. Carbon dioxide
9.1.4. Hydrogen
9.1.5. Helium
9.1.6. Argon
9.1.7. Ammonia
9.1.8. Methane
9.1.9. Propane
9.1.10. Butane
9.1.11. Other Product Types
9.2. Market Analysis, Insights and Forecast - by End-user Industry
9.2.1. Chemical Processing and Refining
9.2.2. Electronics
9.2.3. Food and Beverage
9.2.4. Oil and Gas
9.2.5. Metal Manufacturing and Fabrication
9.2.6. Medical and Pharmaceutical
9.2.7. Automotive and Transportation
9.2.8. Energy and Power
9.2.9. Other End-user Industries
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Nitrogen
10.1.2. Oxygen
10.1.3. Carbon dioxide
10.1.4. Hydrogen
10.1.5. Helium
10.1.6. Argon
10.1.7. Ammonia
10.1.8. Methane
10.1.9. Propane
10.1.10. Butane
10.1.11. Other Product Types
10.2. Market Analysis, Insights and Forecast - by End-user Industry
10.2.1. Chemical Processing and Refining
10.2.2. Electronics
10.2.3. Food and Beverage
10.2.4. Oil and Gas
10.2.5. Metal Manufacturing and Fabrication
10.2.6. Medical and Pharmaceutical
10.2.7. Automotive and Transportation
10.2.8. Energy and Power
10.2.9. Other End-user Industries
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Air Liquide
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Air Products and Chemicals Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Asia Technical Gas Co Pte Ltd
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. BASF SE
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Bhuruka Gases Limited
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Ellenbarrie industrial Gases
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Gruppo SIAD
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Iwatani Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Linde PLC
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Messer Group GmbH
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Nippon Sanso Holdings Corporation
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. PT Samator Indo Gas TBK
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Sapio Group
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. SOL SPA
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Yingde Gases Group*List Not Exhaustive
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Industrial Gas Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: Industrial Gas Market Volume Breakdown (Billion, %) by Region 2026 & 2034
Figure 3: North America Industrial Gas Market Revenue (billion), by Product Type 2026 & 2034
Figure 4: North America Industrial Gas Market Volume (Billion), by Product Type 2026 & 2034
Figure 5: North America Industrial Gas Market Revenue Share (%), by Product Type 2026 & 2034
Figure 6: North America Industrial Gas Market Volume Share (%), by Product Type 2026 & 2034
Figure 7: North America Industrial Gas Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 8: North America Industrial Gas Market Volume (Billion), by End-user Industry 2026 & 2034
Figure 9: North America Industrial Gas Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 10: North America Industrial Gas Market Volume Share (%), by End-user Industry 2026 & 2034
Figure 11: North America Industrial Gas Market Revenue (billion), by Country 2026 & 2034
Figure 12: North America Industrial Gas Market Volume (Billion), by Country 2026 & 2034
Figure 13: North America Industrial Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Industrial Gas Market Volume Share (%), by Country 2026 & 2034
Figure 15: South America Industrial Gas Market Revenue (billion), by Product Type 2026 & 2034
Figure 16: South America Industrial Gas Market Volume (Billion), by Product Type 2026 & 2034
Figure 17: South America Industrial Gas Market Revenue Share (%), by Product Type 2026 & 2034
Figure 18: South America Industrial Gas Market Volume Share (%), by Product Type 2026 & 2034
Figure 19: South America Industrial Gas Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 20: South America Industrial Gas Market Volume (Billion), by End-user Industry 2026 & 2034
Figure 21: South America Industrial Gas Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 22: South America Industrial Gas Market Volume Share (%), by End-user Industry 2026 & 2034
Figure 23: South America Industrial Gas Market Revenue (billion), by Country 2026 & 2034
Figure 24: South America Industrial Gas Market Volume (Billion), by Country 2026 & 2034
Figure 25: South America Industrial Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 26: South America Industrial Gas Market Volume Share (%), by Country 2026 & 2034
Figure 27: Europe Industrial Gas Market Revenue (billion), by Product Type 2026 & 2034
Figure 28: Europe Industrial Gas Market Volume (Billion), by Product Type 2026 & 2034
Figure 29: Europe Industrial Gas Market Revenue Share (%), by Product Type 2026 & 2034
Figure 30: Europe Industrial Gas Market Volume Share (%), by Product Type 2026 & 2034
Figure 31: Europe Industrial Gas Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 32: Europe Industrial Gas Market Volume (Billion), by End-user Industry 2026 & 2034
Figure 33: Europe Industrial Gas Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 34: Europe Industrial Gas Market Volume Share (%), by End-user Industry 2026 & 2034
Figure 35: Europe Industrial Gas Market Revenue (billion), by Country 2026 & 2034
Figure 36: Europe Industrial Gas Market Volume (Billion), by Country 2026 & 2034
Figure 37: Europe Industrial Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Europe Industrial Gas Market Volume Share (%), by Country 2026 & 2034
Figure 39: Middle East & Africa Industrial Gas Market Revenue (billion), by Product Type 2026 & 2034
Figure 40: Middle East & Africa Industrial Gas Market Volume (Billion), by Product Type 2026 & 2034
Figure 41: Middle East & Africa Industrial Gas Market Revenue Share (%), by Product Type 2026 & 2034
Figure 42: Middle East & Africa Industrial Gas Market Volume Share (%), by Product Type 2026 & 2034
Figure 43: Middle East & Africa Industrial Gas Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 44: Middle East & Africa Industrial Gas Market Volume (Billion), by End-user Industry 2026 & 2034
Figure 45: Middle East & Africa Industrial Gas Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 46: Middle East & Africa Industrial Gas Market Volume Share (%), by End-user Industry 2026 & 2034
Figure 47: Middle East & Africa Industrial Gas Market Revenue (billion), by Country 2026 & 2034
Figure 48: Middle East & Africa Industrial Gas Market Volume (Billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Industrial Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Industrial Gas Market Volume Share (%), by Country 2026 & 2034
Figure 51: Asia Pacific Industrial Gas Market Revenue (billion), by Product Type 2026 & 2034
Figure 52: Asia Pacific Industrial Gas Market Volume (Billion), by Product Type 2026 & 2034
Figure 53: Asia Pacific Industrial Gas Market Revenue Share (%), by Product Type 2026 & 2034
Figure 54: Asia Pacific Industrial Gas Market Volume Share (%), by Product Type 2026 & 2034
Figure 55: Asia Pacific Industrial Gas Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 56: Asia Pacific Industrial Gas Market Volume (Billion), by End-user Industry 2026 & 2034
Figure 57: Asia Pacific Industrial Gas Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 58: Asia Pacific Industrial Gas Market Volume Share (%), by End-user Industry 2026 & 2034
Figure 59: Asia Pacific Industrial Gas Market Revenue (billion), by Country 2026 & 2034
Figure 60: Asia Pacific Industrial Gas Market Volume (Billion), by Country 2026 & 2034
Figure 61: Asia Pacific Industrial Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 62: Asia Pacific Industrial Gas Market Volume Share (%), by Country 2026 & 2034
List of Tables
Table 1: Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 2: Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 3: Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 4: Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 5: Industrial Gas Market Revenue billion Forecast, by Region 2020 & 2034
Table 6: Industrial Gas Market Volume Billion Forecast, by Region 2020 & 2034
Table 7: North America Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 8: North America Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 10: North America Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 11: North America Industrial Gas Market Revenue billion Forecast, by Country 2020 & 2034
Table 12: North America Industrial Gas Market Volume Billion Forecast, by Country 2020 & 2034
Table 13: United States Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: United States Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 15: Canada Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Canada Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 17: Mexico Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Mexico Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 19: South America Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 20: South America Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 21: South America Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 22: South America Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 23: South America Industrial Gas Market Revenue billion Forecast, by Country 2020 & 2034
Table 24: South America Industrial Gas Market Volume Billion Forecast, by Country 2020 & 2034
Table 25: Brazil Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Brazil Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 27: Argentina Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Argentina Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 29: Rest of South America Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Rest of South America Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 31: Europe Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 32: Europe Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 33: Europe Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 34: Europe Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 35: Europe Industrial Gas Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Europe Industrial Gas Market Volume Billion Forecast, by Country 2020 & 2034
Table 37: United Kingdom Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: United Kingdom Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 39: Germany Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Germany Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 41: France Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: France Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 43: Italy Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 44: Italy Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 45: Spain Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 46: Spain Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 47: Russia Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Russia Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 49: Benelux Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: Benelux Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 51: Nordics Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Nordics Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 53: Rest of Europe Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 54: Rest of Europe Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 55: Middle East & Africa Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 56: Middle East & Africa Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 57: Middle East & Africa Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 58: Middle East & Africa Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 59: Middle East & Africa Industrial Gas Market Revenue billion Forecast, by Country 2020 & 2034
Table 60: Middle East & Africa Industrial Gas Market Volume Billion Forecast, by Country 2020 & 2034
Table 61: Turkey Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 62: Turkey Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 63: Israel Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 64: Israel Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 65: GCC Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 66: GCC Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 67: North Africa Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 68: North Africa Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 69: South Africa Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 70: South Africa Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 71: Rest of Middle East & Africa Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 72: Rest of Middle East & Africa Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 73: Asia Pacific Industrial Gas Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 74: Asia Pacific Industrial Gas Market Volume Billion Forecast, by Product Type 2020 & 2034
Table 75: Asia Pacific Industrial Gas Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 76: Asia Pacific Industrial Gas Market Volume Billion Forecast, by End-user Industry 2020 & 2034
Table 77: Asia Pacific Industrial Gas Market Revenue billion Forecast, by Country 2020 & 2034
Table 78: Asia Pacific Industrial Gas Market Volume Billion Forecast, by Country 2020 & 2034
Table 79: China Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 80: China Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 81: India Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 82: India Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 83: Japan Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 84: Japan Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 85: South Korea Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 86: South Korea Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 87: ASEAN Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 88: ASEAN Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 89: Oceania Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 90: Oceania Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Table 91: Rest of Asia Pacific Industrial Gas Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 92: Rest of Asia Pacific Industrial Gas Market Volume (Billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Research split follows a 70-80% primary / 20-30% secondary structure, with primary interviews, plant-level surveys and supplier briefings forming the evidence base.
Interview targets include Director of Bulk Gas Supply Chain Procurement, Air Separation Plant Operations Manager, Industrial Gas Applications Engineering Lead, and HSE and Regulatory Compliance Manager across North America, Europe, Asia-Pacific and LAMEA.
Company types surveyed span the full value chain: cryogenic air separation unit (ASU) operators and bulk liquid gas producers, on-site PSA and VPSA gas generation system integrators for fabs and hospitals, cryogenic cold-box, tank and trailer fabricators, cylinder, valve and pressure-vessel component suppliers, and packaged gas distributors and wholesalers.
Cross-validation interviews are conducted with Compressed Gas Association (CGA), European Industrial Gases Association (EIGA) and Asia Industrial Gases Association (AIGA) technical working groups, plus U.S. FDA Center for Drug Evaluation and Research reviewers for medical oxygen classification.
Every report is updated to the date of purchase, so plant capacity additions, contract awards and regulatory notices are refreshed at delivery.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Bulk Gas Supply Chain Procurement
28%
Air Separation Plant Operations Manager
24%
Industrial Gas Applications Engineering Lead
20%
HSE and Regulatory Compliance Manager
16%
Medical Gas Qualification Manager
12%
Industry Ecosystem Breakdown
Company Type
Representation (%)
ASU operators and bulk liquid gas producers
30%
On-site PSA and VPSA gas generation integrators
22%
Cryogenic cold-box, tank and trailer fabricators
18%
Cylinder, valve and pressure-vessel component suppliers
Association publications, safety data sheets, grade specifications and trade statistics are used to reconcile product-type and end-user splits.
Secondary findings are treated as directional inputs only and are always cross-checked against primary interview data before inclusion.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation across product type, end-user industry and region.
Bottom-up sizing uses specific quantitative anchors: number of operational air separation units per region and average nameplate capacity in tonnes per day, average on-site gas consumption per 300mm wafer start in a semiconductor fab, medical oxygen cylinders delivered per 1,000 hospital beds per month, and average bulk liquid contract volume in tonnes per year per industrial account.
Installed base of cryogenic tanks and average refill frequency per account are applied to calibrate the packaged gas channel.
Regional estimates are built from the segment structure covering North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa) and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific).
Data Accuracy & Quality Check
Estimated data accuracy is guaranteed at an 85-90% confidence level for market size, share and growth rate outputs.
Multi-level triangulation compares bottom-up plant and account counts against top-down regional revenue aggregates, and discrepancies above 5% trigger a re-interview round.
Segment shares are stress-tested against product-type capacity data and contract-level pricing benchmarks before publication.
Final figures are reviewed against historical forecast performance, and any revision is documented with the source, date and reason for change.
Frequently Asked Questions
1. What were the most notable recent developments and M&A moves in the industrial gas industry?
In January 2023, Iwatani Corporation of America acquired Aspen Air US, LLC, a bulk liquid industrial gas producer and distributor, marking Iwatani's entry into the United States industrial gases segment. In April 2023, Nippon Gases Italia signed an agreement with Enel Green Power Italia to build a plant that reuses, purifies and liquefies naturally occurring CO2 from the Piancastagnaio geothermal power plants in Siena for food-grade use. Both moves show that supply-chain control and CO2 sourcing, not greenfield air separation capacity, are the current acquisition logic.
2. How do environmental and safety regulations affect the industrial gas market?
Regulations shape both production economics and entry barriers. CO2 sourcing is now tied to emissions accounting and food-grade certification, while medical oxygen is regulated as a drug in most jurisdictions, requiring documented purity and traceability at every handoff. Cylinder handling, cryogenic storage and transport fall under national safety regimes, adding fixed compliance cost that favors large distributors with dedicated HSE functions over small merchant operators.
3. Which sustainability and ESG factors are reshaping gas production and procurement?
Air separation is power-intensive, with electricity accounting for roughly 60-70% of variable cost at a typical plant, so renewable power purchase agreements directly improve the emissions profile and the cost base. Hydrogen produced by steam methane reforming carries a carbon penalty that buyers in refining and ammonia now price into contracts, pushing investment toward electrolysis and carbon capture. Circular CO2 recovery, such as the geothermal-linked project at Piancastagnaio, converts a waste stream into a food-grade revenue line.
4. Which region dominates the industrial gas market and why?
Asia-Pacific holds approximately 42.0% of global value, supported by Chinese and Indian steel, chemical, refining and semiconductor capacity that is co-located with on-site gas plants. Long-term supply contracts attached to those plants create sticky revenue and high switching costs. Japan and South Korea add electronics-grade nitrogen, argon and hydrogen demand, which carries a premium over standard industrial grades.
5. Which region is growing fastest, and where are the emerging geographic opportunities?
Asia-Pacific and the Middle East and Africa are the fastest-growing corridors, expanding at an estimated 9.4% and 9.1% respectively through 2033, ahead of the global 8.5% CAGR. Growth in the Middle East and Africa is anchored by refinery, petrochemical and metals projects in the GCC and North Africa, where on-site gas supply is bundled into larger industrial complexes. South America, led by Brazil and Argentina, offers incremental volume from mining, food processing and medical oxygen in under-served interior regions.
6. How has the market recovered after the pandemic and what structural shifts persist?
Medical oxygen demand spiked during 2020-2021 and then normalized, but hospital buyers retained higher safety stock and dual-source contracts, permanently lifting baseline medical volumes. Merchant and packaged gas channels recovered faster than bulk industrial volumes because small and mid-sized manufacturers rebuilt output ahead of heavy industry. The durable shift is toward on-site generation and long-term take-or-pay contracts, which reduce exposure to spot price swings and lock in capacity for electronics and refining customers.