Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Alpha Olefin Market Size & CAGR 7.5% (2025-2033)
Alpha Olefin Market
Alpha Olefin Market Size & CAGR 7.5% (2025-2033)
Alpha Olefin Market by Product (1-Octene, 1-Hexene, 1-Butene, Others), by Application (Synthetic Lubricants, Detergent Alcohol, Polyethylene, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 14, 2026|Base Year : 2025|Pages : 280
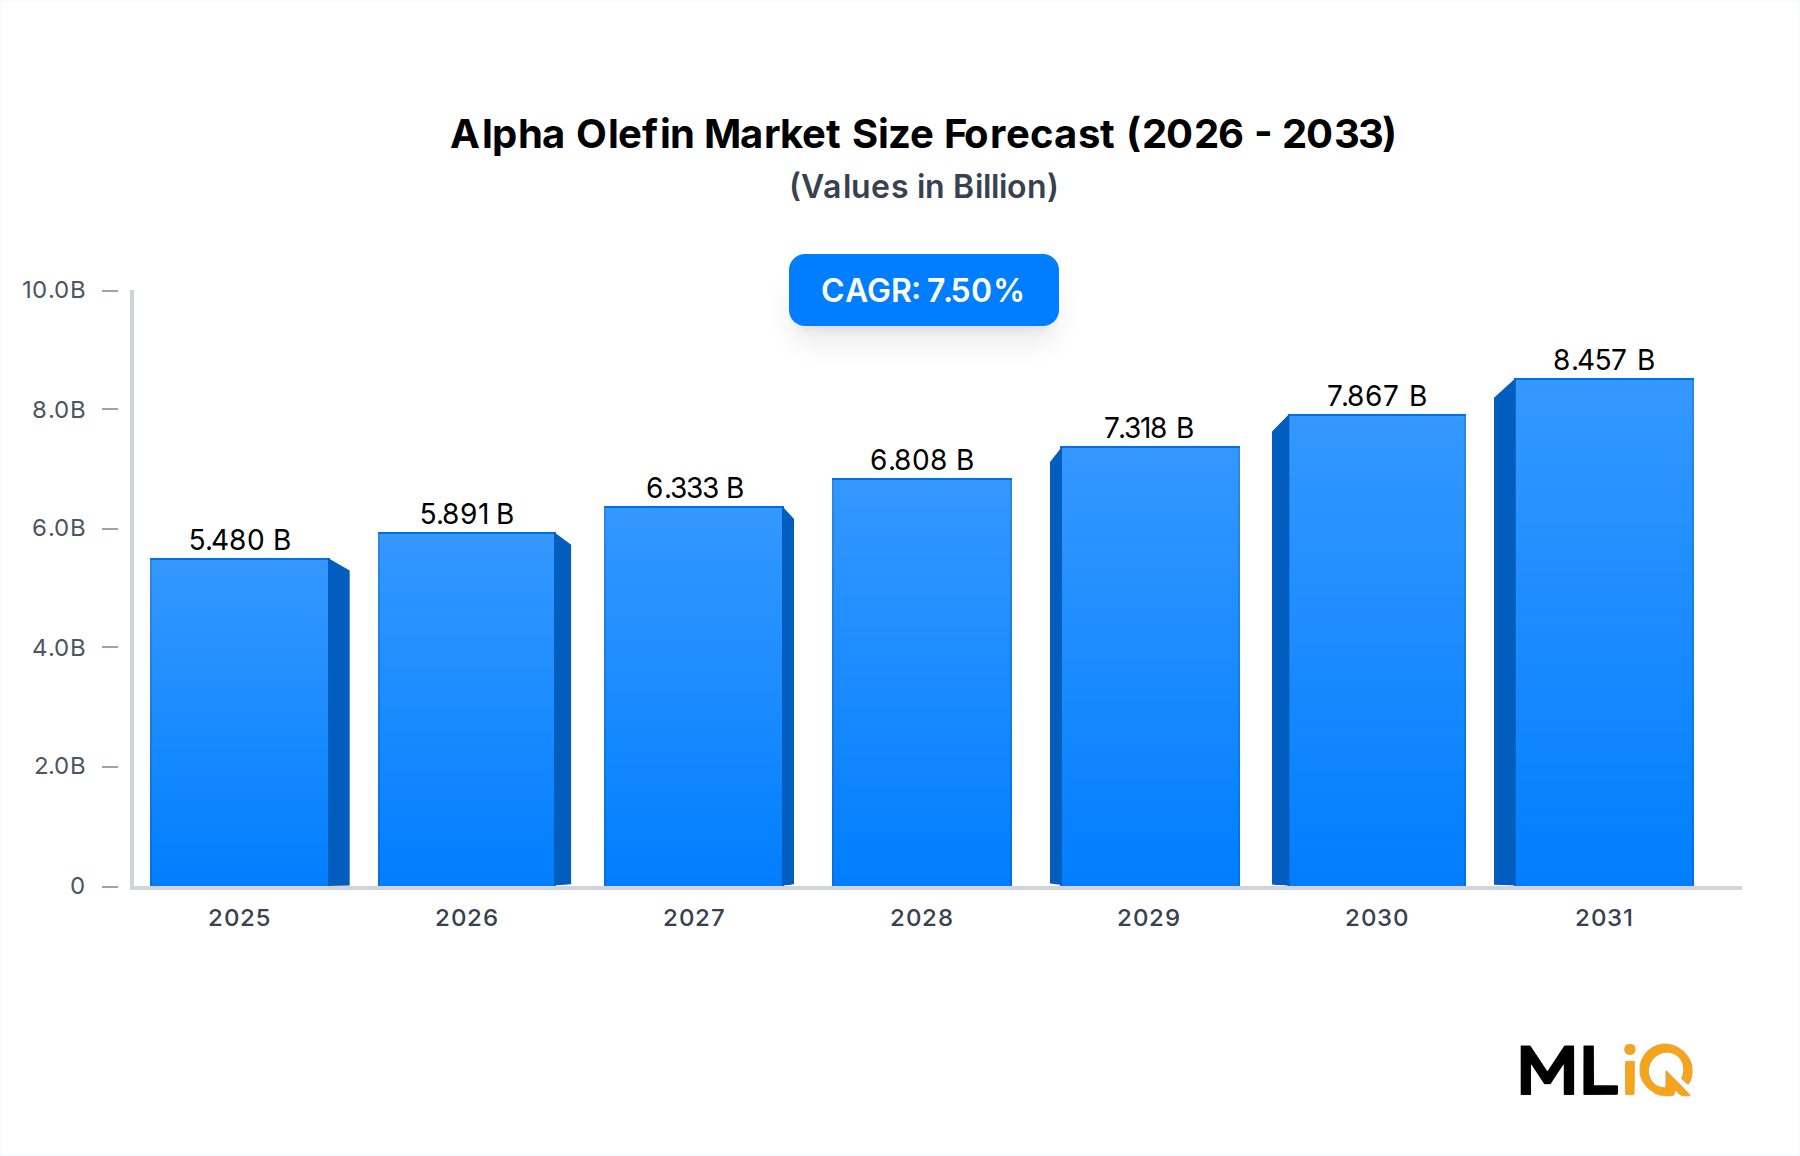
The Alpha Olefin Market is valued at $5.48 billion in 2025 and is projected to reach $9.77 billion by 2033, expanding at a 7.5% CAGR. Demand is anchored by polyethylene co-monomer consumption, with the Polyethylene Market representing the largest downstream outlet. The 1-Hexene Market and 1-Octene Market together account for 61% of product volume because these comonomers deliver superior resin properties in linear low-density polyethylene (LLDPE) and high-density polyethylene (HDPE).
Alpha Olefin Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
5.480 B
2025
5.891 B
2026
6.333 B
2027
6.808 B
2028
7.318 B
2029
7.867 B
2030
8.457 B
2031
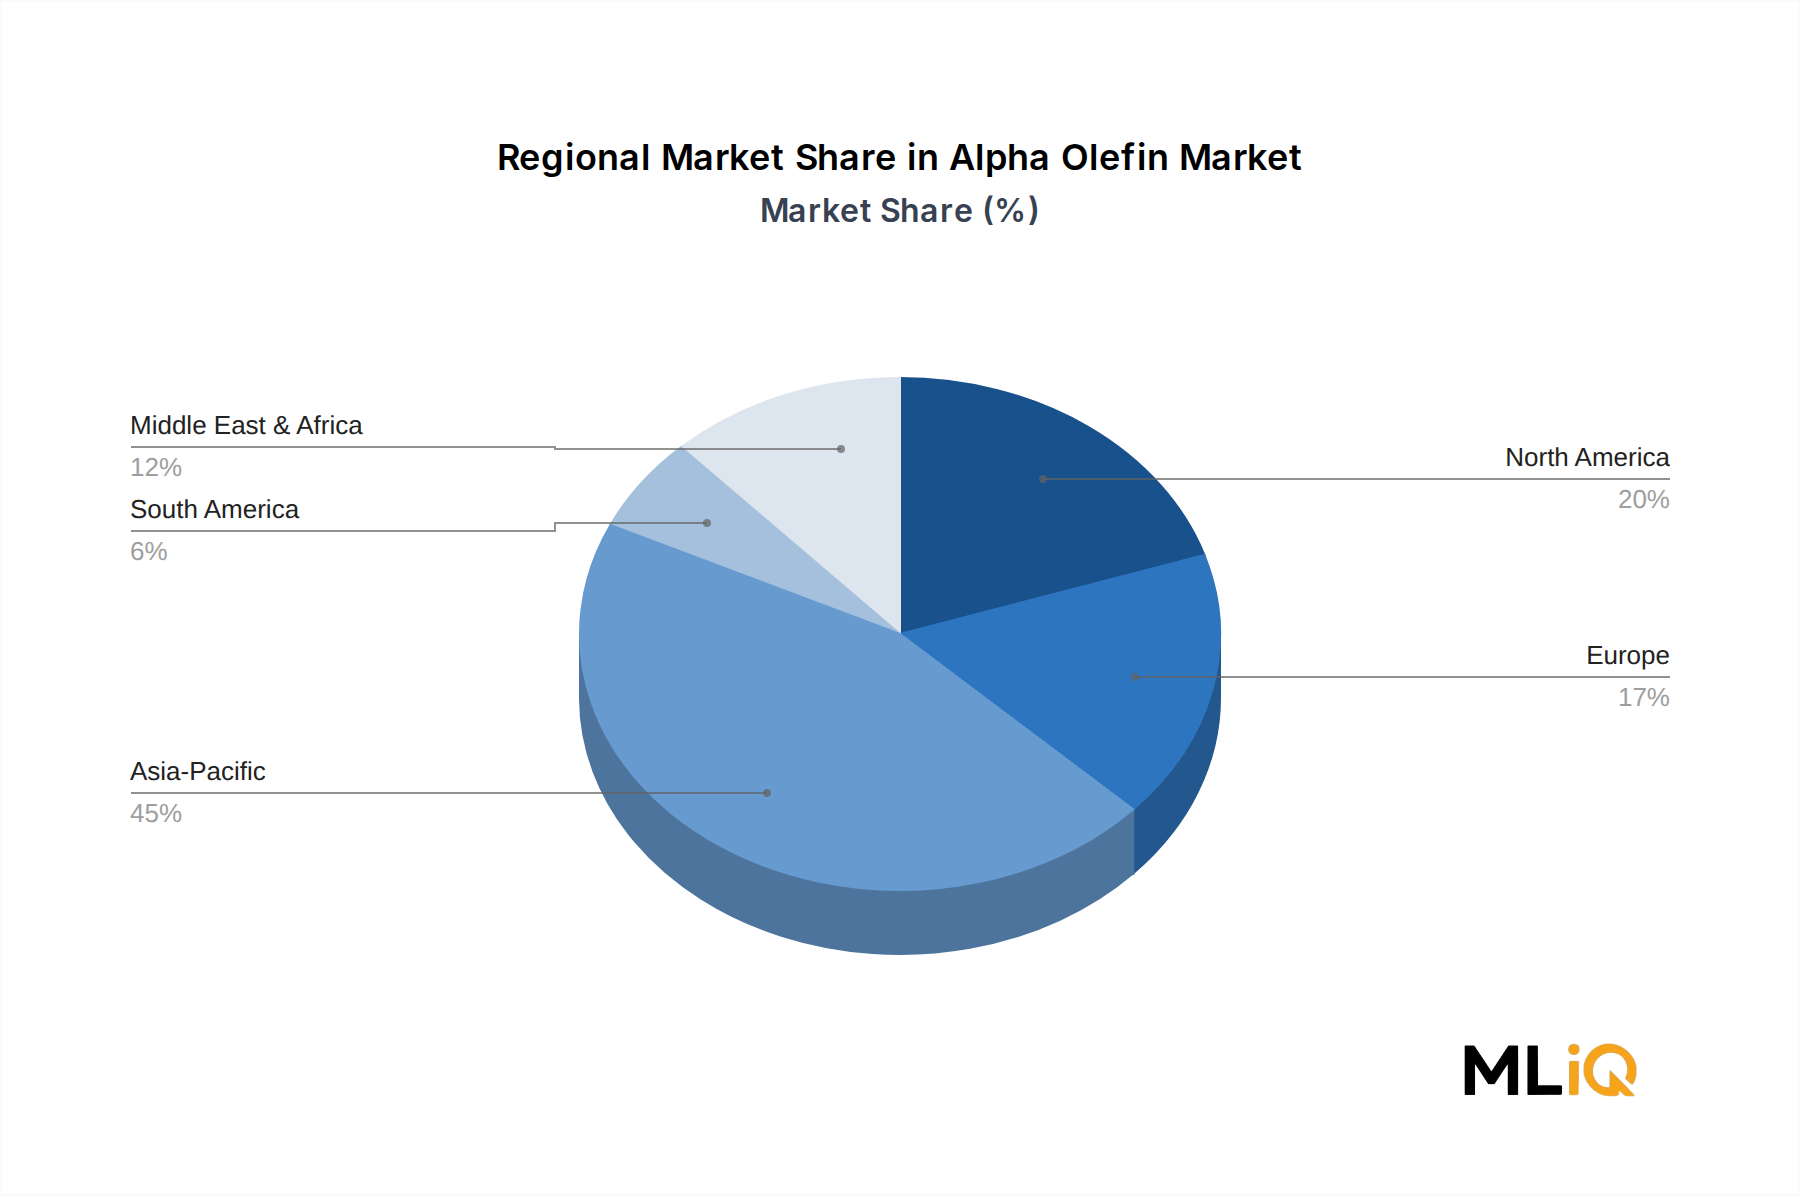
Asia-Pacific dominates both supply and demand, holding 44% of global alpha olefin consumption. China alone added more than 4.2 million tonnes of polyethylene resin capacity between 2022 and 2025, pulling incremental 1-hexene and 1-octene volumes. The Linear Alpha Olefin Market has also shifted toward on-purpose production technologies, reducing dependence on full-range cracker co-product streams. Ethylene feedstock economics remain the single largest cost variable, with naphtha-based producers in Europe and Asia facing a $180–$320 per tonne cost disadvantage versus ethane-based Middle East and North American operators.
Key commercial signals for 2025–2033:
Capacity additions: On-purpose 1-hexene and 1-octene projects account for 68% of announced LAO capacity through 2030.
Application mix: Polyethylene uses 58% of alpha olefins; synthetic lubricants and detergent alcohols use 14% and 12%, respectively.
Trade flows: Middle East & Africa exports 72% of its LAO output, primarily to Asia-Pacific and Europe.
Margin pressure: Integrated producers capture $220–$400 per tonne of value from ethylene to LAO, while non-integrated buyers face volatile contract pricing.
The Ethylene Market remains the upstream anchor, and the Petrochemicals Market provides the capital and infrastructure context for LAO expansions. The Synthetic Lubricants Market and Detergent Alcohol Market are smaller but higher-margin outlets, growing at 6.9% and 6.1% CAGRs, respectively. Overall, the Alpha Olefin Market is moving toward on-purpose, application-specific capacity, with Asia-Pacific shaping both price formation and technology adoption.
Segment Deep-Dive: Polyethylene Dominance in Alpha Olefin Market
Segment Analysis Matrix
CAGR (2025–2033)
Market Share (2025)
Key Demand Driver
Polyethylene
7.8%
58%
LLDPE/HDPE resin demand for packaging, pipes, and automotive parts
Synthetic Lubricants
6.9%
14%
Polyalphaolefin (PAO) base stocks for EV thermal management and industrial lubricants
Detergent Alcohol
6.1%
12%
Alcohol ethoxylates and surfactant demand in Asia-Pacific
1-Hexene (product)
8.1%
34%
Co-monomer for LLDPE film and HDPE blow molding
1-Octene (product)
7.6%
28%
Co-monomer for high-performance PE and synthetic lubricants
Largest Revenue Segment: Polyethylene
Polyethylene consumes 2.9 million tonnes of alpha olefins annually, equivalent to 58% of total demand. The Polyethylene Market is driven by LLDPE film for food packaging, HDPE for pipes and containers, and specialty copolymers for automotive fuel tanks. 1-Hexene and 1-Octene are the preferred comonomers because they reduce density and improve tear strength. On-purpose 1-hexene capacity in the Middle East and North America has lowered import dependence for Asian converters.
Sub-Segment Dynamics
1-Hexene Market: 1-Hexene holds 34% of product volume and grows at 8.1% CAGR, supported by LLDPE capacity additions in China and India.
1-Octene Market: 1-Octene accounts for 28% of product volume and commands a $150–$250 per tonne premium over 1-hexene due to higher comonomer performance.
1-Butene Market: 1-Butene remains a lower-cost comonomer for HDPE and linear low-density polyethylene, with 22% of product volume and a 5.9% CAGR as producers prioritize higher-alpha comonomers for premium resins.
Detergent Alcohol Market: Detergent alcohols use 12% of alpha olefins; the shift to bio-based surfactants creates substitution risk but also premium pricing for certified sustainable LAO derivatives.
Synthetic Lubricants Market: PAO demand grows at 6.9% CAGR, with EV drivetrains requiring 1.5–2.0 liters of PAO per vehicle for thermal management and gear lubrication.
Margin Pressures
Feedstock volatility: Ethylene contract prices in Asia and Europe moved within a $200 per tonne band during 2024, compressing non-integrated LAO margins.
Capital intensity: A 200,000 tonne per annum on-purpose 1-hexene unit requires $450–$600 million in capex, limiting new entrants.
Product qualification: LLDPE producers require 6–12 months to qualify a new 1-octene supplier, creating switching costs but also locking in incumbent volumes.
Logistics costs: Alpha olefins require dedicated storage and nitrogen blanketing; inland Chinese buyers pay $40–$70 per tonne for safe handling and transport.
Primary Market Drivers & Growth Restraints in Alpha Olefin Market
Market Dynamics Impact Analysis
Description
Impact Level
Timeline
Driver
Polyethylene resin demand growth in Asia-Pacific packaging and infrastructure
High
Long term
Driver
On-purpose 1-hexene and 1-octene capacity additions
High
Medium term
Driver
Shift to PAO synthetic lubricants in electric vehicles
Medium
Long term
Driver
Detergent alcohol demand tied to urbanization and hygiene spending
Medium
Long term
Restraint
Volatile ethylene feedstock prices and naphtha-ethane spread
High
Short term
Restraint
High capital intensity of on-purpose LAO units
Medium
Long term
Restraint
Regulatory pressure on single-use plastics in Europe and North America
Medium
Long term
Restraint
Trade tariffs and anti-dumping duties on polyethylene and LAO derivatives
Medium
Short term
The Ethylene Market is the dominant cost driver: ethylene represents 60–75% of alpha olefin cash cost. When ethylene prices rise by $100 per tonne, LAO production costs increase by $65–$80 per tonne, depending on yield. The Petrochemicals Market cycle also influences capex decisions; during the 2023–2024 downturn, several planned LAO projects were deferred by 12–18 months.
Demand catalysts are concentrated in polyethylene. Global polyethylene resin demand is forecast to grow by 3.8% annually through 2033, with LLDPE and HDPE accounting for 76% of incremental alpha olefin demand. The Polyethylene Market in China and India alone will require an additional 1.1 million tonnes of 1-hexene and 1-octene by 2030. On-purpose technology reduces the historical constraint of cracker co-product availability, enabling producers to match comonomer grades to resin specifications.
Restraints are primarily financial and regulatory. A greenfield LAO complex needs $1.2–$1.8 billion for a 500,000 tonne per annum full-range facility, with a 5–7 year payback under mid-cycle pricing. European regulations on single-use plastics could reduce HDPE and LLDPE film demand growth by 0.4–0.6 percentage points annually, partially offset by recycled polymer mandates that favor virgin comonomer performance. Trade policy remains a wildcard: anti-dumping duties on polyethylene from Asia-Pacific and the Middle East can redirect LAO derivatives and alter regional pricing.
Integrated ethylene-to-LAO complex and global logistics
Polyethylene producers, detergent alcohol buyers
Leader
Chevron Phillips Chemical Company LLC
Full-range LAO and on-purpose 1-hexene technology
LLDPE film producers, technology licensees
Leader
Exxon Mobil Corporation
Cracker integration and PAO synthetic lubricant portfolio
Synthetic lubricant blenders, automotive OEMs
Leader
INEOS
Derivative integration and European customer access
Detergent and lubricant formulators
Challenger
Evonik Industries AG
Specialty LAO derivatives and surfactant intermediates
Detergent alcohol producers, personal care formulators
Challenger
Idemitsu Kosan Co., Ltd
Linear alpha olefin process expertise and Asian market presence
Asia-Pacific PE producers
Niche
Qatar Chemical Company Ltd
Low-cost gas-based ethylene feedstock
Export-oriented polymer makers
Challenger
LANXESS
Specialty chemical distribution and additive formulation
Industrial formulators
Niche
The Linear Alpha Olefin Market is moderately concentrated, with the top five suppliers controlling 58% of global capacity. Integration into ethylene and polyethylene is the strongest competitive moat.
SABIC: Operates one of the largest LAO complexes in the Middle East, with 1.3 million tonnes per annum of alpha olefin capacity and backward integration into ethane cracking.
Chevron Phillips Chemical Company LLC: Holds proprietary on-purpose 1-hexene technology and supplies 30% of global 1-hexene merchant volumes. Its licensing model accelerates capacity additions in Asia.
Exxon Mobil Corporation: Combines refinery and chemical integration with a 400,000 tonne per annum PAO business, targeting EV thermal management fluids.
INEOS: Uses European cracker flexibility and downstream detergent alcohol assets to serve formulators; its LAO volumes are largely captive.
Evonik Industries AG: Focuses on high-purity LAO derivatives and surfactant intermediates, with 12% of European detergent alcohol precursor capacity.
Idemitsu Kosan Co., Ltd: Supplies niche alpha olefin grades to Japanese and South Korean polyethylene producers, with 180,000 tonnes per annum of LAO capacity.
Qatar Chemical Company Ltd: Leverages low-cost ethane from Qatar to export LAO and polyethylene to Asia and Europe, with 750,000 tonnes per annum of olefin capacity.
LANXESS: Participates through specialty chemical distribution and additive packages for lubricant and polymer formulators, not primary LAO production.
Strategic Milestones & Recent Developments in Alpha Olefin Market
Latest Strategic Moves
Company
Event Type
Impact
Q1 2025
SABIC
Expansion
Added 150,000 tonnes per annum of 1-hexene capacity in Saudi Arabia
Q4 2024
Chevron Phillips Chemical Company LLC
Technology licensing
Licensed on-purpose 1-hexene process to an Asian producer, adding 120,000 tonnes per annum
Q3 2024
INEOS
Partnership
Joint marketing of LAO derivatives in Europe to improve detergent alcohol supply reliability
Q2 2024
Exxon Mobil Corporation
Launch
New PAO grade for EV thermal management with 15% higher oxidation stability
Q1 2024
Evonik Industries AG
M&A
Acquired surfactant intermediates assets to backward integrate into detergent alcohol feedstocks
2023
Qatar Chemical Company Ltd
Expansion
Debottlenecked LAO unit by 80,000 tonnes per annum to serve Asian polyethylene demand
Q1 2025 – SABIC expansion: The 150,000 tonnes per annum 1-hexene addition strengthens SABIC's position in Asia-Pacific LLDPE markets and reduces regional import reliance.
Q4 2024 – Chevron Phillips Chemical licensing: The technology license adds 120,000 tonnes per annum of on-purpose 1-hexene capacity, validating the shift away from full-range co-product supply.
Q3 2024 – INEOS partnership: The European marketing agreement improves detergent alcohol precursor availability, where REACH compliance and logistics costs create barriers.
Q2 2024 – Exxon Mobil PAO launch: The new PAO grade targets EV thermal management, a segment growing at 9.2% CAGR and requiring high-viscosity-index base stocks.
Q1 2024 – Evonik acquisition: The deal secures surfactant intermediates and supports integrated detergent alcohol production in Europe.
2023 – Qatar Chemical debottlenecking: The 80,000 tonnes per annum expansion lowers unit costs and increases export volumes to China and Southeast Asia.
Regional Market Analysis & Growth Corridors for Alpha Olefin Market
Regional Growth Comparison
Projected CAGR (%)
Base Year Valuation ($B)
Primary Catalyst
Regulatory Stringency
North America
6.9%
1.04
Shale gas ethane advantage and PAO lubricant demand
Medium
Europe
6.2%
0.99
REACH-compliant detergent alcohol and synthetic lubricant growth
High
Asia-Pacific
8.8%
2.41
Polyethylene resin capacity additions in China and India
Medium
Middle East & Africa
7.6%
0.66
Low-cost ethylene feedstock and export-oriented LAO capacity
Low
South America
6.4%
0.38
Petrochemicals integration in Brazil and Argentina
Medium
Asia-Pacific is the fastest-growing and largest region, with 44% of global Alpha Olefin Market revenue in 2025. China's polyethylene capacity additions drive 1-Hexene Market and 1-Octene Market demand, while India's detergent alcohol demand supports 1-Butene Market volumes for HDPE and surfactant intermediates. The region is expected to add 2.3 million tonnes of alpha olefin capacity by 2033, primarily on-purpose 1-hexene and 1-octene.
North America is the most mature market, growing at 6.9% CAGR from a $1.04 billion base. Shale gas ethane provides a $200–$300 per tonne cost advantage, and the Synthetic Lubricants Market benefits from PAO demand in EV thermal management. The Polyethylene Market remains the largest outlet, but export competitiveness depends on trade policy and logistics.
Europe grows at 6.2% CAGR, constrained by high naphtha feedstock costs and stringent REACH regulation. The Detergent Alcohol Market and Synthetic Lubricants Market are the primary growth pockets, with demand shifting toward bio-based and recycled feedstocks. Middle East & Africa grows at 7.6% CAGR, leveraging low-cost ethane and export-oriented LAO capacity; regulatory stringency is low, but carbon border adjustment mechanisms could affect export economics after 2026. South America grows at 6.4% CAGR, led by Brazil's petrochemical integration and Argentina's shale gas potential, though currency volatility and underinvestment limit capacity growth.
Supply Chain & Raw Material Dynamics: Alpha Olefin Market
Upstream dependencies are concentrated in ethylene and cracker co-product streams. The Ethylene Market determines LAO cash costs, and the Petrochemicals Market cycle shapes capacity decisions. Key supply chain dynamics:
Feedstock concentration: 78% of global alpha olefin capacity is integrated with ethylene crackers or on-purpose ethylene-to-LAO units. Non-integrated producers purchase ethylene on contract, exposing them to $150–$250 per tonne price swings.
Sourcing risks: Full-range LAO units produce a slate of 1-butene, 1-hexene, 1-octene, and heavier fractions. Demand growth is skewed toward 1-hexene and 1-octene, creating a product imbalance that forces producers to find outlets for 1-butene and C10+ fractions.
Price volatility: Between 2021 and 2024, 1-hexene spot prices in Asia moved from $1,450 to $2,100 per tonne and back to $1,700 per tonne, driven by ethylene costs and polyethylene operating rates.
Historical disruptions: The 2021 U.S. winter storm Uri shut 60% of Gulf Coast ethylene capacity for up to two weeks, causing a $400 per tonne spike in 1-hexene prices. COVID-19 logistics constraints in 2020–2021 delayed LAO shipments by 4–6 weeks.
Vendor dependencies: Chevron Phillips Chemical Company LLC, SABIC, and Exxon Mobil Corporation control a significant share of merchant 1-hexene and 1-octene supply. A single unplanned outage at a 200,000 tonne per annum unit can tighten global markets by 3–5%.
Logistics and storage: Alpha olefins require stainless steel or lined vessels, nitrogen blanketing, and temperature control below 40°C to prevent polymerization. Dedicated storage adds $25–$45 per tonne to delivered costs in inland Asia.
The 1-Octene Market faces tighter supply than 1-hexene because fewer on-purpose units produce it. This supports a structural premium of $150–$250 per tonne and encourages new on-purpose 1-octene technology. The 1-Hexene Market is better supplied, but qualification cycles at LLDPE producers limit rapid market rebalancing.
Alpha olefins are regulated as industrial chemicals, with compliance requirements varying by region. Key frameworks:
Europe: REACH requires registration of 1-hexene, 1-octene, 1-butene, and detergent alcohol intermediates. The European Chemicals Agency (ECHA) has placed certain LAO derivatives on the Community Rolling Action Plan, increasing testing costs by 10–15% for producers. The Single-Use Plastics Directive reduces demand for virgin HDPE and LLDPE film, indirectly affecting Polyethylene Market growth.
North America: The U.S. Environmental Protection Agency (EPA) regulates LAO under the Toxic Substances Control Act (TSCA). New on-purpose 1-hexene and 1-octene facilities require pre-manufacture notices, adding 6–12 months to project timelines. OSHA process safety management applies to ethylene and LAO storage.
Asia-Pacific: China's Ministry of Ecology and Environment enforces VOC emission limits on petrochemical complexes, requiring $15–$30 million in additional control equipment for a 500,000 tonne per annum LAO unit. India's Chemical (Amendment) Rules align with REACH-style registration for imported alpha olefins.
Middle East & Africa: Regulatory stringency is lower, but GCC producers face increasing scrutiny under EU carbon border adjustment mechanism (CBAM) for polyethylene and LAO exports. Saudi Arabia's environmental standards are tightening under Vision 2030.
Global standards: ISO 9001 and ISO 14001 certification is mandatory for most polyethylene and detergent alcohol customers. The Synthetic Lubricants Market requires API base oil approvals for PAO grades, and the Detergent Alcohol Market requires biodegradability documentation under OECD 301B.
Policy changes projected through 2033 include stricter carbon pricing in Europe, expanded chemical registration in Asia-Pacific, and potential anti-dumping duties on LAO derivatives. Compliance costs are expected to add 3–5% to delivered alpha olefin prices in regulated markets, favoring integrated producers with scale and low-carbon feedstock access.
Alpha Olefin Market Segmentation
1. Product
1.1. 1-Octene
1.2. 1-Hexene
1.3. 1-Butene
1.4. Others
2. Application
2.1. Synthetic Lubricants
2.2. Detergent Alcohol
2.3. Polyethylene
2.4. Others
Alpha Olefin Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Alpha Olefin Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.5% from 2020-2034
Segmentation
By Product
1-Octene
1-Hexene
1-Butene
Others
By Application
Synthetic Lubricants
Detergent Alcohol
Polyethylene
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. 1-Octene
5.1.2. 1-Hexene
5.1.3. 1-Butene
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Synthetic Lubricants
5.2.2. Detergent Alcohol
5.2.3. Polyethylene
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. 1-Octene
6.1.2. 1-Hexene
6.1.3. 1-Butene
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Synthetic Lubricants
6.2.2. Detergent Alcohol
6.2.3. Polyethylene
6.2.4. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. 1-Octene
7.1.2. 1-Hexene
7.1.3. 1-Butene
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Synthetic Lubricants
7.2.2. Detergent Alcohol
7.2.3. Polyethylene
7.2.4. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. 1-Octene
8.1.2. 1-Hexene
8.1.3. 1-Butene
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Synthetic Lubricants
8.2.2. Detergent Alcohol
8.2.3. Polyethylene
8.2.4. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. 1-Octene
9.1.2. 1-Hexene
9.1.3. 1-Butene
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Synthetic Lubricants
9.2.2. Detergent Alcohol
9.2.3. Polyethylene
9.2.4. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. 1-Octene
10.1.2. 1-Hexene
10.1.3. 1-Butene
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Synthetic Lubricants
10.2.2. Detergent Alcohol
10.2.3. Polyethylene
10.2.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. SABIC
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Qatar Chemical Company Ltd
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Idemitsu Kosan Co.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ltd
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Chevron Phillips Chemical Company LLC
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Evonik Industries AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. INEOS
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. LANXESS
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Exxon Mobil Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Alpha Olefin Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Alpha Olefin Market Revenue (billion), by Product 2026 & 2034
Figure 3: North America Alpha Olefin Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Alpha Olefin Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Alpha Olefin Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Alpha Olefin Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Alpha Olefin Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Alpha Olefin Market Revenue (billion), by Product 2026 & 2034
Figure 9: South America Alpha Olefin Market Revenue Share (%), by Product 2026 & 2034
Figure 10: South America Alpha Olefin Market Revenue (billion), by Application 2026 & 2034
Figure 11: South America Alpha Olefin Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Alpha Olefin Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Alpha Olefin Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Alpha Olefin Market Revenue (billion), by Product 2026 & 2034
Figure 15: Europe Alpha Olefin Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Alpha Olefin Market Revenue (billion), by Application 2026 & 2034
Figure 17: Europe Alpha Olefin Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Alpha Olefin Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Alpha Olefin Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Alpha Olefin Market Revenue (billion), by Product 2026 & 2034
Figure 21: Middle East & Africa Alpha Olefin Market Revenue Share (%), by Product 2026 & 2034
Figure 22: Middle East & Africa Alpha Olefin Market Revenue (billion), by Application 2026 & 2034
Figure 23: Middle East & Africa Alpha Olefin Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Alpha Olefin Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Alpha Olefin Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Alpha Olefin Market Revenue (billion), by Product 2026 & 2034
Figure 27: Asia Pacific Alpha Olefin Market Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Alpha Olefin Market Revenue (billion), by Application 2026 & 2034
Figure 29: Asia Pacific Alpha Olefin Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Alpha Olefin Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Alpha Olefin Market Revenue Share (%), by Country 2026 & 2034
Table 46: Rest of Asia Pacific Alpha Olefin Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of the study, with 300+ interviews conducted across the alpha olefin value chain. Participants include ethylene cracker operators co-producing linear alpha olefins, on-purpose 1-hexene and 1-octene technology licensors, high-density polyethylene and linear low-density polyethylene resin producers, detergent alcohol and polyalphaolefin synthetic lubricant manufacturers, and specialty chemical distributors and export traders for alpha olefin streams.
Stakeholder interviews target job titles including Alpha Olefin Business Unit Director, Polyolefin Procurement Manager, Process Technology Licensing Engineer, Petrochemical Supply Chain Analyst, and Regulatory & Product Stewardship Lead.
Interviews are structured around capacity, utilization, feedstock contracts, application qualification timelines, and pricing mechanisms. Each interview is transcribed and coded for quantitative triangulation.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Alpha Olefin Business Unit Director
25%
Polyolefin Procurement Manager
25%
Process Technology Licensing Engineer
20%
Petrochemical Supply Chain Analyst
15%
Regulatory & Product Stewardship Lead
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ethylene cracker operators co-producing linear alpha olefins
30%
On-purpose 1-hexene and 1-octene technology licensors
20%
High-density polyethylene and linear low-density polyethylene resin producers
25%
Detergent alcohol and polyalphaolefin synthetic lubricant manufacturers
15%
Specialty chemical distributors and export traders for alpha olefin streams
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of inputs and relies on financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Benchmarking covers plant-level capacity, on-purpose versus full-range technology economics, polyethylene resin demand, and detergent alcohol and synthetic lubricant consumption trends.
Demand Modeling & Market Estimation
Bottom-up and top-down methodologies are used simultaneously, validated via multi-level data triangulation. The bottom-up model multiplies specific quantitative metrics: global ethylene cracker capacity by region (tonnes per annum), average alpha olefin yield per ethylene cracker (%), polyethylene resin demand by application (million tonnes), detergent alcohol and synthetic lubricant consumption per capita, and on-purpose 1-hexene and 1-octene plant utilization rates.
Top-down modeling starts from the broader petrochemicals and polyethylene markets and assigns alpha olefin intensity by product grade and application. Regional demand is cross-checked against trade flows, import/export statistics, and producer capacity announcements.
Segment-level forecasts for 1-octene, 1-hexene, 1-butene, and others are reconciled with application demand for synthetic lubricants, detergent alcohol, polyethylene, and other outlets. The base year is 2025, with forecasts to 2034.
Data Accuracy & Quality Check
Estimated data accuracy is guaranteed at 85–90%. All quantitative inputs are validated through at least two independent sources, and discrepancies greater than 5% trigger reconciliation interviews.
Quality control includes a multi-level data triangulation process: primary interview data, secondary financial and trade databases, and regulatory filings. Outlier capacity figures are tested against nameplate and effective operating rates.
Every report is updated to the date of purchase. Post-purchase updates capture new capacity announcements, feedstock price movements, and regulatory changes, ensuring the Alpha Olefin Market analysis remains current through the forecast horizon.
Frequently Asked Questions
1. How has the Alpha Olefin Market recovered after the pandemic, and what structural shifts are permanent?
The market recovered by 2022 as polyethylene demand rebounded and cracker utilization returned above 85%. A permanent shift is the move toward on-purpose 1-hexene and 1-octene capacity, which now accounts for 68% of announced additions through 2030. Asia-Pacific added over 4.2 million tonnes of polyethylene resin capacity between 2022 and 2025, pulling alpha olefin demand away from traditional Western trade flows.
2. What are the largest product and application segments in the Alpha Olefin Market?
1-Hexene and 1-Octene are the largest products, together representing 61% of volume in 2025, while 1-Butene holds 22%. Polyethylene is the dominant application at 58% of demand, followed by synthetic lubricants at 14% and detergent alcohol at 12%. Growth is fastest in 1-Hexene at 8.1% CAGR, driven by LLDPE film and HDPE blow molding.
3. How are purchasing trends changing for alpha olefin buyers?
Buyers increasingly require supply contracts with 3-5 year terms and price formulas linked to ethylene, rather than spot purchases. LLDPE producers now demand 6-12 month qualification trials for new 1-octene suppliers, favoring incumbents like Chevron Phillips Chemical Company LLC, SABIC, and Exxon Mobil Corporation. Sustainability clauses for lower-carbon alpha olefins appear in 30% of European detergent alcohol tenders.
4. What are the current pricing trends and cost structure dynamics in the Alpha Olefin Market?
Alpha olefin prices are 60-75% driven by ethylene cash costs, with 1-hexene spot prices in Asia moving between $1,450 and $2,100 per tonne from 2021 to 2024. 1-Octene carries a structural premium of $150-$250 per tonne because fewer on-purpose units produce it. Integrated producers with ethane feedstock hold a $200-$300 per tonne cost advantage over naphtha-based European and Asian producers.
5. How do sustainability and ESG factors affect the Alpha Olefin Market?
REACH, TSCA, and China's VOC rules require registration and emissions controls, adding 3-5% to delivered costs in regulated markets. The EU Single-Use Plastics Directive could reduce virgin polyethylene film demand growth by 0.4-0.6 percentage points annually. Bio-based detergent alcohols and recycled polymer mandates are creating premium niches, particularly for certified sustainable alpha olefin derivatives.
6. What are the primary growth drivers and demand catalysts for the Alpha Olefin Market?
Polyethylene resin demand growth of 3.8% annually through 2033 is the largest catalyst, requiring an additional 1.1 million tonnes of 1-hexene and 1-octene by 2030 in China and India alone. On-purpose capacity additions and PAO synthetic lubricant demand in EVs, growing at 9.2% CAGR, are secondary drivers. Middle East & Africa exports 72% of its LAO output, linking regional capacity growth to Asian polyethylene expansion.