Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Chemical Injection Skids Market: 5.8% CAGR to 2033
Chemical Injection Skids Market
Chemical Injection Skids Market: 5.8% CAGR to 2033
Chemical Injection Skids Market by End-user Industry (Petrochemicals, Chemicals, Energy & Power, Oil & Gas, Water Treatment), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Chemical Injection Skids Market
Chemical injection skids are packaged assemblies of metering pumps, manifolds, flow meters, control valves, and instrumentation that dose precise volumes of corrosion inhibitors, scale inhibitors, biocides, demulsifiers, and coagulants into process streams. The category is small in absolute value, USD 1.60 billion in 2024, but high in consequence: an estimated 68% of installed units run continuous duty, where a dosing deviation triggers pipeline corrosion, off-spec product, or a regulatory exceedance within hours.
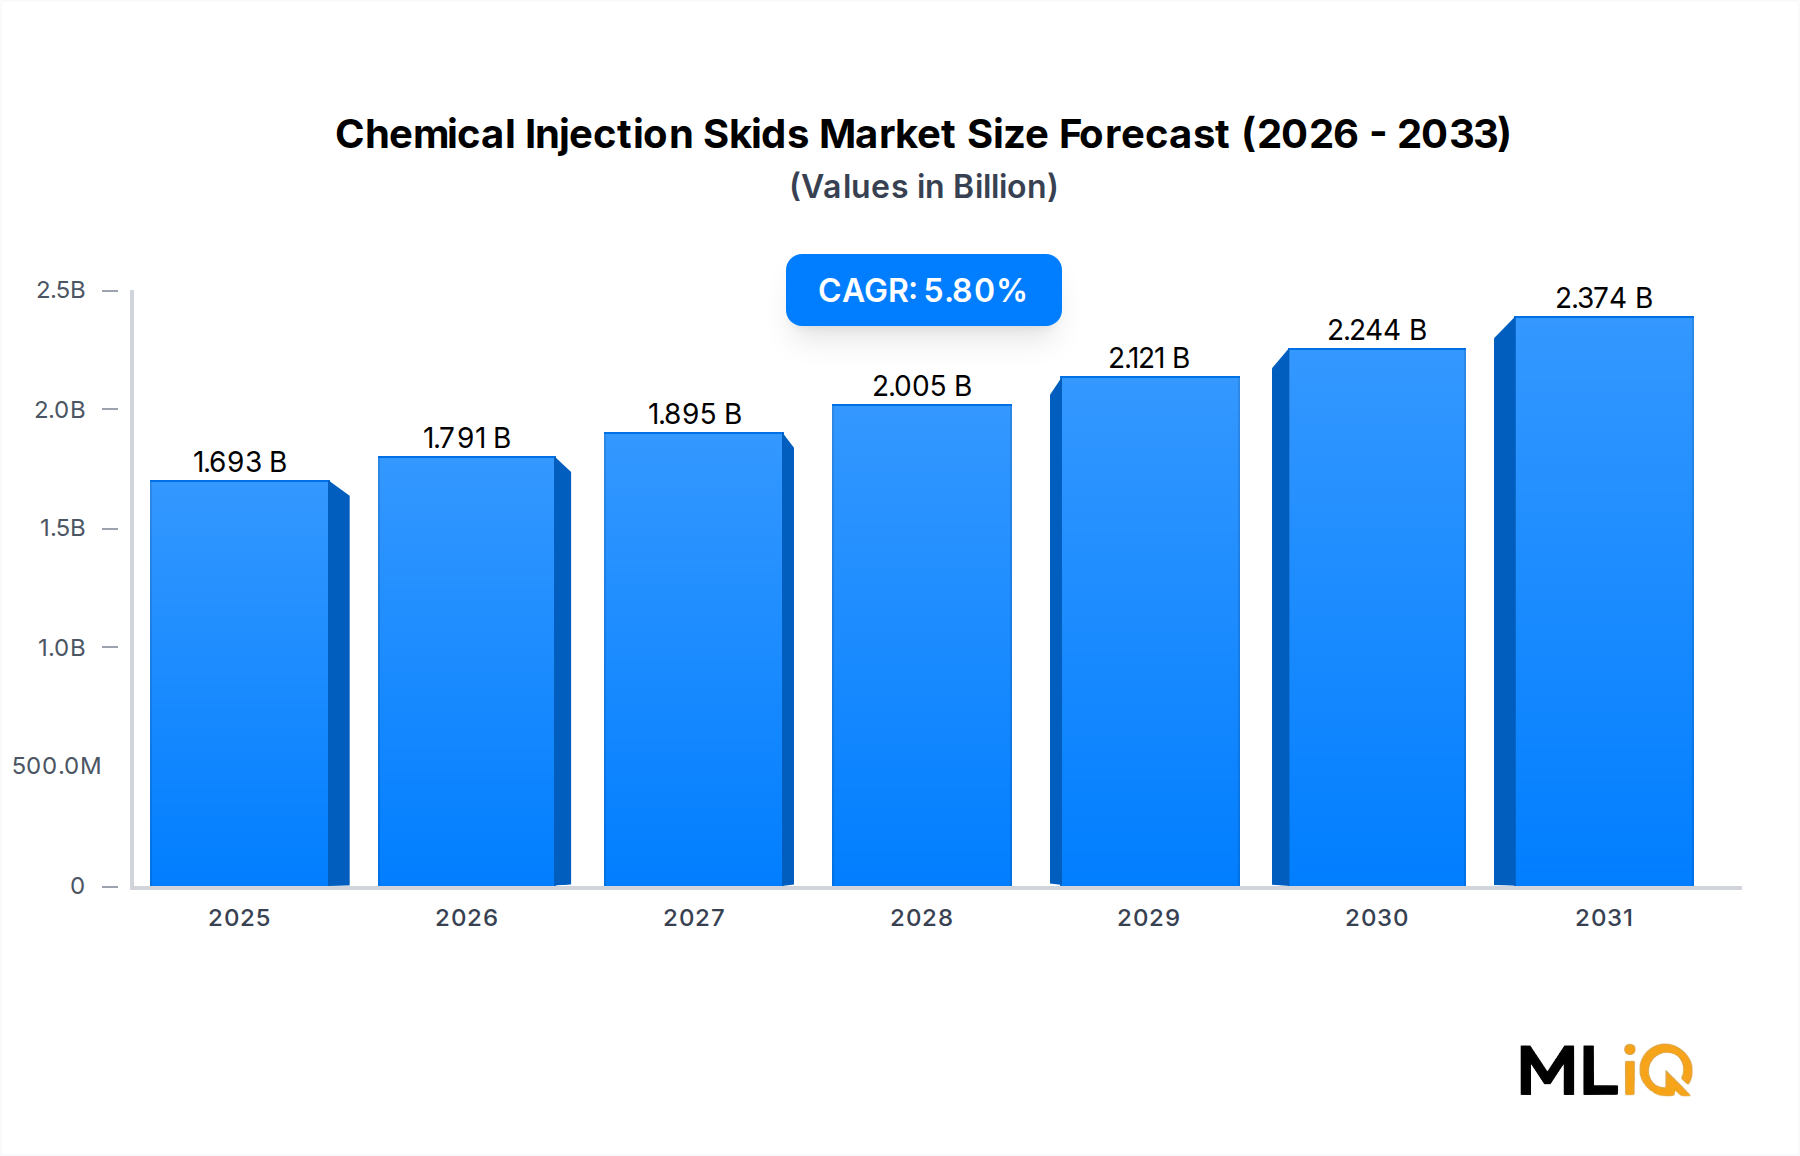
Chemical Injection Skids Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.693 B
2025
1.791 B
2026
1.895 B
2027
2.005 B
2028
2.121 B
2029
2.244 B
2030
2.374 B
2031
Three demand structures define the 2026-2034 forecast. First, upstream and midstream operators in mature basins are extending asset life rather than drilling new wells, which pushes retrofit spending into the Chemical Injection Skid Packages Market. Second, power generators and industrial boiler operators are tightening water chemistry control as efficiency and emissions targets rise. Third, municipal and industrial water utilities are converting manual dosing to instrumentation-grade systems.
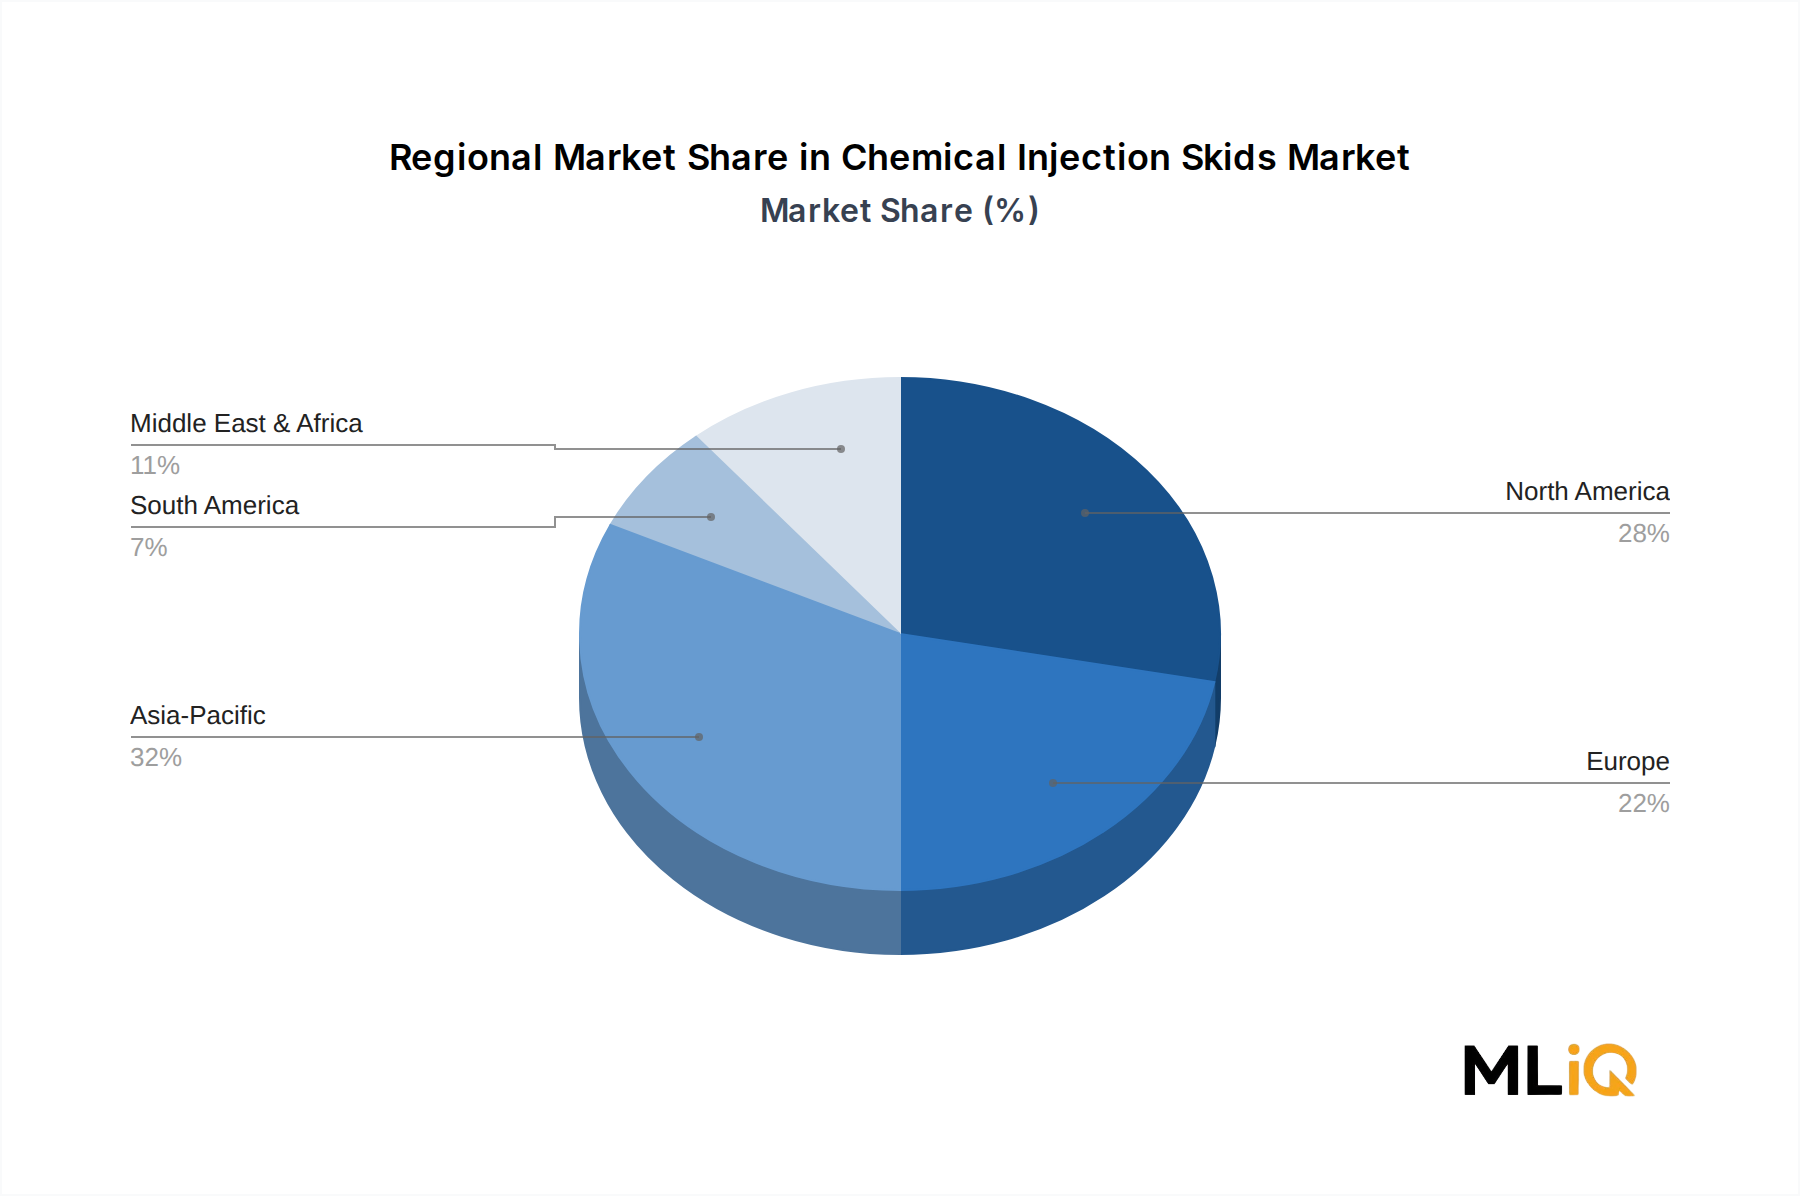
Asia-Pacific holds ~32% of global revenue (about USD 512 million in 2024), led by refining, petrochemical, and municipal water investment in China, India, and ASEAN.
Oil & Gas contributes ~34% of end-user spend, with water treatment and power adding roughly 38% combined.
Energy & Power is the fastest-expanding pool at 6.7% CAGR, driven by boiler feedwater and emissions-control chemistry.
Retrofit and aftermarket activity is estimated at 38% of skid revenue, rising as the installed base passes its 10-12 year replacement window.
Modular skid packaging cuts field installation labor by 30-40% versus stick-built dosing assemblies and shortens project schedules by 4-8 weeks.
Pricing power sits with the pump head and the control layer, not the skid frame. Suppliers that bundle API 675-compliant metering pumps with certified control panels defend gross margins in the 35-45% range, while frame-and-piping fabricators typically operate at 18-24%. Consolidation among owners of pump and instrumentation IP is therefore the single most important structural force through 2033.
Segment Deep-Dive: Oil & Gas Dominance in Chemical Injection Skids Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Oil & Gas
5.2
34
Corrosion and scale inhibition in aging wells and gathering lines
Disinfection, coagulation, and membrane antiscalant dosing
Others (food, pharma, mining)
4.5
7
Hygienic and reagent-grade dosing
Total
5.8
100
—
Oil & Gas: Volume Anchored in Aging Fields
Oil and gas is the largest single revenue pool at ~34% share, but its growth rate (5.2% CAGR) trails the overall market because Western upstream capital discipline caps new greenfield skid orders. Growth comes from three retrofit vectors:
Continuous corrosion inhibitor injection on mature gathering networks, where one skid can serve 8-20 injection points.
Demulsifier and desalter dosing in refineries running heavier crude slates.
Scale and hydrate inhibition at subsea and remote wellheads, where the Oil & Gas Chemical Injection Market is shifting toward solar-powered, low-flow metering skids.
Average contract values in upstream retrofit range from USD 60,000 to USD 450,000 per skid, depending on injection-point count, materials of construction, and certification scope. Buyers in this segment weight field-proven pump mean-time-between-failure data above capital cost.
Energy & Power: The Fastest-Growing Demand Pool
At 6.7% CAGR, energy and power is the growth engine of the forecast period. Combined-cycle plants, biomass boilers, and industrial cogeneration units all require tighter feedwater and steam-cycle chemistry as heat rates and emission limits tighten. The Metering Pump Skids Market tied to boiler and cooling-water duty is expanding faster than the broader pump category because utilities are retiring manual chemical feed in favor of closed-loop skids with redundant pump heads.
Diaphragm-based pump heads dominate this duty. The Diaphragm Pump Systems Market accounts for an estimated 61% of skid-mounted pump heads in power and water service, because PTFE and PVDF diaphragms tolerate hypochlorite, coagulant, and caustic chemistries that attack plunger seals. This material preference creates a durable recurring revenue stream in diaphragm and check-valve replacement, typically on a 12-24 month cycle.
Margin Pressures Across the Segment Stack
Alloy price volatility feeds directly into frame, manifold, and pump-head cost, which represents 22-30% of total skid bill of materials.
Certification (ATEX, IECEx, PED, UL 508A) adds 8-12% to unit cost and lengthens lead times by 6-10 weeks.
Water treatment tenders are the most price-competitive: municipal procurement usually awards on lowest compliant bid, compressing distributor margins to 12-18%.
Chemicals and petrochemicals buyers accept higher prices for dosing accuracy and audit trails, sustaining 30-38% gross margins for instrumentation-rich packages.
Primary Market Drivers & Growth Restraints in Chemical Injection Skids Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Rapid growth in chemical and petrochemical capacity additions across Asia-Pacific and the Middle East
High
Long term
Driver
Accelerating demand from water treatment applications, including disinfection and membrane antiscalant dosing
High
Long term
Driver
Retrofit of aging dosing assets as installed skids pass the 10-12 year replacement cycle
Medium
Short term
Driver
Tightening effluent and emissions limits requiring verifiable, auditable dosing records
High
Medium term
Restraint
Maturing markets in developed economies of Europe and North America, where capex is largely replacement-driven
High
Long term
Restraint
Long lead times of 16-30 weeks for specialty alloy pump heads and certified control panels
Medium
Short term
Restraint
Shortage of commissioning and calibration technicians for dosing control loops
Medium
Medium term
Two structural drivers carry the forecast. First, capacity expansion in the Specialty Chemicals Market adds reagent and additive dosing points at new plants in China, India, Saudi Arabia, and Southeast Asia, where a single greenfield complex can require 40-120 injection points. Second, the Water Treatment Chemical Dosing Market is converting from manual gravity feed to skid-mounted dosing under tightening discharge permits, with municipal utilities replacing chlorination hardware at scale.
Retrofit economics reinforce both drivers. A skid replacement costs USD 45,000-300,000 against a corrosion-failure remediation cost that routinely exceeds USD 1.5 million in midstream pipeline service, so payback arguments are straightforward when asset integrity teams control the budget.
The restraint side is geographic rather than cyclical. Europe grows at 4.2% CAGR and North America at 4.6% CAGR, both dominated by replacement demand where incumbents already hold framework agreements. Europe's Very High regulatory stringency also lengthens qualification cycles: a new dosing chemistry or wetted material can require 9-15 months of compliance documentation before commercial deployment, slowing new-entrant penetration.
Competitive Ecosystem & Key Vendor Profiles: Chemical Injection Skids Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
IDEX Corporation
Metering pump platforms plus flow instrumentation
Upstream, refining, water utilities
Leader
SPX FLOW Inc
Engineered fluid handling and hygienic dosing packages
Food, pharma, power, oil & gas
Leader
Lewa GmbH
High-pressure diaphragm metering pumps and process skids
Refining, chemicals, gas processing
Leader
Milton Roy Europe
Controlled-volume pumps and dosing controllers
Water, power, industrial chemicals
Leader
Proserv Group Inc
Field service, controls, and brownfield skid integration
Upstream oil & gas
Challenger
Integrated Flow Solutions LLC (IFS)
Modular packaged skids and fuel gas conditioning
Midstream, power generation
Challenger
Petronash
Skid packaging and process modules for upstream duty
Middle East upstream operators
Challenger
Seko SpA
Compact dosing pumps and proportional controllers
Water treatment, industrial laundries
Niche
AES Arabia Ltd
Water and wastewater dosing packages
GCC municipal and industrial water
Niche
Carotek Inc, Intech Process Automation Inc
Distribution, SCADA, and dosing loop integration
Regional process plants
Niche
Competition in the Industrial Flow Control Market is layered: pump OEMs own the dosing accuracy specification, fabricators own the mechanical package, and automation integrators own the control narrative. Buyers increasingly consolidate award to a single vendor able to warranty the entire dosing loop, which favors IDEX, SPX FLOW, and Lewa in technically demanding service.
IDEX Corporation: Controls metering pump IP and instrumentation across Pulsafeeder-class platforms, giving it specification control at the pump-head level and defensible aftermarket parts revenue.
SPX FLOW Inc: Post-take-private, it has concentrated on process equipment and hygienic dosing, positioning against food, pharmaceutical, and power accounts that require documented cleanability.
Lewa GmbH: Holds a strong position in high-pressure diaphragm metering above 400 bar, a specification band where few integrators can qualify a competing package.
Milton Roy Europe: Combines controlled-volume pumps with dosing controllers, making it a frequent incumbent in municipal water and industrial cooling frameworks.
Proserv Group Inc: Competes on brownfield service and controls retrofit rather than greenfield fabrication, capturing revenue from skids other vendors originally supplied.
Integrated Flow Solutions LLC (IFS): Uses pre-engineered modular designs to compress delivery schedules, targeting midstream and power customers with repeated standard configurations.
Petronash: Leverages regional fabrication and upstream relationships to win Middle East skid packaging awards tied to national oil company programs.
Seko SpA: Compresses cost in compact dosing with proportional controllers, keeping pressure on tender pricing in municipal water segments.
AES Arabia Ltd: Localizes water and wastewater dosing integration in the GCC, where import lead time and site service access decide awards.
Carotek Inc and Intech Process Automation Inc: Occupy the integration layer, specifying competitor hardware into control architectures where SCADA and dosing logic dominate the value proposition.
Strategic Milestones & Recent Developments in Chemical Injection Skids Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Apr 2022
SPX FLOW Inc
M&A: take-private by Lone Star Funds at approx. USD 3.8 billion
Removed a listed competitor from public markets and redirected portfolio toward process equipment
Aug 2023
IDEX Corporation
M&A: bolt-on acquisition of Muon Group
Added precision micro-component capacity adjacent to metering pump platforms
2023
Proserv Group Inc
Contract awards and service-centre expansion
Deepened brownfield skid service position in upstream oil and gas
2023-2024
Seko SpA
Product launch: digital proportional dosing controllers
Displaced analogue dosing hardware in municipal water tenders
Extended reach into refinery and gas-processing duty above 400 bar
2022: The SPX FLOW take-private reset competitive benchmarks for public-market valuation of fluid handling assets, and it accelerated divestment of non-core product lines.
2023: IDEX's Muon Group acquisition reinforced a pattern of buying precision component capacity rather than skid fabrication capacity, keeping capital away from low-margin frame assembly.
2023-2024: The migration to digital dosing controllers moved differentiation toward firmware, calibration algorithms, and audit logging, shifting value away from mechanical assembly.
2024: Modular skid standardization shortened delivery windows, a direct competitive response to the 16-30 week lead times that frustrate project schedules.
Fabrication-side capacity remains a constraint. Consolidation in the Stainless Steel Fabrication Market has lengthened lead times for certified manifold assemblies to 16-20 weeks, and skid integrators report that alloy availability, not order intake, is the binding limit on revenue growth in North America and Europe.
Regional Market Analysis & Growth Corridors for Chemical Injection Skids Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (USD million)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
7.1
512
Refining, chemical, and power capacity additions; municipal water investment
Medium-High
Middle East & Africa
6.3
176
Upstream production chemicals and desalination dosing
Medium
South America
5.4
112
Deepwater and heavy-oil corrosion inhibition
Medium
North America
4.6
448
Midstream retrofit and produced-water reuse
High
Europe
4.2
352
Replacement demand and emissions compliance
Very High
Asia-Pacific is the fastest-growing corridor at 7.1% CAGR, adding about USD 0.45 billion of incremental annual revenue between 2024 and 2033. China and India account for the majority of that gain through refinery and petrochemical expansion, while ASEAN water utilities drive standardization of compact dosing skids.
Middle East & Africa grows at 6.3% CAGR on the back of upstream production chemicals and desalination antiscalant dosing. GCC projects favor locally packaged skids to reduce import lead time, which supports regional fabricators over global OEMs.
North America at 4.6% CAGR is replacement-driven, but produced-water reuse in shale basins adds a new dosing duty where volumes are less predictable than in conventional refining.
Europe at 4.2% CAGR is the most mature and the most regulated market, where REACH substance restrictions and PED conformity assessment lengthen every new product introduction.
South America at 5.4% CAGR is concentrated in Brazilian deepwater and heavy-oil service, where scale and wax inhibition chemistry requires high-pressure dosing capability rather than compact water-duty packages.
The practical implication is that growth capital should follow certification capability, not geography alone. Suppliers able to hold API 675 performance documentation, ATEX and IECEx certification, and NSF/ANSI 60 listing simultaneously can bid across all five regions, while single-market fabricators remain exposed to the 4-5% growth band in developed economies.
Technology Innovation & R&D Trajectory in Chemical Injection Skids Market
Technology
Adoption Horizon
Disruption Vector
Incumbent Risk
Closed-loop digital dosing control with flow feedback
2025-2028
Moves value from hardware to control software and analytics
Medium: favors OEMs with software capability
Diaphragm leak detection with IoT telemetry
2025-2029
Enables condition-based maintenance and service contracts
Medium
Additive-manufactured manifolds and exotic-alloy pump heads
2027-2032
Cuts lead time and enables low-volume exotic geometries
Low-Medium
Solar-powered low-flow skids for remote wellheads
2025-2030
Removes power infrastructure cost from project economics
Low
Closed-loop control is the most commercially advanced shift. Dosing accuracy claims that once rested on pump stroke calibration are now validated by inline flow measurement, which means the Automated Dosing Systems Market competes directly with mechanical metering for specification space. OEMs that control both the pump head and the controller retain margin; those that supply only the pump become component vendors to a software-defined package.
Telemetry adoption follows the same logic. Remote monitoring of diaphragm integrity and stroke count converts a capital sale into a maintenance annuity, and vendors report that service attach rates above 40% materially improve account economics. This dynamic disproportionately benefits established pump platforms with installed bases, because retrofitting telemetry to an existing skid is cheaper than replacing it.
Additive manufacturing remains a medium-term threat to conventional manifold supply. Printing corrosion-resistant manifold bodies could compress lead times from 16-20 weeks to under 6 weeks for exotic alloys, undermining the scheduling advantage that vertically integrated fabricators currently hold. Patent activity in dosing control algorithms and diaphragm sensing has risen, and R&D budgets among the leading pump OEMs are being redirected from hydraulic efficiency toward electronics and diagnostics.
Regulatory & Policy Landscape: Chemical Injection Skids Market
Framework
Geography
Scope
Compliance Impact
API 675 and API 674
Global oil and gas
Controlled-volume and reciprocating pump design and testing
Sets dosing accuracy specifications; effectively mandatory in downstream tenders
PED 2014/68/EU and ATEX 2014/34/EU
European Union
Pressure equipment and hazardous-area equipment
Adds 8-12% to unit cost; CE marking required for placement
IECEx, NEC, and UL 508A
Global and North America
Hazardous-area electrical assemblies and industrial control panels
Drives demand for SIL-rated control hardware and validation documentation
Regulatory pressure acts as a demand accelerator rather than a brake in most regions. API 675 remains the reference specification for controlled-volume dosing accuracy, and downstream and midstream operators increasingly require documented performance curves at acceptance, which raises the technical bar for low-cost fabricators. In hazardous areas, ATEX and IECEx certification is a fixed cost that favors suppliers with existing certified platforms and penalizes single-project entrants.
European substance regulation is the most restrictive variable. REACH restrictions on specific biocides and coagulant chemistries force operators to re-qualify wetted materials and dosing parameters, and PED conformity assessment adds both documentation and third-party inspection cost. In the United States, the combination of EPA discharge limits and NSF/ANSI 60 and 61 listing requirements means municipal awards effectively exclude uncertified packages.
Asia-Pacific regulation is tightening rather than converging. China's evolving discharge standards and India's water quality mandates are raising the technical specification floor in markets that previously accepted manual dosing, which supports premium skid demand. The policy takeaway for suppliers is that certification breadth now determines addressable market size: a package lacking ATEX, PED, or NSF listing is structurally excluded from roughly half of global tender volume.
Methodology
Primary Research
Research split: 70-80% of total project effort is primary research; 20-30% is secondary research and benchmarking. This balance is maintained because dosing accuracy, certification scope, and service attach rates are not fully disclosed in public filings.
Company types surveyed (primary participants): modular chemical injection skid fabricators and package integrators; controlled-volume API 675 metering pump OEMs; instrumentation and PLC/SCADA automation integrators for dosing control loops; EPC contractors serving oil and gas, refining, and power generation; and water utility chemical dosing operators plus municipal procurement teams.
Stakeholder job titles interviewed: Director of Rotating & Metering Equipment Engineering; Upstream Production Chemicals Category Manager; Refinery Process Automation & Instrumentation Lead; Municipal Water Treatment Operations Superintendent.
Industry associations and regulatory bodies referenced: American Petroleum Institute (API), Hydraulic Institute (HI), Europump (Europump), and the International Society of Automation (ISA).
Interview structure: 45-70 minute semi-structured calls covering installed base, replacement cycles, certification cost, and vendor qualification criteria, supplemented by written questionnaires for procurement respondents.
Secondary Research & Industry Benchmarking
Financial and transaction data are sourced from Bloomberg, Factiva, Hoovers, and PitchBook for M&A activity, take-private valuations, and capital deployment patterns among pump and skid suppliers.
Government and regulatory sources include the U.S. Energy Information Administration (EIA) for refinery, power, and upstream capacity data, and the U.S. Environmental Protection Agency (EPA) for discharge and drinking-water treatment requirements.
Trade association publications, customs statistics (HS 8413 and 8481), and technical standards documents (API 675, API 674, PED 2014/68/EU, IEC 61511) are used for specification and compliance benchmarking. Market research websites are not used as sources.
Every report is updated to the date of purchase, with regional capacity, tariff, and certification data refreshed against the latest available releases.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously. The top-down model allocates global chemical injection skid revenue across five end-user industries and five regions using installed-base economics and project award data.
The bottom-up model multiplies specific quantitative metrics: installed base of API 675 controlled-volume metering pumps per refinery, chemical plant, and offshore platform; average chemical injection rate in litres per hour and number of injection points per well pad or process unit; average skid replacement and retrofit cycle of 10-12 years across upstream, midstream, and power assets; and municipal water utility chemical dosing spend per million gallons treated per day.
Segment revenue is then reconciled against reported OEM and integrator revenue, project award values, and import-export volumes to produce a single validated market size for 2024 and a forecast to 2033.
Multi-level data triangulation validates the estimate across three independent planes: supplier revenue, end-user installed base and replacement behaviour, and trade flow statistics.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level: 85-90%, reflecting the project-based, negotiated nature of skid pricing and the limited public disclosure of dosing equipment revenue by segment.
Cross-validation steps include comparison of interview-derived growth rates against customs import series, and reconciliation of regional estimates against announced EPC project schedules.
Outlier responses are re-tested with a second respondent in the same company type before inclusion, and any variance above 15% between primary and secondary estimates triggers a targeted follow-up round.
Final figures are reviewed by a senior analyst for internal consistency, with all CAGR values and segment shares confirmed to sum correctly across regions and end-user industries before publication.
Chemical Injection Skids Market Segmentation
1. End-user Industry
1.1. Petrochemicals
1.2. Chemicals
1.3. Energy & Power
1.4. Oil & Gas
1.5. Water Treatment
Chemical Injection Skids Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Chemical Injection Skids Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.8% from 2020-2034
Segmentation
By End-user Industry
Petrochemicals
Chemicals
Energy & Power
Oil & Gas
Water Treatment
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End-user Industry
5.1.1. Petrochemicals
5.1.2. Chemicals
5.1.3. Energy & Power
5.1.4. Oil & Gas
5.1.5. Water Treatment
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End-user Industry
6.1.1. Petrochemicals
6.1.2. Chemicals
6.1.3. Energy & Power
6.1.4. Oil & Gas
6.1.5. Water Treatment
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End-user Industry
7.1.1. Petrochemicals
7.1.2. Chemicals
7.1.3. Energy & Power
7.1.4. Oil & Gas
7.1.5. Water Treatment
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End-user Industry
8.1.1. Petrochemicals
8.1.2. Chemicals
8.1.3. Energy & Power
8.1.4. Oil & Gas
8.1.5. Water Treatment
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End-user Industry
9.1.1. Petrochemicals
9.1.2. Chemicals
9.1.3. Energy & Power
9.1.4. Oil & Gas
9.1.5. Water Treatment
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End-user Industry
10.1.1. Petrochemicals
10.1.2. Chemicals
10.1.3. Energy & Power
10.1.4. Oil & Gas
10.1.5. Water Treatment
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AES Arabia Ltd
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Carotek Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Casainox Flow Solutions
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Degremont Technologies Ltd
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. IDEX Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. ITC SL
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Intech Process Automation Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Integrated Flow Solutions LLC (IFS)
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Lewa GmbH
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Milton Roy Europe
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Petrak Industries Inc
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Petronash
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Proserv Group Inc
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Seko SpA
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. SPX FLOW Inc
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Swelore Engineering*List Not Exhaustive
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Chemical Injection Skids Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Chemical Injection Skids Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 3: North America Chemical Injection Skids Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 4: North America Chemical Injection Skids Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Chemical Injection Skids Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Chemical Injection Skids Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 7: South America Chemical Injection Skids Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 8: South America Chemical Injection Skids Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Chemical Injection Skids Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Chemical Injection Skids Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 11: Europe Chemical Injection Skids Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 12: Europe Chemical Injection Skids Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Chemical Injection Skids Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Chemical Injection Skids Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 15: Middle East & Africa Chemical Injection Skids Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 16: Middle East & Africa Chemical Injection Skids Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Chemical Injection Skids Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Chemical Injection Skids Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 19: Asia Pacific Chemical Injection Skids Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 20: Asia Pacific Chemical Injection Skids Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Chemical Injection Skids Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 2: Chemical Injection Skids Market Revenue billion Forecast, by Region 2020 & 2034
Table 3: North America Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 4: North America Chemical Injection Skids Market Revenue billion Forecast, by Country 2020 & 2034
Table 5: United States Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 6: Canada Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 7: Mexico Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 8: South America Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 9: South America Chemical Injection Skids Market Revenue billion Forecast, by Country 2020 & 2034
Table 10: Brazil Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Argentina Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Europe Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 14: Europe Chemical Injection Skids Market Revenue billion Forecast, by Country 2020 & 2034
Table 15: United Kingdom Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Germany Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: France Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Italy Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Spain Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Russia Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Benelux Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Nordics Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 25: Middle East & Africa Chemical Injection Skids Market Revenue billion Forecast, by Country 2020 & 2034
Table 26: Turkey Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Israel Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: GCC Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: North Africa Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: South Africa Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Chemical Injection Skids Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 33: Asia Pacific Chemical Injection Skids Market Revenue billion Forecast, by Country 2020 & 2034
Table 34: China Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: India Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Japan Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: South Korea Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: ASEAN Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Oceania Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific Chemical Injection Skids Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Quality Assurance Framework
Comprehensive validation mechanisms ensuring market intelligence accuracy, reliability, and adherence to international standards.
Multi-source Verification
500+ data sources cross-validated
Expert Review
200+ industry specialists validation
Standards Compliance
NAICS, SIC, ISIC, TRBC standards
Real-Time Monitoring
Continuous market tracking updates
Frequently Asked Questions
1. How much venture capital and private equity money is moving into chemical injection skid technology?
Disclosed venture rounds in the dosing and metering equipment space are modest, typically USD 5-40 million, and concentrate on digital dosing controllers, telemetry, and remote-monitoring software rather than mechanical hardware. The larger capital flows are strategic: SPX FLOW Inc. was taken private by Lone Star Funds in a transaction valued near USD 3.8 billion in 2022, and IDEX Corporation has continued bolt-on acquisitions in adjacent precision components. Industrial growth equity stays selective because skid fabrication is project-based with limited recurring revenue.
2. What raw materials and supply chain risks affect chemical injection skid production?
Skid frames, manifolds, and pump heads rely on 316L and duplex stainless steel, Hastelloy C-276 for aggressive service, and PTFE or PVDF diaphragms; these materials represent roughly 22-30% of skid bill-of-materials cost. Nickel and molybdenum price swings feed directly into alloy plate pricing, while lead times for specialty alloy pump heads and certified control panels run 16-30 weeks. Single-source qualification of API 675 pump heads is the most frequently reported supply bottleneck among integrators.
3. What is the chemical injection skids market size and CAGR through 2033?
The market was valued at USD 1.60 billion in 2024 and is projected to reach USD 2.66 billion by 2033, expanding at a 5.8% CAGR. Asia-Pacific accounts for roughly 32% of global revenue, about USD 512 million, and is forecast to grow at 7.1%, the fastest of the five regions. Oil and gas remains the largest end-user segment at approximately 34% share.
4. Which regulations and standards govern chemical injection skid design and installation?
API 675 and API 674 define controlled-volume and reciprocating pump performance, and downstream tenders routinely make API 675 dosing accuracy a mandatory specification. In hazardous areas, ATEX 2014/34/EU, IECEx, and UL 508A govern electrical assemblies, while PED 2014/68/EU covers pressure-containing skid components in the EU. Municipal water projects add NSF/ANSI 60 and 61 certification, and combined compliance typically adds 8-12% to unit cost.
5. How do export-import flows shape the chemical injection skids trade?
Complete skid packages are exported mainly from Germany, Italy, the United States, and increasingly China and India, classified under HS heading 8413 for pumps for liquids and 8481 for valves. US Section 301 tariffs on Chinese pump and valve imports, at 25% on many lines, have pushed North American buyers toward domestic and European fabrication. Middle East and Southeast Asian demand is largely met through project-based imports tied to EPC contracts.
6. What recent M&A activity and product launches have shaped the chemical injection skid market?
SPX FLOW Inc.'s take-private by Lone Star Funds in 2022, valued near USD 3.8 billion, and IDEX Corporation's 2023 acquisition of Muon Group are the most consequential structural moves among pump and skid suppliers. Product activity has centered on digital dosing controllers, pre-engineered modular skid packages, and high-pressure diaphragm metering pumps rated above 400 bar. Vendors are also bundling telemetry and condition-based maintenance to convert one-off skid sales into service contracts.