Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Thickeners Market Forecast: 5.4% CAGR to 2033
Thickeners Market
Thickeners Market Forecast: 5.4% CAGR to 2033
Thickeners Market by Type (Inorganic Thickener, Cellulose Ether, Polysaccharides, Polypeptides, Synthetic Polymer, Natural Polymer, Others), by Application (Paints and Coatings, Textile, Paper and Pulp, Detergent, Food and Beverages, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 300
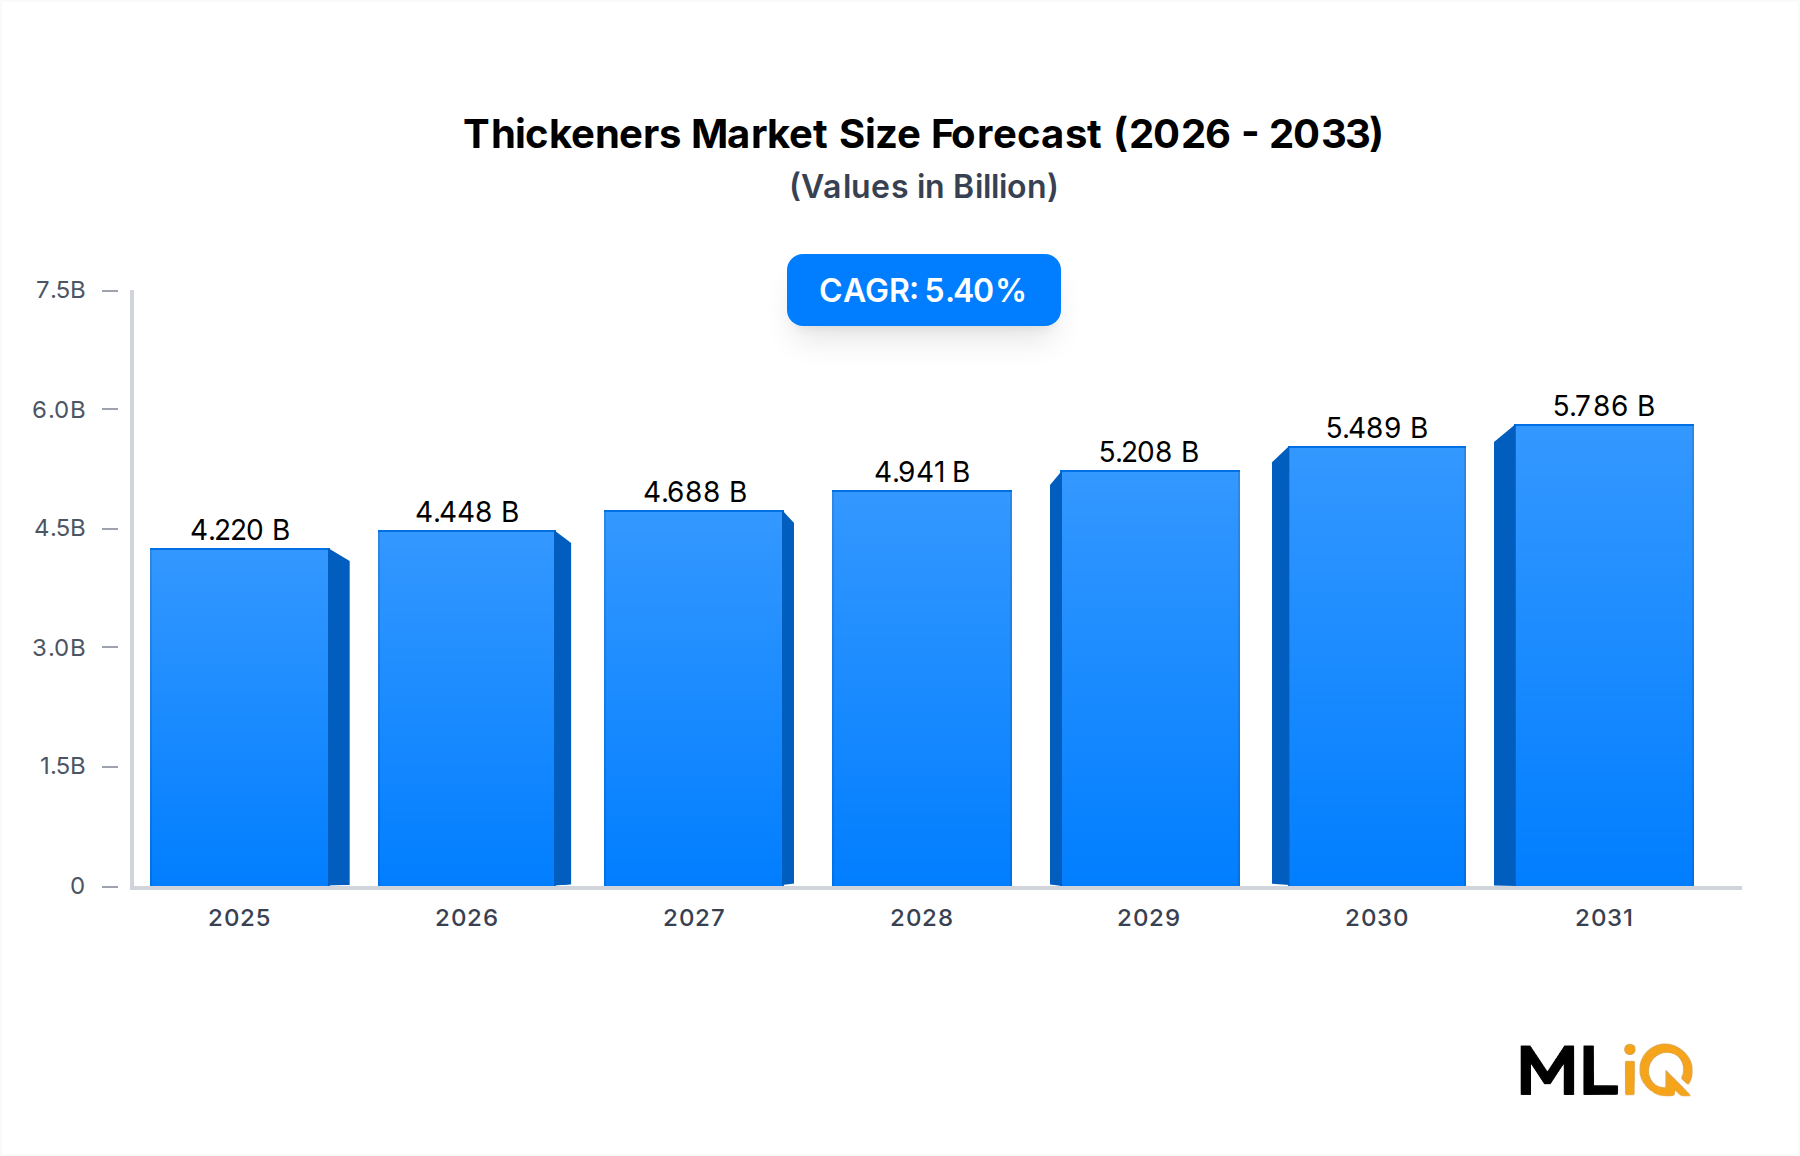
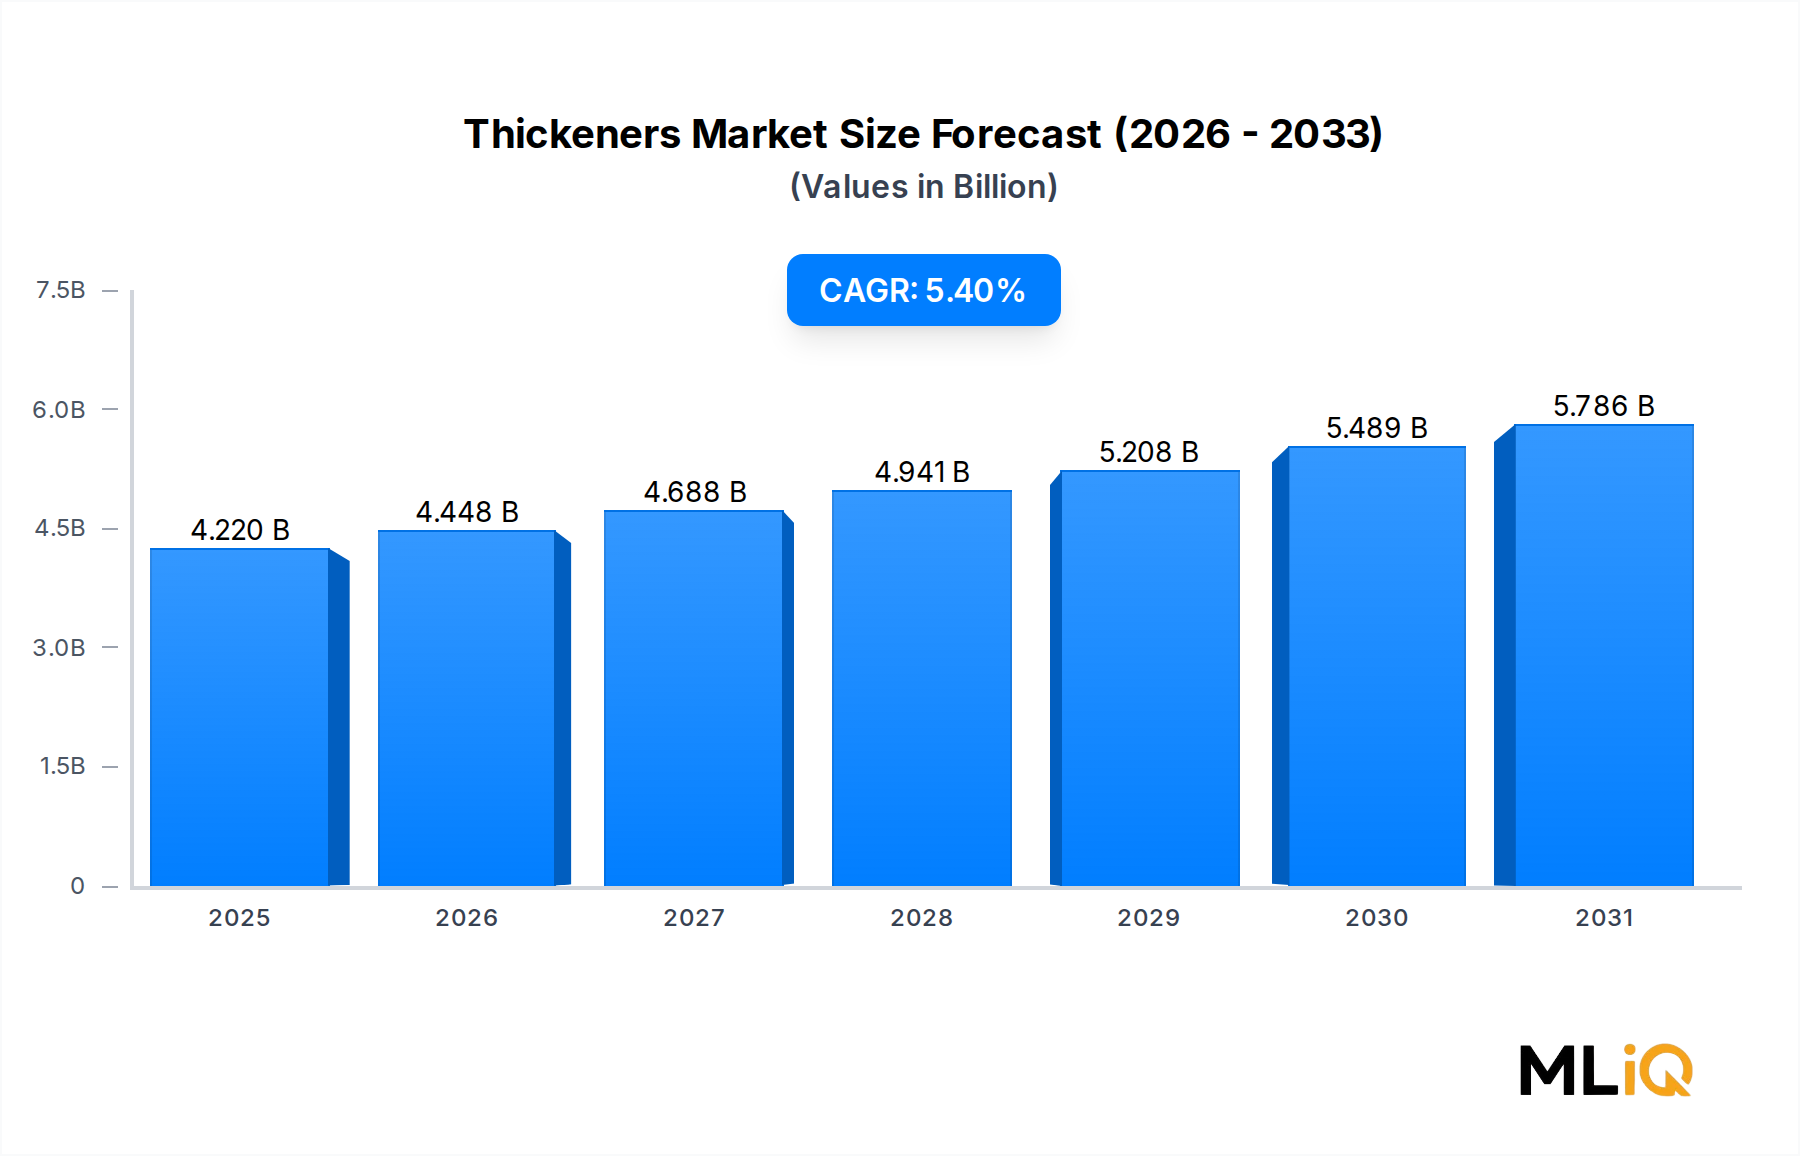
The global value of the Thickeners Market is USD 4.22 billion in 2025 and is forecast to reach USD 6.42 billion by 2033, growing at a 5.4% CAGR. Demand is concentrated in the Paints and Coatings Market, where waterborne formulations require cellulose ethers, synthetic acrylics, and associative rheology additives. The Food and Beverages Market adds stable volume for hydrocolloids and modified starches, while textile and paper applications absorb lower-grade grades. Cellulose Ether Market volume leads all product classes, supported by construction activity and low-VOC coating mandates. Synthetic Polymer Market growth is faster, at roughly 6.2% CAGR, because alkali-swellable and hydrophobically modified emulsions replace solvent-borne systems. Natural Polymer Market demand remains regionally fragmented due to raw material seasonality and higher logistics costs.
Thickeners Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.220 B
2025
4.448 B
2026
4.688 B
2027
4.941 B
2028
5.208 B
2029
5.489 B
2030
5.786 B
2031
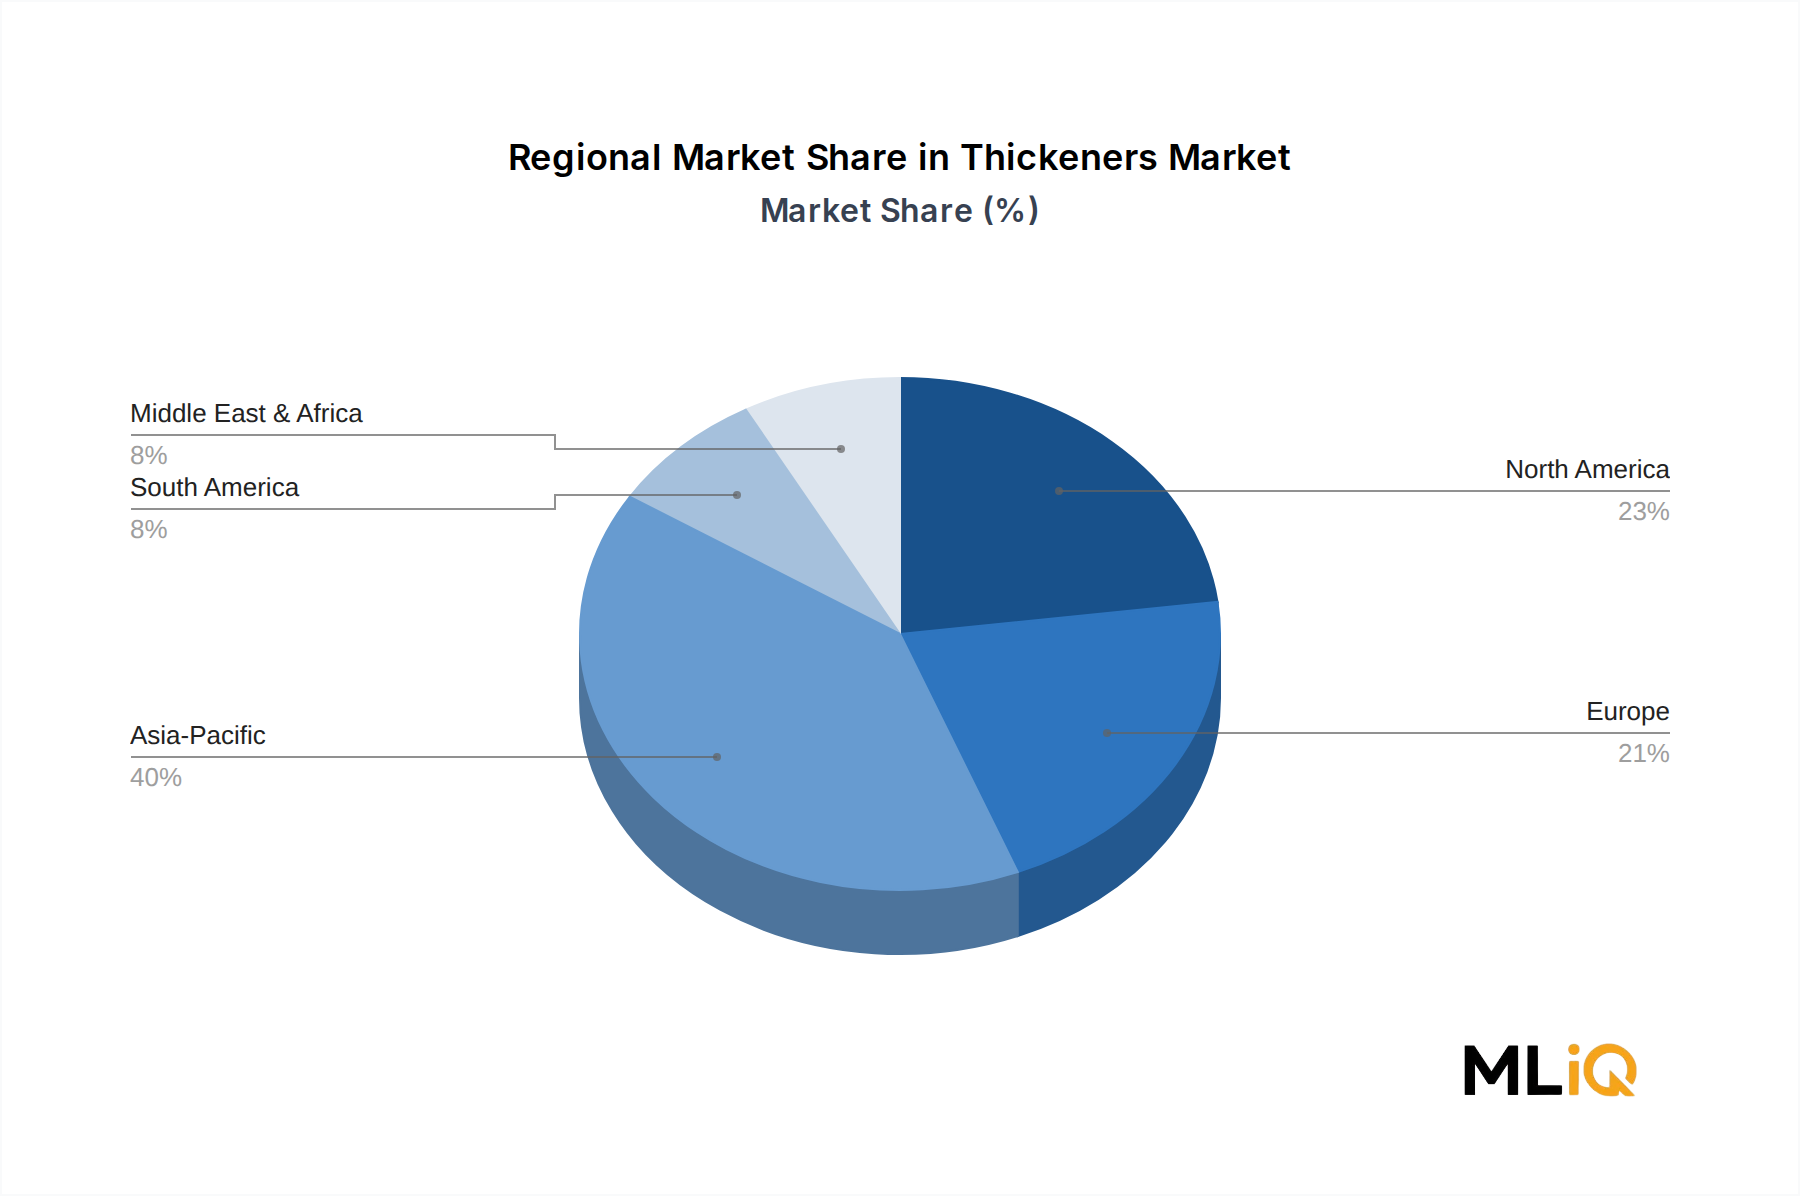
Asia-Pacific accounts for 40% of global value, with China and India as the largest volume centers.
North America holds 23% share, driven by premium coatings, food processing, and pharmaceutical excipients.
Europe holds 21% share, but REACH and EFSA compliance raise formulation costs.
The Rheology Modifiers Market overlaps directly with thickeners in coatings, inks, and personal care.
Cellulose Ether Market pricing faces pressure from wood pulp and cotton linter costs, while synthetic grades track propylene and acrylic acid.
Specialty Chemicals Market consolidation has narrowed the supplier base, raising qualification barriers for new entrants.
Strategic focus is shifting toward bio-based and low-shear thickeners. Suppliers that can offer both natural and synthetic portfolios are better positioned to serve formulators reducing volatile organic compounds. Volume growth is steady, but value growth depends on price recovery in Europe and North America after 2025 inventory destocking. The largest margin pool remains in high-purity cellulose ethers for food, pharmaceutical, and premium architectural coatings.
Segment Deep-Dive: Cellulose Ether Dominance in Thickeners Market
Segment Analysis Matrix
CAGR (%)
Market Share (%)
Key Demand Driver
Cellulose Ether
5.8
38
Waterborne Paints and Coatings Market
Synthetic Polymer
6.2
24
Low-VOC detergents and industrial coatings
Polysaccharides
5.1
18
Food and Beverages Market texture and stability
The Cellulose Ether Market is the largest revenue segment, with 38% share and an estimated USD 1.60 billion in 2025 revenue. Hydroxyethyl cellulose and hydroxypropyl methylcellulose dominate architectural coatings, while methylcellulose and carboxymethyl cellulose serve food and pharmaceutical uses. The segment benefits from waterborne Paints and Coatings Market expansion, especially in Asia-Pacific where construction completions and infrastructure spending remain high. Margin pressure comes from pulp and cotton linter prices, energy costs, and regulatory limits on residual solvents. Producers with integrated cellulose sourcing and multi-site production can protect gross margins better than import-dependent blenders.
Sub-Segment Dynamics
Hydroxyethyl cellulose is the largest cellulose ether sub-type, used in interior and exterior waterborne coatings.
Carboxymethyl cellulose captures food, detergent, and oilfield applications, but faces substitution by synthetic acrylics in some detergent formats.
Methylcellulose and HPMC carry premium pricing in pharmaceutical and food applications; certification costs limit supplier counts.
Polysaccharides Market includes xanthan gum, pectin, and guar derivatives; volume growth is tied to clean-label Food and Beverages Market demand.
Synthetic Polymer Market is the fastest-growing class, led by HEUR, HASE, and associative acrylic thickeners that deliver shear-thinning without flocculation.
Natural Polymer Market retains cost-sensitive textile and paper customers, but supply variability from guar and starch crops creates price spikes.
Margin and Competitive Pressure
The Cellulose Ether Market faces a two-speed margin profile. Food-grade and pharmaceutical-grade ethers command 20-30% gross margins when producers hold certifications and long-term supply agreements. Technical-grade ethers for paints and construction trade at lower margins, often 12-18%, because formulators can dual-source across regions. Synthetic Polymer Market suppliers compete on formulation patents and service, not just price, which supports higher margins in premium coatings. Polysaccharides Market participants face weather-driven raw material risk, and natural polymer suppliers absorb freight costs when regional harvests fail. The main strategic risk is overcapacity in Chinese cellulose ether production, which can depress export prices and pressure European and North American producers.
Primary Market Drivers & Growth Restraints in Thickeners Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Waterborne Paints and Coatings Market expansion
High
Short term
Driver
Food and Beverages Market clean-label hydrocolloid demand
High
Long term
Driver
Synthetic Polymer Market shift to low-VOC rheology modifiers
Medium
Short term
Restraint
Petrochemical Feedstock Market volatility
High
Short term
Restraint
EU REACH and EFSA compliance costs
Medium
Long term
Restraint
Natural Polymer Market raw material variability
Medium
Short term
Regulatory push for low-VOC coatings is the strongest demand catalyst. Waterborne architectural coatings use 0.3-1.5% thickener by weight, and every liter of solvent-based coating converted to waterborne creates incremental cellulose ether or synthetic associative demand. The Paints and Coatings Market alone consumes an estimated 42% of global thickener volume, making construction cycles the primary swing factor. The Food and Beverages Market is a second engine: hydrocolloids improve texture, suspension, and shelf stability in plant-based beverages, sauces, and dairy alternatives. Clean-label reformulation favors xanthan, pectin, and cellulose gum over modified starches in some regions, benefiting the Polysaccharides Market.
Quantitative Bottlenecks
Petrochemical Feedstock Market volatility affects acrylic acid, ethylene oxide, and propylene derivatives used in Synthetic Polymer Market products. A 10% acrylic acid price swing can alter synthetic thickener production costs by 6-8%.
Energy-intensive drying in cellulose ether manufacturing exposes European producers to natural gas price spikes; energy can represent 15-20% of conversion cost.
REACH registration and EFSA re-evaluation raise compliance spending. A single food additive re-evaluation can cost a supplier EUR 250,000-500,000 in dossier preparation.
Logistics costs for natural gums from West Africa, India, and South America can add 8-12% to delivered cost during container shortages.
Substitution risk is moderate: synthetic associative thickeners can replace cellulose ethers in some coatings, but food and pharmaceutical applications remain formulation-specific.
Restraints are not demand-limiting in aggregate, but they reshape supplier economics. The highest-risk restraint is raw material price volatility in the Petrochemical Feedstock Market, because synthetic thickeners compete directly with cellulose ethers on cost-in-use. Compliance costs in Europe favor large incumbents with dedicated regulatory teams. Natural polymer suppliers face the opposite problem: low barriers to production but high variability in quality and supply.
BASF SE: Maintains a broad portfolio across Cellulose Ether Market and Synthetic Polymer Market products; scale supports regulatory compliance and global supply.
Dow Inc.: Uses cellulosic and acrylic chemistries to serve Paints and Coatings Market customers; integration into waterborne systems is a core advantage.
CP Kelco U.S., Inc.: Strong in Polysaccharides Market for Food and Beverages Market applications, including xanthan and pectin.
Ashland Inc: Focuses on pharmaceutical and food-grade cellulose ethers; certification depth creates switching costs.
Elementis plc: Competes in Rheology Modifiers Market with hectorite and associative thickeners for premium coatings.
DuPont: Leverages biopolymer and cellulosic expertise in food and industrial applications; portfolio fits clean-label trends.
The Lubrizol Corporation: Supplies rheology modifiers and dispersants to coatings and industrial formulators; service and formulation support differentiate.
PPG Industries, Inc.: Vertically integrated in coatings, giving it captive demand for thickener technologies but limited merchant sales.
Henkel Corporation: Uses thickener systems in adhesives and consumer products; demand is tied to industrial and home care cycles.
Akzo Nobel N.V: Paints integration creates demand for thickeners, though merchant additive sales are not core.
Competitive positioning depends on application-specific qualification. Food and pharmaceutical grades require FDA, EFSA, and pharmacopeia compliance, which narrows the field to established producers. In coatings, suppliers compete on shear rheology, leveling, and spatter resistance. The Synthetic Polymer Market is more innovation-driven, with patents around associative monomers and hydrophobic modification. Natural Polymer Market participants compete on price and supply reliability, not formulation patents.
Strategic Milestones & Recent Developments in Thickeners Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2025
BASF SE
Capacity expansion
Medium
2024
CP Kelco U.S., Inc.
Ownership transition
High
2024
Ashland Inc
Portfolio divestiture
Low
2023
Elementis plc
Product launch
Medium
2022
DuPont
Product launch
Medium
2025: BASF SE expanded cellulose ether and rheology modifier capacity to serve waterborne Paints and Coatings Market demand in Asia and Europe. The move reinforces its position in the Cellulose Ether Market.
2024: CP Kelco U.S., Inc. underwent an ownership transition under J.M. Huber, strengthening integration in Polysaccharides Market and Food and Beverages Market supply.
2024: Ashland Inc divested a non-core adhesives unit, allowing sharper focus on pharmaceutical and food-grade cellulose ethers.
2023: Elementis plc launched a low-shear rheology modifier for high-solids coatings, targeting the Rheology Modifiers Market and reducing formulation viscosity drift.
2022: DuPont introduced a cellulosic thickener for plant-based beverages, supporting clean-label Food and Beverages Market formulation.
These moves point to consolidation around application-specific portfolios. Suppliers are exiting low-margin commodity thickeners and investing in food, pharmaceutical, and premium coating grades. The Synthetic Polymer Market is seeing more launches than capacity additions, because product differentiation matters more than volume. M&A activity is moderate, with strategic buyers seeking regional access and certified production assets.
Regional Market Analysis & Growth Corridors for Thickeners Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Asia-Pacific
6.1
USD 1.69 billion
Paints and Coatings Market and construction
Medium
North America
4.8
USD 0.97 billion
Food and Beverages Market and low-VOC coatings
High
Europe
4.6
USD 0.89 billion
REACH-compliant rheology additives
High
South America
5.2
USD 0.34 billion
Coatings and food processing
Medium
Middle East & Africa
5.5
USD 0.33 billion
Construction and detergents
Low-Medium
Asia-Pacific is the largest and fastest-growing region, with 40% of global value and a 6.1% CAGR. China dominates cellulose ether capacity, while India and Southeast Asia expand Paints and Coatings Market consumption. Regulatory stringency is moderate, but environmental enforcement is rising, pushing formulators toward waterborne systems. Japan and South Korea are mature markets with high-value food and electronics-related thickener demand.
North America holds 23% share and grows at 4.8% CAGR. The Food and Beverages Market is a stable base, particularly for hydrocolloids and modified cellulose in plant-based foods. Low-VOC rules in California and other states support Synthetic Polymer Market demand. The region has high regulatory stringency, with FDA and EPA oversight shaping food and industrial thickener approvals.
Europe holds 21% share and grows at 4.6% CAGR. REACH and EFSA requirements raise compliance costs and slow new entrants, but they also protect incumbent positions. The region is a leader in bio-based thickener R&D, including cellulose derivatives from certified wood pulp and fermentable polysaccharides. South America and the Middle East & Africa together hold 16% share and grow at 5.2% and 5.5% CAGR, respectively, driven by construction, detergents, and local food processing.
Technology Innovation & R&D Trajectory in Thickeners Market
Three innovation tracks are reshaping formulation. First, associative acrylic thickeners in the Synthetic Polymer Market use hydrophobic blocks to build viscosity only when needed, reducing sag and improving leveling in waterborne coatings. Second, enzymatic and fermentation-derived hydrocolloids expand the Natural Polymer Market with consistent molecular weights and lower land-use intensity. Third, nano-cellulose and micro-fibrillated cellulose offer high yield stress at low dosage, but commercial scale-up remains limited by drying energy and dispersibility.
Adoption timelines differ. Associative acrylics are already mainstream in North America and Europe and will gain share in Asia-Pacific as low-VOC rules tighten. Fermentation-derived polysaccharides are commercial in food, but cost remains 2-3x xanthan gum for some grades. Nano-cellulose is at pilot-to-early-commercial stage, with broad adoption unlikely before 2030. R&D spending in Specialty Chemicals Market leaders averages 3-5% of annual revenue, with patent activity concentrated in cellulose ether modification, associative monomers, and bio-based rheology modifiers. Incumbent cellulose ether producers are not displaced quickly because qualification cycles in food and pharma take 12-24 months. However, synthetic alternatives threaten technical-grade cellulose ethers in coatings and detergents, where reformulation costs are lower.
Export, Cross-Border Trade & Tariff Impact on Thickeners Market
Trade flows follow raw material and application demand. China is the largest net exporter of cellulose ethers and synthetic thickeners, sending volume to Asia-Pacific, Europe, and the Americas. Europe and North America export high-value food-grade and pharmaceutical-grade thickeners, while importing technical grades from Asia. India and Southeast Asia are growing exporters of guar gum and xanthan, linking the Polysaccharides Market to agricultural trade. The Petrochemical Feedstock Market determines the cost base for synthetic acrylic thickeners, with propylene and acrylic acid flows concentrated in the Middle East, North America, and Northeast Asia.
Tariff and non-tariff barriers matter. Anti-dumping duties on cellulose ethers in the EU and India have raised landed costs for Chinese material, redirecting some volume to Southeast Asia and the Middle East. REACH registration, FDA food-contact rules, and EFSA approvals act as non-tariff barriers that favor established suppliers. A 5-10% tariff on thickener imports can shift sourcing decisions for formulators with low switching costs, but food and pharmaceutical qualification limits rapid substitution. Cross-border shipment volumes are also sensitive to container freight rates; during peak disruption, freight added 8-12% to delivered natural gum costs. Trade policy risk is highest for commodity grades and lower for certified specialty products.
Thickeners Market Segmentation
1. Type
1.1. Inorganic Thickener
1.2. Cellulose Ether
1.3. Polysaccharides
1.4. Polypeptides
1.5. Synthetic Polymer
1.6. Natural Polymer
1.7. Others
2. Application
2.1. Paints and Coatings
2.2. Textile
2.3. Paper and Pulp
2.4. Detergent
2.5. Food and Beverages
2.6. Others
Thickeners Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Thickeners Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.4% from 2020-2034
Segmentation
By Type
Inorganic Thickener
Cellulose Ether
Polysaccharides
Polypeptides
Synthetic Polymer
Natural Polymer
Others
By Application
Paints and Coatings
Textile
Paper and Pulp
Detergent
Food and Beverages
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Inorganic Thickener
5.1.2. Cellulose Ether
5.1.3. Polysaccharides
5.1.4. Polypeptides
5.1.5. Synthetic Polymer
5.1.6. Natural Polymer
5.1.7. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Paints and Coatings
5.2.2. Textile
5.2.3. Paper and Pulp
5.2.4. Detergent
5.2.5. Food and Beverages
5.2.6. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Inorganic Thickener
6.1.2. Cellulose Ether
6.1.3. Polysaccharides
6.1.4. Polypeptides
6.1.5. Synthetic Polymer
6.1.6. Natural Polymer
6.1.7. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Paints and Coatings
6.2.2. Textile
6.2.3. Paper and Pulp
6.2.4. Detergent
6.2.5. Food and Beverages
6.2.6. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Inorganic Thickener
7.1.2. Cellulose Ether
7.1.3. Polysaccharides
7.1.4. Polypeptides
7.1.5. Synthetic Polymer
7.1.6. Natural Polymer
7.1.7. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Paints and Coatings
7.2.2. Textile
7.2.3. Paper and Pulp
7.2.4. Detergent
7.2.5. Food and Beverages
7.2.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Inorganic Thickener
8.1.2. Cellulose Ether
8.1.3. Polysaccharides
8.1.4. Polypeptides
8.1.5. Synthetic Polymer
8.1.6. Natural Polymer
8.1.7. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Paints and Coatings
8.2.2. Textile
8.2.3. Paper and Pulp
8.2.4. Detergent
8.2.5. Food and Beverages
8.2.6. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Inorganic Thickener
9.1.2. Cellulose Ether
9.1.3. Polysaccharides
9.1.4. Polypeptides
9.1.5. Synthetic Polymer
9.1.6. Natural Polymer
9.1.7. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Paints and Coatings
9.2.2. Textile
9.2.3. Paper and Pulp
9.2.4. Detergent
9.2.5. Food and Beverages
9.2.6. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Inorganic Thickener
10.1.2. Cellulose Ether
10.1.3. Polysaccharides
10.1.4. Polypeptides
10.1.5. Synthetic Polymer
10.1.6. Natural Polymer
10.1.7. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Paints and Coatings
10.2.2. Textile
10.2.3. Paper and Pulp
10.2.4. Detergent
10.2.5. Food and Beverages
10.2.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. PPG Industries
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Elementis plc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Dow Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. CP Kelco U.S.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. DuPont
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Ashland Inc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. The Lubrizol Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. BASF SE
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Henkel Corporation
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Akzo Nobel N.V
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Thickeners Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Thickeners Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Thickeners Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Thickeners Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Thickeners Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Thickeners Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Thickeners Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Thickeners Market Revenue (billion), by Type 2026 & 2034
Figure 9: South America Thickeners Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Thickeners Market Revenue (billion), by Application 2026 & 2034
Figure 11: South America Thickeners Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Thickeners Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Thickeners Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Thickeners Market Revenue (billion), by Type 2026 & 2034
Figure 15: Europe Thickeners Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Thickeners Market Revenue (billion), by Application 2026 & 2034
Figure 17: Europe Thickeners Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Thickeners Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Thickeners Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Thickeners Market Revenue (billion), by Type 2026 & 2034
Figure 21: Middle East & Africa Thickeners Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Thickeners Market Revenue (billion), by Application 2026 & 2034
Figure 23: Middle East & Africa Thickeners Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Thickeners Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Thickeners Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Thickeners Market Revenue (billion), by Type 2026 & 2034
Figure 27: Asia Pacific Thickeners Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Thickeners Market Revenue (billion), by Application 2026 & 2034
Figure 29: Asia Pacific Thickeners Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Thickeners Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Thickeners Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Thickeners Market Revenue billion Forecast, by Type 2020 & 2034
Table 46: Rest of Asia Pacific Thickeners Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total project input, with 20-30% from secondary sources. We interview decision-makers across the thickener value chain to validate volume, pricing, and application-level demand.
Company types interviewed: cellulose ether producers for paints and food grades; synthetic rheology modifier manufacturers for waterborne coatings; natural gum and polysaccharide suppliers for food and industrial uses; paints and coatings formulators; food and beverage ingredient blenders.
Interviews cover qualification cycles, substitution risk, raw material contracts, capacity utilization, and regional pricing. We triangulate responses against shipment data, trade statistics, and formulation benchmarks.
Plant Operations Manager, Cellulose Ether Production
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Cellulose Ether Producers
30%
Synthetic Rheology Modifier Manufacturers
25%
Natural Gum and Polysaccharide Suppliers
20%
Paints and Coatings Formulators
15%
Food and Beverage Ingredient Blenders
10%
Secondary Research & Industry Benchmarking
Secondary research covers 20-30% of inputs and uses Bloomberg, Factiva, Hoovers, and PitchBook for company filings, capital expenditure, M&A, and valuation benchmarking. We also use .gov, .org, and trade association sources, including U.S. FDA, U.S. EPA, and the European Chemical Industry Council (Cefic). No market research websites are used as primary sources.
We benchmark thickener consumption per liter of waterborne coating, per ton of processed food, and per ton of detergent. Historical price series for cellulose ethers, xanthan gum, guar gum, and acrylic acid are indexed to producer price indices and trade databases.
Company-level benchmarking covers capacity, product mix, certification status, and regional sales presence for BASF SE, Dow Inc., CP Kelco U.S., Inc., Ashland Inc, Elementis plc, DuPont, The Lubrizol Corporation, PPG Industries, Inc., Henkel Corporation, and Akzo Nobel N.V.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously. The top-down model starts with global specialty chemical and coatings demand and applies thickener intensity ratios by application. The bottom-up model builds from quantitative metrics: global paints and coatings production volume by region (million liters); average cellulose ether loading per ton of waterborne coating; food and beverage thickener dosage per 1,000 tons of processed product; and average thickener loading rate in detergent formulations.
Multi-level data triangulation validates the base year USD 4.22 billion market and the 5.4% CAGR to 2033. Segment splits are reconciled across Type and Application, with cross-checks against regional capacity, import-export balances, and supplier revenue disclosures.
Regional models use construction completions, food processing output, detergent production, and paper and pulp output. We adjust for product substitution, regulatory bans, and inventory cycles.
All estimates are updated to the date of purchase, with rolling revisions when tariffs, capacity announcements, or regulatory decisions change the demand outlook.
Data Accuracy & Quality Check
The estimated data accuracy level is 85-90%. Confidence intervals narrow for mature applications such as paints and food, and widen for emerging bio-based thickeners and nano-cellulose.
Quality checks include duplicate interviews, cross-source price verification, and sanity tests against parent market growth. Outliers are re-interviewed or flagged with lower confidence.
Every report is updated to the date of purchase. Forecasts are revised when raw material benchmarks, trade policy, or regulatory approvals materially shift.
Final datasets are reviewed by senior analysts for segment consistency, regional sum checks, and unit alignment. Any variance above 5% between top-down and bottom-up results triggers a targeted re-interview.
Frequently Asked Questions
1. How has the Thickeners Market recovered after pandemic disruptions?
The Thickeners Market returned to structural growth after 2023 inventory destocking, with 2025 value estimated at USD 4.22 billion. Recovery is uneven: architectural coatings and food stabilizers normalized faster than textile and paper thickeners, which remain tied to industrial output. Long-term structural shifts favor cellulose ethers and synthetic associative thickeners over commodity natural gums in regulated applications.
2. What are the primary growth drivers for the Thickeners Market?
Waterborne Paints and Coatings Market expansion is the largest catalyst, followed by clean-label Food and Beverages Market demand for hydrocolloids. Construction activity in Asia-Pacific and low-VOC regulations in North America and Europe push formulators toward cellulose ethers and synthetic acrylic rheology modifiers. These drivers support a 5.4% CAGR from 2025 to 2033.
3. Which raw material sourcing factors affect Thickeners Market supply?
Cellulose ether producers depend on wood pulp and cotton linters, while synthetic grades track the Petrochemical Feedstock Market for acrylic acid, ethylene oxide, and propylene derivatives. Natural gum supply is exposed to harvest variability in India, West Africa, and South America, and container freight can add 8-12% to delivered cost during disruptions. Suppliers with multi-region raw material contracts reduce input risk.
4. How do regulations impact the Thickeners Market?
Food-grade thickeners require U.S. FDA and EFSA approvals, and REACH registration applies to European chemical supply. Compliance costs can reach EUR 250,000-500,000 per food additive re-evaluation, narrowing the supplier field to established firms. These rules raise barriers but also protect incumbents in the Cellulose Ether Market and Polysaccharides Market.
5. Who are the main barriers to entry in Thickeners Market?
Barriers include application-specific qualification, regulatory registrations, cellulose ether production scale, and long customer validation cycles of 12-24 months. BASF SE, Dow Inc., and CP Kelco U.S., Inc. hold advantages in certification, formulation know-how, and global supply. New entrants can compete in technical-grade Synthetic Polymer Market niches but face price pressure from Asian capacity.
6. What is the current size and forecast CAGR of the Thickeners Market?
The market is valued at USD 4.22 billion in 2025 and is projected to reach USD 6.42 billion by 2033, expanding at a 5.4% CAGR. Cellulose Ether remains the dominant segment at 38% share, while Paints and Coatings is the largest application. Asia-Pacific accounts for 40% of global value and is the fastest-growing region.