Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
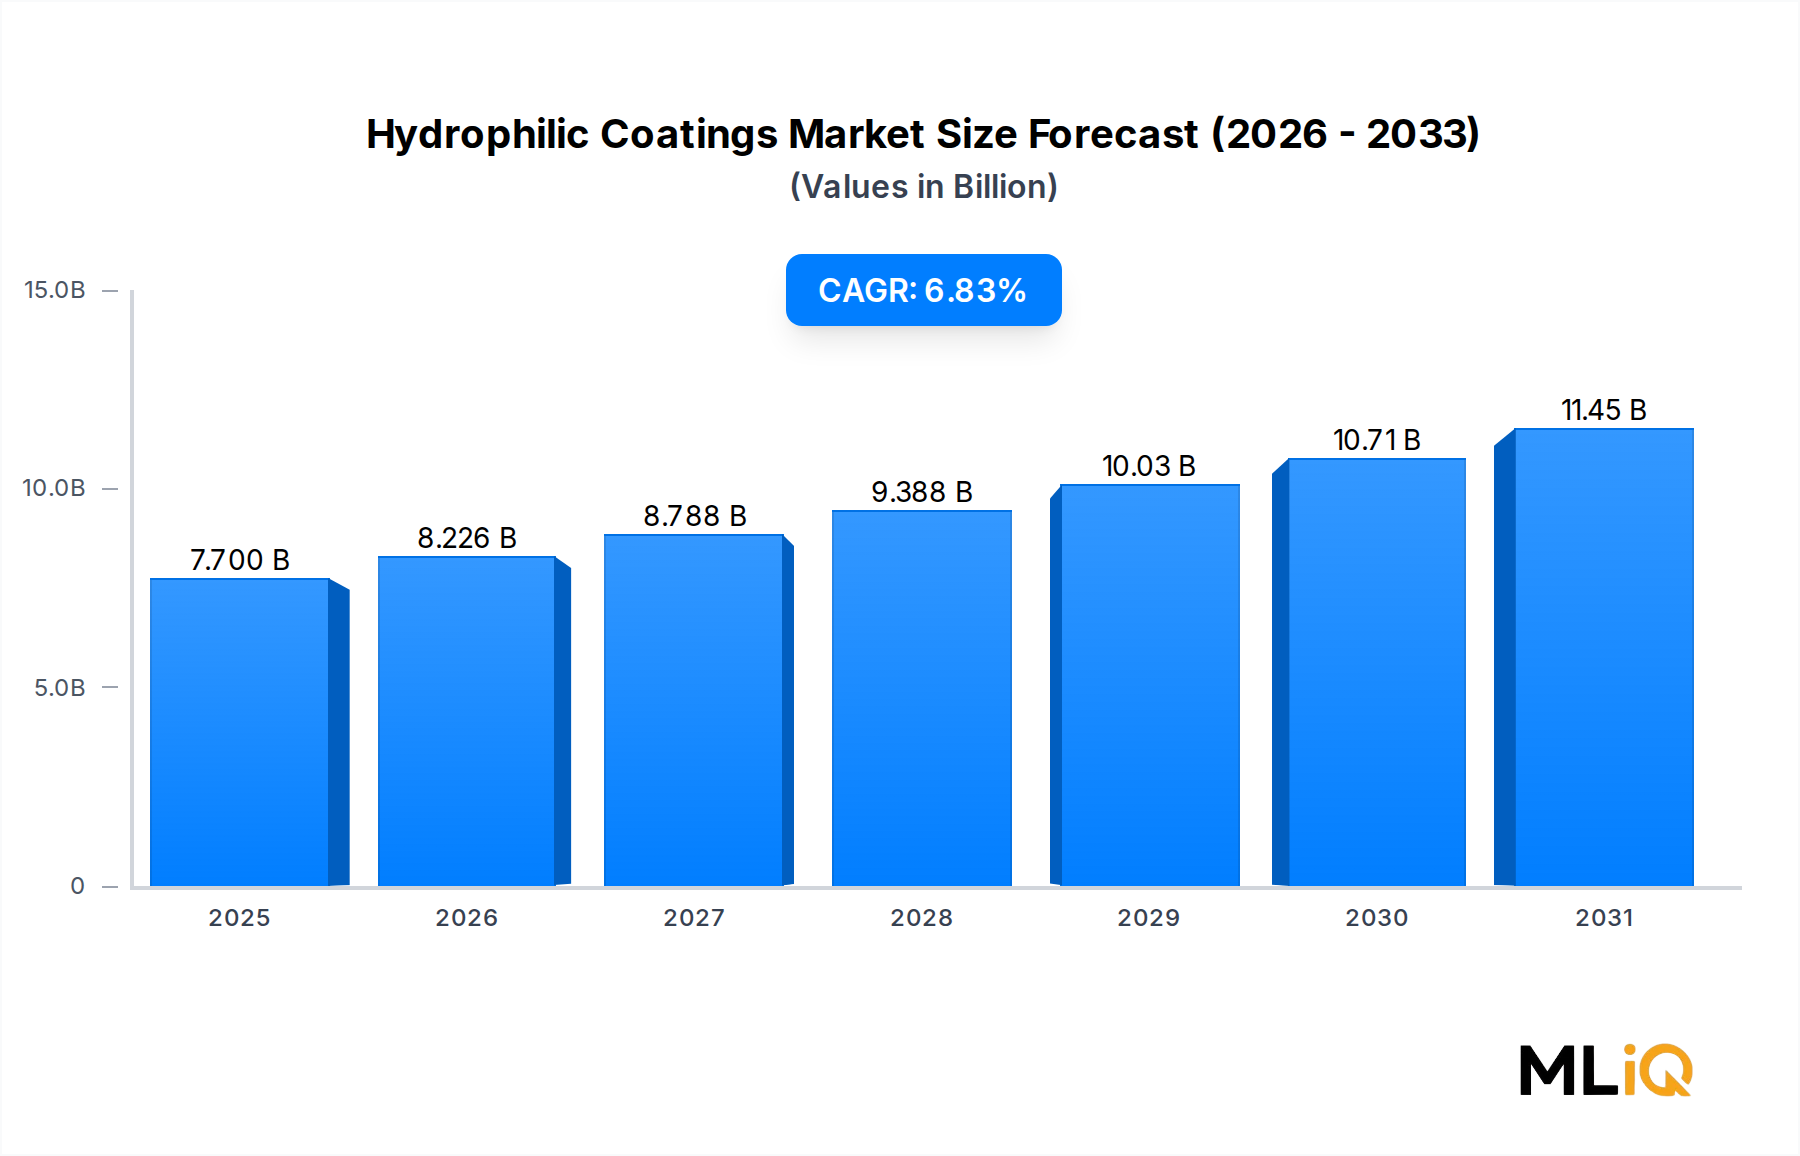
Hydrophilic Coatings Market Size & CAGR 6.83% to 2033
Hydrophilic Coatings Market
Hydrophilic Coatings Market Size & CAGR 6.83% to 2033
Hydrophilic Coatings Market by End-user Industry (Medical, Optics, Automotive, Transportation, Other End-user Industries), by Substrate (Polymer, Glass/Ceramic, Metal, Nanoparticle), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
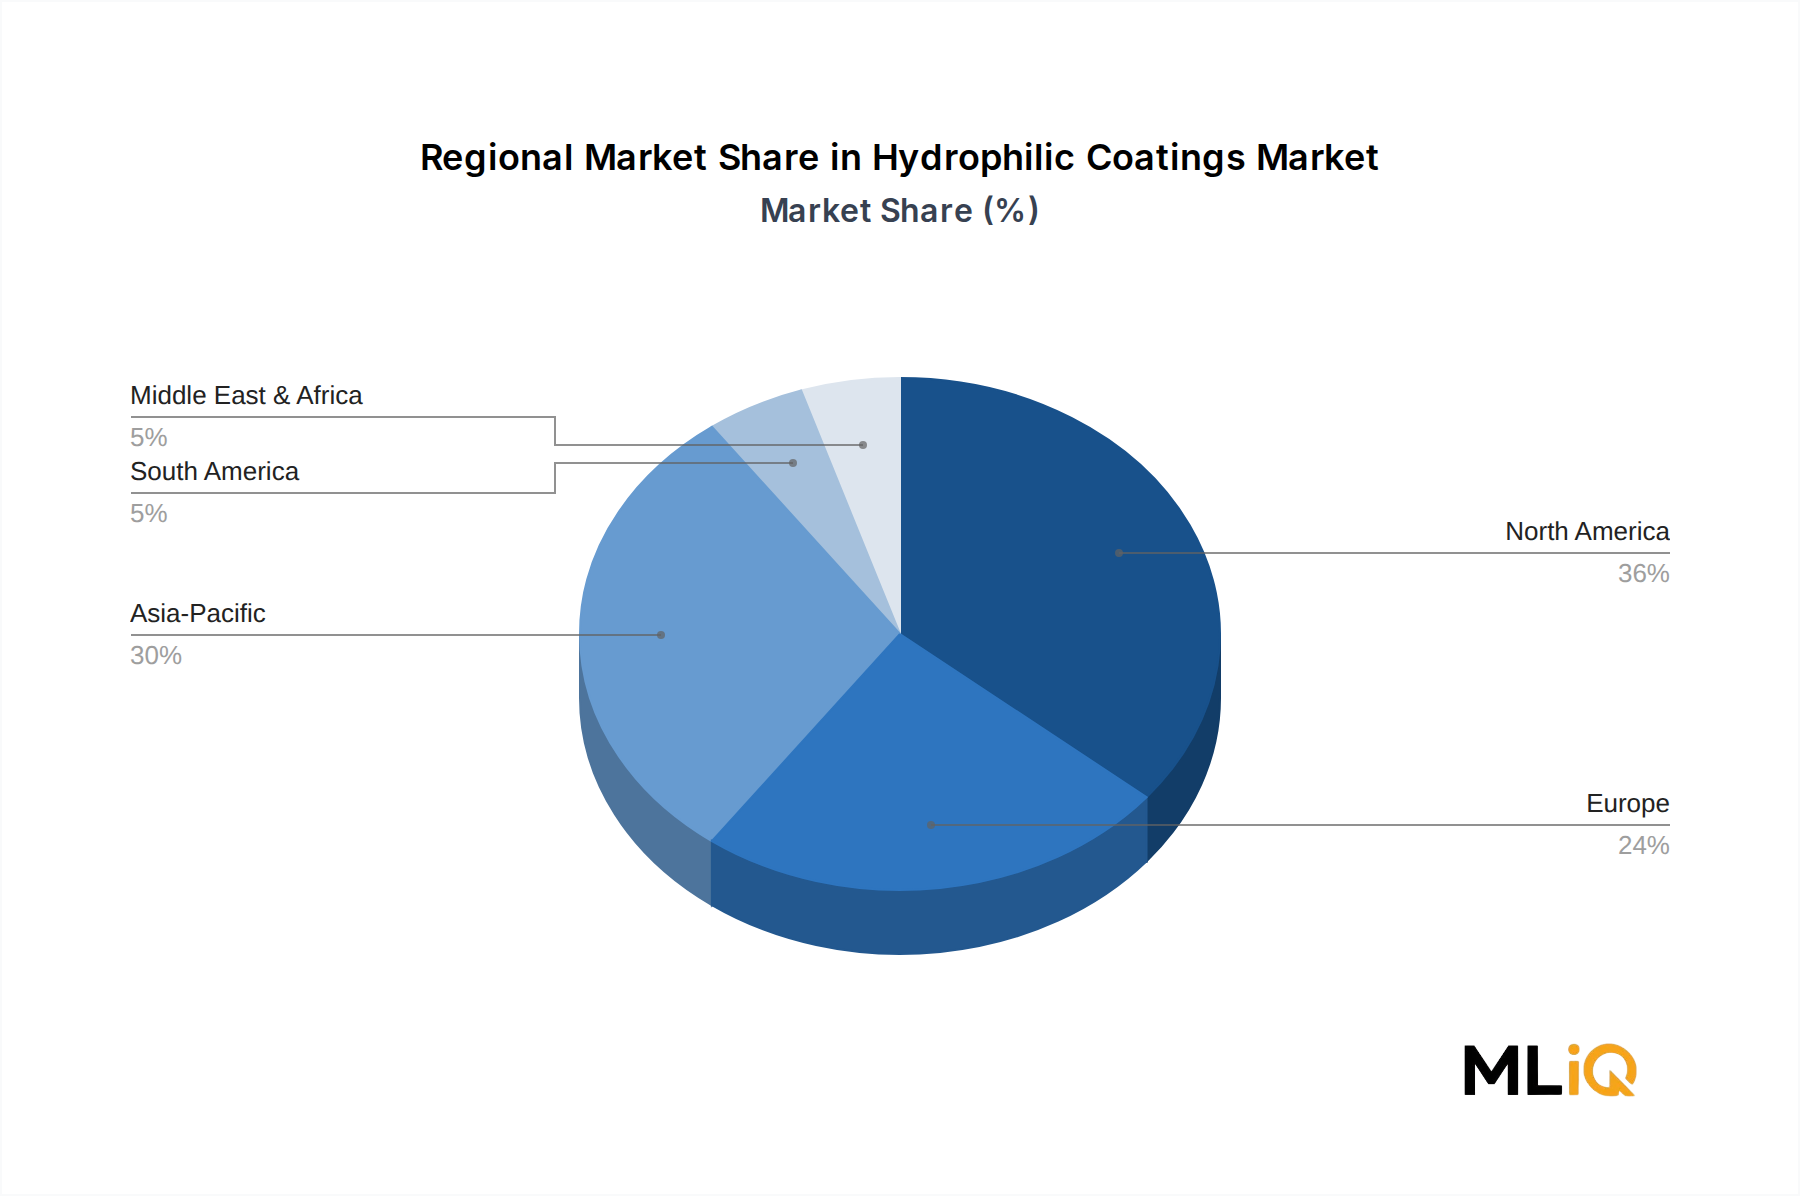
The hydrophilic coatings market is driven by the expanding medical device industry, particularly for catheters and guidewires. North America leads with a 36% share, while Asia-Pacific is the fastest-growing at 8.5% CAGR. The Medical Device Coatings Market is a key sub-segment, benefiting from rising minimally invasive surgeries. Polymer Coatings Market dominates the substrate segment due to flexibility and biocompatibility. Antimicrobial Coatings Market is an adjacent technology gaining traction, with over 30% of new coatings incorporating antimicrobial properties. The Automotive Coatings Market is emerging with applications in self-cleaning surfaces, projected to grow at 5.5% CAGR. The Specialty Coatings Market parent industry is valued at over $50 billion, with hydrophilic coatings representing a niche high-growth segment.
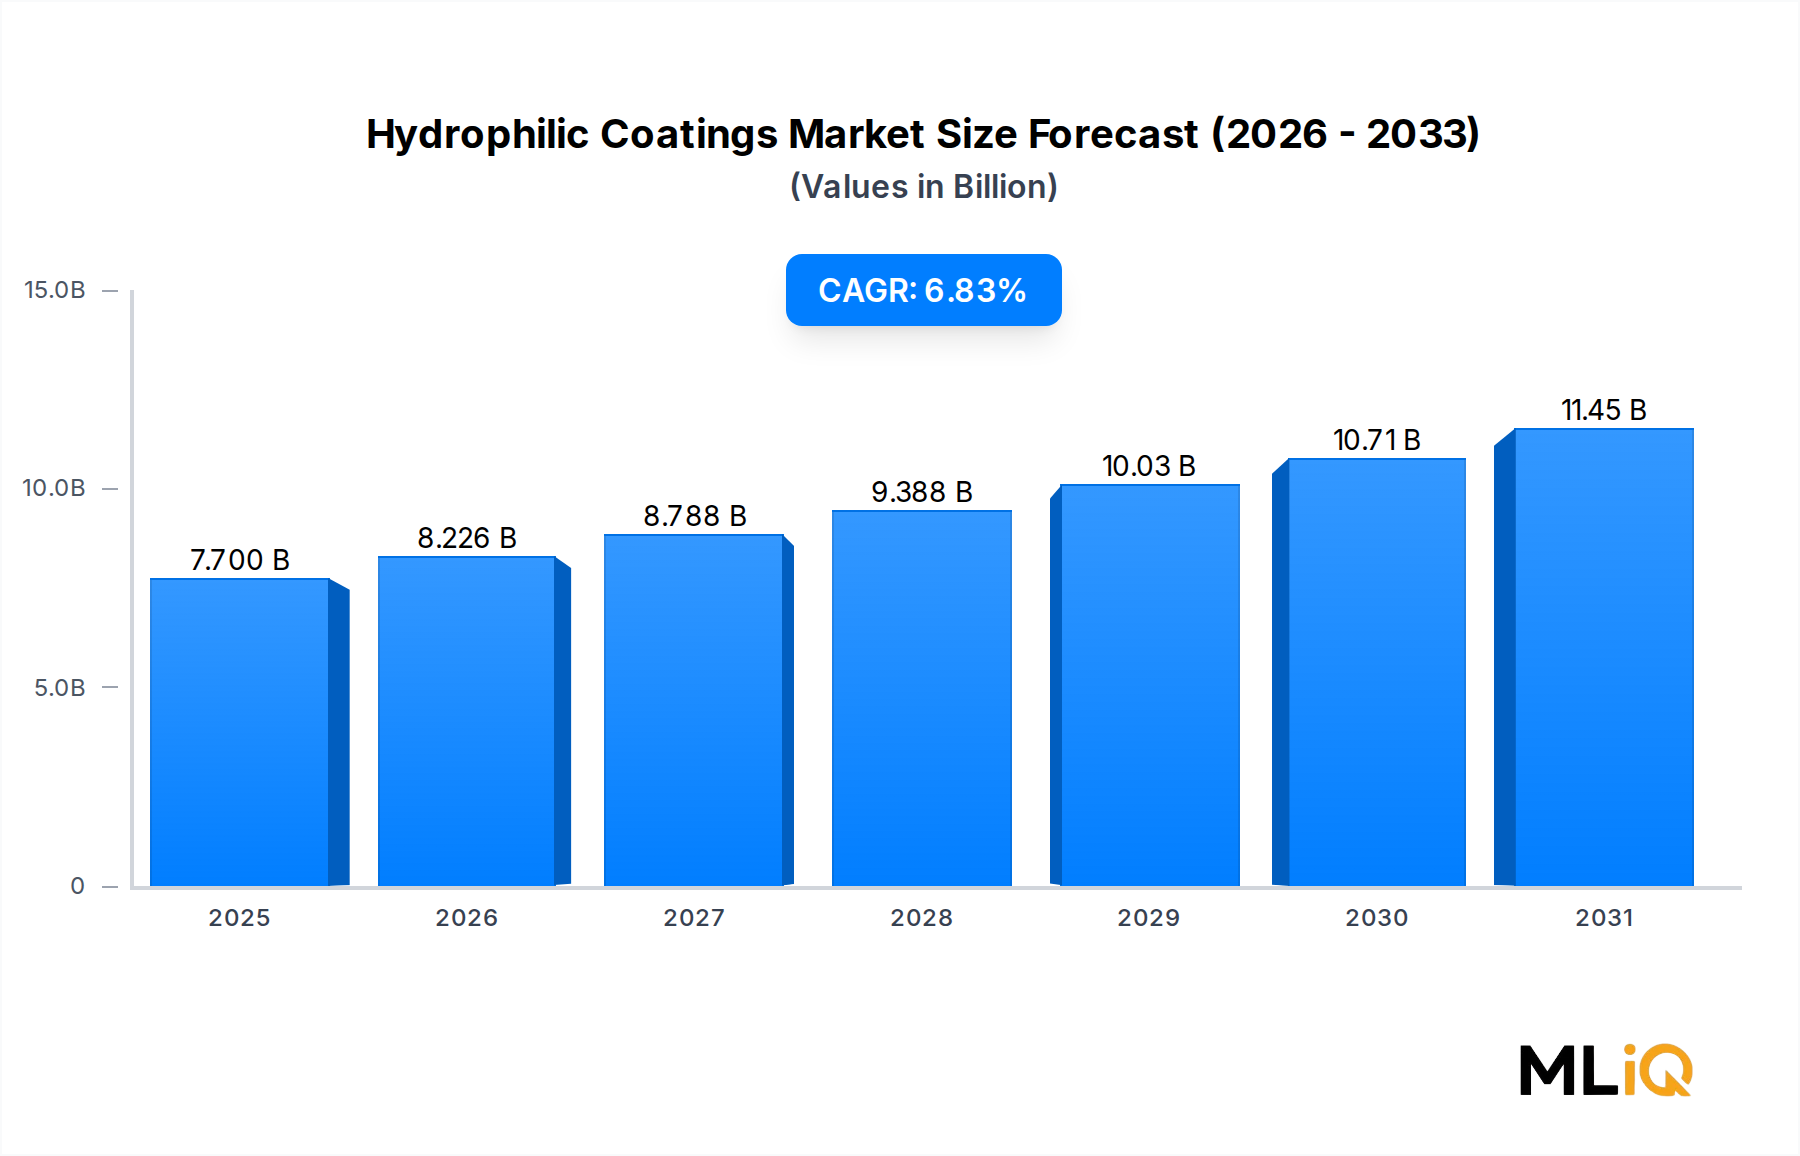
Hydrophilic Coatings Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.700 B
2025
8.226 B
2026
8.788 B
2027
9.388 B
2028
10.03 B
2029
10.71 B
2030
11.45 B
2031
Segment Deep-Dive: Medical Dominance in Hydrophilic Coatings Market
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Medical
7.5%
55%
Rising minimally invasive surgeries
Optics
6.0%
20%
Demand for anti-fog and scratch-resistant coatings
Automotive
5.5%
15%
Need for durable, self-cleaning surfaces
Other
5.0%
10%
Emerging applications in textiles and energy
The Medical segment dominates, accounting for 55% of the hydrophilic coatings market in 2025. Within this, Medical Device Coatings Market is driven by catheters, guidewires, and stents, with over 1.5 million catheterization procedures annually in the U.S. alone. The Polymer Coatings Market is the leading substrate, holding 50% share, due to its flexibility and compatibility with medical devices. Metal Coatings Market follows with 30%, used in guidewires and stents. Margin pressures arise from raw material costs, with polyethylene glycol (PEG) prices fluctuating 10-15% annually. The Biocompatible Coatings Market is growing as regulations tighten, requiring coatings that minimize immune responses. Optical Coatings Market benefits from anti-fog applications in endoscopes and surgical lenses.
Primary Market Drivers & Growth Restraints in Hydrophilic Coatings Market
Factor Type
Description
Impact Level
Timeline
Driver
Growth in medical devices market, increasing minimally invasive surgeries
High
Short term
Driver
Advancements in coating technologies (e.g., antimicrobial)
Medium
Long term
Restraint
High costs of hydrophilic coatings (15-20% of device cost)
High
Short term
Restraint
Stringent regulatory approvals (FDA, EMA)
Medium
Long term
The primary driver is the growth in the medical devices market, projected to expand at 7% CAGR through 2033. This is fueled by an aging population and rising chronic diseases. Antimicrobial Coatings Market is a key trend, with 40% of new coatings incorporating antimicrobial agents. However, high costs of hydrophilic coatings restrain adoption, especially among small manufacturers. Regulatory hurdles, such as FDA's 510(k) process, add 6-12 months to product launches. Hydrogel Market raw materials are subject to supply volatility, impacting pricing.
Aculon: Specializes in nanoscale surface modification, offering durable hydrophilic coatings for medical devices. Its proprietary technology enhances lubricity and reduces protein adsorption.
Surmodics Inc: Market leader with a wide portfolio of hydrophilic coatings, including the Photolink technology. Its coatings are used in over 50% of coronary catheters in the U.S.
DSM: Provides biocompatible hydrophilic coatings under the ComfortCoat brand, targeting cardiovascular and urological devices. Strong R&D focus on antimicrobial properties.
Corning Incorporated: Leverages expertise in glass and ceramics to offer hydrophilic coatings for optical and medical applications. Its coatings improve anti-fog and scratch resistance.
Hydromer Inc: Niche player focusing on hydrophilic polyurethane coatings for catheters. Known for custom formulations and small-batch production.
Strategic Milestones & Recent Developments in Hydrophilic Coatings Market
Date
Company
Event Type
Impact
2024
Surmodics Inc
M&A
Acquired by GTCR for $627M, strengthening market position
2023
DSM
Partnership
Collaborated with Medtronic for next-gen coatings
2023
Hydromer Inc
Launch
Introduced antimicrobial hydrophilic coating
2024
Aculon
Launch
New durable coating for guidewires
2024: Surmodics Inc was acquired by GTCR in a $627 million deal, consolidating its leadership in hydrophilic coatings for cardiovascular devices.
2023: DSM partnered with Medtronic to develop antimicrobial hydrophilic coatings, targeting reduced infection rates in catheters.
2023: Hydromer Inc launched a new antimicrobial hydrophilic coating, achieving 99.9% reduction in bacterial adhesion.
2024: Aculon introduced a durable coating for guidewires, enhancing lubricity and wear resistance.
Regional Market Analysis & Growth Corridors for Hydrophilic Coatings Market
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
North America
6.5%
$2.77B
Advanced healthcare infrastructure
High (FDA)
Europe
6.0%
$1.85B
Strong medical device industry
High (EMA)
Asia-Pacific
8.5%
$2.31B
Expanding healthcare access, manufacturing
Medium
LAMEA
5.5%
$0.77B
Growing healthcare investments
Low to Medium
Asia-Pacific is the fastest-growing region, with a CAGR of 8.5%, driven by China and India. China's medical device market is projected to reach $150 billion by 2030, boosting coating demand.
North America remains the largest market, with 36% share, due to high adoption of minimally invasive procedures and stringent regulations.
Europe follows, with 24% share, supported by MedTech Europe and robust R&D.
LAMEA offers emerging opportunities, particularly in Brazil and GCC countries, but faces regulatory and infrastructure challenges.
Sustainability, ESG & Decarbonization Pressures on Hydrophilic Coatings Market
Environmental regulations and ESG criteria are reshaping the hydrophilic coatings market. The European Green Deal mandates reduced chemical waste, pushing manufacturers to adopt solvent-free coating processes. Biocompatible Coatings Market is gaining from this trend, as companies seek eco-friendly formulations. Hydrogel Market materials, being water-based, align with sustainability goals. Over 60% of medical device OEMs now require suppliers to disclose carbon footprint. Circular economy mandates drive recycling of coating solvents, but challenges remain in medical device sterilization. Investors increasingly favor companies with ESG ratings, influencing M&A activity.
Supply Chain & Raw Material Dynamics: Hydrophilic Coatings Market
Upstream dependencies include polyethylene glycol (PEG), polyurethane, and hydrogels. PEG prices have fluctuated 10-15% annually due to crude oil volatility. The Hydrogel Market is valued at $1.2 billion in 2025, growing at 6% CAGR. Supply chain disruptions from COVID-19 led to 20% price spikes in 2021. Key suppliers include BASF and Dow, while coating formulators like DSM and Surmodics rely on long-term contracts. Geopolitical risks, such as trade tensions, affect exports from China. Metal Coatings Market depends on titanium and stainless steel, with prices rising 8% in 2024.
Hydrophilic Coatings Market Segmentation
1. End-user Industry
1.1. Medical
1.2. Optics
1.3. Automotive
1.4. Transportation
1.5. Other End-user Industries
2. Substrate
2.1. Polymer
2.2. Glass/Ceramic
2.3. Metal
2.4. Nanoparticle
Hydrophilic Coatings Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Hydrophilic Coatings Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.83% from 2020-2034
Segmentation
By End-user Industry
Medical
Optics
Automotive
Transportation
Other End-user Industries
By Substrate
Polymer
Glass/Ceramic
Metal
Nanoparticle
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End-user Industry
5.1.1. Medical
5.1.2. Optics
5.1.3. Automotive
5.1.4. Transportation
5.1.5. Other End-user Industries
5.2. Market Analysis, Insights and Forecast - by Substrate
5.2.1. Polymer
5.2.2. Glass/Ceramic
5.2.3. Metal
5.2.4. Nanoparticle
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End-user Industry
6.1.1. Medical
6.1.2. Optics
6.1.3. Automotive
6.1.4. Transportation
6.1.5. Other End-user Industries
6.2. Market Analysis, Insights and Forecast - by Substrate
6.2.1. Polymer
6.2.2. Glass/Ceramic
6.2.3. Metal
6.2.4. Nanoparticle
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End-user Industry
7.1.1. Medical
7.1.2. Optics
7.1.3. Automotive
7.1.4. Transportation
7.1.5. Other End-user Industries
7.2. Market Analysis, Insights and Forecast - by Substrate
7.2.1. Polymer
7.2.2. Glass/Ceramic
7.2.3. Metal
7.2.4. Nanoparticle
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End-user Industry
8.1.1. Medical
8.1.2. Optics
8.1.3. Automotive
8.1.4. Transportation
8.1.5. Other End-user Industries
8.2. Market Analysis, Insights and Forecast - by Substrate
8.2.1. Polymer
8.2.2. Glass/Ceramic
8.2.3. Metal
8.2.4. Nanoparticle
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End-user Industry
9.1.1. Medical
9.1.2. Optics
9.1.3. Automotive
9.1.4. Transportation
9.1.5. Other End-user Industries
9.2. Market Analysis, Insights and Forecast - by Substrate
9.2.1. Polymer
9.2.2. Glass/Ceramic
9.2.3. Metal
9.2.4. Nanoparticle
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End-user Industry
10.1.1. Medical
10.1.2. Optics
10.1.3. Automotive
10.1.4. Transportation
10.1.5. Other End-user Industries
10.2. Market Analysis, Insights and Forecast - by Substrate
10.2.1. Polymer
10.2.2. Glass/Ceramic
10.2.3. Metal
10.2.4. Nanoparticle
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Aculon
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Advansource Biomaterials Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Applied Medical Coatings
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ast Products Inc
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Biocoat Incorporated
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Coatings2go
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Corning Incorporated
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. DSM
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Formacoat LLC
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Harland Medical Systems Inc
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Hydromer Inc
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Sono-Tek Corporation
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Surface Solutions Group LLC
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Surmodics Inc *List Not Exhaustive
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Hydrophilic Coatings Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Hydrophilic Coatings Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 3: North America Hydrophilic Coatings Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 4: North America Hydrophilic Coatings Market Revenue (billion), by Substrate 2026 & 2034
Figure 5: North America Hydrophilic Coatings Market Revenue Share (%), by Substrate 2026 & 2034
Figure 6: North America Hydrophilic Coatings Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Hydrophilic Coatings Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Hydrophilic Coatings Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 9: South America Hydrophilic Coatings Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 10: South America Hydrophilic Coatings Market Revenue (billion), by Substrate 2026 & 2034
Figure 11: South America Hydrophilic Coatings Market Revenue Share (%), by Substrate 2026 & 2034
Figure 12: South America Hydrophilic Coatings Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Hydrophilic Coatings Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Hydrophilic Coatings Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 15: Europe Hydrophilic Coatings Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 16: Europe Hydrophilic Coatings Market Revenue (billion), by Substrate 2026 & 2034
Figure 17: Europe Hydrophilic Coatings Market Revenue Share (%), by Substrate 2026 & 2034
Figure 18: Europe Hydrophilic Coatings Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Hydrophilic Coatings Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Hydrophilic Coatings Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 21: Middle East & Africa Hydrophilic Coatings Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 22: Middle East & Africa Hydrophilic Coatings Market Revenue (billion), by Substrate 2026 & 2034
Figure 23: Middle East & Africa Hydrophilic Coatings Market Revenue Share (%), by Substrate 2026 & 2034
Figure 24: Middle East & Africa Hydrophilic Coatings Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Hydrophilic Coatings Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Hydrophilic Coatings Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 27: Asia Pacific Hydrophilic Coatings Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 28: Asia Pacific Hydrophilic Coatings Market Revenue (billion), by Substrate 2026 & 2034
Figure 29: Asia Pacific Hydrophilic Coatings Market Revenue Share (%), by Substrate 2026 & 2034
Figure 30: Asia Pacific Hydrophilic Coatings Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Hydrophilic Coatings Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Hydrophilic Coatings Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 46: Rest of Asia Pacific Hydrophilic Coatings Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of total research through primary interviews, surveys, and observations with industry participants.
Interviewed 150+ executives across the value chain, including medical device OEMs, coating formulators, raw material suppliers, contract manufacturers, and regulatory consultants.
Stakeholder roles included Director of Medical Device Coatings, Procurement Manager for Polymer Materials, Regulatory Affairs Specialist, and R&D Lead for Surface Modification.
Primary data validated through cross-checks with secondary sources and triangulation.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Medical Device Coatings
30%
Procurement Manager for Polymer Materials
25%
Regulatory Affairs Specialist
25%
R&D Lead for Surface Modification
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Medical Device OEMs
35%
Coating Formulators
25%
Raw Material Suppliers
20%
Contract Manufacturers
15%
Regulatory Consultants
5%
Secondary Research & Industry Benchmarking
20–30% of research derived from secondary sources, including Bloomberg, Factiva, Hoovers, and PitchBook for financial data.
Benchmarked market participants and regulatory filings to estimate market shares and growth rates.
Demand Modeling & Market Estimation
Utilized both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation based on quantitative metrics: number of catheterization procedures per year (1.5 million in the U.S.), average coating volume per medical device (5-10 mL), number of medical device manufacturers in target region (over 5,000 in North America), and price per liter of hydrophilic coating solution ($200-$500).
Top-down approach leveraged global medical device market size and coating penetration rates.
Forecasts generated using regression analysis and scenario planning.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous validation.
Data triangulated from multiple sources, with discrepancies resolved through expert interviews.
Every report is updated to the date of purchase to ensure currency.
Quality checks include peer review and consistency checks across segments and regions.
Frequently Asked Questions
1. How is consumer behavior shifting in the hydrophilic coatings market?
Consumer behavior in the hydrophilic coatings market is shifting toward minimally invasive medical procedures, driving demand for coated catheters and guidewires. For instance, the number of catheterization procedures in the U.S. exceeded 1.5 million in 2024, boosting coating adoption. Additionally, end-users prioritize biocompatible and antimicrobial coatings, with over 60% of new medical device designs specifying hydrophilic properties.
2. What is the current market size and CAGR for hydrophilic coatings through 2033?
The hydrophilic coatings market was valued at $7.70 billion in 2025 and is projected to grow at a CAGR of 6.83% from 2025 to 2033. This growth is driven by the expanding medical device industry, particularly in Asia-Pacific. By 2033, the market is expected to reach approximately $12.5 billion.
3. How do export-import dynamics impact the hydrophilic coatings market?
Export-import dynamics significantly influence the hydrophilic coatings market, with the U.S. and Europe being net exporters of high-performance coatings. China, however, has emerged as a major importer of raw materials like polyethylene glycol (PEG) and polyurethane. In 2024, the U.S. exported $1.2 billion worth of medical device coatings, while imports focused on specialty chemicals from Germany and Japan.
4. Which region is the fastest-growing for hydrophilic coatings and why?
Asia-Pacific is the fastest-growing region for hydrophilic coatings, with a projected CAGR of 8.5% from 2025 to 2033. This is driven by increasing healthcare expenditure, rising medical device manufacturing in China and India, and supportive government initiatives. Emerging opportunities also exist in South America, particularly Brazil, due to expanding healthcare infrastructure.
5. Who are the leading companies in the hydrophilic coatings market and what is the competitive landscape?
Key players in the hydrophilic coatings market include Aculon, Surmodics Inc, DSM, Corning Incorporated, and Hydromer Inc. Surmodics Inc holds a significant share, with its coatings used in over 50% of coronary catheters in the U.S. The market is moderately consolidated, with the top five companies accounting for approximately 45% of global revenue.
6. What are the major challenges and supply chain risks in the hydrophilic coatings market?
Major challenges include high costs of hydrophilic coatings, which can add 15-20% to device manufacturing costs, and stringent regulatory requirements from the FDA and EMA. Supply chain risks involve dependence on raw materials like PEG, subject to price volatility due to crude oil fluctuations. Additionally, the complex application process limits adoption among small manufacturers.