Opacifiers Market to Reach $36B by 2033 at 5.37% CAGR
Opacifiers Market
Opacifiers Market to Reach $36B by 2033 at 5.37% CAGR
Opacifiers Market by Type (Titanium Dioxide, Opaque Polymers, Zinc Oxide, Cerium Oxide, Others), by Application (Ceramics, Paints and Coatings, Paper, Personal Care, Plastics, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
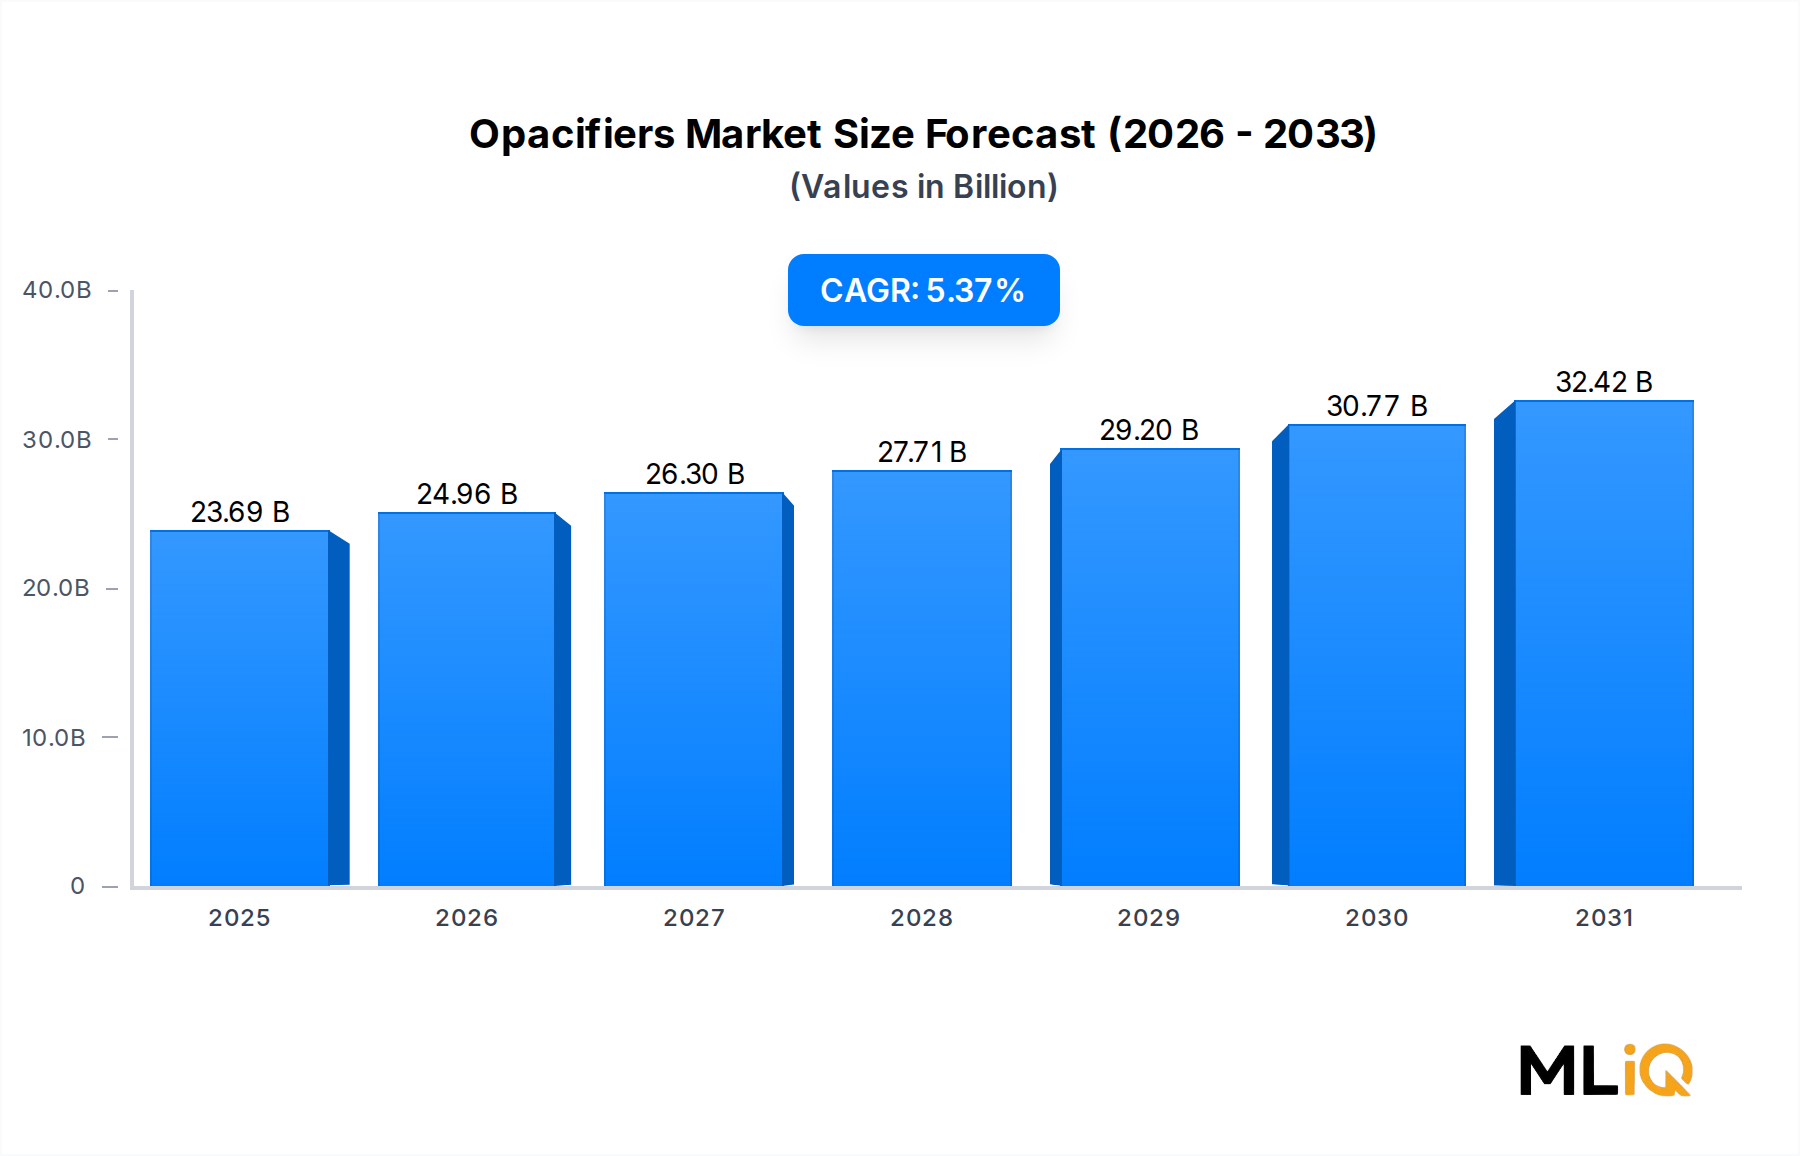
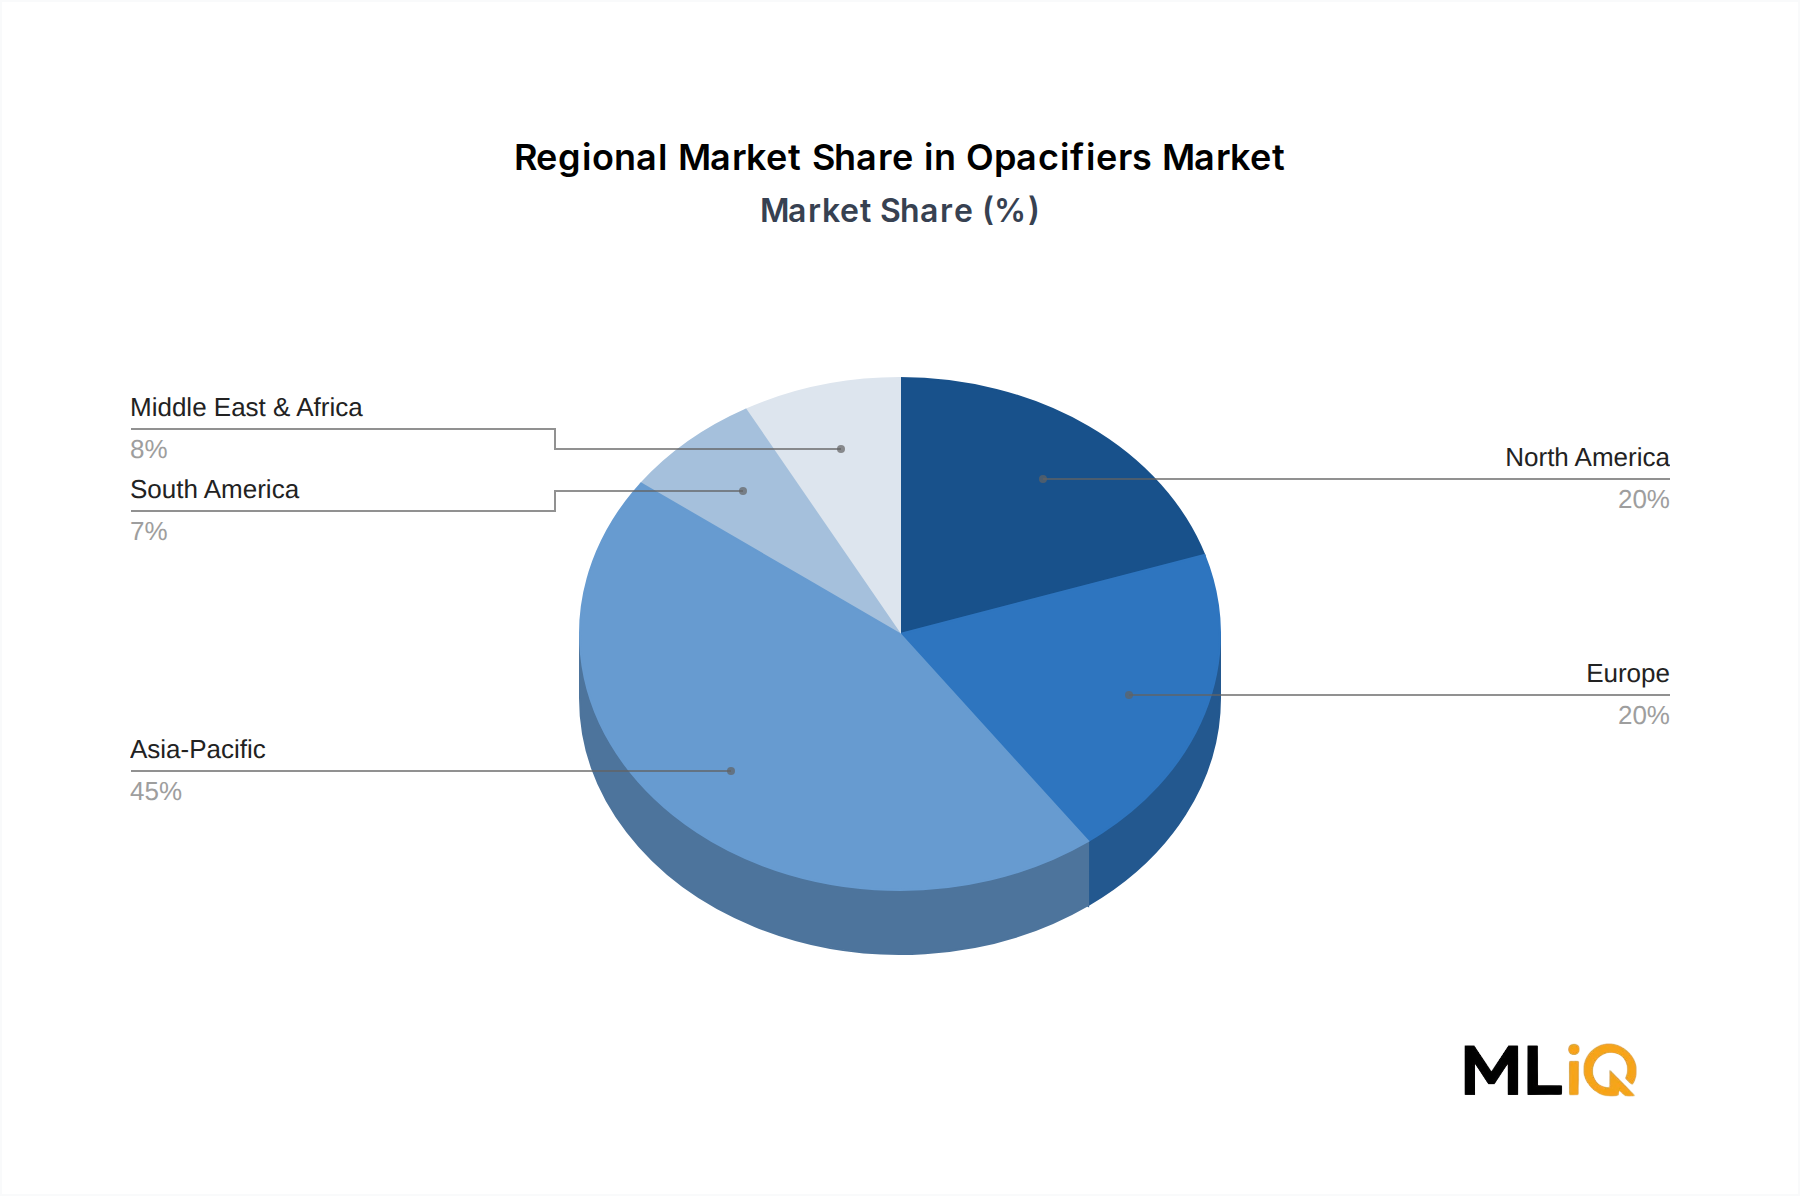
The Opacifiers Market is projected to grow from $23.69 billion in 2025 to $36.0 billion by 2033, registering a CAGR of 5.37%. This growth is propelled by robust demand from the Paints and Coatings Market, which consumes over 45% of opacifiers, and increasing applications in plastics, paper, and personal care. Asia-Pacific leads with a 45% market share, driven by rapid industrialization and construction activities in China and India.
Opacifiers Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
23.69 B
2025
24.96 B
2026
26.30 B
2027
27.71 B
2028
29.20 B
2029
30.77 B
2030
32.42 B
2031
The Titanium Dioxide Opacifiers Market holds the largest share, accounting for approximately 60% of total value, due to its superior opacity and whiteness. However, environmental regulations on TiO2 in Europe and North America are prompting a shift toward alternative opacifiers such as opaque polymers and zinc oxide. The Opaque Polymers Market is gaining traction in water-based coatings, offering voided latex particles that provide opacity without TiO2.
Key trends include the rising demand for eco-friendly and high-performance opacifiers, especially in the Personal Care Opacifiers Market for sunscreens and color cosmetics. The Specialty Chemicals Market is witnessing consolidation, with major players like Dow and Arkema investing in capacity expansions. Overall, the market presents lucrative opportunities in emerging economies, though raw material price volatility and regulatory hurdles remain challenges.
Segment Deep-Dive: Titanium Dioxide Dominance in Opacifiers Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Titanium Dioxide
5.0%
60%
Superior opacity and whiteness in paints and coatings
Opaque Polymers
6.5%
20%
Eco-friendly alternative in water-based formulations
Zinc Oxide
4.8%
10%
UV protection in personal care and ceramics
Others (Cerium Oxide, etc.)
5.5%
10%
Niche applications in glass and electronics
Titanium dioxide (TiO2) dominates the Opacifiers Market, with a 60% revenue share in 2025. Its high refractive index and hiding power make it indispensable in the Paints and Coatings Market, which accounts for over 70% of TiO2 consumption. However, the segment faces margin pressure from fluctuating raw material prices and regulatory scrutiny; the EU classified TiO2 as a suspected carcinogen in 2020, leading to labeling requirements.
Opaque polymers represent the fastest-growing segment, with a CAGR of 6.5%, driven by the shift toward low-VOC and water-based coatings. These polymers create voids that scatter light, partially replacing TiO2 and reducing cost. The Opaque Polymers Market is particularly strong in North America and Europe, where environmental regulations are stringent.
The Zinc Oxide Opacifiers Market, with a 10% market share, is used in ceramics, personal care (sunscreens), and rubber. Its growth is steady at 4.8% CAGR, supported by demand for UV protection in the Personal Care Opacifiers Market. Cerium oxide and other opacifiers hold niche positions, with applications in glass polishing and electronics.
Margin pressures are intensifying due to raw material cost inflation and energy prices. TiO2 producers are investing in chloride process technology to reduce waste and costs. Overall, the segment landscape is evolving toward sustainable alternatives, though TiO2 will retain dominance through 2033.
Primary Market Drivers & Growth Restraints in Opacifiers Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Growing demand from Paints and Coatings Market due to construction and automotive recovery
High
Short-term
Driver
Rising use of opacifiers in Plastics Market for packaging and consumer goods
Medium
Medium-term
Driver
Shift toward eco-friendly opacifiers in Personal Care Opacifiers Market
High
Long-term
Restraint
Stringent regulations on TiO2 (EU carcinogen classification)
High
Long-term
Restraint
Volatile raw material prices (titanium ore, zinc)
High
Short-term
Restraint
Supply chain disruptions from COVID-19 and geopolitical tensions
Medium
Short-term
The Opacifiers Market is primarily driven by the Paints and Coatings Market, which accounts for 45% of global demand. Construction spending growth in Asia-Pacific, particularly China and India, is a key catalyst, with infrastructure investments rising by 7% annually. The Plastics Market also fuels demand, as opacifiers enhance whiteness and opacity in packaging.
Environmental regulations pose significant restraints. The EU's classification of TiO2 as a category 2 carcinogen by inhalation has led to mandatory labeling and reduced use in certain applications. In the US, the EPA is reviewing TiO2 under the Toxic Substances Control Act. These regulations increase compliance costs and drive substitution with alternative opacifiers.
Raw material price volatility is another bottleneck. Titanium ore prices fluctuated by 20% in 2022, impacting TiO2 production costs. Zinc prices also spiked due to energy crises in Europe. Supply chain disruptions from COVID-19 lockdowns and the Russia-Ukraine war have exacerbated logistics challenges, though conditions are normalizing.
Broad portfolio of opaque polymers and TiO2 alternatives
Paints, coatings, personal care
Leader
Arkema Group
Specialty opacifiers and high-performance additives
Coatings, plastics
Leader
Tronox Holdings Plc
Integrated TiO2 production from ore to pigment
Paints, plastics, paper
Leader
Venator Materials PLC
Global TiO2 and performance additives
Coatings, plastics
Challenger
KRONOS Worldwide Inc
TiO2 manufacturing with global reach
Coatings, paper, ceramics
Challenger
Ashland
Opaque polymers for personal care and coatings
Personal care, pharmaceuticals
Niche
OMNOVA Solutions Inc
Specialty chemicals and opaque polymers
Coatings, paper
Niche
Indulor Chemie GmbH
Polymer opacifiers for industrial coatings
Coatings, adhesives
Niche
Dow: A global leader in materials science, Dow offers a range of opacifiers including opaque polymers under its ACUSOL and RHOPLEX brands. The company focuses on sustainable solutions and has a strong presence in the Paints and Coatings Market.
Arkema Group: Arkema provides specialty opacifiers and additives, leveraging its expertise in polymer chemistry. Its products target high-performance coatings and plastics, with a focus on innovation.
Tronox Holdings Plc: As one of the largest integrated TiO2 producers, Tronox controls the entire value chain from mining to pigment. It serves diverse end markets including paints, plastics, and paper.
Venator Materials PLC: Venator is a leading global producer of TiO2 and performance additives, with a strong customer base in the coatings industry. The company has been expanding its specialty product lines.
KRONOS Worldwide Inc: KRONOS manufactures TiO2 pigments for coatings, paper, and ceramics. It operates globally and emphasizes quality and technical support.
Ashland: Ashland offers opaque polymers for personal care and coatings, focusing on rheology and opacity. Its products are used in sunscreens and color cosmetics.
OMNOVA Solutions Inc: OMNOVA produces specialty chemicals and opaque polymers for coatings, paper, and textiles. The company is known for its sustainable product innovations.
Indulor Chemie GmbH: Indulor specializes in polymer opacifiers for industrial coatings and adhesives. It serves niche markets with customized solutions.
Strategic Milestones & Recent Developments in Opacifiers Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2023
Tronox Holdings Plc
Capacity Expansion
Increased TiO2 production by 10% in Australia
2022
Dow
Partnership
Collaborated with a coatings company to develop bio-based opacifiers
2021
Venator Materials PLC
M&A
Acquired a specialty pigment producer to expand portfolio
2020
Arkema Group
Launch
Introduced a new range of high-performance opaque polymers
2019
KRONOS Worldwide Inc
Capacity Expansion
Expanded TiO2 plant in Germany
2023: Tronox Holdings Plc completed a 10% capacity expansion at its Australian TiO2 plant, aiming to meet rising demand from the Paints and Coatings Market. This move strengthens its position as a leading integrated producer.
2022: Dow partnered with a major coatings manufacturer to develop bio-based opacifiers, targeting reduced carbon footprint. The collaboration aligns with the growing demand for sustainable solutions in the Specialty Chemicals Market.
2021: Venator Materials PLC acquired a specialty pigment producer, enhancing its product portfolio for plastics and personal care applications. The acquisition aimed to diversify revenue streams.
2020: Arkema Group launched a new line of high-performance opaque polymers for water-based coatings, addressing the need for TiO2 alternatives. This launch targeted the European market.
2019: KRONOS Worldwide Inc expanded its TiO2 plant in Germany, increasing capacity by 15%. The expansion supported growing demand from the Paper Opacifiers Market and ceramics.
Regional Market Analysis & Growth Corridors for Opacifiers Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation ($ Billion)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
6.2%
10.66
Rapid industrialization and construction in China and India
Moderate
North America
4.5%
4.74
Recovery in automotive and construction sectors
High
Europe
4.2%
4.74
Demand for eco-friendly opacifiers and coatings
High
LAMEA
5.0%
3.55
Infrastructure development and personal care market growth
Low to Moderate
Asia-Pacific: The largest and fastest-growing region, with a 45% share and a CAGR of 6.2%. China and India drive demand through construction booms and expanding manufacturing. Regulatory frameworks are less stringent than in the West, but environmental rules are tightening.
North America: A mature market with a 4.5% CAGR, valued at $4.74 billion in 2025. The US and Canada focus on high-performance and sustainable opacifiers. EPA regulations on TiO2 influence product formulations.
Europe: Similar to North America in size, Europe grows at 4.2% CAGR. Stringent REACH regulations push innovation in opaque polymers and alternative opacifiers. Germany, France, and UK are key markets.
LAMEA: A diverse region comprising Latin America, Middle East, and Africa. It grows at 5.0% CAGR, driven by infrastructure projects in Brazil and GCC countries, and rising personal care demand in South Africa. Regulatory oversight varies widely.
Pricing Dynamics, Cost Structures & Margin Pressure in Opacifiers Market
Average selling prices (ASP) for opacifiers have climbed due to inflationary pressures. Titanium dioxide prices increased by 10-15% from 2021 to 2023, reaching $3,200 per ton in Europe. Cost structures are dominated by raw materials (60-70%), followed by energy (15-20%), labor (10%), and logistics (5%). The Titanium Dioxide Pigment Market faces margin pressure from volatile titanium ore prices and energy costs, while opaque polymers command premium prices due to their sustainable profile. Manufacturers are passing costs to customers, but competitive intensity limits pricing power in standard grades. In the Paints and Coatings Market, formulators seek cost-effective alternatives, boosting demand for opaque polymers that reduce TiO2 loading.
Supply Chain & Raw Material Dynamics: Opacifiers Market
The supply chain for opacifiers begins with raw materials such as titanium ore (ilmenite, rutile), zinc ore, and cerium compounds. Titanium ore prices are volatile, influenced by mining output and geopolitical factors; prices rose 20% in 2022 before stabilizing in 2023. Key suppliers include Rio Tinto, Iluka Resources, and Tronox. The Specialty Chemicals Market is experiencing supply chain disruptions due to logistics bottlenecks and energy shortages, particularly in Europe. Manufacturers are diversifying sourcing and investing in recycling. For opaque polymers, key inputs are acrylic monomers and styrene, derived from petrochemicals. The Plastics Market and Paper Opacifiers Market are sensitive to these raw material trends, with price fluctuations directly impacting margins. Overall, supply chain resilience is a priority, with companies increasing inventory buffers and exploring alternative materials.
Opacifiers Market Segmentation
1. Type
1.1. Titanium Dioxide
1.2. Opaque Polymers
1.3. Zinc Oxide
1.4. Cerium Oxide
1.5. Others
2. Application
2.1. Ceramics
2.2. Paints and Coatings
2.3. Paper
2.4. Personal Care
2.5. Plastics
2.6. Others
Opacifiers Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Opacifiers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.37% from 2020-2034
Segmentation
By Type
Titanium Dioxide
Opaque Polymers
Zinc Oxide
Cerium Oxide
Others
By Application
Ceramics
Paints and Coatings
Paper
Personal Care
Plastics
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Titanium Dioxide
5.1.2. Opaque Polymers
5.1.3. Zinc Oxide
5.1.4. Cerium Oxide
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Ceramics
5.2.2. Paints and Coatings
5.2.3. Paper
5.2.4. Personal Care
5.2.5. Plastics
5.2.6. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Titanium Dioxide
6.1.2. Opaque Polymers
6.1.3. Zinc Oxide
6.1.4. Cerium Oxide
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Ceramics
6.2.2. Paints and Coatings
6.2.3. Paper
6.2.4. Personal Care
6.2.5. Plastics
6.2.6. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Titanium Dioxide
7.1.2. Opaque Polymers
7.1.3. Zinc Oxide
7.1.4. Cerium Oxide
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Ceramics
7.2.2. Paints and Coatings
7.2.3. Paper
7.2.4. Personal Care
7.2.5. Plastics
7.2.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Titanium Dioxide
8.1.2. Opaque Polymers
8.1.3. Zinc Oxide
8.1.4. Cerium Oxide
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Ceramics
8.2.2. Paints and Coatings
8.2.3. Paper
8.2.4. Personal Care
8.2.5. Plastics
8.2.6. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Titanium Dioxide
9.1.2. Opaque Polymers
9.1.3. Zinc Oxide
9.1.4. Cerium Oxide
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Ceramics
9.2.2. Paints and Coatings
9.2.3. Paper
9.2.4. Personal Care
9.2.5. Plastics
9.2.6. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Titanium Dioxide
10.1.2. Opaque Polymers
10.1.3. Zinc Oxide
10.1.4. Cerium Oxide
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Ceramics
10.2.2. Paints and Coatings
10.2.3. Paper
10.2.4. Personal Care
10.2.5. Plastics
10.2.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AMGEEN MINERALS
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Arkema Group
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Ashland
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Dow
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Indulor Chemie GmbH
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. KRONOS Worldwide Inc
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. OMNOVA Solutions Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Tronox Holdings Plc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Venator Materials PLC
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Quaternia*List Not Exhaustive
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Opacifiers Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Opacifiers Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Opacifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Opacifiers Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Opacifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Opacifiers Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Opacifiers Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Opacifiers Market Revenue (billion), by Type 2026 & 2034
Figure 9: South America Opacifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Opacifiers Market Revenue (billion), by Application 2026 & 2034
Figure 11: South America Opacifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Opacifiers Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Opacifiers Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Opacifiers Market Revenue (billion), by Type 2026 & 2034
Figure 15: Europe Opacifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Opacifiers Market Revenue (billion), by Application 2026 & 2034
Figure 17: Europe Opacifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Opacifiers Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Opacifiers Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Opacifiers Market Revenue (billion), by Type 2026 & 2034
Figure 21: Middle East & Africa Opacifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Opacifiers Market Revenue (billion), by Application 2026 & 2034
Figure 23: Middle East & Africa Opacifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Opacifiers Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Opacifiers Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Opacifiers Market Revenue (billion), by Type 2026 & 2034
Figure 27: Asia Pacific Opacifiers Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Opacifiers Market Revenue (billion), by Application 2026 & 2034
Figure 29: Asia Pacific Opacifiers Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Opacifiers Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Opacifiers Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Opacifiers Market Revenue billion Forecast, by Type 2020 & 2034
Table 46: Rest of Asia Pacific Opacifiers Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of our data collection efforts, ensuring high granularity and accuracy.
We conduct in-depth interviews with 5 specific company types in the opacifiers value chain: titanium dioxide pigment producers, opaque polymer manufacturers, zinc oxide suppliers, specialty chemical distributors, and end-product manufacturers (paints, plastics, paper).
We target 4 stakeholder job titles: Procurement Director, R&D Manager, Production Manager, and Quality Assurance Manager.
Interviews are structured to capture quantitative and qualitative insights on pricing, demand, and supply chain dynamics.
Data accuracy is guaranteed at 85–90%, validated through cross-referencing with secondary sources.
Industry benchmarks are derived from historical trends, regulatory filings, and technical literature.
All reports are updated to the date of purchase to ensure relevance.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation uses specific quantitative metrics: number of paint and coating production facilities globally, average opacifier consumption per ton of coating, growth in plastics production volume, and personal care product sales.
Top-down estimation starts with global chemical market size and allocates share to opacifiers based on application demand.
Regional demand is modeled using construction spending, automotive production, and paper output data.
Data Accuracy & Quality Check
Data accuracy is assured at 85–90% through rigorous validation.
We triangulate primary interview data with secondary sources and historical trends.
Outliers are re-examined, and discrepancies are resolved via follow-up interviews.
Final estimates are cross-checked against industry benchmarks and expert opinions.
Frequently Asked Questions
1. What are the major challenges and supply chain risks in the Opacifiers Market?
Key challenges include volatile raw material prices, particularly titanium dioxide, which saw a 15% price increase in 2022 due to energy costs. Regulatory pressures from EPA and REACH on TiO2 classification add compliance costs. Supply chain disruptions from COVID-19 and geopolitical tensions have also impacted logistics and availability.
2. What are the primary growth drivers for the Opacifiers Market?
Growth is driven by rising demand from the Paints and Coatings Market, which accounts for over 40% of opacifier consumption, and the Plastics Market. Increasing construction activities and automotive production in Asia-Pacific, coupled with a shift toward high-performance and eco-friendly opacifiers, are key catalysts. The market is projected to grow at a 5.37% CAGR through 2033.
3. What is the current market size and projected CAGR for the Opacifiers Market through 2033?
The Opacifiers Market was valued at $23.69 billion in 2025 and is expected to reach $36.0 billion by 2033, growing at a CAGR of 5.37%. This growth is supported by expanding applications in ceramics, paper, and personal care. Asia-Pacific dominates with a 45% share of the global market.
4. How are pricing trends and cost structures evolving in the Opacifiers Market?
Average selling prices for titanium dioxide-based opacifiers have risen due to higher energy and raw material costs, with a 10-15% increase from 2021 to 2022. Cost structures are dominated by raw materials (60-70%), followed by energy (15-20%) and labor (10%). Pricing power varies by segment, with specialized opaque polymers commanding premium prices.
5. What consumer behavior shifts are impacting the Opacifiers Market?
Consumers are increasingly favoring eco-friendly and low-VOC products, driving demand for water-based opacifiers in the Paints and Coatings Market. There is also a growing preference for high-opacity, durable formulations in the Personal Care Opacifiers Market, particularly in sunscreens and cosmetics. This shift is pushing manufacturers to innovate sustainable solutions.
6. Which end-user industries drive demand in the Opacifiers Market?
Paints and coatings is the largest end-user, accounting for about 45% of demand, followed by plastics (20%), paper (15%), and personal care (10%). The Ceramics Opacifiers Market is also growing, driven by construction and sanitaryware. Emerging applications in 3D printing and electronics present new opportunities.
About Market Lens IQ
Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.