Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Indonesia Concrete Admixtures Market: 6.57% CAGR to 2033
Indonesia Concrete Admixtures Market
Indonesia Concrete Admixtures Market: 6.57% CAGR to 2033
Indonesia Concrete Admixtures Market by End Use Sector (Commercial, Industrial and Institutional, Infrastructure, Residential), by Sub Product (Accelerator, Air Entraining Admixture, High Range Water Reducer (Super Plasticizer), Retarder, Shrinkage Reducing Admixture, Viscosity Modifier, Water Reducer (Plasticizer), Other Types), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 197
Key Insights & Executive Summary: Indonesia Concrete Admixtures Market
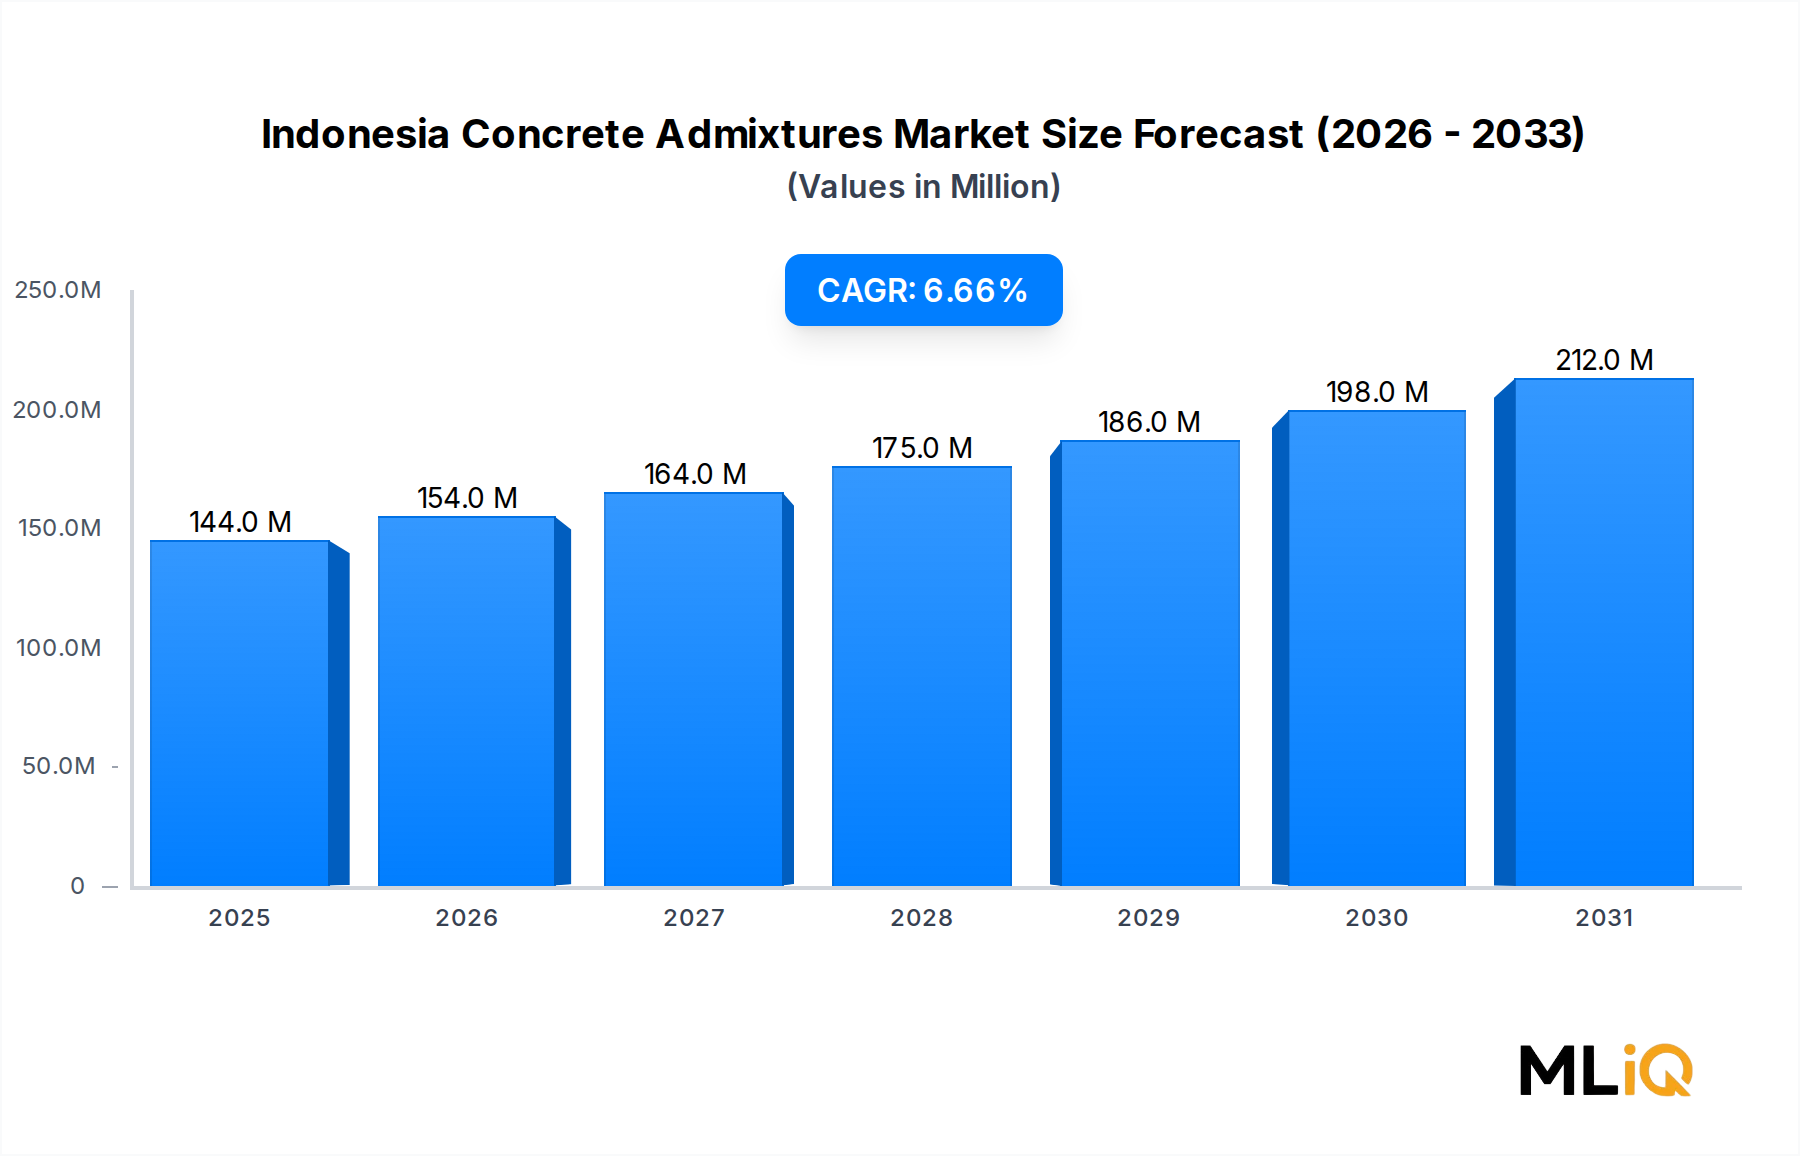
Indonesia Concrete Admixtures Market Size (In Million)
250.0M
200.0M
150.0M
100.0M
50.0M
0
144.0 M
2025
154.0 M
2026
164.0 M
2027
175.0 M
2028
186.0 M
2029
198.0 M
2030
212.0 M
2031
Market at a Glance
The sector expands from USD 144.40 million in 2025 to approximately USD 240.2 million by 2033, a 6.57% CAGR that exceeds Indonesia's overall construction materials growth of about 4.8%. Three forces set the pace: state infrastructure spending, conversion from site-mixed to plant-mixed concrete, and tighter SNI cement standards that raise admixture dosing per cubic meter.
Infrastructure represents an estimated 38% of admixture volume, led by the Nusantara capital program, Trans-Sumatra toll roads, and hydropower dams.
The Indonesia Ready-Mix Concrete Market is expanding at roughly 7% annually, and each additional cubic meter of plant-mixed concrete carries 1.5-2.5 kg of admixture.
Superplasticizers hold 36% of product value, reflecting demand for high-slump, low-water mixes in high-rise and precast work.
Import dependence is material: an estimated 55-60% of polycarboxylate ether feedstock originates from China, Japan, and South Korea.
The Indonesia Construction Chemicals Market is being reshaped by consolidation. Sika's absorption of MBCC Group and Saint-Gobain's purchase of GCP Applied Technologies concentrated technical service capability, while local formulators such as PT Kimia Konstruksi Indonesia compete on price and delivery speed. Margin pressure is measurable: PCE resin costs rose 12% in 2024, and batching plant operators resist price increases above 5%.
Demand catalysts through 2033 include a housing backlog of 9.9 million units, the USD 33 billion Nusantara build-out, and a national target of full ready-mix penetration in tier-1 cities by 2030. Restraints center on imported raw material exposure, rupiah volatility, and a thin pool of trained concrete technologists.
Segment Deep-Dive: High Range Water Reducer (Super Plasticizer) Dominance in Indonesia Concrete Admixtures Market
Segment Analysis Matrix
Segment
CAGR (2025-2033)
Market Share (%)
Key Demand Driver
High Range Water Reducer (Super Plasticizer)
7.4%
36%
High-rise and precast mixes requiring 25-40% water reduction
Water Reducer (Plasticizer)
5.8%
18%
Low-cost residential and non-structural pours
Accelerator
6.9%
11%
Fast-track infrastructure repair and precast cycle times
Retarder
5.4%
9%
Long-haul delivery across Java and Sumatra corridors
Air Entraining Admixture
5.2%
8%
Workability and durability in high-humidity climates
Shrinkage Reducing Admixture
7.0%
6%
Crack control in slabs and industrial flooring
Viscosity Modifier
6.6%
5%
Self-consolidating and underwater concrete
Other Types
6.0%
7%
Corrosion inhibitors and waterproofing integrators
Revenue Concentration and Sub-Segment Dynamics
Superplasticizers, predominantly polycarboxylate ether (PCE) chemistry, generated an estimated USD 52 million of the USD 144.40 million base-year value and are forecast to reach roughly USD 92 million by 2033. The Indonesia Superplasticizer Market benefits from three structural conditions: high ambient temperatures that accelerate slump loss, long delivery distances between batching plants and urban job sites, and rising use of self-consolidating and high-strength grades above C40.
PCE share of superplasticizer volume: approximately 68% in 2025, up from 55% in 2019.
Naphthalene sulfonate (SNF) share: about 24%, declining as specifiers demand 30%+ water reduction.
Lignosulfonate plasticizers: concentrated in the Indonesia Concrete Water Reducer Market, serving residential pours where cost per cubic meter overrides specification.
The Indonesia Polycarboxylate Ether Market remains import-linked, with powder and liquid resin shipments from China, Japan, and South Korea feeding both integrated producers and independent formulators. Resin price volatility of plus or minus 15% within a single year is normal and transmits directly into finished admixture pricing.
End-Use Overlay and Margin Pressure
End Use Sector
Share (%)
Typical Dosage (kg/m3)
Price Sensitivity
Infrastructure
38%
1.8-2.5
Low-Medium
Residential
27%
0.8-1.5
High
Commercial
20%
1.5-2.2
Medium
Industrial and Institutional
15%
1.2-2.0
Medium
Gross margins for integrated producers sit between 22% and 30%, while local blenders that purchase PCE resin on spot terms operate at 15-20%. The gap widens when freight and port handling add 6-9% to landed feedstock cost. Technical service, not chemistry alone, determines whether a supplier defends price: plants that receive on-site slump adjustment and dosage optimization tolerate a 4-6% premium.
Primary Market Drivers & Growth Restraints in Indonesia Concrete Admixtures Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Nusantara capital build-out and Trans-Sumatra toll corridors, roughly USD 33 billion committed through 2029
High
Short-Long term
Driver
Ready-mix penetration rising from 42% toward an estimated 58% of concrete volume by 2030
High
Long term
Driver
SNI cement and concrete standards tightening water-cement ratio limits
Medium
Long term
Driver
Precast and modular construction growth in Java industrial estates
Price competition from local formulators operating at 15-20% gross margin
Medium
Short term
Restraint
Shortage of trained concrete technologists at batching plants
Medium
Long term
Restraint
Slow permitting and land acquisition on public projects
Medium
Short term
Catalysts Under Quantitative Review
The Indonesia Concrete Accelerator Market is the clearest beneficiary of fast-track repair and precast cycle-time compression, growing at 6.9% CAGR as contractors shorten demolding windows. The Indonesia Infrastructure Construction Market underpins this demand: public works budgets allocate close to USD 28-30 billion annually to transport and water infrastructure, and each kilometer of rigid pavement consumes 6-9 tonnes of admixture-blended concrete.
Volume upside: every 1 percentage point gain in ready-mix penetration adds roughly 1,800-2,200 tonnes of annual admixture demand.
Cost exposure: a 5% rupiah depreciation against the US dollar raises blended admixture production cost by approximately 2-3%.
Substitution risk: polymer alternatives such as modified lignosulfonates can displace up to 8% of PCE volume in non-structural applications.
Regulatory movement matters less for headline demand than for product mix. Mandatory SNI certification on select construction chemicals lengthens approval timelines by 3-6 months but favors established suppliers with testing infrastructure, effectively raising the compliance floor for small blenders.
Competitive Ecosystem & Key Vendor Profiles: Indonesia Concrete Admixtures Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Sika AG
PCE superplasticizer portfolio, global technical service
Ready-mix producers, EPC contractors
Leader
MBCC Group
Admixture systems integrated with repair and waterproofing
Infrastructure and commercial contractors
Leader
MAPEI S.p.A.
Broad construction chemical range, distributor depth
Commercial builders, applicators
Challenger
Fosroc Inc
Admixtures plus concrete repair for infrastructure
Infrastructure contractors
Challenger
Saint-Gobain
GCP admixture technology and cement additive IP
Large ready-mix groups
Challenger
RPM International Inc
Specialty admixtures and surface treatments
Industrial flooring, precast
Challenger
Kao Corporation
Surfactant and PCE polymer chemistry capability
Formulators, licensed producers
Niche
Cementaid International Group
Durability and waterproofing formulations
Marine and water infrastructure
Niche
PT Grolen New Building Material Indonesia
Local production, same-day Java delivery
Regional ready-mix plants
Niche
PT Kimia Konstruksi Indonesia
Cost-competitive blends, local technical support
Residential and mid-tier commercial
Niche
Sika AG: operates the widest admixture portfolio in the region and used the MBCC transaction to consolidate master builder technology across ready-mix and precast accounts.
MBCC Group: retains strong specification influence in infrastructure, with admixture systems bundled into repair, grouting, and waterproofing packages.
MAPEI S.p.A.: leverages an extensive distributor network to reach commercial applicators, and its Indonesia Construction Chemicals Market presence extends into tile adhesives and flooring.
Fosroc Inc: positions admixtures alongside concrete repair and protective coatings, targeting toll road and port rehabilitation programs.
Saint-Gobain: absorbed GCP Applied Technologies to combine admixture chemistry with the Indonesia Cement Additives Market portfolio, creating a dual-channel offer to cement producers and batching plants.
RPM International Inc: through Euclid Chemical, focuses on specialty admixtures and surface treatments for industrial flooring and precast operations.
Kao Corporation: supplies surfactant and polymer chemistry to formulators rather than competing directly at the jobsite.
Cementaid International Group: differentiates on durability and waterproofing formulations for marine and water-retaining structures.
PT Grolen New Building Material Indonesia: competes on local production economics and same-day delivery inside Java.
PT Kimia Konstruksi Indonesia: serves price-sensitive residential and mid-tier commercial accounts with locally blended products.
Strategic Milestones & Recent Developments in Indonesia Concrete Admixtures Market
Latest Strategic Moves
Date
Company
Event Type
Impact
May 2023
Sika AG
M&A
Acquired MBCC Group, excluding admixture operations in Europe, North America, Australia, and New Zealand; expanded admixture and waterproofing capability
September 2022
Saint-Gobain
M&A
Acquired GCP Applied Technologies, adding cement additive and admixture technology to a single platform
February 2022
RPM International Inc
Launch
Euclid Chemical introduced EUCON ECO-STRENGTH, EUCON AM-10L, and EUCOSHIELD
Chronological Detail
February 2022: RPM International's Euclid Chemical unit released three admixtures aimed at sustainability and low-temperature performance, signalling a shift toward bio-based and lower-carbon formulations that Indonesian specifiers now request.
September 2022: Saint-Gobain completed the acquisition of GCP Applied Technologies, creating a combined platform spanning cement additives, concrete admixtures, and building materials. The transaction increased competitive pressure on regional formulators lacking comparable research budgets.
May 2023: Sika AG acquired MBCC Group, carving out European, North American, Australian, and New Zealand admixture operations to satisfy competition authorities. The resulting entity holds broader formulation IP and service coverage relevant to Indonesian infrastructure accounts.
These moves accelerated supplier consolidation, and the top five vendors now influence an estimated 60-65% of specification decisions at tier-1 ready-mix producers.
Regional Market Analysis & Growth Corridors for Indonesia Concrete Admixtures Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (USD million)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
6.9%
1,020
Nusantara and ASEAN infrastructure pipelines
Moderate-High (SNI, EN 934 adoption)
North America
4.2%
395
Repair and rehabilitation of aging structures
High (ASTM C494, ACI 318)
Europe
4.6%
372
Decarbonization and low-clinker cement use
Very High (EN 934 series)
LAMEA
5.8%
268
Port, energy, and urban housing projects
Moderate
Indonesia (country focus)
6.57%
144.40
Infrastructure spending and ready-mix conversion
Moderate (SNI certification)
Fastest-Growing versus Most Mature Markets
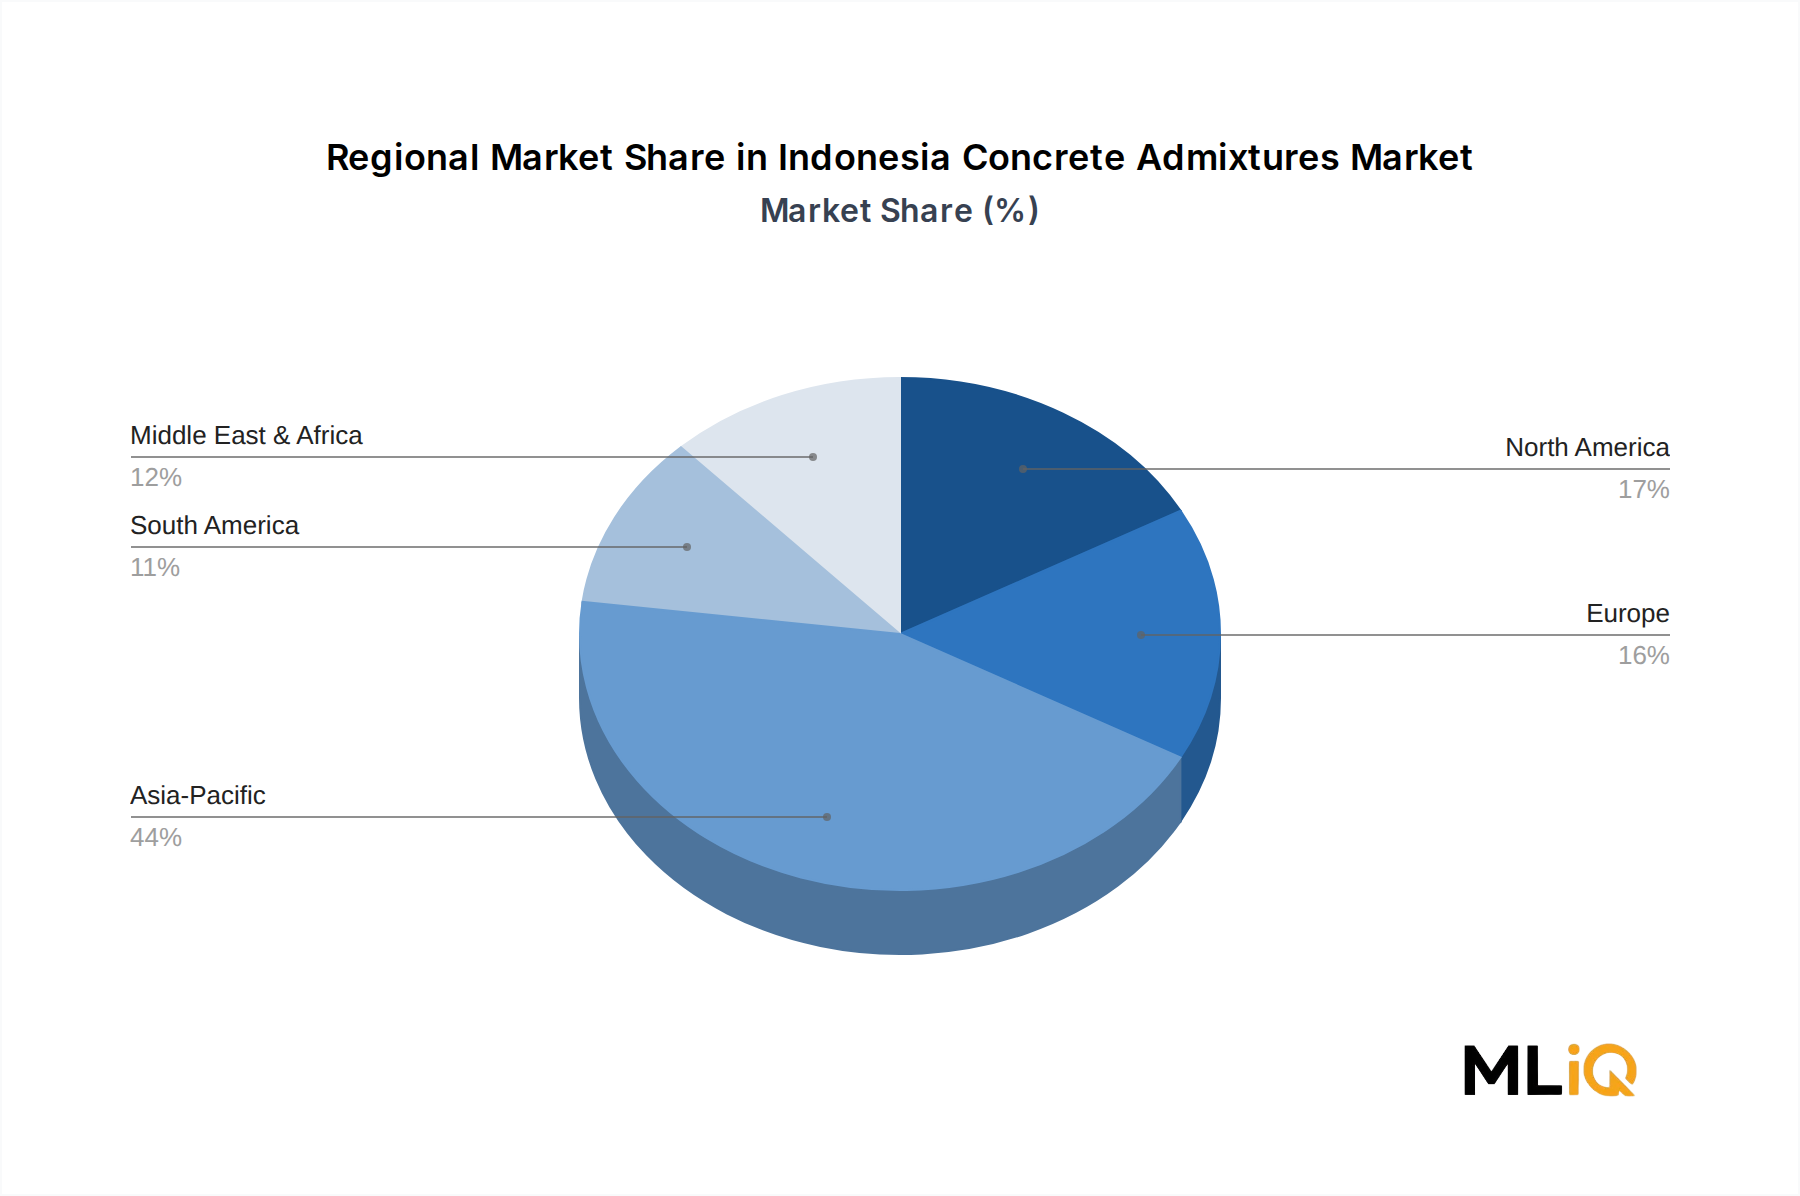
Asia-Pacific is the volume engine, holding roughly 44% of global admixture consumption, with Indonesia contributing around 9% of that regional total.
North America and Europe are mature, growing at 4.2% and 4.6% respectively, where demand is dominated by repair, rehabilitation, and low-carbon binder compatibility rather than new-build volume.
LAMEA shows mid-single-digit expansion tied to port, energy, and housing pipelines, but currency and payment risk reduce supplier appetite.
Indonesia's growth corridor runs from Java's industrial estates to Sumatra and Kalimantan resource-linked projects, where logistics cost adds 8-12% to delivered admixture price.
Supplier strategy differs by region: European vendors compete on regulatory compliance and carbon accounting, while Indonesian buyers weight delivery reliability and dosing support more heavily than documentation depth.
Export, Cross-Border Trade & Tariff Impact on Indonesia Concrete Admixtures Market
Trade Corridor Map
Corridor
Direction
Key Product
Volume/Value Indicator
China to Indonesia
Import
PCE powder and liquid resin
~38% of imported admixture inputs
Japan and South Korea to Indonesia
Import
High-performance PCE, specialty polymers
~14%
Indonesia to ASEAN (Malaysia, Philippines, Vietnam)
Export
Blended admixtures, waterproofing integrators
USD 18-22 million annually
Europe to Indonesia
Import
Specialty retarders, shrinkage reducers
~9%
Middle East to Indonesia
Import
SNF-based plasticizers
~7%
Tariff exposure is limited: most admixture formulations enter under HS 3824.40 at 0-5% most-favored-nation duty, and intra-ASEAN shipments move at zero duty under the ASEAN Trade in Goods Agreement. Non-tariff measures matter more, including import licensing and mandatory SNI certification on selected construction chemicals, which adds 3-6 months to market entry.
Local content rules for public projects, typically requiring 25-40% domestic content, push foreign suppliers toward local blending partnerships rather than finished-product imports. Demand for lower-carbon formulations also links the sector to the Indonesia Green Construction Materials Market, where admixture suppliers position water reduction as a direct route to cement savings of 8-15% per cubic meter.
Customer Segmentation & Buying Behavior in Indonesia Concrete Admixtures Market
Buyer Segments and Procurement Patterns
Buyer Segment
Procurement Channel
Primary Decision Criteria
Price Elasticity
Tier-1 ready-mix producers
Direct supply contracts
Dose efficiency, slump retention, technical service
Low-Medium
Regional batching plants
Distributors and traders
Unit price, credit terms, delivery speed
High
Precast fabricators
Direct plus technical trials
Cycle-time reduction, surface finish
Medium
Infrastructure EPC contractors
Specification-driven
Compliance with project BOQ and durability targets
Low
Shifts in Buyer Expectations
Tier-1 producers now run formal trial batching over 12-24 months before approving a new admixture, and they demand dosage optimization data rather than generic product literature. Regional plants, by contrast, buy on landed price and consignment terms, and switch suppliers when the price gap exceeds 6-8%.
Digital purchasing is rising fastest among mid-tier buyers, with roughly 30% of repeat orders now placed through WhatsApp-based sales channels and distributor portals.
Technical service expectations have shifted from product supply to on-site slump adjustment, with suppliers absorbing up to 2-3 site visits per month per major account.
Payment behavior remains a friction point: average receivables run 75-100 days for ready-mix accounts and 120 days for public sector contractors.
Price elasticity is sharply segmented. Infrastructure accounts are largely inelastic because admixture represents under 3% of total concrete cost, while residential pours, where margins are thin, see volume substitution toward lower-cost plasticizers when prices move upward.
Methodology
Primary Research
Primary research accounts for 70-80% of total effort, with 20-30% from secondary sources.
Interviewed concrete admixture formulators and blending plant operators supplying ready-mix and precast customers across Java, Sumatra, and Kalimantan.
Interviewed polycarboxylate ether and lignosulfonate raw material suppliers and importers handling feedstock from China, Japan, and South Korea.
Interviewed ready-mix concrete batching plant owners and operations managers, covering dosage practices, approval cycles, and supplier switching behavior.
Interviewed infrastructure EPC contractors and precast fabricators, capturing specification criteria for toll roads, ports, dams, and the Nusantara capital program.
Interviewed construction chemical distributors and traders serving tier-2 and tier-3 cities, capturing pricing and credit dynamics.
Stakeholder job titles targeted: Concrete Admixture Product Manager, Ready-Mix Procurement Director, Concrete Technical Service Engineer, and Infrastructure Project Materials Manager.
Government sources include Indonesia's Ministry of Public Works and Housing portals and national statistics releases on construction output and cement consumption.
Trade and association data drawn from cement and ready-mix producer associations, plus customs records on HS 3824.40 shipments.
Regulatory texts reviewed include SNI cement and concrete standards, EN 934 series requirements, and ASEAN Trade in Goods Agreement tariff schedules.
All secondary figures are reconciled against primary interview ranges and flagged where variance exceeds 5%.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies applied simultaneously, validated through multi-level data triangulation across product, end-use, and channel dimensions.
Bottom-up variables include: tonnes of ready-mix concrete produced annually in Indonesia, average admixture dosage in kg per cubic meter by end-use sector, number of active batching plants by province, and average delivered admixture price per tonne by product family.
Product-level build modeled across eight sub-product categories and four end-use sectors to produce base-year value of USD 144.40 million.
Volume-to-value conversion applied using import parity pricing adjusted for duty, freight, and distributor margin.
Forecast horizon 2025-2033 uses a 6.57% CAGR derived from construction output growth, ready-mix penetration curve, and per-cubic-meter dosing trends.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, maintained through iterative validation rounds.
Every quantitative claim is traced to at least two independent sources or primary interviews before inclusion.
Outlier responses are re-contacted and excluded if unsupported by cross-verification.
Segment shares are normalized so that product and end-use breakdowns each sum to 100%.
Every report is updated to the date of purchase, with revisions logged and dated in the delivery file.
Indonesia Concrete Admixtures Market Segmentation
1. End Use Sector
1.1. Commercial
1.2. Industrial and Institutional
1.3. Infrastructure
1.4. Residential
2. Sub Product
2.1. Accelerator
2.2. Air Entraining Admixture
2.3. High Range Water Reducer (Super Plasticizer)
2.4. Retarder
2.5. Shrinkage Reducing Admixture
2.6. Viscosity Modifier
2.7. Water Reducer (Plasticizer)
2.8. Other Types
Indonesia Concrete Admixtures Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Indonesia Concrete Admixtures Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.57% from 2020-2034
Segmentation
By End Use Sector
Commercial
Industrial and Institutional
Infrastructure
Residential
By Sub Product
Accelerator
Air Entraining Admixture
High Range Water Reducer (Super Plasticizer)
Retarder
Shrinkage Reducing Admixture
Viscosity Modifier
Water Reducer (Plasticizer)
Other Types
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End Use Sector
5.1.1. Commercial
5.1.2. Industrial and Institutional
5.1.3. Infrastructure
5.1.4. Residential
5.2. Market Analysis, Insights and Forecast - by Sub Product
5.2.1. Accelerator
5.2.2. Air Entraining Admixture
5.2.3. High Range Water Reducer (Super Plasticizer)
5.2.4. Retarder
5.2.5. Shrinkage Reducing Admixture
5.2.6. Viscosity Modifier
5.2.7. Water Reducer (Plasticizer)
5.2.8. Other Types
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End Use Sector
6.1.1. Commercial
6.1.2. Industrial and Institutional
6.1.3. Infrastructure
6.1.4. Residential
6.2. Market Analysis, Insights and Forecast - by Sub Product
6.2.1. Accelerator
6.2.2. Air Entraining Admixture
6.2.3. High Range Water Reducer (Super Plasticizer)
6.2.4. Retarder
6.2.5. Shrinkage Reducing Admixture
6.2.6. Viscosity Modifier
6.2.7. Water Reducer (Plasticizer)
6.2.8. Other Types
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End Use Sector
7.1.1. Commercial
7.1.2. Industrial and Institutional
7.1.3. Infrastructure
7.1.4. Residential
7.2. Market Analysis, Insights and Forecast - by Sub Product
7.2.1. Accelerator
7.2.2. Air Entraining Admixture
7.2.3. High Range Water Reducer (Super Plasticizer)
7.2.4. Retarder
7.2.5. Shrinkage Reducing Admixture
7.2.6. Viscosity Modifier
7.2.7. Water Reducer (Plasticizer)
7.2.8. Other Types
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End Use Sector
8.1.1. Commercial
8.1.2. Industrial and Institutional
8.1.3. Infrastructure
8.1.4. Residential
8.2. Market Analysis, Insights and Forecast - by Sub Product
8.2.1. Accelerator
8.2.2. Air Entraining Admixture
8.2.3. High Range Water Reducer (Super Plasticizer)
8.2.4. Retarder
8.2.5. Shrinkage Reducing Admixture
8.2.6. Viscosity Modifier
8.2.7. Water Reducer (Plasticizer)
8.2.8. Other Types
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End Use Sector
9.1.1. Commercial
9.1.2. Industrial and Institutional
9.1.3. Infrastructure
9.1.4. Residential
9.2. Market Analysis, Insights and Forecast - by Sub Product
9.2.1. Accelerator
9.2.2. Air Entraining Admixture
9.2.3. High Range Water Reducer (Super Plasticizer)
9.2.4. Retarder
9.2.5. Shrinkage Reducing Admixture
9.2.6. Viscosity Modifier
9.2.7. Water Reducer (Plasticizer)
9.2.8. Other Types
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End Use Sector
10.1.1. Commercial
10.1.2. Industrial and Institutional
10.1.3. Infrastructure
10.1.4. Residential
10.2. Market Analysis, Insights and Forecast - by Sub Product
10.2.1. Accelerator
10.2.2. Air Entraining Admixture
10.2.3. High Range Water Reducer (Super Plasticizer)
10.2.4. Retarder
10.2.5. Shrinkage Reducing Admixture
10.2.6. Viscosity Modifier
10.2.7. Water Reducer (Plasticizer)
10.2.8. Other Types
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Cementaid International Group of Companies
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Fosroc Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Kao Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. MAPEI S p A
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. MBCC Group
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. PT Grolen New Building Material Indonesia
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. PT Kimia Konstruksi Indonesia
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. RPM International Inc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Saint-Gobain
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Sika A
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Indonesia Concrete Admixtures Market Revenue Breakdown (million, %) by Product 2026 & 2034
Figure 2: Indonesia Concrete Admixtures Market Value Share (%), by End Use Sector 2026 & 2034
Figure 3: Indonesia Concrete Admixtures Market Value Share (%), by Sub Product 2026 & 2034
Figure 4: Indonesia Concrete Admixtures Market Share (%) by Company 2026
List of Tables
Table 1: Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 2: Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 3: Indonesia Concrete Admixtures Market Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 5: North America Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 6: North America Indonesia Concrete Admixtures Market Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 11: South America Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 12: South America Indonesia Concrete Admixtures Market Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 17: Europe Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 18: Europe Indonesia Concrete Admixtures Market Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 29: Middle East & Africa Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 30: Middle East & Africa Indonesia Concrete Admixtures Market Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Indonesia Concrete Admixtures Market Revenue million Forecast, by End Use Sector 2020 & 2034
Table 38: Asia Pacific Indonesia Concrete Admixtures Market Revenue million Forecast, by Sub Product 2020 & 2034
Table 39: Asia Pacific Indonesia Concrete Admixtures Market Revenue million Forecast, by Country 2020 & 2034
Table 40: China Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Indonesia Concrete Admixtures Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total effort, with 20-30% from secondary sources.
Interviewed concrete admixture formulators and blending plant operators supplying ready-mix and precast customers across Java, Sumatra, and Kalimantan.
Interviewed polycarboxylate ether and lignosulfonate raw material suppliers and importers handling feedstock from China, Japan, and South Korea.
Interviewed ready-mix concrete batching plant owners and operations managers, covering dosage practices, approval cycles, and supplier switching behavior.
Interviewed infrastructure EPC contractors and precast fabricators, capturing specification criteria for toll roads, ports, dams, and the Nusantara capital program.
Interviewed construction chemical distributors and traders serving tier-2 and tier-3 cities, capturing pricing and credit dynamics.
Stakeholder job titles targeted: Concrete Admixture Product Manager, Ready-Mix Procurement Director, Concrete Technical Service Engineer, and Infrastructure Project Materials Manager.
Government sources include Indonesia's Ministry of Public Works and Housing portals and national statistics releases on construction output and cement consumption.
Trade and association data drawn from cement and ready-mix producer associations, plus customs records on HS 3824.40 shipments.
Regulatory texts reviewed include SNI cement and concrete standards, EN 934 series requirements, and ASEAN Trade in Goods Agreement tariff schedules.
All secondary figures are reconciled against primary interview ranges and flagged where variance exceeds 5%.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies applied simultaneously, validated through multi-level data triangulation across product, end-use, and channel dimensions.
Bottom-up variables include: tonnes of ready-mix concrete produced annually in Indonesia, average admixture dosage in kg per cubic meter by end-use sector, number of active batching plants by province, and average delivered admixture price per tonne by product family.
Product-level build modeled across eight sub-product categories and four end-use sectors to produce base-year value of USD 144.40 million.
Volume-to-value conversion applied using import parity pricing adjusted for duty, freight, and distributor margin.
Forecast horizon 2025-2033 uses a 6.57% CAGR derived from construction output growth, ready-mix penetration curve, and per-cubic-meter dosing trends.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, maintained through iterative validation rounds.
Every quantitative claim is traced to at least two independent sources or primary interviews before inclusion.
Outlier responses are re-contacted and excluded if unsupported by cross-verification.
Segment shares are normalized so that product and end-use breakdowns each sum to 100%.
Every report is updated to the date of purchase, with revisions logged and dated in the delivery file.
Frequently Asked Questions
1. Which region dominates the Indonesia Concrete Admixtures Market and why?
Asia-Pacific is the dominant producing and consuming region, accounting for roughly 44% of global admixture demand, and Indonesia alone represents about 9% of that regional volume. The leadership rests on large domestic ready-mix capacity, the USD 33 billion Nusantara capital program, and low-cost access to polycarboxylate ether feedstock from China, Japan, and South Korea. Domestic formulators also benefit from shorter freight distances than European or North American suppliers.
2. What are the main barriers to entry for new admixture suppliers in Indonesia?
Technical qualification is the first barrier: batching plants require trial batching and performance data across 12 to 24 months before approving a new admixture brand. Distribution reach is the second, since the top five suppliers control an estimated 60-65% of specification influence among tier-1 ready-mix producers. Access to stable PCE resin supply and the working capital to hold inventory during rupiah volatility further limit new entrants.
3. How do import and export flows shape the Indonesia Concrete Admixtures Market?
Indonesia imports an estimated 55-60% of its polycarboxylate ether feedstock, with China supplying about 38% of imported admixture inputs and Japan and South Korea adding approximately 14%. Outbound shipments of blended admixtures to Malaysia, the Philippines, and Vietnam are valued at roughly USD 18-22 million annually. Tariffs are minimal at 0-5% under HS 3824.40, and ASEAN Trade in Goods Agreement rules allow zero-duty intra-regional movement.
4. Which product segments generate the most revenue?
High Range Water Reducer (Super Plasticizer) is the largest product segment at 36% of value and an estimated USD 52 million in 2025, growing at 7.4% annually. Water Reducer (Plasticizer) follows at 18% share, while Accelerator and Retarder together account for 20%. Shrinkage Reducing Admixture is the fastest-growing smaller category at 7.0% CAGR, driven by industrial flooring and slab crack-control specifications.
5. What are the primary growth drivers and demand catalysts?
Infrastructure construction drives 38% of admixture volume, supported by the Nusantara capital project, Trans-Sumatra toll roads, and hydropower dams. Rising ready-mix penetration, moving from 42% toward an estimated 58% of concrete volume by 2030, adds admixture consumption per cubic meter. A residential housing backlog of 9.9 million units and tighter SNI cement standards reinforce the 6.57% CAGR through 2033.
6. How much investment activity and consolidation is occurring in this sector?
Sika AG acquired MBCC Group in May 2023, excluding certain regional admixture operations, while Saint-Gobain purchased GCP Applied Technologies in September 2022, concentrating technical capability among fewer global players. Direct venture capital activity in Indonesian admixture formulation remains limited, with most funding flowing into ready-mix plant capacity and construction chemical distribution. Local formulators such as PT Kimia Konstruksi Indonesia typically expand through retained earnings rather than equity rounds.