Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Crystalline PET Market: 8.6% CAGR Outlook to 2033
Crystalline Polyethylene Terephthalate Market
Crystalline PET Market: 8.6% CAGR Outlook to 2033
Crystalline Polyethylene Terephthalate Market by Manufacturing Process (Extrusion Process, Molding Process), by Application (Trays, Cups, Films/Sheets, Bottles, Others), by End user industry (Food Beverage, Pharmaceutical, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
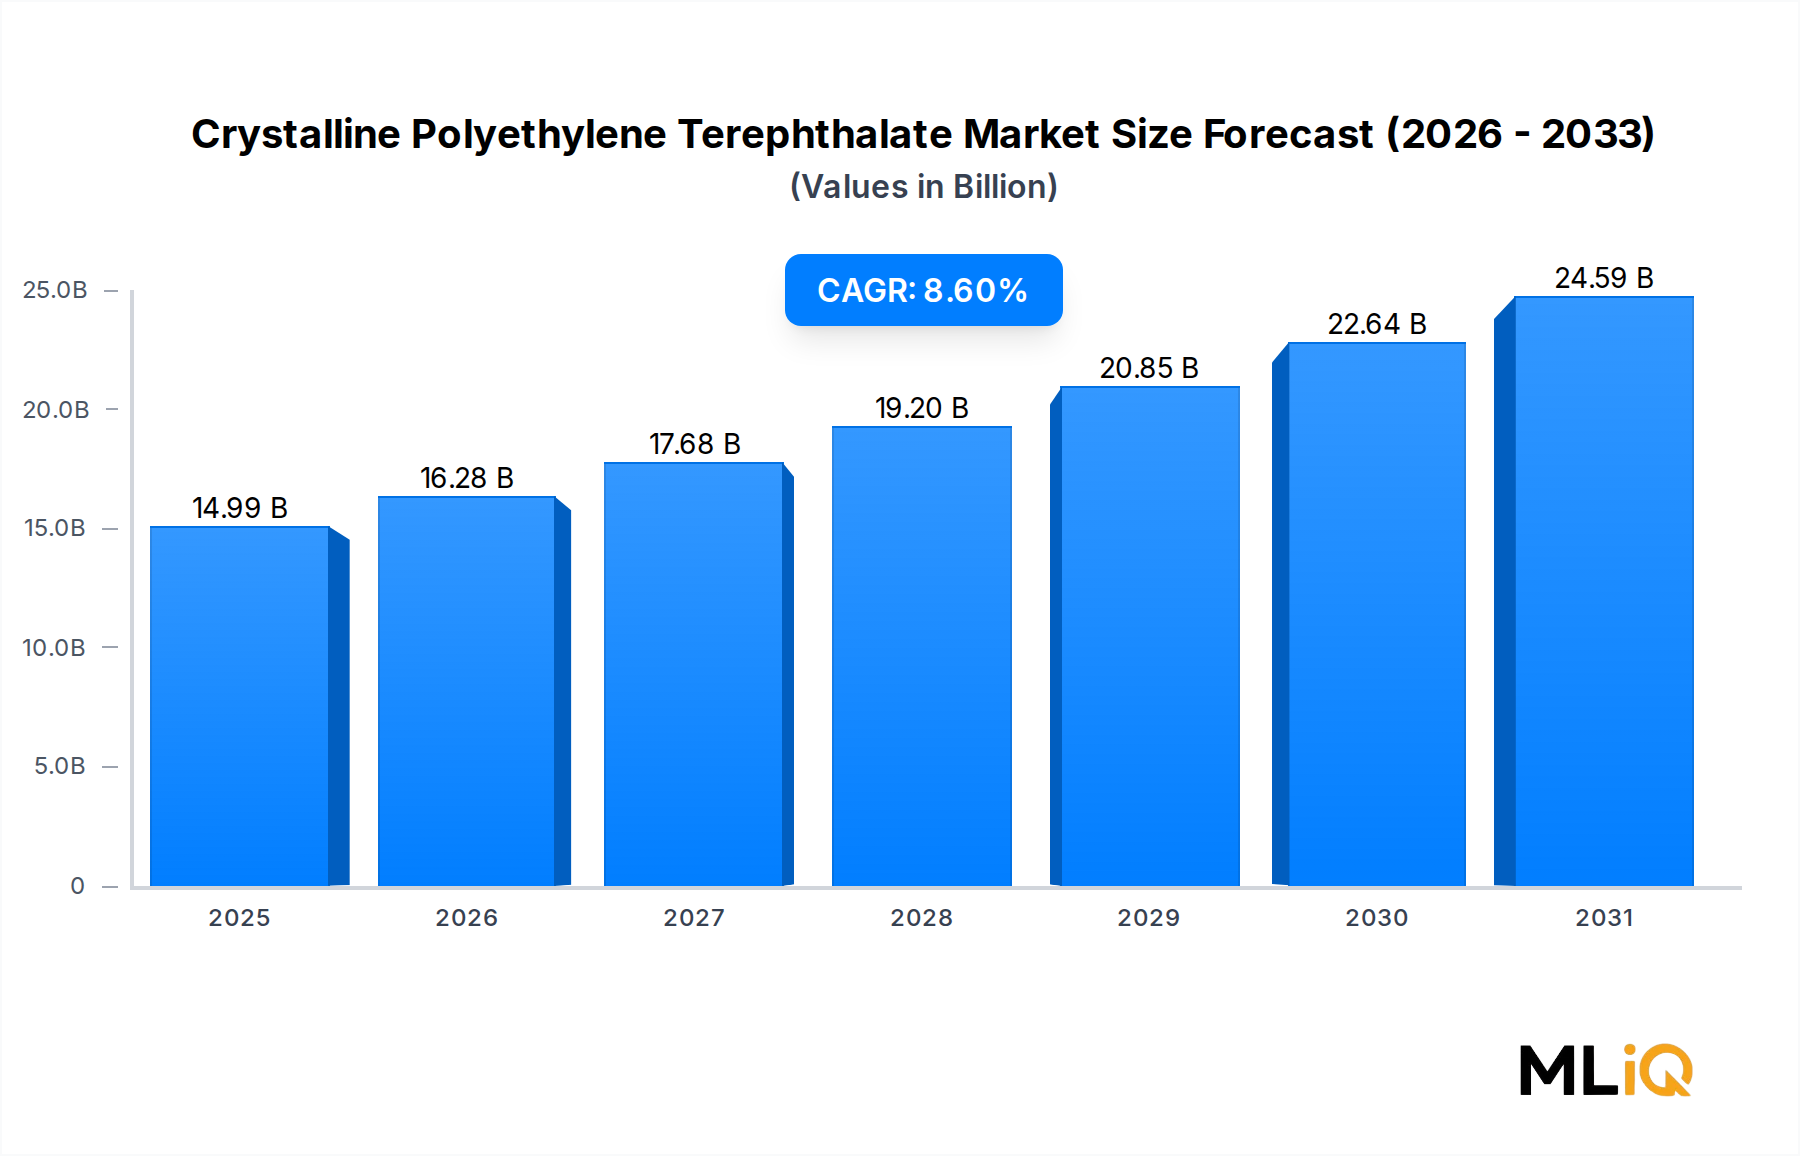
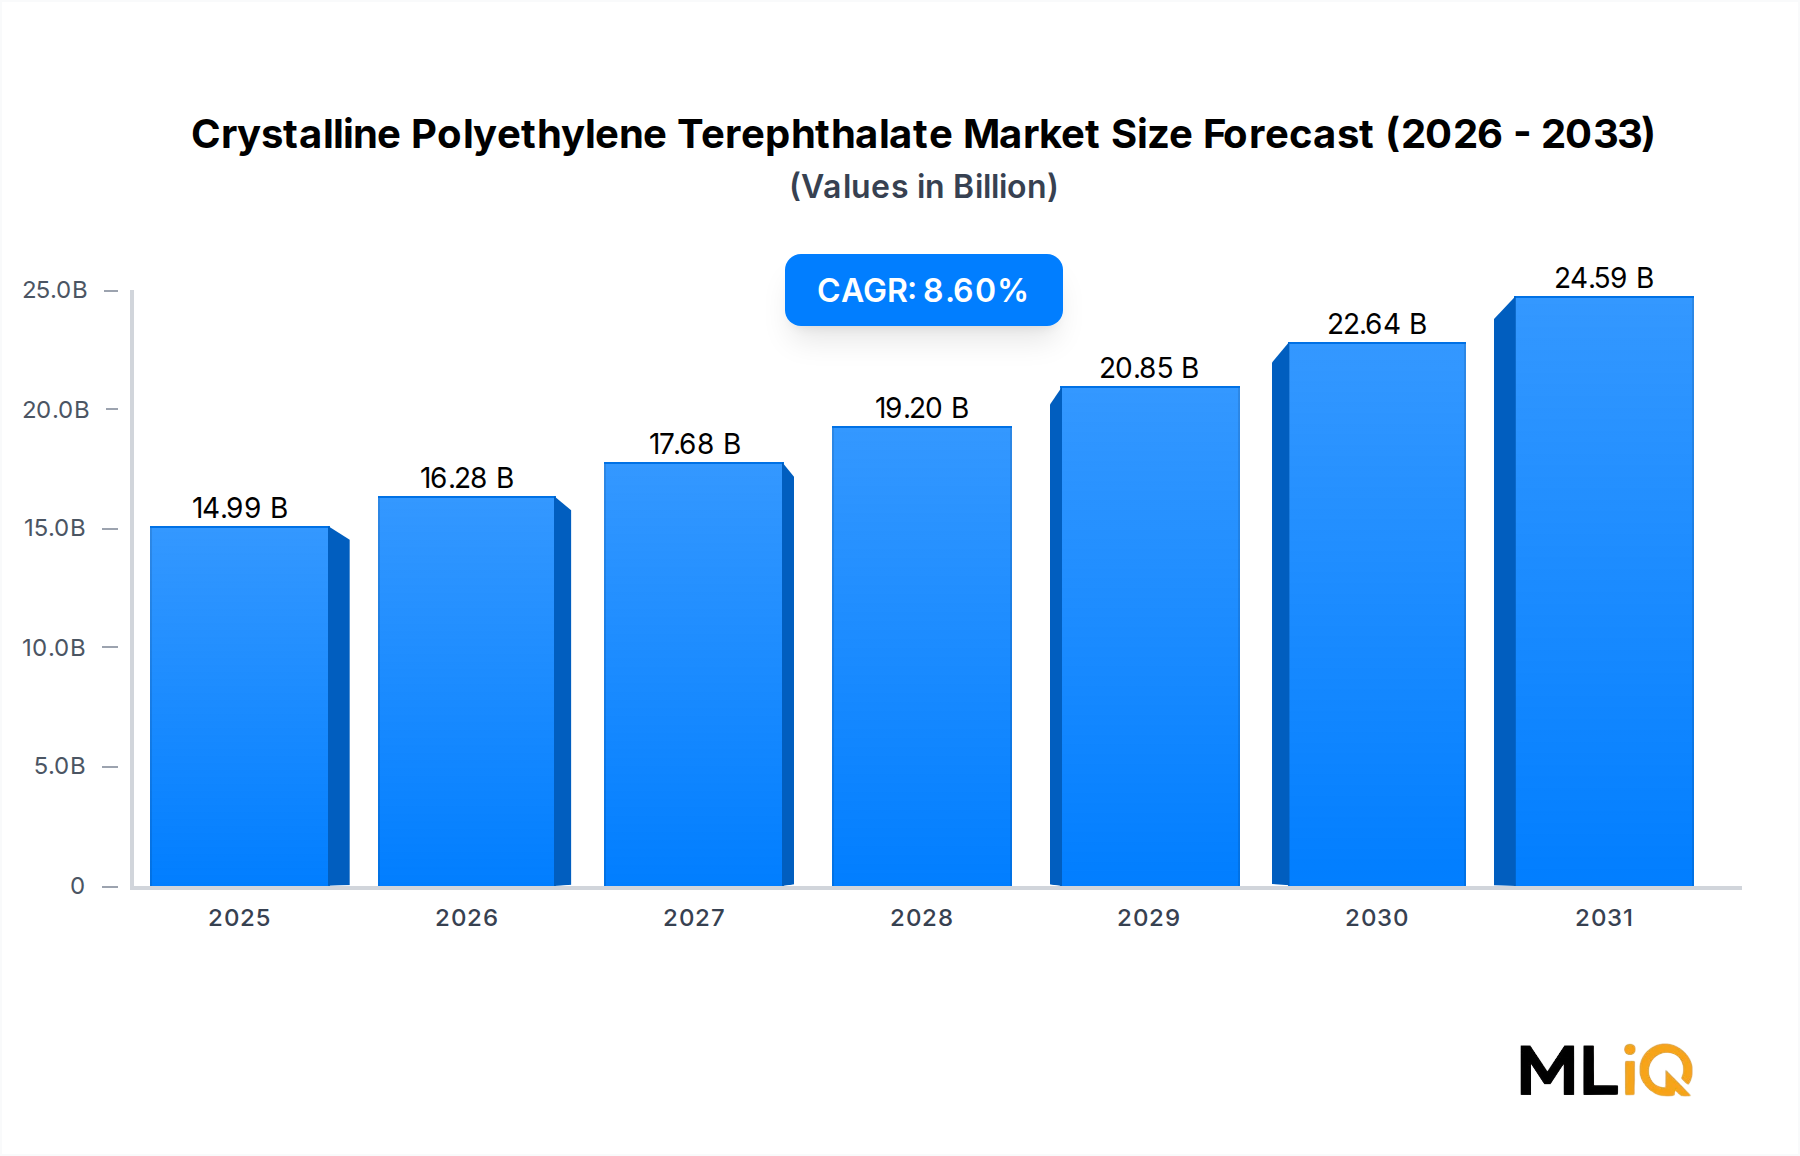
The Crystalline Polyethylene Terephthalate Market closed 2024 at USD 13.8 billion and compounds at 8.6% through 2033, adding roughly USD 15.3 billion of incremental annual value. Crystallized grades, produced through controlled cooling and solid-state polycondensation, hold a heat-resistance advantage over amorphous PET, which explains why demand concentrates in rigid, thermally stressed packaging rather than commodity fiber.
Crystalline Polyethylene Terephthalate Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
14.99 B
2025
16.28 B
2026
17.68 B
2027
19.20 B
2028
20.85 B
2029
22.64 B
2030
24.59 B
2031
Three structural forces set the tone:
Capacity migration eastward. China, India, and ASEAN host more than half of global polymerization capacity, and new bottle-grade lines averaged USD 1,180-1,260/tonne cash cost in 2024, below European and North American equivalents.
Mandated recycled content. EU rules set binding recycled-content targets for PET beverage bottles, with a 25% threshold from 2025 and 30% by 2030, pulling food-grade rPET into the specification of the broader Polyethylene Terephthalate Market.
Substitution pressure at the low end. Aluminum cans and fiber-based formats continue to erode thin-wall single-serve cup volumes in North America and Western Europe.
Downstream, the food and beverage channel absorbs an estimated 70-74% of crystallized PET output, followed by pharmaceutical and medical packaging at 9-11%. Pricing power is uneven: resin producers operate on 8-14% gross spreads when PTA and MEG are volatile, while converters with proprietary thermoforming tooling sustain 18-24% margins.
Key takeaway: volume growth remains robust, but value growth depends on how quickly producers shift mix toward food-grade rPET, high-heat CPET trays, and thin-wall barrier bottles. Suppliers that lag on recyclability certification face share loss in Europe first, then North America.
Segment Deep-Dive: Bottles Dominance in Crystalline Polyethylene Terephthalate Market
Dual-ovenable ready-meal trays and institutional food service
Trays
7.4%
~14%
Airline catering and frozen-food retail formats
Cups
6.9%
~11%
Foodservice coffee and dairy cups; fiber substitution
Others (strapping, thermoformed parts)
7.8%
~8%
Industrial strapping and electronics carrier tape
Why Bottles Lead
Bottle production consumes the largest share of PET Bottle Grade Resin Market volumes because beverage filling lines require high intrinsic viscosity (0.78-0.84 dL/g) resin that resists CO2 permeation and drop impact. Global beverage bottle shipments grew 3.6% in 2024, and the crystallized and high-IV sub-segment grew faster than the container total because premium and hot-fill SKUs migrate away from amorphous grades.
Highest barrier to entry: food-contact rPET approval requires EFSA or FDA letter-of-no-objection validation.
Highest recycling pull: bottle-to-bottle loops are the only PET stream with mature collection infrastructure.
Highest price ceiling: food-grade rPET pellets traded at a USD 180-240/tonne premium to virgin bottle-grade resin in Europe through 2024.
Films/Sheets and CPET Trays
Crystallized PET sheet, known as CPET, is the fastest-growing non-bottle application in the Crystalline PET Resin Market. Dual-ovenable trays withstand 200-220C for up to 45 minutes, a performance envelope fiber and PP alternatives only partially match.
Airline and institutional catering contracts convert at 4-6% annual volume growth.
Converter margins are structurally higher than resin margins because tooling and print capability are not commoditized.
Margin pressure comes from PP-based trays, which are 10-15% cheaper per unit at equivalent gauge.
Margin Dynamics
Integrated producers (PTA-to-PET) capture USD 120-160/tonne more spread than non-integrated peers during feedstock spikes.
Non-integrated converters absorb volatility and pass through with a 30-60 day lag.
Energy cost per tonne of PET is roughly USD 55-75, making European producers sensitive to gas prices.
Takeaway: bottles and CPET sheet together represent about two-thirds of revenue, and both are being reshaped by recycled-content regulation rather than by raw demand growth alone.
Shift from glass to PET in emerging-market beverage bottling
Medium
Short-Long term
Restraint
Volatile PTA and MEG feedstock pricing compressing converter margins
High
Short term
Restraint
Fiber-based and aluminum substitution in cups and single-serve formats
Medium
Long term
Restraint
Limited food-grade rPET collection capacity outside the EU
High
Short-Medium term
Drivers are demand-pull, not supply-push. Recycled-content law converts an optional sustainability feature into a purchase requirement, and resin buyers now negotiate rPET allocation inside annual contracts rather than on spot terms.
EU bottle collection reached ~63% in 2024, but food-grade reclaim capacity covers only about half of the 2030 obligation.
Pharmaceutical blister and sterile-barrier demand is small in tonnage but carries 2-3x the margin of commodity bottle resin.
Restraints are cost-side and structural. Feedstock volatility pushes working capital requirements up; a USD 90/tonne swing in PTA moves resin cost by roughly 6%. Collection infrastructure, not polymerization capacity, is the true ceiling on recycled supply. Policy risk compounds this: China's recycled plastics import restrictions and India's quality control orders have redirected trade flows and raised landed costs by 4-7% in some destination markets. Net effect: value grows at 8.6% while volume growth of roughly 5.2% trails it, indicating mix enrichment toward higher-specification grades.
Indorama Ventures Public Company Limited: controls the broadest crystallization-grade PET footprint across Asia, Europe, and the Americas, and runs recycled feedstock at multiple sites to serve mandated bottle-to-bottle contracts.
DAK Americas LLC: operates large-scale bottle resin lines in the U.S. Southeast and Mexico; its scale delivers low cash conversion cost during feedstock spikes.
Eastman Chemical Company: differentiates through specialty copolyester and chemical recycling platforms, targeting medical and premium food packaging where regulatory approval carries a moat.
Far Eastern New Century Corporation: vertically integrated from PTA through fiber and resin; strong position in Asian beverage and foodservice channels.
Alpek / Grupo Petrotemex: integrated Mexican producer with a PTA-to-PET chain and cross-border supply into U.S. bottlers.
La Seda de Barcelona: European specialty and recycled PET supplier with a converter-focused service model.
Quadrant, Switzerland: supplies high-performance PET sheet and finished machined components for medical and industrial applications.
Competitive intensity is driven by integration economics rather than branding. The top five suppliers control an estimated 55-60% of global bottle-grade capacity. Takeaway: no supplier can win on price alone once recycled-content compliance enters the contract.
Strategic Milestones & Recent Developments in Crystalline Polyethylene Terephthalate Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024 Q1
Indorama Ventures
Capacity / recycling
Expanded food-grade rPET capacity to serve EU mandates
2024 Q2
Eastman Chemical
Technology launch
Molecular recycling feedstock qualified for food-contact resin
2024 Q3
DAK Americas
Capacity
Bottle-grade line upgrades lifted food-grade output
2024 Q4
Alpek / Grupo Petrotemex
Partnership
Cross-border supply agreements with U.S. bottlers
2025 Q1
Far Eastern New Century
Product launch
Higher-IV resin grade for hot-fill and pressurized formats
2024 Q1 — Indorama Ventures brought additional food-grade recycled PET capacity online, aligning supply with the EU 25% recycled content threshold effective 2025.
2024 Q2 — Eastman Chemical qualified chemically recycled feedstock for food-contact applications, reducing dependence on mechanical reclaim for high-specification grades.
2024 Q3 — DAK Americas completed upgrades raising bottle-grade output; the move targets U.S. state-level recycled-content rules.
2024 Q4 — Alpek's Grupo Petrotemex unit formalized cross-border resin supply agreements covering Mexican production for U.S. bottlers.
2025 Q1 — Far Eastern New Century introduced a higher intrinsic viscosity grade for hot-fill and carbonated formats, competing directly with established European suppliers.
Takeaway: development activity concentrates on recycled feedstock qualification and high-specification resin grades, not on greenfield polymerization capacity.
Bottling capacity and packaging demand in China, India, ASEAN
Medium
Europe
8.1%
2.9
Recycled-content mandates, CPET tray demand
High
North America
7.6%
2.7
State-level rPET rules, foodservice and medical packaging
Medium-High
South America
7.2%
1.0
Brazilian beverage bottling, Mexican export resin
Low-Medium
Middle East & Africa
8.9%
0.7
New bottling lines, low feedstock cost advantage
Low
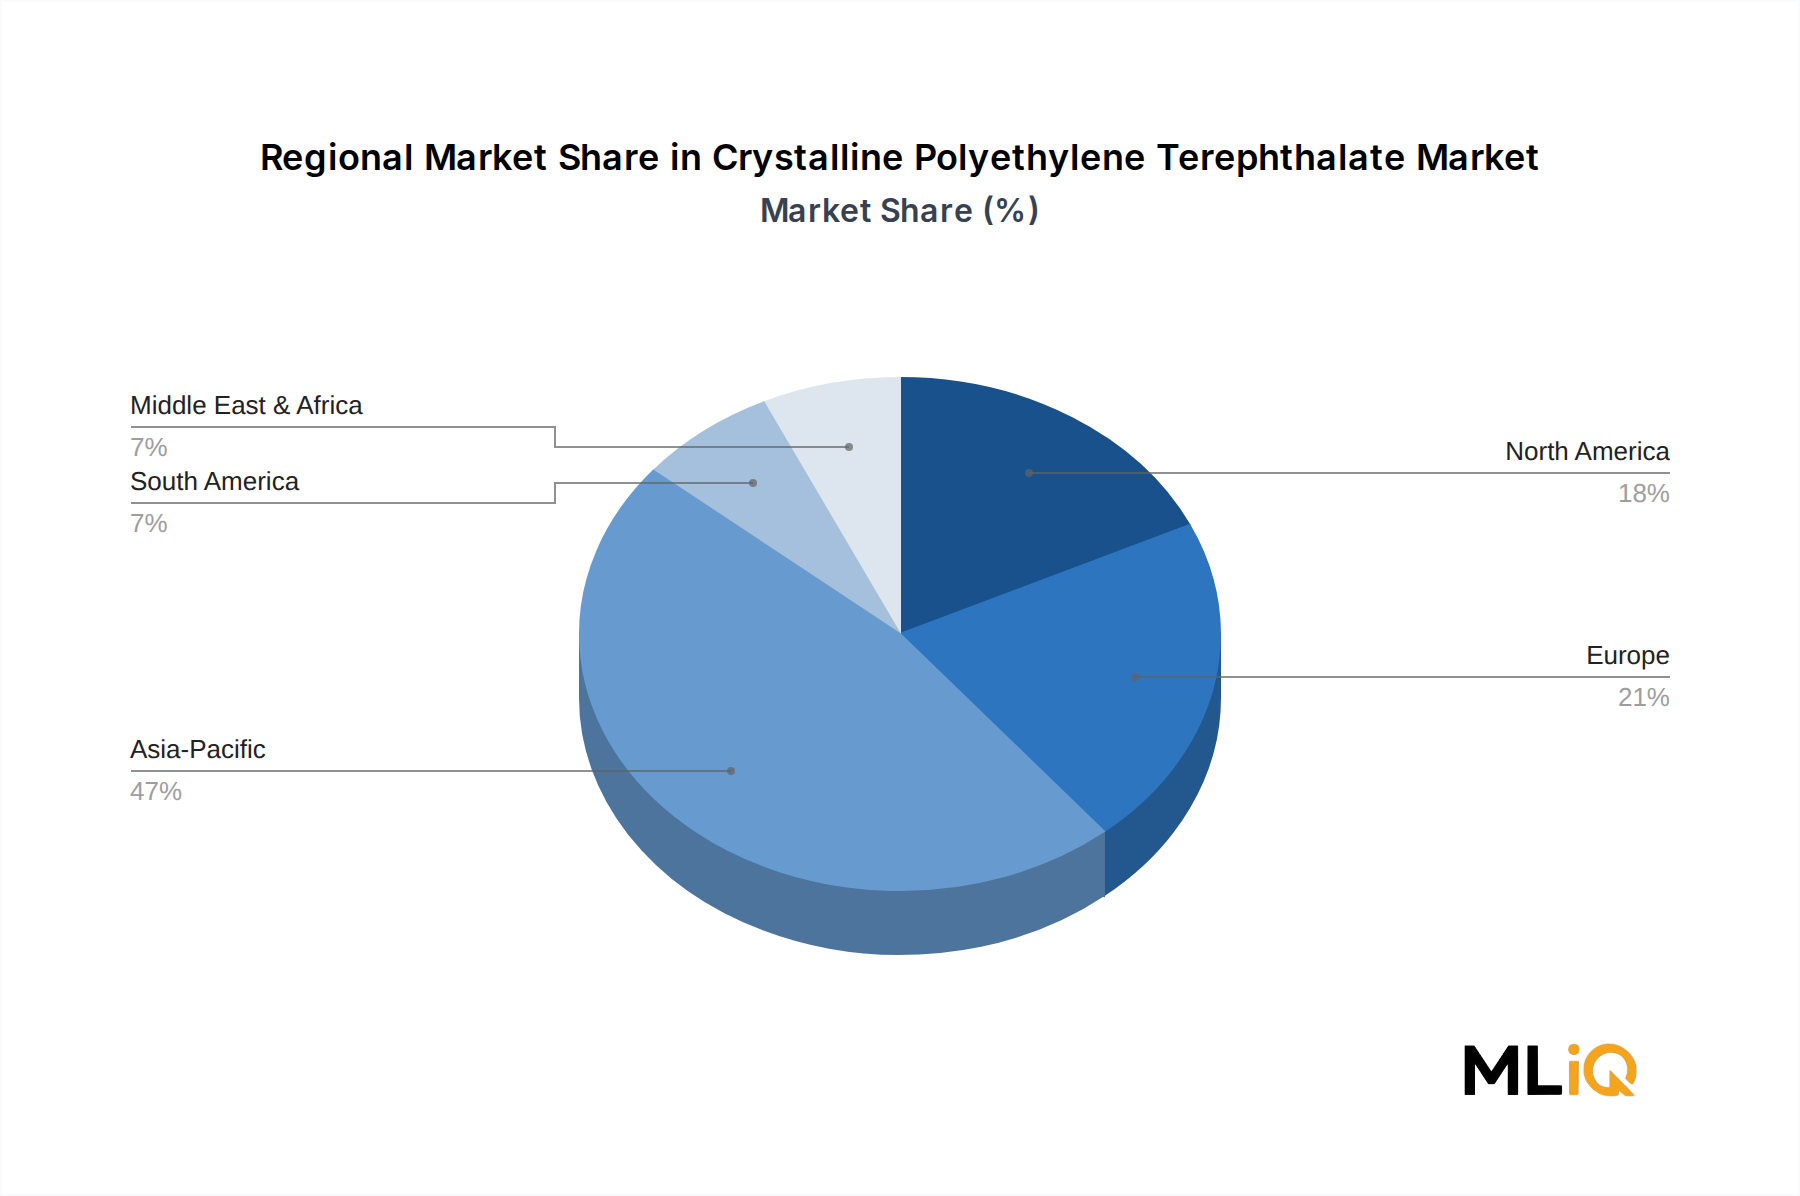
Asia-Pacific is the largest and fastest-growing block. Chinese and Indian polymerization capacity additions keep resin landed cost competitive, and domestic beverage consumption continues to rise.
Europe is the most mature and the most regulation-driven. Recycled-content obligations make the Recycled PET Market a supply-constrained segment rather than a discretionary one.
North America grows steadily, with medical and foodservice demand supporting higher-margin volumes.
LAMEA is small but expanding at 8.9% in the Middle East and Africa, supported by low-cost feedstock and new bottling investment.
Fastest-Growing vs. Most Mature
Fastest: Asia-Pacific at 9.3%, where per-capita packaging consumption still trails Western levels.
Most mature: Europe, where volume growth of 3-4% is offset by price and specification premium.
Watch item: Brazil and Gulf states, where new capacity could shift trade balances by 2027.
Trade flows matter here. China remains the largest net exporter of bottle-grade PET, while the EU and the United States are net importers of finished vessels and net exporters of high-grade recyclate.
Supply Chain & Raw Material Dynamics: Crystalline Polyethylene Terephthalate Market
Crystallized PET is a two-feedstock polymer. The Purified Terephthalic Acid Market supplies the diacid and the Monoethylene Glycol Market supplies the diol; roughly 0.855 tonnes of PET are produced per tonne of PTA consumed in a balanced stoichiometric reaction.
Input
Typical Cost Share of Resin
2024 Price Direction
Supply Risk
PTA
50-58%
Stable to soft
Medium
MEG
18-24%
Volatile upward
Medium-High
Energy / utilities
6-9%
Elevated in Europe
High (regional)
Recycled flake (rPET)
n/a
+8-12% premium
High
PTA capacity additions in China pushed Asian PTA prices lower through 2024, easing integrated producer costs.
MEG tightness around maintenance turnarounds drove USD 60-110/tonne quarterly swings.
Food-grade rPET flake availability is the hard constraint; collection rates, not reclaim technology, limit supply.
Bio-based PET Market volumes remain under 1% of total output; cost parity is not expected before 2030.
Takeaway: integrated, dual-feedstock producers absorb volatility better than single-stream converters, and recycled feedstock is the fastest-appreciating input in the chain.
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Manufacturing Process
5.1.1. Extrusion Process
5.1.2. Molding Process
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Trays
5.2.2. Cups
5.2.3. Films/Sheets
5.2.4. Bottles
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by End user industry
5.3.1. Food Beverage
5.3.2. Pharmaceutical
5.3.3. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Manufacturing Process
6.1.1. Extrusion Process
6.1.2. Molding Process
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Trays
6.2.2. Cups
6.2.3. Films/Sheets
6.2.4. Bottles
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by End user industry
6.3.1. Food Beverage
6.3.2. Pharmaceutical
6.3.3. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Manufacturing Process
7.1.1. Extrusion Process
7.1.2. Molding Process
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Trays
7.2.2. Cups
7.2.3. Films/Sheets
7.2.4. Bottles
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by End user industry
7.3.1. Food Beverage
7.3.2. Pharmaceutical
7.3.3. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Manufacturing Process
8.1.1. Extrusion Process
8.1.2. Molding Process
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Trays
8.2.2. Cups
8.2.3. Films/Sheets
8.2.4. Bottles
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by End user industry
8.3.1. Food Beverage
8.3.2. Pharmaceutical
8.3.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Manufacturing Process
9.1.1. Extrusion Process
9.1.2. Molding Process
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Trays
9.2.2. Cups
9.2.3. Films/Sheets
9.2.4. Bottles
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by End user industry
9.3.1. Food Beverage
9.3.2. Pharmaceutical
9.3.3. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Manufacturing Process
10.1.1. Extrusion Process
10.1.2. Molding Process
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Trays
10.2.2. Cups
10.2.3. Films/Sheets
10.2.4. Bottles
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by End user industry
10.3.1. Food Beverage
10.3.2. Pharmaceutical
10.3.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Eastman Chemical Company (U.S.)9.1.1. Company Overview9.1.2. Key Executives9.1.3. Company Snapshot9.1.4. Operating Business Segments9.1.5. Product Portfolio9.1.6. Business Performance9.1.7. Key Strategic Moves and Developments9.2. Bayer MaterialScience AG (Germany)9.2.1. Company Overview9.2.2. Key Executives9.2.3. Company Snapshot9.2.4. Operating Business Segments9.2.5. Product Portfolio9.2.6. Business Performance9.2.7. Key Strategic Moves and Developments9.3. La Seda De Barcelona (Spain)9.3.1. Company Overview9.3.2. Key Executives9.3.3. Company Snapshot9.3.4. Operating Business Segments9.3.5. Product Portfolio9.3.6. Business Performance9.3.7. Key Strategic Moves and Developments9.4. Petrotemex S.A. De C.V. (Mexico)9.4.1. Company Overview9.4.2. Key Executives9.4.3. Company Snapshot9.4.4. Operating Business Segments9.4.5. Product Portfolio9.4.6. Business Performance9.4.7. Key Strategic Moves and Developments9.5. Quadrant (Switzerland)9.5.1. Company Overview9.5.2. Key Executives9.5.3. Company Snapshot9.5.4. Operating Business Segments9.5.5. Product Portfolio9.5.6. Business Performance9.5.7. Key Strategic Moves and Developments9.6. Indorama Ventures Public Limited Company (Netherlands)9.6.1. Company Overview9.6.2. Key Executives9.6.3. Company Snapshot9.6.4. Operating Business Segments9.6.5. Product Portfolio9.6.6. Business Performance9.6.7. Key Strategic Moves and Developments9.7. DAK Americas LLC (U.S.)9.7.1. Company Overview9.7.2. Key Executives9.7.3. Company Snapshot9.7.4. Operating Business Segments9.7.5. Product Portfolio9.7.6. Business Performance9.7.7. Key Strategic Moves and Developments9.8. Far Eastern New Century Corporation9.8.1. Company Overview9.8.2. Key Executives9.8.3. Company Snapshot9.8.4. Operating Business Segments9.8.5. Product Portfolio9.8.6. Business Performance9.8.7. Key Strategic Moves and Developments9.9. Grupo Petrotemex9.9.1. Company Overview9.9.2. Key Executives9.9.3. Company Snapshot9.9.4. Operating Business Segments9.9.5. Product Portfolio9.9.6. Business Performance9.9.7. Key Strategic Moves and Developments9.10. S. A. De C. V.9.10.1. Company Overview9.10.2. Key Executives9.10.3. Company Snapshot9.10.4. Operating Business Segments9.10.5. Product Portfolio9.10.6. Business Performance9.10.7. Key Strategic Moves and Developments9.11. Indorama Ventures Public Company Limited9.11.1. Company Overview9.11.2. Key Executives9.11.3. Company Snapshot9.11.4. Operating Business Segments9.11.5. Product Portfolio9.11.6. Business Performance9.11.7. Key Strategic Moves and Developments9.12. DAK Americas LLC9.12.1. Company Overview9.12.2. Key Executives9.12.3. Company Snapshot9.12.4. Operating Business Segments9.12.5. Product Portfolio9.12.6. Business Performance9.12.7. Key Strategic Moves and Developments9.13. DowDupont Inc.9.13.1. Company Overview9.13.2. Key Executives9.13.3. Company Snapshot9.13.4. Operating Business Segments9.13.5. Product Portfolio9.13.6. Business Performance9.13.7. Key Strategic Moves and Developments
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Crystalline Polyethylene Terephthalate Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Manufacturing Process 2026 & 2034
Figure 3: North America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 4: North America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Crystalline Polyethylene Terephthalate Market Revenue (billion), by End user industry 2026 & 2034
Figure 7: North America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by End user industry 2026 & 2034
Figure 8: North America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Manufacturing Process 2026 & 2034
Figure 11: South America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 12: South America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Application 2026 & 2034
Figure 13: South America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Application 2026 & 2034
Figure 14: South America Crystalline Polyethylene Terephthalate Market Revenue (billion), by End user industry 2026 & 2034
Figure 15: South America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by End user industry 2026 & 2034
Figure 16: South America Crystalline Polyethylene Terephthalate Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Crystalline Polyethylene Terephthalate Market Revenue (billion), by Manufacturing Process 2026 & 2034
Figure 19: Europe Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 20: Europe Crystalline Polyethylene Terephthalate Market Revenue (billion), by Application 2026 & 2034
Figure 21: Europe Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Crystalline Polyethylene Terephthalate Market Revenue (billion), by End user industry 2026 & 2034
Figure 23: Europe Crystalline Polyethylene Terephthalate Market Revenue Share (%), by End user industry 2026 & 2034
Figure 24: Europe Crystalline Polyethylene Terephthalate Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue (billion), by Manufacturing Process 2026 & 2034
Figure 27: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 28: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue (billion), by Application 2026 & 2034
Figure 29: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue (billion), by End user industry 2026 & 2034
Figure 31: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue Share (%), by End user industry 2026 & 2034
Figure 32: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue (billion), by Manufacturing Process 2026 & 2034
Figure 35: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 36: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue (billion), by Application 2026 & 2034
Figure 37: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Application 2026 & 2034
Figure 38: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue (billion), by End user industry 2026 & 2034
Figure 39: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue Share (%), by End user industry 2026 & 2034
Figure 40: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Crystalline Polyethylene Terephthalate Market Revenue billion Forecast, by Manufacturing Process 2020 & 2034
Table 52: Rest of Asia Pacific Crystalline Polyethylene Terephthalate Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% primary / 20-30% secondary split. Primary interviews and structured surveys supply the dominant share of all demand, capacity, and pricing inputs used in the crystallized PET model.
Targeted value-chain interviews covering: (1) bottle-grade crystallized PET resin producers operating continuous polymerization lines; (2) sheet extrusion and thermoforming converters running CPET tray and dual-ovenable container lines; (3) solid-state polycondensation (SSP) toll processors and pellet upgraders; (4) blow-molding convertors serving carbonated soft drink and water bottlers; (5) rPET flake and pellet recyclers supplying food-contact-approved recycled feedstock.
Stakeholder job titles interviewed: PET Resin Procurement Director (Beverage Packaging); Polymer Process Engineering Manager (SSP and Extrusion Lines); Packaging Sustainability & Regulatory Compliance Lead; Category Sourcing Manager (Thermoformed Food Containers).
Guaranteed estimated data accuracy level of 85-90%, validated against reported producer volumes and converter shipment disclosures where available.
Interviews are refreshed to the date of purchase, so every report reflects the latest licensing decisions, line restarts, and contract awards.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
PET Resin Procurement Director, Beverage Packaging
30%
Polymer Process Engineering Manager (SSP and Extrusion Lines)
24%
Packaging Sustainability & Regulatory Compliance Lead
No market research reseller websites are used as benchmark inputs; every secondary datapoint is traceable to a primary filing, statute, or association publication.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are run simultaneously and reconciled through multi-level data triangulation across application, process, end-user, and region.
Bottom-up quantitative inputs specific to this market: (1) installed crystallized PET polymerization capacity (kt/yr) per producer multiplied by verified line utilization rates; (2) bottle-to-bottle and tray-to-tray rPET content percentages mandated per jurisdiction, applied to regional container shipment volumes; (3) average CPET tray gram weight per unit multiplied by annual unit shipments from foodservice and retail catering channels; (4) resin price spread between virgin bottle-grade and food-grade rPET pellets (USD/tonne), used to split value from volume; (5) conversion yield of 0.855 tonnes PET per tonne of PTA consumed, used to reconcile upstream feedstock consumption with downstream resin output.
Segment build: Manufacturing Process (Extrusion Process, Molding Process), Application (Trays, Cups, Films/Sheets, Bottles, Others), and End user industry (Food Beverage, Pharmaceutical, Others) are modelled separately, then reaggregated to global and regional totals.
Regional build: North America (United States, Canada, Mexico); South America (Brazil, Argentina, Rest of South America); Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe); Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa); Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). Forecast horizon 2026-2034.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, held by cross-checking producer disclosed volumes against converter offtake and import/export customs records.
Divergence above a 5% threshold between top-down and bottom-up estimates triggers a re-interview cycle with at least three independent respondents per disputed data point.
Capacity and pricing figures are sanity-checked against feedstock consumption implied by the 0.855 tonne PET-per-tonne PTA conversion ratio.
Recycled-content assumptions are validated against EFSA and FDA authorization lists, so compliance-driven demand is never double counted.
Every report is updated to the date of purchase, ensuring capacity changes, feedstock price resets, and regulatory amendments published after the base year are reflected.
Frequently Asked Questions
1. How has the Crystalline Polyethylene Terephthalate Market recovered since the pandemic, and which structural shifts have persisted?
Volumes recovered faster than value: global crystallized PET demand returned to 2019 levels by late 2022, and the market reached USD 13.8 billion in 2024 with an 8.6% CAGR to 2033. The durable shift is specification, not tonnage. Recycled-content rules, led by the EU's 25% bottle threshold from 2025, moved food-grade rPET from a marketing option into a contractual requirement. Inventory behaviour also changed: bottlers now hold 30-45 days of resin cover instead of the pre-pandemic 60-90 days.
2. What notable developments, M&A activity, or product launches shaped the market in 2024 and 2025?
Activity centred on recycled feedstock qualification and higher-specification grades rather than greenfield capacity. Indorama Ventures expanded food-grade rPET output, Eastman Chemical qualified chemically recycled feedstock for food-contact resin, and DAK Americas completed bottle-grade line upgrades in 2024. In early 2025 Far Eastern New Century introduced a higher intrinsic viscosity grade for hot-fill and pressurized formats. The top five suppliers now hold an estimated 55-60% of global bottle-grade capacity.
3. Which end-user industries drive downstream demand for crystallized PET?
Food and beverage packaging absorbs an estimated 70-74% of crystallized PET output, led by carbonated soft drinks, water, and hot-fill juices in bottles plus dual-ovenable CPET trays. The Food and Beverage Packaging Market is followed by the Pharmaceutical Packaging Market at roughly 9-11% of volumes, where sterility and barrier performance justify a 2-3x margin premium over commodity bottle resin. Industrial applications such as strapping and carrier tape take the remaining share.
4. What are the biggest challenges and supply-chain risks facing crystallized PET producers?
Feedstock volatility is the primary margin risk: a USD 90 per tonne move in purified terephthalic acid shifts resin cost by about 6%, and MEG swings of USD 60-110 per tonne have occurred around maintenance turnarounds. Food-grade recycled flake availability is the hardest constraint, since collection rates rather than reclaim technology cap supply. Fiber-based and aluminum substitution in cups and single-serve formats adds structural demand risk in North America and Western Europe.
5. How do export-import dynamics shape the global crystallized PET trade?
China remains the largest net exporter of bottle-grade PET, while the EU and the United States are net importers of finished vessels and net exporters of higher-value recyclate. Chinese restrictions on recycled plastics imports have redirected Asian trade routes and raised landed resin cost by 4-7% in affected destination markets. India's quality control order regime adds certification friction at the border, slowing import clearance for uncertified resin.
6. Which region dominates the Crystalline Polyethylene Terephthalate Market and why?
Asia-Pacific leads with roughly 47% of global revenue and the fastest projected CAGR at 9.3%, supported by Chinese, Indian, and ASEAN bottling capacity plus competitive resin landed cost. Europe is the most mature and most regulation-driven region, growing at 8.1% on the back of binding recycled-content mandates. North America follows at 7.6%, with medical and foodservice packaging supporting higher-margin volumes. Middle East and Africa is the smallest block at roughly USD 0.7 billion but expands at 8.9%.