Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Plastics Injection Molding Market: 4.1% CAGR to $192.7B
Plastics Injection Molding Market
Plastics Injection Molding Market: 4.1% CAGR to $192.7B
Plastics Injection Molding Market by Raw Material Type (Polypropylene, Acrylonitrile Butadiene Styrene (ABS), Polystyrene, Polyethylene, Polyvinyl Chloride (PVC), Polycarbonate, Polyamide, Other Raw Materials), by Applications (Packaging, Building and Construction, Consumer Goods, Electronics, Automotive and Transportation, Healthcare, Other Applications), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
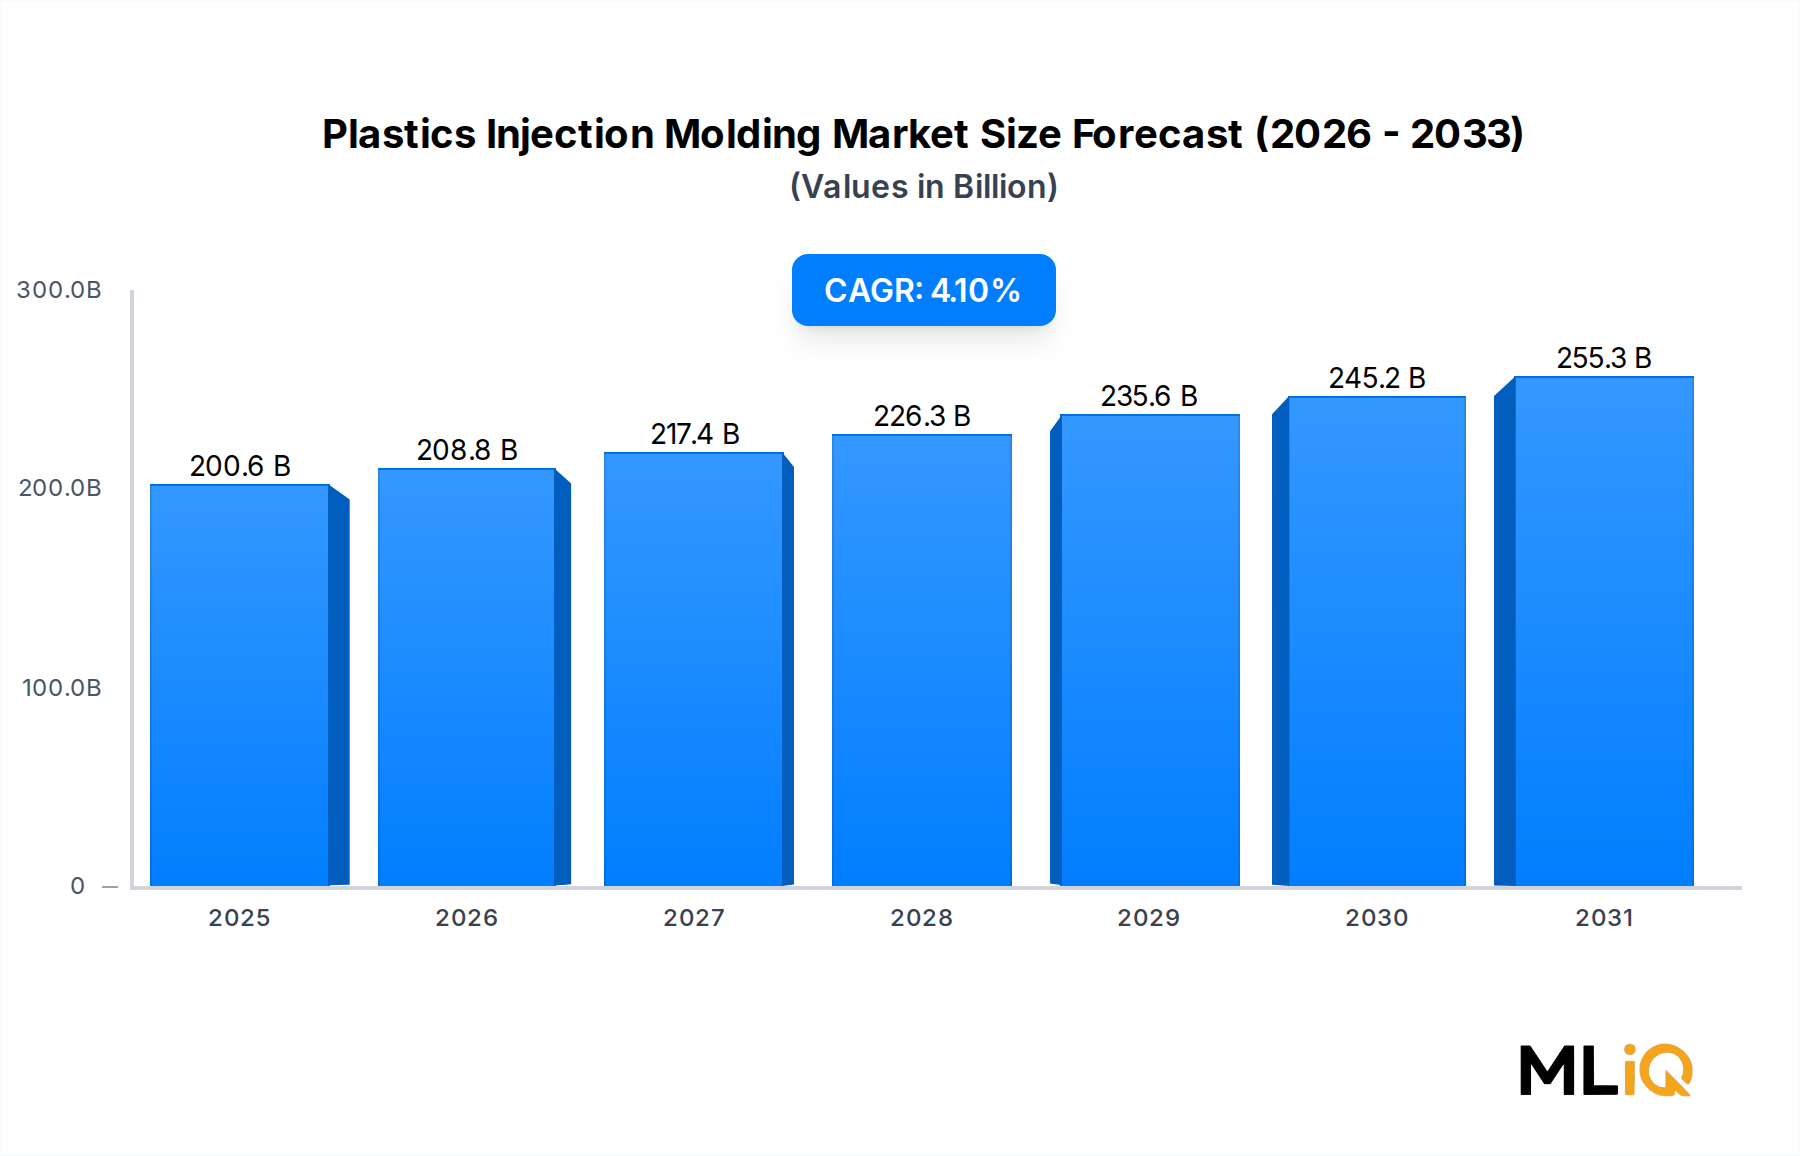
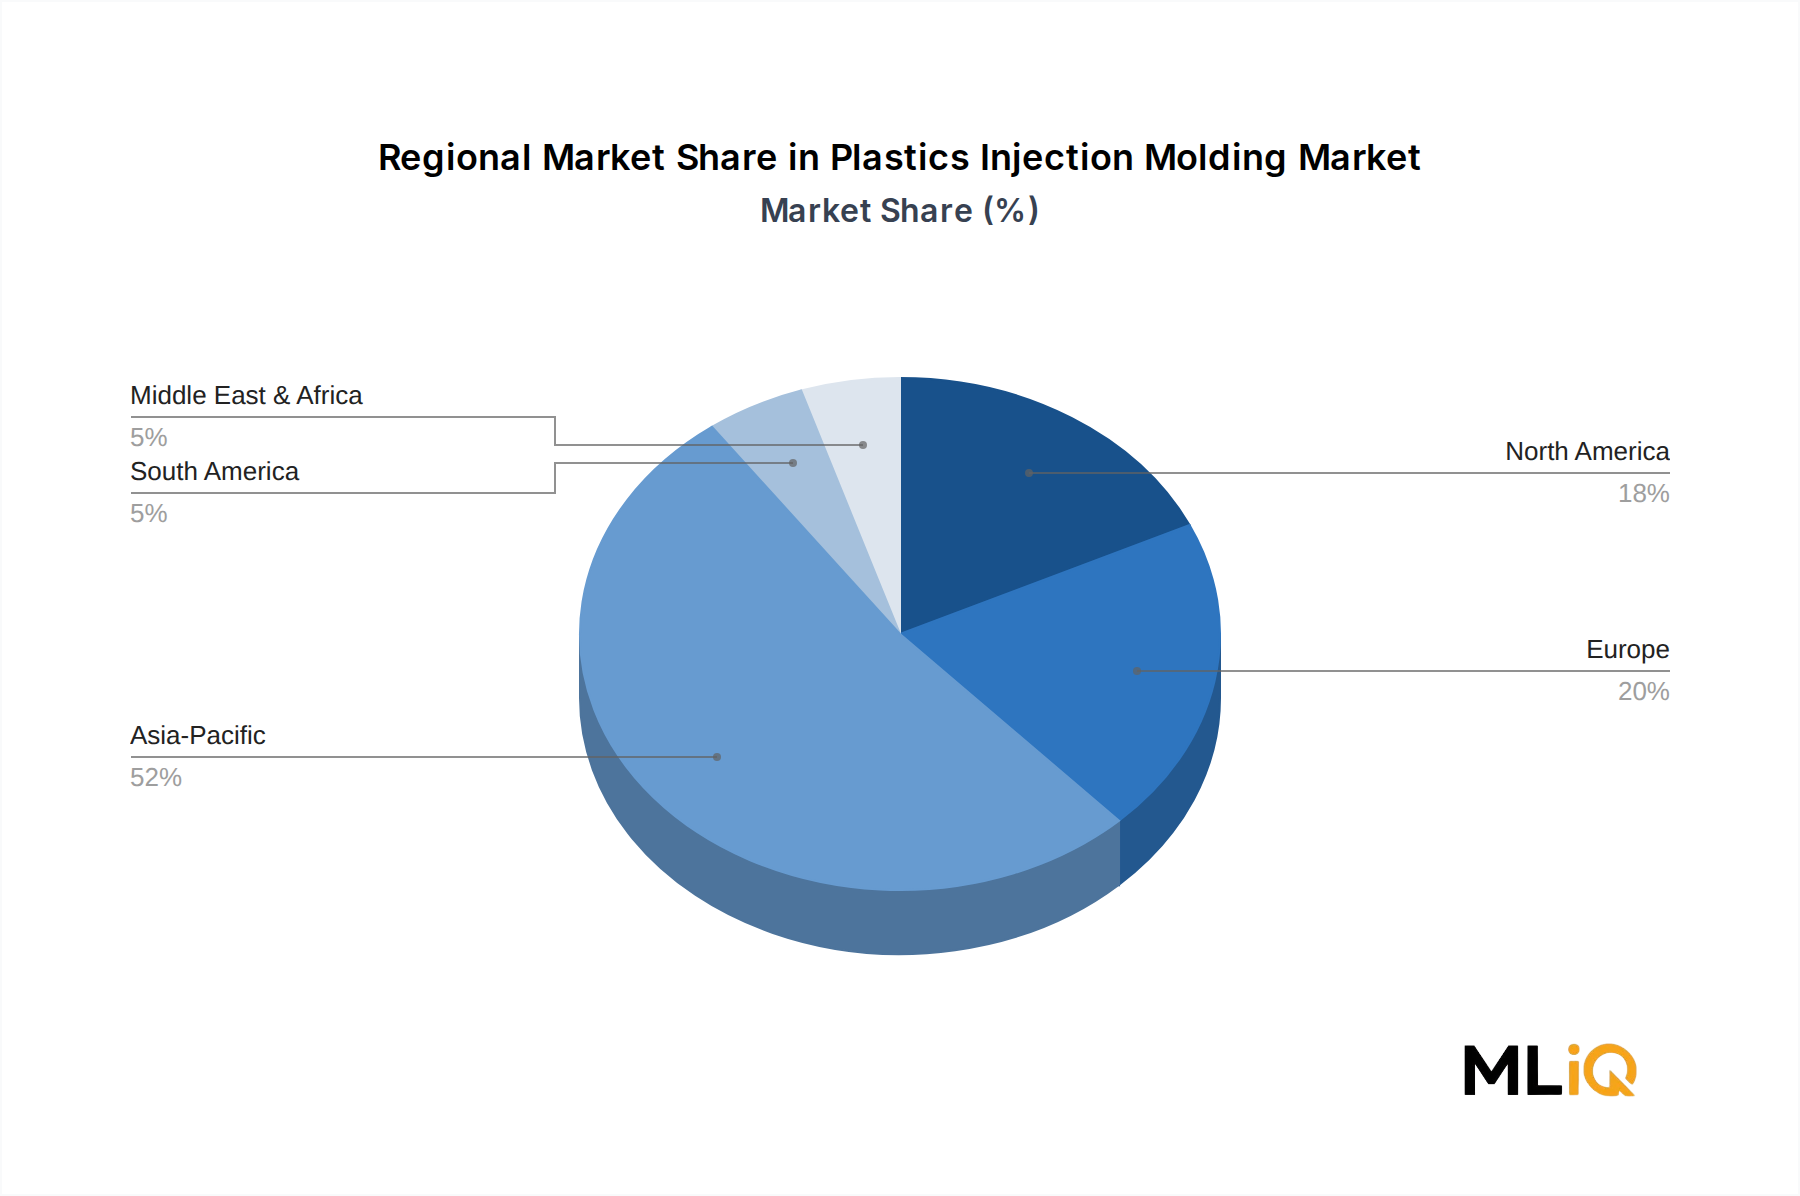
The global Plastics Injection Molding Market is valued at $192.7 billion in 2024 and is projected to reach $278.5 billion by 2033, growing at a CAGR of 4.1%. This growth is underpinned by rising demand from packaging, automotive, and healthcare sectors. The Packaging Injection Molding Market alone represents over 30% of total revenue, driven by e-commerce and food safety requirements. The Automotive Injection Molding Market is expanding due to lightweighting trends, with electric vehicles requiring 30% more plastic components than traditional vehicles. Asia-Pacific dominates with a 52% share, fueled by China's manufacturing base and India's growing packaging sector.
Plastics Injection Molding Market Size (In Billion)
300.0B
200.0B
100.0B
0
200.6 B
2025
208.8 B
2026
217.4 B
2027
226.3 B
2028
235.6 B
2029
245.2 B
2030
255.3 B
2031
Macro drivers include urbanization, sustainability mandates, and technological advancements in micro molding. However, high entry costs and competition from alternative technologies like thermoforming restrain faster adoption. The market is moderately consolidated, with key players such as ALPLA, Amcor, and Berry Global leading through vertical integration and innovation.
Segment Deep-Dive: Packaging Dominance in Plastics Injection Molding Market
Segment Analysis Matrix
Growth Rate (CAGR)
Market Share (%)
Key Demand Driver
Packaging
4.5%
32%
E-commerce, food & beverage
Automotive & Transportation
4.8%
22%
Lightweighting, EV components
Consumer Goods
3.9%
15%
Urbanization, disposable income
Healthcare
5.2%
10%
Medical device demand, aging population
Building & Construction
3.5%
12%
Infrastructure spending
Electronics
4.0%
6%
Miniaturization, connectivity
Other
3.0%
3%
Miscellaneous
The Packaging Injection Molding Market is the largest revenue generator, with 32% share, driven by rigid containers, caps, and closures. Polypropylene (PP) and polyethylene (PE) are the dominant materials, accounting for 65% of packaging resin consumption. Margin pressures stem from volatile resin prices and sustainability mandates, pushing molders to adopt recycled content. The Medical Injection Molding Market is the fastest-growing, with a 5.2% CAGR, due to increased demand for syringes, inhalers, and diagnostic devices. High-precision micro molding is critical here, with tight tolerances under 0.01 mm. The Micro Injection Molding Market is emerging as a high-growth niche, with applications in medical devices and electronics, growing at 7% CAGR.
Sub-Segment Dynamics
Polypropylene Injection Molding Market: Largest raw material segment, used in packaging, automotive, and consumer goods. Demand for PP is growing at 4.2% CAGR.
Polyethylene Injection Molding Market: Second-largest, with HDPE and LDPE used in bottles, toys, and pipes. Growth is steady at 3.8%.
Liquid Silicone Rubber Injection Molding Market: Niche but high-growth at 6.5% CAGR, driven by medical and automotive seals.
Favorable demand from consumer goods and electronics
Medium
Short-term
Restraint
High entry cost for new molders
Medium
Long-term
Restraint
Presence of alternative technologies
Medium
Long-term
The Packaging Injection Molding Market is propelled by e-commerce growth, which increased packaging demand by 8% annually since 2020. In automotive, the shift to electric vehicles (EVs) is a catalyst: EVs use 30% more plastic than internal combustion engines, boosting demand for under-hood and interior components. The Custom Injection Molding Market benefits from outsourcing trends, with OEMs seeking specialized molders for complex parts.
Restraints include the high cost of injection molding machines (average $150,000 per unit) and mold tooling (up to $100,000 per mold). Alternative technologies like 3D printing and thermoforming are viable for low-volume or large parts, but injection molding remains superior for high-volume precision. Regulatory pressures on single-use plastics are a double-edged sword, driving innovation in biodegradable polymers but also threatening traditional markets.
ALPLA: Global packaging leader with over 180 injection molding machines; invested $850,000 in an Indian mold shop in 2022 to expand local production.
Amcor PLC: Focuses on sustainable packaging, with 100% recyclable goals by 2025; leverages injection molding for caps and closures.
Berry Global Inc: Broad portfolio across packaging and healthcare; actively acquires niche molders to enhance capabilities.
Magna International: Major automotive supplier; uses injection molding for interior and exterior components, benefiting from EV lightweighting.
Silgan Holdings Inc: Specializes in closures and containers; strong in food and pharmaceutical markets.
EVCO Plastics: Custom molder with 183 machines; invested $11 million in Wisconsin expansion in 2022.
HTI Plastics: Niche player in custom molding, serving consumer and industrial sectors with quick-turn tooling.
Strategic Milestones & Recent Developments in Plastics Injection Molding Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Oct 2022
EVCO Plastics
Expansion
Added capacity with $11M investment
Jul 2022
ALPLA
Investment
$850K for mold shop in India
2023
Berry Global
Acquisition
Acquired niche molder to expand healthcare
2024
Amcor
Partnership
Collaborated on recyclable packaging
October 2022: EVCO Plastics proposed an $11 million expansion in Wisconsin, adding capacity to its 183 injection molding machines. This move targets growing demand from medical and industrial customers.
July 2022: ALPLA invested $850,000 in an Indian mold shop, its third after Austria and Germany. This investment may increase ALPLA's total investments in Pashamylaram, India, to $61 million.
2023: Berry Global acquired a healthcare-focused molder to strengthen its medical device offerings, responding to the 5.2% CAGR in medical injection molding.
2024: Amcor partnered with a bio-resin supplier to develop compostable injection-molded containers, aligning with EU sustainability directives.
Asia-Pacific is the fastest-growing region, with a 5.0% CAGR, driven by China's dominance in manufacturing and India's expanding packaging sector. China alone accounts for 40% of global injection molding capacity. North America and Europe are mature markets with stricter regulations, but they lead in technological innovation, especially in micro molding and medical devices. The Injection Molding Machine Market is concentrated in these regions, with key OEMs like Haitian International and Engel. South America and MEA offer untapped potential, with Brazil and GCC countries investing in local production to reduce imports.
Global trade in injection-molded products is dominated by Asia-Pacific exports, particularly from China, which ships over $50 billion worth of plastic parts annually. Tariffs such as the US Section 301 tariffs on Chinese goods have increased costs by 10-25% for molders, prompting some to shift production to Vietnam and Mexico. The Custom Injection Molding Market is particularly sensitive to trade policies, as OEMs seek low-cost suppliers. Non-tariff barriers include strict quality standards in the EU and FDA regulations in the US, which limit imports from certain regions. The Polypropylene Injection Molding Market is affected by resin trade flows, with Asia-Pacific being a net exporter of PP pellets.
Investment, M&A & Funding Activity in Plastics Injection Molding Market
The plastics injection molding sector has seen steady M&A activity, with private equity firms acquiring custom molders to consolidate fragmented markets. In 2023, Berry Global acquired a medical molder for $200 million, while Amcor invested $50 million in a new recycling facility. Venture capital funding is flowing into micro molding and liquid silicone rubber technologies, with startups raising over $100 million in the past two years. The Liquid Silicone Rubber Injection Molding Market and Medical Injection Molding Market are attracting the most capital due to high margins and growth potential. Strategic partnerships between resin suppliers and molders are also increasing to secure supply chains.
Plastics Injection Molding Market Segmentation
1. Raw Material Type
1.1. Polypropylene
1.2. Acrylonitrile Butadiene Styrene (ABS)
1.3. Polystyrene
1.4. Polyethylene
1.5. Polyvinyl Chloride (PVC)
1.6. Polycarbonate
1.7. Polyamide
1.8. Other Raw Materials
2. Applications
2.1. Packaging
2.2. Building and Construction
2.3. Consumer Goods
2.4. Electronics
2.5. Automotive and Transportation
2.6. Healthcare
2.7. Other Applications
Plastics Injection Molding Market Segmentation By Geography
Table 91: Rest of Asia Pacific Plastics Injection Molding Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 92: Rest of Asia Pacific Plastics Injection Molding Market Volume (Million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70-80% primary research through interviews with Resin/Polymer Suppliers, Injection Molding Machine OEMs, Mold/Tooling Manufacturers, Custom Injection Molders, and End-User OEMs across packaging, automotive, and healthcare.
Interviewed Procurement Directors for Polymer Resins, Manufacturing Operations Managers, Packaging Development Engineers, and Quality Assurance Managers to capture demand-side insights.
Engaged with industry associations including the Plastics Industry Association (PLASTICS), European Plastics Converters (EuPC), and regulatory bodies such as the U.S. Food and Drug Administration (FDA) and Environmental Protection Agency (EPA).
Data accuracy guaranteed at 85-90% through cross-validation of primary inputs with secondary sources.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Directors
25%
Manufacturing/Operations Managers
30%
R&D Engineers
20%
Quality Assurance/Regulatory Affairs
15%
Supply Chain Managers
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Resin/Polymer Suppliers
15%
Injection Molding Machine OEMs
10%
Mold/Tooling Manufacturers
15%
Custom Injection Molders
35%
End-User OEMs
25%
Secondary Research & Industry Benchmarking
Utilized 20-30% secondary research from financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Referenced government sources such as U.S. Census Bureau (census.gov), Eurostat (europa.eu), and trade association reports from PLASTICS (plasticsindustry.org).
Analyzed company filings, annual reports, and patent databases to benchmark competitive strategies and technology trends.
Every report is updated to the date of purchase to ensure current market intelligence.
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up approach utilized quantitative metrics: number of injection molding machines installed globally (approx. 1.2 million), average annual production output per machine (150 tons), average selling price per ton of molded parts ($3,500), and resin consumption volume by application.
Top-down approach leveraged regional GDP, manufacturing output, and industry value-added data to size the market.
Cross-checked with segment-level data from raw material types (Polypropylene, ABS, etc.) and applications (Packaging, Automotive, etc.).
Data Accuracy & Quality Check
Ensured 85-90% estimated data accuracy through rigorous validation: primary interview transcripts were cross-referenced with secondary sources and historical trends.
Multi-level data triangulation involved comparing supplier-reported volumes, OEM demand forecasts, and trade statistics.
Outlier detection and sanity checks were performed at each stage; discrepancies beyond 5% were investigated.
Final figures were reviewed by senior analysts and industry experts before publication.
Frequently Asked Questions
1. What are the key segments of the Plastics Injection Molding Market?
The market is segmented by raw material type (Polypropylene, ABS, Polyethylene, etc.) and by application (Packaging, Automotive, Consumer Goods, Electronics, Healthcare, Building & Construction). Packaging is the dominant application, accounting for over 30% of market share, driven by e-commerce and food packaging demand.
2. How is sustainability impacting the Plastics Injection Molding Market?
Sustainability regulations, such as the EU Single-Use Plastics Directive, are pushing molders to adopt recyclable and bio-based polymers. Companies like Amcor have pledged to make 100% of their packaging recyclable by 2025, increasing demand for injection-molded PET and PP containers. This shift requires capital investment in new mold technologies and material innovation.
3. What disruptive technologies are shaping the Plastics Injection Molding Market?
Micro injection molding and liquid silicone rubber (LSR) injection molding are gaining traction, especially in medical devices and electronics. 3D printing poses a substitute for low-volume production, but injection molding remains cost-effective for high volumes. Automation and AI-driven quality control are improving cycle times by up to 20%.
4. What are the key raw material sourcing challenges in the Plastics Injection Molding Market?
Volatility in polymer prices, especially polypropylene and polyethylene, due to crude oil fluctuations and supply chain disruptions, remains a major challenge. In 2022, polypropylene prices surged by 25%, squeezing molder margins. Regional sourcing is increasing to mitigate logistics risks, with Asia-Pacific dominating resin production.
5. How do regulations affect the Plastics Injection Molding Market?
Regulations such as FDA 21 CFR Part 820 for medical devices and EU MDR impose strict quality and documentation requirements on injection molders. Compliance costs can be significant, but they also create barriers to entry and favor established players. Environmental regulations like REACH and EPA emissions rules drive investment in cleaner technologies.
6. Which end-user industries drive demand in the Plastics Injection Molding Market?
Packaging, automotive, healthcare, and electronics are the primary end-user industries. The automotive sector is shifting towards lightweight plastic components to improve fuel efficiency, with electric vehicles using 30% more plastics than internal combustion engines. Packaging demand is sustained by urbanization and single-serve product trends.