Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Catalyst Market: 4.9% CAGR in Developing Economies to 2033
Catalyst Market
Catalyst Market: 4.9% CAGR in Developing Economies to 2033
Catalyst Market by Type (Zeolites, Metals, Chemical Compounds, Enzymes, Organometallic Materials), by Process (Recycling, Regeneration, Rejuvenation), by Application (Petroleum Refining, Chemical Synthesis, Polymer Catalysis, Environmental), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 580
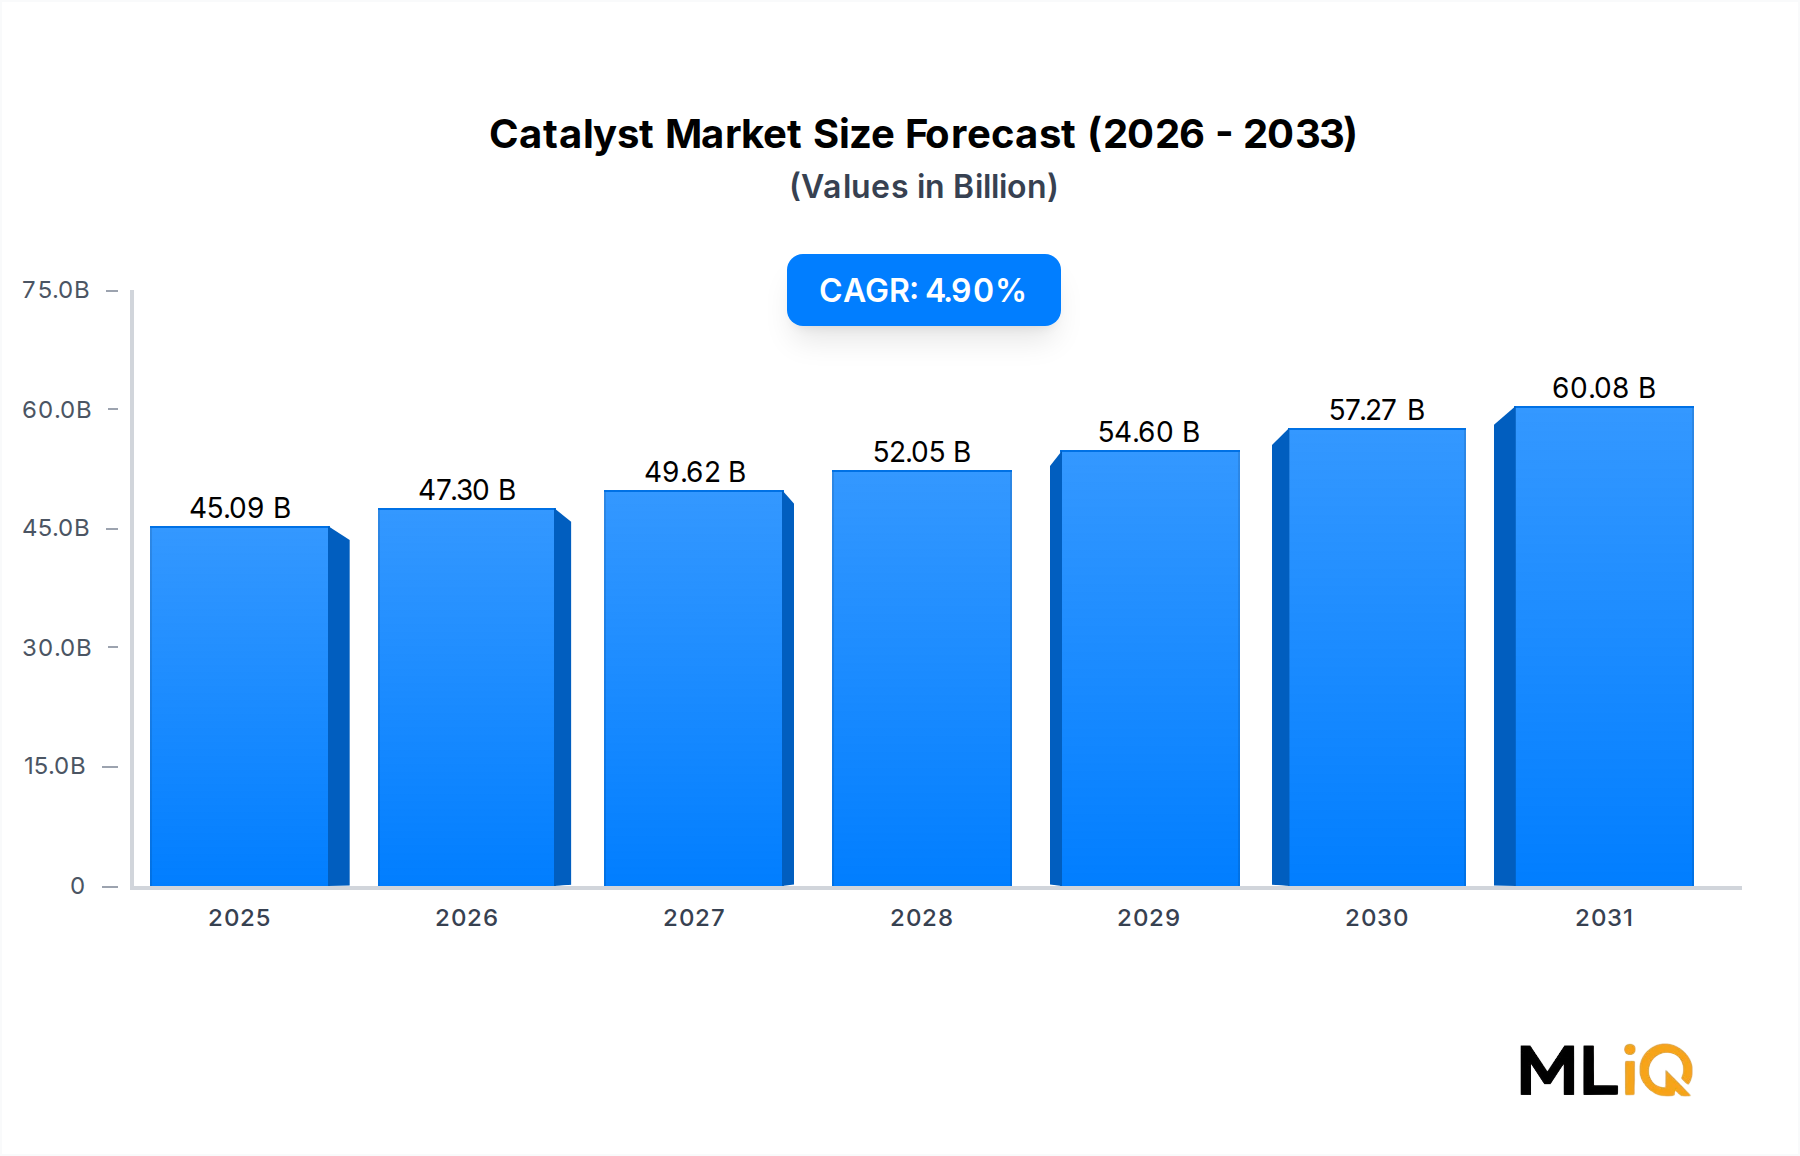
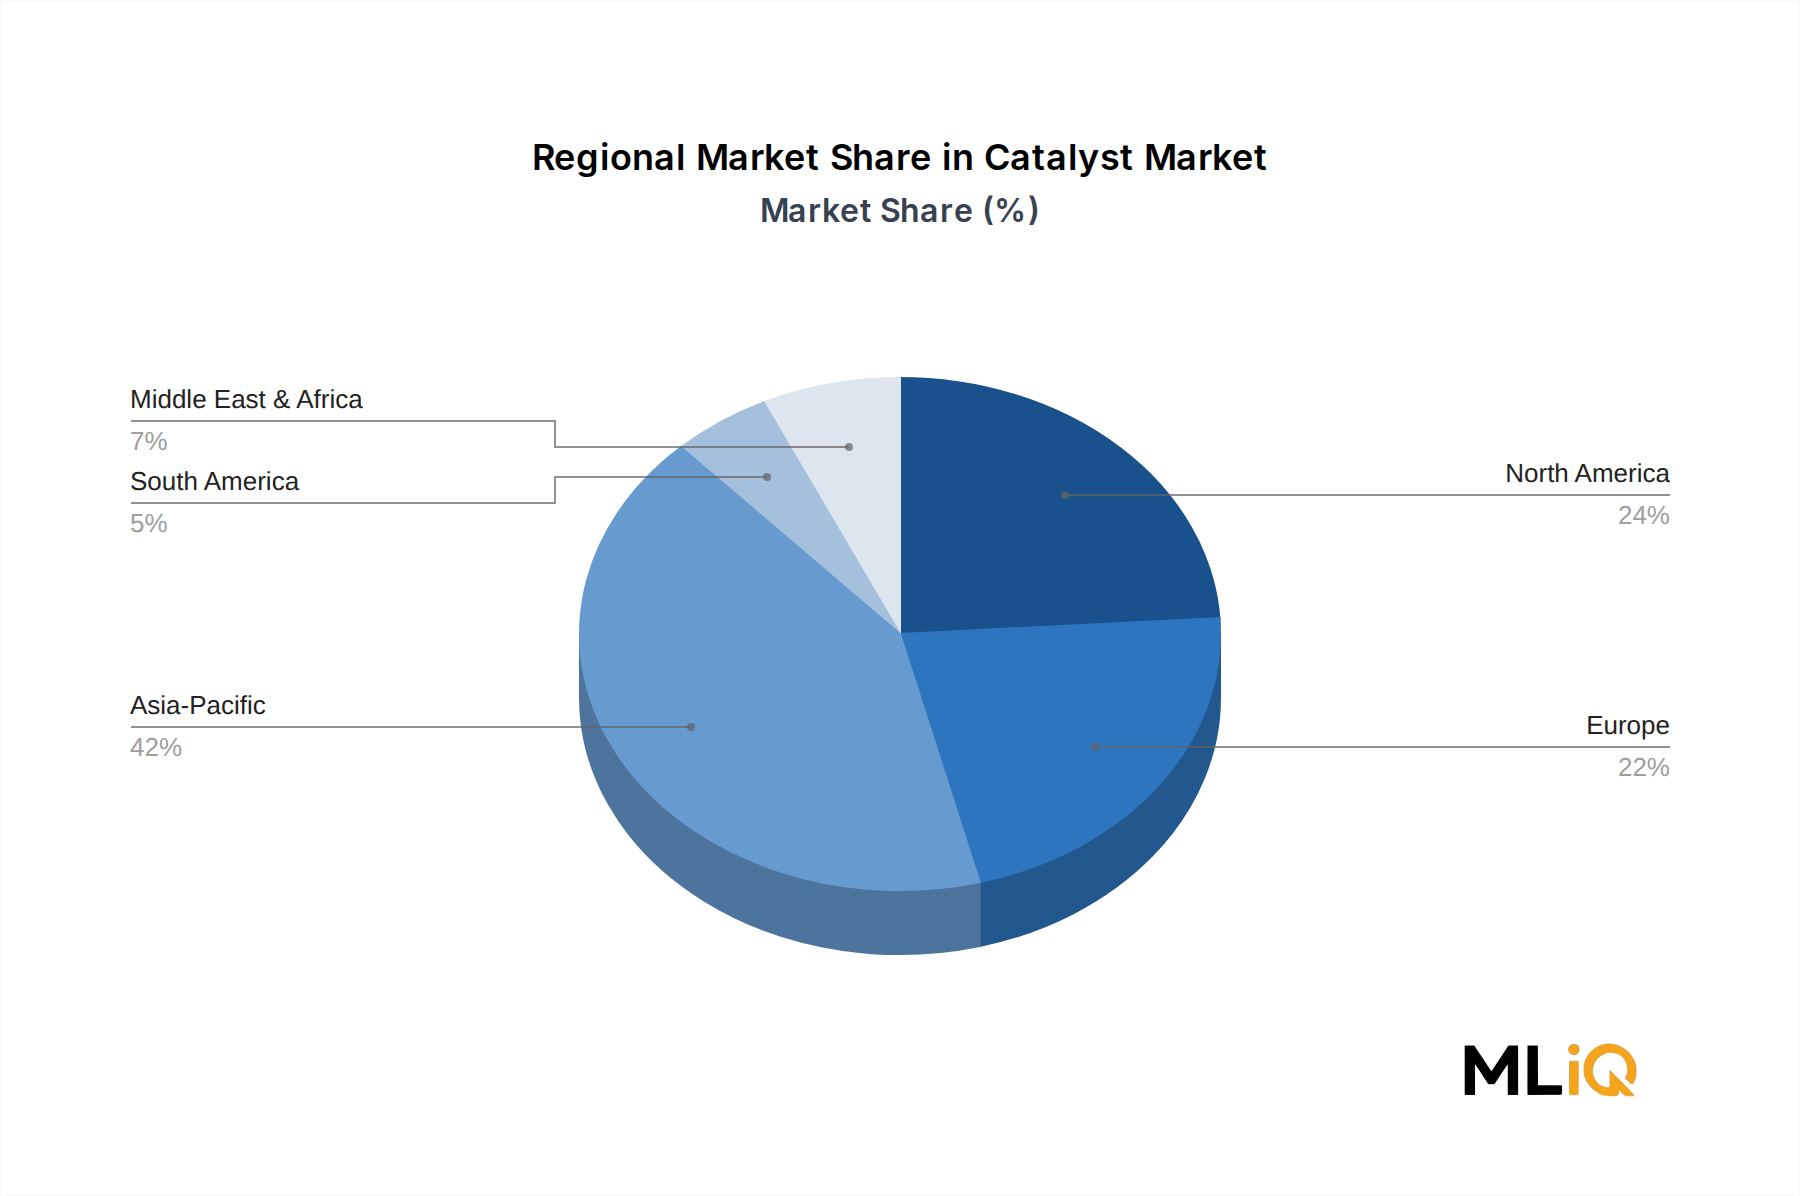
The Catalyst Market is valued at $45.09 billion in 2025 and is forecast to reach $66.1 billion by 2033, expanding at a 4.9% CAGR. Demand is anchored by refinery capacity additions, petrochemical plant utilization, and tightening emissions rules. Asia-Pacific contributes 42% of global revenue, followed by North America at 24% and Europe at 22%. The Petroleum Refining Catalyst Market accounts for the largest application share, while the Zeolite Catalyst Market is the leading type at 31% of type revenue. The Metal Catalyst Market represents 24%, and the Enzyme Catalyst Market is the fastest-growing type at 6.8% CAGR through 2033.
Catalyst Market Size (In Billion)
75.0B
60.0B
45.0B
30.0B
15.0B
0
45.09 B
2025
47.30 B
2026
49.62 B
2027
52.05 B
2028
54.60 B
2029
57.27 B
2030
60.08 B
2031
Key takeaways
The Industrial Catalyst Market is a volume-driven business: global refining throughput above 82 million barrels per day and petrochemical capacity growth of 3.5% annually support steady catalyst replacement demand.
The Chemical Synthesis Catalyst Market benefits from specialty chemical output and a shift toward lower-carbon methanol and ammonia.
The Polymer Catalysis Market is supported by polyolefin demand growth of 4.0% annually, with metallocene and Ziegler-Natta catalysts gaining share.
The Environmental Catalyst Market is the fastest-growing application, driven by NOx, SOx, and volatile organic compound controls.
The Catalyst Regeneration Market expands as refiners and chemical producers seek to lower replacement costs and reduce precious metal losses.
Regulatory pressure and feedstock variability create margin risk, but regeneration, recycling, and high-selectivity catalyst formulations offer defensible value pools. Asia-Pacific and the Middle East remain the primary growth corridors, while North America and Europe focus on replacement, efficiency, and compliance.
Segment Deep-Dive: Petroleum Refining Dominance in Catalyst Market
Petroleum refining is the dominant application, generating 38% of Catalyst Market revenue in 2025. Fluid catalytic cracking (FCC), hydrocracking, and hydrotreating units consume large volumes of zeolite and metal catalysts. The segment grows at 4.2% CAGR, slower than environmental and polymer applications, but its scale makes it the revenue anchor.
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Petroleum Refining
4.2
38
Clean fuel specifications, FCC and hydrocracker capacity
Chemical Synthesis
5.1
24
Methanol, ammonia, and specialty chemical capacity
Polymer Catalysis
5.6
18
Polyolefin demand and metallocene catalyst adoption
Environmental
6.1
12
NOx, SOx, and VOC emission controls
Other Applications
4.9
8
Niche hydrogenation and fine chemical uses
Sub-Segment Dynamics
FCC catalysts remain the largest single product category. The Zeolite Catalyst Market is central here, with USY and ZSM-5 zeolites used in more than 400 FCC units worldwide.
Hydroprocessing catalysts rely on the Metal Catalyst Market, especially nickel-molybdenum, cobalt-molybdenum, and platinum-group metal formulations. Replacement cycles range from 1 to 4 years, depending on feedstock sulfur and metals content.
Chemical Synthesis Catalyst Market demand is tied to methanol and ammonia plants. Global methanol capacity exceeds 160 million tons per year, with catalyst replacement every 3 to 5 years.
Polymer Catalysis Market growth is driven by polyethylene and polypropylene capacity additions in China, the Middle East, and North America. Metallocene catalysts command a price premium of 20–35% over conventional Ziegler-Natta systems.
Environmental Catalyst Market is the fastest-growing application. Selective catalytic reduction (SCR) and diesel oxidation catalysts are required for Euro 7 and China VI standards.
Margin Pressures
Precious metal prices create earnings volatility. Platinum, palladium, and rhodium loadings can represent 40–60% of finished catalyst cost for emissions control.
Chinese FCC catalyst overcapacity has compressed prices for standard grades, pushing suppliers toward differentiated zeolites and regeneration services.
The Catalyst Regeneration Market offers margin relief: regenerated catalyst can cost 30–50% less than new catalyst, but performance penalties limit use in high-severity units.
Enzyme Catalyst Market margins are higher but volumes remain small; industrial biocatalysis is expanding in pharmaceutical and fine chemical production.
Overall, petroleum refining remains the volume engine, while chemical synthesis, polymer catalysis, and environmental applications provide faster growth and higher-value differentiation.
Primary Market Drivers & Growth Restraints in Catalyst Market
The Catalyst Market grows at 4.9% CAGR because demand is tied to physical throughput, environmental compliance, and process economics. Drivers and restraints differ by region and application.
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Refining and petrochemical capacity additions in Asia-Pacific and the Middle East
High
Long term
Driver
Stricter fuel and emissions regulations (Euro 7, China VI, IMO 2020)
High
Short term
Driver
Polyolefin and specialty chemical demand growth
High
Long term
Driver
Catalyst regeneration and recycling economics
Medium
Short term
Restraint
Volatility in platinum-group metal and rare earth prices
High
Short term
Restraint
Long qualification cycles for new catalyst formulations
Medium
Long term
Restraint
Supply concentration for zeolite precursors and rare earths
High
Medium term
Restraint
Regulatory pressure to reduce certain heavy-metal catalysts
Medium
Long term
Quantitative Drivers
Global refining capacity is projected to add 5.0 million barrels per day by 2030, mostly in Asia and the Middle East. Each new hydrotreater requires an initial catalyst fill and recurring replacement, supporting the Petroleum Refining Catalyst Market.
Euro 7 and China VI standards tighten NOx limits by 30–50% versus prior norms, increasing demand for the Environmental Catalyst Market.
Polymer demand growth of 4.0% annually drives the Polymer Catalysis Market, especially in packaging, automotive, and construction.
The Industrial Catalyst Market benefits from a shift toward chemical recycling and low-carbon ammonia, where catalyst selectivity directly affects yield and energy use.
Restraints and Bottlenecks
Platinum-group metal prices can swing 30–40% within a year, forcing catalyst buyers to accept price-adjustment clauses. This volatility raises working capital needs and delays project sanctioning.
Rare earth and zeolite precursor supply is concentrated. China accounts for over 60% of rare earth mining and 85% of refining, creating a single-point risk for the Metal Catalyst Market.
Catalyst qualification in refining and petrochemicals takes 18–36 months, slowing adoption of new formulations even when performance gains are proven.
Environmental regulations cut both ways: they boost the Environmental Catalyst Market but also push phase-outs of certain heavy-metal and cobalt-based catalysts, requiring reformulation.
The balance of drivers and restraints supports steady growth rather than explosive expansion. Suppliers that reduce precious metal content, improve regeneration, and localize supply chains can outperform the 4.9% CAGR baseline.
The Catalyst Market is concentrated in refining and chemical catalysts, with the top five suppliers holding an estimated 55% of global revenue. Competition is based on formulation know-how, precious metal management, and plant-level technical service.
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
BASF SE
Zeolite and metal catalysts for refining and chemicals
Refiners, chemical producers
Leader
Johnson Matthey
Platinum-group metal catalysts and emissions control
Automotive, chemical, refining
Leader
Albemarle Corporation
Hydroprocessing and FCC catalysts
Refiners
Leader
W.R. Grace & Co.
FCC, polyolefin, and specialty catalysts
Refiners, polymer producers
Leader
Clariant AG
Syngas, dehydrogenation, and specialty catalysts
Chemical, refining
Challenger
Evonik Industries AG
Organometallic and polyolefin catalysts
Polymer producers
Challenger
Chevron Phillips Chemical Company LLC
Proprietary polyolefin catalysts
Polymer producers
Niche
ExxonMobil Corporation
In-house refining and petrochemical catalysts
Integrated oil and chemical
Niche
Vendor Profiles
BASF SE: Operates catalyst plants in Germany, the United States, and China. Its portfolio covers FCC, hydrotreating, and chemical synthesis catalysts, with a growing focus on battery materials and recycling.
Johnson Matthey: A leading supplier of platinum-group metal catalysts for autocatalysts and chemical processes. The company has expanded into blue hydrogen and sustainable fuels catalyst technology.
Albemarle Corporation: Strong in hydroprocessing catalysts and FCC additives. It sold its catalysts business to W.R. Grace in 2023 and has shifted strategic focus toward lithium and bromine specialties.
W.R. Grace & Co.: A top FCC catalyst supplier and a major player in polyolefin catalysts. Its acquisition of Albemarle’s catalysts business strengthened its hydroprocessing position.
Clariant AG: Competes in syngas, propane dehydrogenation, and specialty catalysts. Its catalyst regeneration services support the Catalyst Regeneration Market.
Evonik Industries AG: Supplies organometallic catalysts and polyolefin catalysts. It invests in metallocene and post-metallocene technologies for the Polymer Catalysis Market.
Chevron Phillips Chemical Company LLC: Develops proprietary loop slurry and metallocene catalysts for its own polyethylene processes and licensed technologies.
ExxonMobil Corporation: Develops catalysts primarily for captive refining and petrochemical operations. It licenses select technologies and catalysts to third parties.
The competitive field is shaped by precious metal access, technical service depth, and regional plant footprints. Suppliers with regeneration and recycling capabilities can capture value from the Environmental Catalyst Market and the Chemical Synthesis Catalyst Market.
Strategic Milestones & Recent Developments in Catalyst Market
The past three years brought portfolio moves, capacity additions, and partnerships aimed at low-carbon fuels and circular plastics.
Latest Strategic Moves
Date
Company
Event Type
Impact
2024
BASF SE
Expansion
Added refining catalyst capacity in China to serve Asia-Pacific demand
2024
Johnson Matthey
Partnership
Signed blue hydrogen catalyst supply agreement with an energy major
2023
W.R. Grace & Co.
M&A
Acquired Albemarle’s catalysts business for $300 million, expanding hydroprocessing
2023
Clariant AG
Partnership
Formed catalyst regeneration alliance with a Chinese refinery
2023
Evonik Industries AG
Launch
Commercialized new organometallic catalyst for polyolefin production
2022
Dow Chemical Company
Investment
Funded catalyst R&D for chemical recycling of plastics
Chronological Detail
2022: Dow Chemical Company increased R&D spending on catalysts for chemical recycling, targeting a 30% reduction in energy use for mixed-plastic feedstock. The move signals rising demand for the Environmental Catalyst Market.
2023: W.R. Grace & Co. acquired Albemarle’s catalysts business for $300 million, consolidating FCC and hydroprocessing catalyst supply. The deal strengthened Grace’s position in the Petroleum Refining Catalyst Market.
2023: Clariant AG partnered with a Chinese refinery to provide catalyst regeneration services, expanding the Catalyst Regeneration Market in Asia-Pacific.
2023: Evonik Industries AG launched a new organometallic catalyst for polyolefins, targeting 10–15% higher activity in gas-phase polyethylene processes.
2024: BASF SE expanded refining catalyst production in China, adding capacity for hydrotreating and FCC catalysts. The project supports Asia-Pacific’s 42% share of global Catalyst Market revenue.
2024: Johnson Matthey signed a blue hydrogen catalyst supply agreement, applying its platinum-group metal expertise to low-carbon ammonia and hydrogen. This reinforces the Metal Catalyst Market and Chemical Synthesis Catalyst Market.
These moves show consolidation in mature catalyst lines and investment in enzyme, recycling, and emissions-control technologies.
Regional Market Analysis & Growth Corridors for Catalyst Market
Asia-Pacific leads the Catalyst Market with 42% of 2025 revenue, estimated at $18.9 billion. North America follows at $10.8 billion, Europe at $9.9 billion, and LAMEA at $5.4 billion. Growth rates vary by regulatory intensity, feedstock availability, and industrial capacity.
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Asia-Pacific
5.8
$18.9 billion
Refinery and petrochemical expansion
Medium to High
North America
4.1
$10.8 billion
Refining upgrades, emissions control
High
Europe
4.3
$9.9 billion
Chemical synthesis, REACH compliance
Very High
LAMEA
5.2
$5.4 billion
Gas-to-liquids, mining, refining
Medium
Fastest-Growing Markets
Asia-Pacific is the fastest-growing region at 5.8% CAGR. China and India account for over 60% of regional catalyst demand, driven by new refineries, coal-to-chemicals plants, and polymer capacity. The Zeolite Catalyst Market and Metal Catalyst Market benefit most.
Middle East & Africa grows at 5.2% CAGR, supported by refinery upgrades, gas processing, and petrochemical megaprojects in Saudi Arabia, UAE, and Nigeria. The Petroleum Refining Catalyst Market and Chemical Synthesis Catalyst Market are key.
South America grows at 4.5% CAGR, led by Brazil’s ethanol and petrochemical sectors. Enzyme Catalyst Market demand is rising in biofuel and biochemical production.
Mature Markets
North America grows at 4.1% CAGR, with demand driven by replacement cycles, Tier 3 fuel standards, and petrochemical feedstock advantages. The Industrial Catalyst Market is mature but stable.
Europe grows at 4.3% CAGR, shaped by REACH, Euro 7, and the EU Emissions Trading System. Regulatory stringency raises compliance costs but supports the Environmental Catalyst Market and Catalyst Regeneration Market.
Regional strategies differ: Asia-Pacific focuses on capacity and cost, North America on efficiency and compliance, and Europe on sustainability and circularity. The Polymer Catalysis Market is a common growth vector across all regions.
Technology Innovation & R&D Trajectory in Catalyst Market
Three technology shifts are altering catalyst economics: single-atom catalysts, advanced zeolites for plastic recycling, and industrial enzymes.
Single-atom catalysts maximize metal utilization, potentially cutting platinum-group metal loadings by 50–70%. Adoption is early, with pilot-scale use in hydrogenation and emissions control expected by 2027–2030. This threatens conventional Metal Catalyst Market suppliers dependent on high precious metal volumes.
Advanced zeolites for chemical recycling of plastics can convert mixed polyolefin waste into naphtha-range liquids. Pilot plants in Europe and Japan target 70–80% yield. This expands the Zeolite Catalyst Market and Polymer Catalysis Market but requires new formulation expertise.
Industrial enzymes are replacing chemical catalysts in fine chemicals, pharmaceuticals, and biofuels. The Enzyme Catalyst Market grows at 6.8% CAGR, with R&D investment by Novozymes, BASF, and DSM. Enzyme catalysts operate at lower temperatures and reduce energy use by 20–40%.
Patent activity is concentrated in zeolite frameworks, single-atom supports, and enzyme immobilization. R&D spending among top 10 suppliers averages 3–5% of catalyst revenue, with higher intensity in enzyme and emissions-control catalysts. Incumbent business models are reinforced where catalysts are integrated with process licenses, but threatened where commodity catalyst grades can be replaced by lower-metal formulations or biocatalysis.
Regulatory trends favor lower-toxicity catalysts, which supports the Environmental Catalyst Market and Catalyst Regeneration Market. Digital tools for catalyst monitoring and predictive replacement are also emerging, reducing unplanned downtime by 15–25%.
Investment, M&A & Funding Activity in Catalyst Market
Capital flows favor consolidation in refining catalysts and growth in recycling, enzymes, and emissions control.
Selected Investment and M&A Activity
Year
Acquirer/Investor
Target/Focus
Deal Type
Rationale
2023
W.R. Grace & Co.
Albemarle catalysts business
M&A
Added hydroprocessing scale
2021
Standard Industries
W.R. Grace & Co.
Take-private
Long-term catalyst platform
2023
Clariant AG
Chinese refinery regeneration
Partnership
Expand Catalyst Regeneration Market
2022
Dow Chemical Company
Chemical recycling catalysts
Internal R&D
Circular plastics
2024
BASF SE
China refining catalyst plant
Capex
Asia-Pacific growth
High-Growth Sub-Segments Attracting Capital
Enzyme catalysts: The Enzyme Catalyst Market attracts venture funding because enzymes reduce energy use and enable bio-based chemicals. Deal sizes remain small, typically $5–50 million, but strategic interest from BASF and DSM is rising.
Catalyst regeneration and recycling: The Catalyst Regeneration Market benefits from precious metal recovery economics. Regeneration can recover 90–95% of platinum-group metal value and reduce waste.
Environmental catalysts: The Environmental Catalyst Market attracts capital due to tightening NOx and SOx rules. SCR catalyst replacements are a recurring revenue stream.
Chemical synthesis catalysts: The Chemical Synthesis Catalyst Market draws investment for low-carbon ammonia, methanol, and hydrogen. These projects often include 10–15 year catalyst supply agreements.
Strategic Acquires and Investors
Integrated oil companies and petrochemical majors seek captive catalyst capability, as seen with ExxonMobil Corporation and Chevron Phillips Chemical Company LLC.
Private equity has shown interest in catalyst regeneration and precious metal recovery assets, where cash flows are tied to replacement cycles.
Specialty chemical companies, including Evonik Industries AG and Clariant AG, pursue bolt-on acquisitions in organometallic and enzyme catalysts.
The Industrial Catalyst Market remains capital-intensive, but the highest returns are shifting toward services, regeneration, and specialty formulations. Investment activity supports a 4.9% CAGR baseline, with upside in enzyme and environmental catalysts.
Catalyst Market Segmentation
1. Type
1.1. Zeolites
1.2. Metals
1.3. Chemical Compounds
1.4. Enzymes
1.5. Organometallic Materials
2. Process
2.1. Recycling
2.2. Regeneration
2.3. Rejuvenation
3. Application
3.1. Petroleum Refining
3.2. Chemical Synthesis
3.3. Polymer Catalysis
3.4. Environmental
Catalyst Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Catalyst Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.9% from 2020-2034
Segmentation
By Type
Zeolites
Metals
Chemical Compounds
Enzymes
Organometallic Materials
By Process
Recycling
Regeneration
Rejuvenation
By Application
Petroleum Refining
Chemical Synthesis
Polymer Catalysis
Environmental
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Zeolites
5.1.2. Metals
5.1.3. Chemical Compounds
5.1.4. Enzymes
5.1.5. Organometallic Materials
5.2. Market Analysis, Insights and Forecast - by Process
5.2.1. Recycling
5.2.2. Regeneration
5.2.3. Rejuvenation
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Petroleum Refining
5.3.2. Chemical Synthesis
5.3.3. Polymer Catalysis
5.3.4. Environmental
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Zeolites
6.1.2. Metals
6.1.3. Chemical Compounds
6.1.4. Enzymes
6.1.5. Organometallic Materials
6.2. Market Analysis, Insights and Forecast - by Process
6.2.1. Recycling
6.2.2. Regeneration
6.2.3. Rejuvenation
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Petroleum Refining
6.3.2. Chemical Synthesis
6.3.3. Polymer Catalysis
6.3.4. Environmental
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Zeolites
7.1.2. Metals
7.1.3. Chemical Compounds
7.1.4. Enzymes
7.1.5. Organometallic Materials
7.2. Market Analysis, Insights and Forecast - by Process
7.2.1. Recycling
7.2.2. Regeneration
7.2.3. Rejuvenation
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Petroleum Refining
7.3.2. Chemical Synthesis
7.3.3. Polymer Catalysis
7.3.4. Environmental
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Zeolites
8.1.2. Metals
8.1.3. Chemical Compounds
8.1.4. Enzymes
8.1.5. Organometallic Materials
8.2. Market Analysis, Insights and Forecast - by Process
8.2.1. Recycling
8.2.2. Regeneration
8.2.3. Rejuvenation
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Petroleum Refining
8.3.2. Chemical Synthesis
8.3.3. Polymer Catalysis
8.3.4. Environmental
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Zeolites
9.1.2. Metals
9.1.3. Chemical Compounds
9.1.4. Enzymes
9.1.5. Organometallic Materials
9.2. Market Analysis, Insights and Forecast - by Process
9.2.1. Recycling
9.2.2. Regeneration
9.2.3. Rejuvenation
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Petroleum Refining
9.3.2. Chemical Synthesis
9.3.3. Polymer Catalysis
9.3.4. Environmental
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Zeolites
10.1.2. Metals
10.1.3. Chemical Compounds
10.1.4. Enzymes
10.1.5. Organometallic Materials
10.2. Market Analysis, Insights and Forecast - by Process
10.2.1. Recycling
10.2.2. Regeneration
10.2.3. Rejuvenation
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Petroleum Refining
10.3.2. Chemical Synthesis
10.3.3. Polymer Catalysis
10.3.4. Environmental
11. Competitive Analysis
11.1. Company Profiles
11.1.1. ALBEMARLE CORPORATION
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. BASF SE
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. DOW CHEMICAL COMPANY
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. W.R. GRACE & CO.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. CHEVRON PHILLIPS CHEMICAL COMPANY LLC
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. CLARIANT AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. EXXONMOBIL CORPORATION
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. DORF KETAL CHEMICALS (I) PVT. LTD.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. EVONIK INDUSTRIES AG
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. JOHNSON MATTHEY
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Catalyst Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Catalyst Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Catalyst Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Catalyst Market Revenue (billion), by Process 2026 & 2034
Figure 5: North America Catalyst Market Revenue Share (%), by Process 2026 & 2034
Figure 6: North America Catalyst Market Revenue (billion), by Application 2026 & 2034
Figure 7: North America Catalyst Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Catalyst Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Catalyst Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Catalyst Market Revenue (billion), by Type 2026 & 2034
Figure 11: South America Catalyst Market Revenue Share (%), by Type 2026 & 2034
Figure 12: South America Catalyst Market Revenue (billion), by Process 2026 & 2034
Figure 13: South America Catalyst Market Revenue Share (%), by Process 2026 & 2034
Figure 14: South America Catalyst Market Revenue (billion), by Application 2026 & 2034
Figure 15: South America Catalyst Market Revenue Share (%), by Application 2026 & 2034
Figure 16: South America Catalyst Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Catalyst Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Catalyst Market Revenue (billion), by Type 2026 & 2034
Figure 19: Europe Catalyst Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Europe Catalyst Market Revenue (billion), by Process 2026 & 2034
Figure 21: Europe Catalyst Market Revenue Share (%), by Process 2026 & 2034
Figure 22: Europe Catalyst Market Revenue (billion), by Application 2026 & 2034
Figure 23: Europe Catalyst Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Catalyst Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Catalyst Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Catalyst Market Revenue (billion), by Type 2026 & 2034
Figure 27: Middle East & Africa Catalyst Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa Catalyst Market Revenue (billion), by Process 2026 & 2034
Figure 29: Middle East & Africa Catalyst Market Revenue Share (%), by Process 2026 & 2034
Figure 30: Middle East & Africa Catalyst Market Revenue (billion), by Application 2026 & 2034
Figure 31: Middle East & Africa Catalyst Market Revenue Share (%), by Application 2026 & 2034
Figure 32: Middle East & Africa Catalyst Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Catalyst Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Catalyst Market Revenue (billion), by Type 2026 & 2034
Figure 35: Asia Pacific Catalyst Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Asia Pacific Catalyst Market Revenue (billion), by Process 2026 & 2034
Figure 37: Asia Pacific Catalyst Market Revenue Share (%), by Process 2026 & 2034
Figure 38: Asia Pacific Catalyst Market Revenue (billion), by Application 2026 & 2034
Figure 39: Asia Pacific Catalyst Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia Pacific Catalyst Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Catalyst Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Catalyst Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Catalyst Market Revenue billion Forecast, by Process 2020 & 2034
Table 52: Rest of Asia Pacific Catalyst Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of this study, with secondary research at 20–30%. The split prioritizes direct validation with catalyst buyers, licensors, and plant operators.
We interview 5 specific company types across the catalyst value chain: zeolite catalyst manufacturers for fluid catalytic cracking (FCC) units; platinum-group metal (PGM) catalyst refiners and reclaimers; catalyst regeneration and recycling service providers for refinery hydrotreaters; petrochemical technology licensors integrating catalyst systems; and enzyme catalyst producers for industrial biocatalysis.
Stakeholder interviews target 4 job titles: Refinery Process Technology Director, Catalyst Procurement Manager, Chemical Synthesis R&D Lead, and Environmental Compliance Manager. These roles control specification, qualification, and replacement decisions.
Primary interviews capture plant-level catalyst loading, replacement cycles, precious metal content, and regeneration economics. This is essential for the Petroleum Refining Catalyst Market, Chemical Synthesis Catalyst Market, Polymer Catalysis Market, and Environmental Catalyst Market.
Interview quotas are stratified by region: Asia-Pacific 35%, North America 25%, Europe 20%, Middle East & Africa 12%, and South America 8%.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Refinery Process Technology Director
30%
Catalyst Procurement Manager
25%
Chemical Synthesis R&D Lead
25%
Environmental Compliance Manager
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Zeolite catalyst manufacturers for FCC units
28%
Platinum-group metal catalyst refiners and reclaimers
24%
Catalyst regeneration and recycling service providers
18%
Petrochemical technology licensors integrating catalyst systems
17%
Enzyme catalyst producers for industrial biocatalysis
We benchmark supply contracts, catalyst pricing, and plant utilization against these sources, without relying on market research websites.
Every report is updated to the date of purchase, with data cutoffs and revision notes included in the appendix.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation. Bottom-up estimates are built from unit-level catalyst consumption and replacement cycles.
Specific quantitative metrics include: number of operating FCC units globally; average catalyst replacement cycle in refinery hydrotreaters (years); platinum-group metal loadings per cubic meter of catalyst; petrochemical capacity utilization rates by region; and catalyst regeneration capacity in tons per year.
These metrics feed volume estimates for the Industrial Catalyst Market, Zeolite Catalyst Market, Metal Catalyst Market, and Enzyme Catalyst Market. Price and mix analysis converts volume to value.
Regional demand models incorporate refinery capacity additions, chemical plant permits, emissions standards, and feedstock sulfur content. Scenario ranges are set at ±10% around the base case.
Top-down validation uses global refining throughput, petrochemical output, and emissions-control equipment sales. Discrepancies above 5% trigger re-interview and data reconciliation.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, based on source triangulation, respondent validation, and historical forecast back-testing.
All primary respondents are screened for direct involvement in catalyst specification, procurement, or plant operations. At least 20% of interviews are re-contacted for verification.
Financial data are cross-checked against Bloomberg, Factiva, Hoovers, and PitchBook. Regulatory data are validated against EPA, DOE, and ECHA publications.
We apply outlier detection, confidence scoring, and sensitivity analysis for precious metal prices and capacity utilization. Final estimates are reviewed by a senior analyst before publication.
Any revision after purchase is logged and dated. The Catalyst Market report includes version control for all tables and forecasts.
Frequently Asked Questions
1. What are the primary growth drivers and demand catalysts for the Catalyst Market?
The main drivers are refinery and petrochemical capacity additions, stringent fuel and emissions rules, and polymer demand growth. Asia-Pacific accounts for 42% of 2025 revenue, and the market is projected to expand at a 4.9% CAGR from $45.09 billion in 2025.
2. Which product types and applications lead the Catalyst Market?
Petroleum refining is the largest application at 38% of revenue, followed by chemical synthesis at 24% and polymer catalysis at 18%. By type, zeolites lead at 31%, while metal catalysts hold 24% and enzyme catalysts are the fastest-growing at 6.8% CAGR.
3. How do raw material sourcing and supply chain issues affect the Catalyst Market?
Platinum-group metals, rare earths, and zeolite precursors are critical inputs. China controls over 60% of rare earth mining and 85% of refining, and platinum-group metal prices can swing 30–40% annually, creating cost and availability risks.
4. Which region dominates the Catalyst Market and why?
Asia-Pacific dominates with 42% of global revenue, supported by refinery expansions in China and India, coal-to-chemicals capacity, and polymer plant investment. Its 5.8% CAGR is the highest among major regions.
5. How do regulations and compliance affect the Catalyst Market?
Regulations such as Euro 7, China VI, and IMO 2020 tighten NOx, SOx, and sulfur limits, boosting the Environmental Catalyst Market. REACH and EPA rules also drive reformulation away from heavy metals, raising R&D costs but supporting regeneration and recycling services.
6. What recent developments, M&A, or product launches shape the Catalyst Market?
In 2023, W.R. Grace acquired Albemarle’s catalysts business for $300 million, consolidating hydroprocessing supply. BASF expanded refining catalyst capacity in China in 2024, and Johnson Matthey signed a blue hydrogen catalyst supply agreement.