Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Glacial Acrylic Acid Market CAGR 3.7% to 2033
Glacial Acrylic Acid Market
Glacial Acrylic Acid Market CAGR 3.7% to 2033
Glacial Acrylic Acid Market by Application (Nappies, Adult and Feminine Hygiene, Detergents, Adhesives, Coatings and Sealants, Water Treatment, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 204
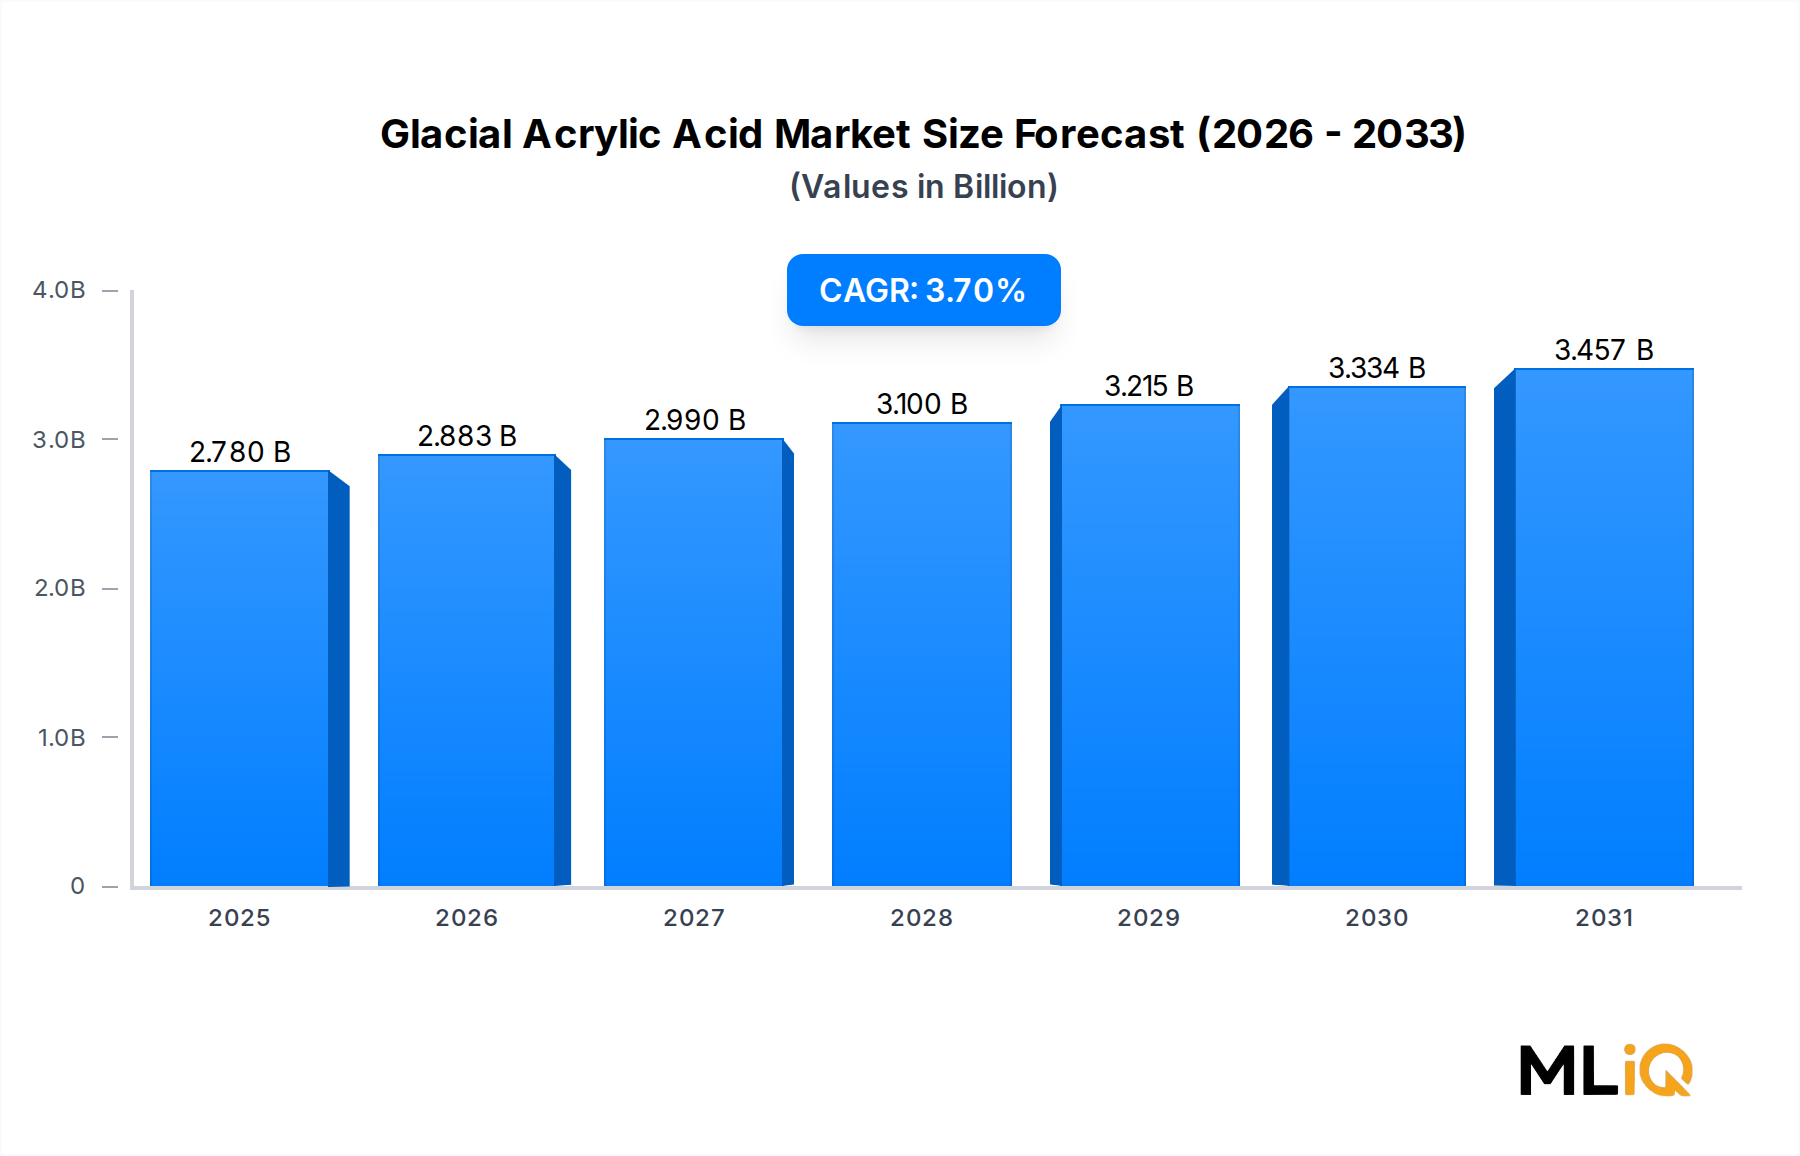
The Glacial Acrylic Acid Market is sized at USD 2.78 billion in 2025 and is projected to reach USD 3.72 billion by 2033, expanding at a 3.7% CAGR. Demand is anchored in the Superabsorbent Polymer Market, which consumes over 60% of global glacial acrylic acid output for hygiene applications. The broader Acrylic Acid Derivatives Market remains closely tied to propylene feedstock economics and hygiene product consumption cycles.
Glacial Acrylic Acid Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.780 B
2025
2.883 B
2026
2.990 B
2027
3.100 B
2028
3.215 B
2029
3.334 B
2030
3.457 B
2031
Key momentum factors:
Hygiene Products Market volume growth in emerging Asia and Latin America adds 1.8-2.2% annual demand.
Bio-based Acrylic Acid Market capacity remains below 5% of total supply but attracts R&D capital.
Adhesives and Sealants Market demand is cyclical, tracking construction and packaging activity.
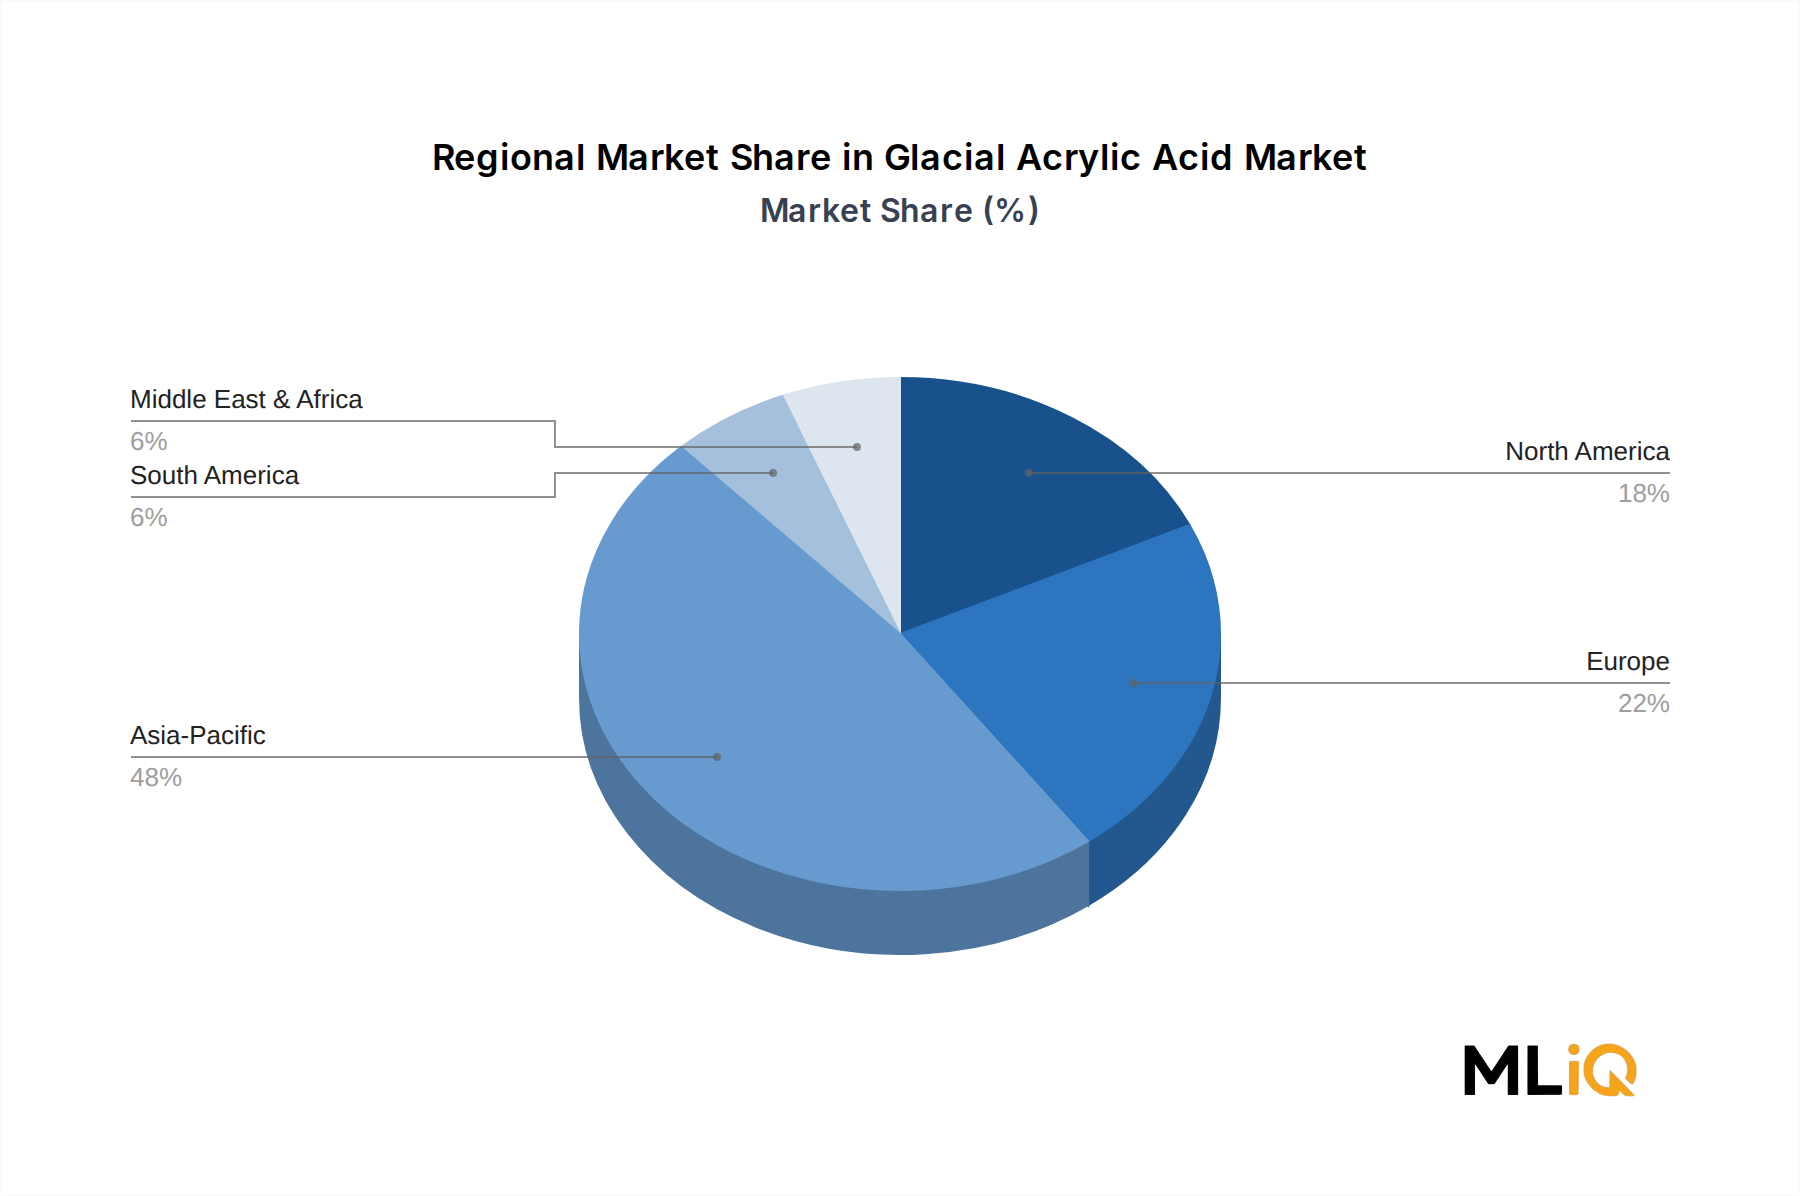
The market shows moderate concentration: the top five producers control approximately 55% of global capacity. Asia-Pacific holds a 48% volume share, with China alone operating more than 40% of global capacity. Margin pressure persists because propylene prices ranged between USD 850 and USD 1,050 per metric ton in 2024, representing 55-65% of cash production cost.
Strategic takeaway: Capacity rationalization in Europe and North America will offset Chinese supply additions through 2027. Producers prioritizing SAP-grade glacial acrylic acid and bio-based routes can defend 150-250 basis points of EBITDA margin above commodity ester producers.
Segment Deep-Dive: Nappies Dominance in Glacial Acrylic Acid Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Nappies
4.1%
42%
Infant hygiene in Asia-Pacific and Africa
Adult and Feminine Hygiene
4.5%
23%
Aging population in Europe and Japan
Adhesives
3.2%
15%
Packaging and construction adhesives
Detergents
2.8%
8%
Industrial and household cleaning
Coatings and Sealants
2.6%
7%
Architectural coatings and sealants
Water Treatment
3.0%
5%
Industrial water recycling
Nappies: Largest Revenue Segment
Nappies generate USD 1.17 billion in glacial acrylic acid demand in 2025, equivalent to 42% of total revenue. This segment relies on superabsorbent polymer (SAP) grade acrylic acid, which requires 99.5%+ purity and low residual monomer. The Superabsorbent Polymer Market absorbs nearly all nappy-grade acrylic acid, leaving limited flexibility for spot buyers. Growth is concentrated in India, Indonesia, and Nigeria, where diaper penetration remains below 30%.
Adult and Feminine Hygiene: Fastest-Growing
Adult incontinence and feminine hygiene products represent 23% of demand and grow at 4.5% CAGR, the highest among all segments. Japan, Germany, and the United States account for 60% of this sub-segment. Producers with SAP-grade capability, including Nippon Shokubai and BASF SE, capture premium pricing of USD 50-80 per metric ton above technical grade.
Margin Pressures
Feedstock volatility: propylene price swings of +/-15% compress segment margins by 200-300 basis points.
Overcapacity in acrylate esters: Chinese acrylate ester producers push excess glacial acrylic acid into hygiene markets, capping price increases.
Regulatory compliance: REACH and EPA restrictions on residual acrylic acid add USD 20-35 per metric ton in testing and documentation costs.
The Hygiene Products Market remains the primary demand engine, but Adhesives and Sealants Market and Water Treatment Chemicals Market provide diversification against hygiene seasonality.
Rising hygiene product demand in emerging economies
High
Long term
Driver
Bio-based acrylic acid commercialization
Medium
Long term
Driver
Industrial water treatment and recycling mandates
Medium
Short term
Driver
Acrylate ester demand for coatings and adhesives
Medium
Short term
Restraint
Propylene feedstock price volatility
High
Short term
Restraint
Stringent environmental and safety regulations
Medium
Long term
Restraint
Chinese overcapacity and export pressure
High
Short term
Restraint
Substitution by bio-based and alternative chemistries
Low
Long term
Drivers: The Glacial Acrylic Acid Market growth rate of 3.7% is supported by population growth, urbanization, and hygiene awareness. The Hygiene Products Market adds 1.5-2.0 million metric tons of SAP demand annually through 2030. Water Treatment Chemicals Market growth of 3.0% CAGR pulls acrylic acid into scale inhibitors and dispersants.
Restraints: The Propylene Market remains the dominant cost variable. A USD 100 per metric ton rise in propylene raises glacial acrylic acid cash cost by USD 65-75 per metric ton. Environmental regulations in Europe and the United States require Best Available Techniques (BAT) for acrylic acid plants, adding USD 15-25 million in retrofit capital for older facilities.
China capacity additions: more than 1.2 million metric tons of new acrylic acid capacity announced between 2024 and 2027, primarily for domestic SAP and acrylate esters.
Bio-based substitution: Bio-based Acrylic Acid Market capacity remains under 150,000 metric tons globally, limiting near-term displacement of fossil-based material.
Crude Oil Market linkage: naphtha-based propylene supply correlates with Brent crude at a 0.65-0.75 coefficient, transmitting oil price shocks into acrylic acid contracts.
Dow Inc: Operates integrated acrylic acid and acrylate ester units in the United States and Europe. Its Acrylate Esters Market position benefits from captive propylene supply and strong formulation partnerships.
BASF SE: The largest global producer of glacial acrylic acid and SAP. Its Verbund integration and Zhanjiang expansion target Hygiene Products Market growth in Asia.
Nippon Shokubai Co Ltd: Holds leading SAP-grade purity and long-term contracts with Japanese and Western nappy manufacturers. It captures premium pricing in the Adult and Feminine Hygiene segment.
LG Chem Ltd: Expands acrylic acid capacity in South Korea to serve Chinese and Southeast Asian SAP producers. Its cost position pressures European exporters.
Arkema: Focuses on specialty acrylates and water treatment chemicals. Its R&D into Bio-based Acrylic Acid Market routes differentiates its portfolio from commodity producers.
Formosa Plastics Corporation: Leverages low-cost feedstock and scale in Taiwan and China. It supplies technical-grade acrylic acid into the Water Treatment Chemicals Market and acrylate esters.
Novomer Inc: Develops CO2-to-acrylic acid catalysts. The technology remains pre-commercial but targets licensees seeking lower-carbon acrylic acid.
Mitsubishi Chemical Holdings Corporation: Maintains global acrylate derivative distribution and serves coatings, adhesives, and electronics customers with high-purity grades.
Strategic Milestones & Recent Developments in Glacial Acrylic Acid Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Zhanjiang acrylic acid expansion
2024
BASF SE
Capacity expansion
Adds Asia supply for SAP and acrylates
SAP grade capacity debottleneck
2023
Nippon Shokubai Co Ltd
Capacity expansion
Supports adult hygiene demand
Acrylic acid plant optimization
2023
Dow Inc
Operational upgrade
Reduces energy cost by 8-12%
Bio-based acrylic acid licensing
2024
Novomer Inc
Partnership
Advances CO2-based route to pilot
Acrylate ester capacity addition
2023
LG Chem Ltd
Capacity expansion
Increases Asian export pressure
Water treatment grade launch
2024
Arkema
Product launch
Targets industrial water recycling
2024 - BASF SE: Announced Zhanjiang acrylic acid capacity as part of its Asian Verbund. The project strengthens supply for the Superabsorbent Polymer Market and reduces logistics costs for Chinese hygiene customers.
2023 - Nippon Shokubai Co Ltd: Debottlenecked SAP-grade acrylic acid lines in Japan. The move protects its premium position in adult and feminine hygiene applications.
2023 - Dow Inc: Upgraded acrylic acid plant controls and energy recovery. The operational change lowers cash cost and supports margin defense in Europe and North America.
2024 - Novomer Inc: Licensed its CO2-based acrylic acid process to an undisclosed partner for pilot validation. Success would create a low-carbon feedstock alternative for the Bio-based Acrylic Acid Market.
2023 - LG Chem Ltd: Added acrylate ester capacity in South Korea. The expansion increases glacial acrylic acid integration and export volumes into Asia-Pacific.
2024 - Arkema: Launched a water-treatment-grade acrylic acid polymer line. The product targets scale inhibition and dispersant demand in the Water Treatment Chemicals Market.
Asia-Pacific: Largest and fastest-growing at 4.2% CAGR. China controls 40%+ of global capacity, while India and ASEAN add diaper and SAP demand. Regulatory enforcement varies, with China GB standards tightening residual monomer limits.
North America: Mature market with 3.0% CAGR. Demand is driven by adult hygiene, coatings, and water treatment. EPA TSCA and Clean Air Act rules set high compliance costs.
Europe: Slowest growth at 2.8% CAGR due to market maturity and substitution. REACH authorization and EU Taxonomy pressure producers to lower carbon intensity. Adult hygiene remains the growth pocket.
LAMEA: Fastest-growing at 4.5% CAGR from a small base. Brazil, Turkey, and GCC countries invest in hygiene production and industrial water treatment. Regulatory frameworks are less stringent, enabling faster capacity additions.
Fastest-growing vs. mature:
Fastest-growing: LAMEA and Asia-Pacific, driven by diaper penetration below 40% and rising SAP capacity.
Most mature: Europe and North America, where demand grows at 2.8-3.0% and competition focuses on product grade and sustainability.
Trade flows: Asia-Pacific exports 35-40% of its acrylic acid and acrylate esters, primarily to LAMEA and Europe.
Supply Chain & Raw Material Dynamics: Glacial Acrylic Acid Market
Upstream Input
Share of Cash Cost
Price Trend 2024
Supply Risk
Propylene
55-65%
USD 850-1,050/metric ton
High
Crude oil/naphtha
15-20%
USD 75-85/bbl Brent
Medium-High
Natural gas
5-10%
USD 2.5-3.5/MMBtu
Medium
Bio-based feedstock
<5%
USD 1,200-1,600/metric ton
Low
The Propylene Market is the primary upstream dependency. Glacial acrylic acid production uses propane dehydrogenation (PDH) or steam cracker propylene, linking costs to Crude Oil Market movements. A 10% rise in Brent crude typically lifts propylene by 6-8% within one quarter, passing through to acrylic acid with a one- to two-month lag.
Supply chain risks:
Geographic concentration:60% of propylene supply for acrylic acid originates in Asia-Pacific and North America. Unplanned cracker outages can tighten spot markets by 10-15%.
Logistics: glacial acrylic acid requires stainless steel or lined vessels and polymerization inhibitor (MEHQ) dosing. Shipping delays in 2021-2022 added USD 40-60 per metric ton to delivered costs.
Bio-based feedstock: Bio-based Acrylic Acid Market relies on glycerol, lactic acid, or CO2. These routes cost 1.5-2.0x fossil-based cash cost at current scale.
Inventory strategy: major buyers hold 30-45 days of SAP-grade acrylic acid, up from 20-30 days before 2020, to buffer supply shocks.
Investment, M&A & Funding Activity in Glacial Acrylic Acid Market
Investment Type
2022-2024 Activity
Target Sub-Segment
Strategic Acquirer/Investor
M&A
Limited large deals
SAP-grade acrylic acid
BASF SE, Nippon Shokubai Co Ltd
Growth capital
Under USD 100 million disclosed
Bio-based Acrylic Acid Market
Novomer Inc, venture funds
Capacity investment
USD 1.5-2.0 billion announced
Asia-Pacific acrylic acid
LG Chem Ltd, Formosa Plastics
Joint ventures
3-4 APAC partnerships
Acrylate Esters Market
Mitsubishi Chemical, regional producers
M&A activity in the Glacial Acrylic Acid Market remains constrained by high asset replacement costs and environmental liabilities. Strategic buyers focus on SAP-grade capacity and backward integration into propylene. Private equity interest is low because acrylic acid plants require USD 300-500 million greenfield capital and long permitting cycles.
Capital flows favor:
Bio-based Acrylic Acid Market: Novomer Inc and several venture-backed startups attracted under USD 100 million in disclosed funding since 2020. Investors target CO2 utilization and lower-carbon acrylic acid.
Asia-Pacific capacity: LG Chem Ltd, Formosa Plastics Corporation, and Chinese producers announced USD 1.5-2.0 billion in new acrylic acid and acrylate ester projects through 2027.
Water Treatment Chemicals Market: Arkema and specialty chemical firms pursue bolt-on acquisitions for polymer and dispersant technology.
Strategic partnerships: BASF SE and hygiene OEMs sign 3-5 year supply agreements for SAP-grade glacial acrylic acid, reducing merchant market liquidity.
Outlook: Investment will concentrate on Asia-Pacific and bio-based routes, while European and North American assets face retrofit costs and carbon pricing pressure.
Glacial Acrylic Acid Market Segmentation
1. Application
1.1. Nappies
1.2. Adult and Feminine Hygiene
1.3. Detergents
1.4. Adhesives
1.5. Coatings and Sealants
1.6. Water Treatment
1.7. Others
Glacial Acrylic Acid Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Glacial Acrylic Acid Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.7% from 2020-2034
Segmentation
By Application
Nappies
Adult and Feminine Hygiene
Detergents
Adhesives
Coatings and Sealants
Water Treatment
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Nappies
5.1.2. Adult and Feminine Hygiene
5.1.3. Detergents
5.1.4. Adhesives
5.1.5. Coatings and Sealants
5.1.6. Water Treatment
5.1.7. Others
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Nappies
6.1.2. Adult and Feminine Hygiene
6.1.3. Detergents
6.1.4. Adhesives
6.1.5. Coatings and Sealants
6.1.6. Water Treatment
6.1.7. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Nappies
7.1.2. Adult and Feminine Hygiene
7.1.3. Detergents
7.1.4. Adhesives
7.1.5. Coatings and Sealants
7.1.6. Water Treatment
7.1.7. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Nappies
8.1.2. Adult and Feminine Hygiene
8.1.3. Detergents
8.1.4. Adhesives
8.1.5. Coatings and Sealants
8.1.6. Water Treatment
8.1.7. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Nappies
9.1.2. Adult and Feminine Hygiene
9.1.3. Detergents
9.1.4. Adhesives
9.1.5. Coatings and Sealants
9.1.6. Water Treatment
9.1.7. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Nappies
10.1.2. Adult and Feminine Hygiene
10.1.3. Detergents
10.1.4. Adhesives
10.1.5. Coatings and Sealants
10.1.6. Water Treatment
10.1.7. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. DOW INC
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Nippon Shokubai Co Ltd
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. BASF PETRONAS Chemicals Sdn. Bhd.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. BASF SE
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Formosa Plastics Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Hexion Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Mitsubishi Chemical Holdings Corporation
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. LG Chem Ltd
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Arkema
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Novomer Inc
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Shandong kaitai petrochemical Co.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Ltd
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Sanmu Group
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Glacial Acrylic Acid Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Glacial Acrylic Acid Market Revenue (billion), by Application 2026 & 2034
Figure 3: North America Glacial Acrylic Acid Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Glacial Acrylic Acid Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Glacial Acrylic Acid Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Glacial Acrylic Acid Market Revenue (billion), by Application 2026 & 2034
Figure 7: South America Glacial Acrylic Acid Market Revenue Share (%), by Application 2026 & 2034
Figure 8: South America Glacial Acrylic Acid Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Glacial Acrylic Acid Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Glacial Acrylic Acid Market Revenue (billion), by Application 2026 & 2034
Figure 11: Europe Glacial Acrylic Acid Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe Glacial Acrylic Acid Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Glacial Acrylic Acid Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Glacial Acrylic Acid Market Revenue (billion), by Application 2026 & 2034
Figure 15: Middle East & Africa Glacial Acrylic Acid Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Middle East & Africa Glacial Acrylic Acid Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Glacial Acrylic Acid Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Glacial Acrylic Acid Market Revenue (billion), by Application 2026 & 2034
Figure 19: Asia Pacific Glacial Acrylic Acid Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Asia Pacific Glacial Acrylic Acid Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Glacial Acrylic Acid Market Revenue Share (%), by Country 2026 & 2034
Table 40: Rest of Asia Pacific Glacial Acrylic Acid Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
The Glacial Acrylic Acid Market study derives 70-80% of inputs from primary research, including interviews with propylene oxidation reactor operators, superabsorbent polymer (SAP) manufacturers, acrylate ester producers, hygiene absorbent product OEMs, and industrial coating formulators.
We conduct structured interviews with SAP Procurement Directors, Acrylic Acid Plant Operations Managers, Hygiene Product Development Leads, and Chemical Regulatory Affairs Managers across Asia-Pacific, Europe, and North America.
We avoid market research websites and rely on .gov, .org, and trade association publications for capacity, trade, and compliance benchmarks.
All data is updated to the date of purchase, with version tracking for every forecast table and vendor profile.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously. Top-down sizing applies global acrylic acid capacity and regional trade data to the 2025 base of USD 2.78 billion.
Bottom-up sizing multiplies quantitative metrics including global superabsorbent polymer capacity utilization rate, average propylene feedstock cost per metric ton, acrylic acid plant nameplate capacity by region, and diaper production volume per 1,000 population.
Multi-level data triangulation validates each segment, region, and application forecast against at least three independent input sets.
The model estimates an 85-90% data accuracy level, with confidence intervals narrowed through primary interviews and plant-level verification.
Forecasts cover 2026-2034, with 2025 as the base year and 3.7% CAGR applied to the Glacial Acrylic Acid Market.
Data Accuracy & Quality Check
Every data point passes a three-stage check: source validation, cross-source reconciliation, and analyst review by a senior market analyst.
We flag deviations above 5% between top-down and bottom-up estimates and resolve them through targeted follow-up interviews.
Company-level data is verified against annual reports, SEC filings, and EU REACH registration dossiers.
Final deliverables are updated to the date of purchase and include a revision log for any post-publication corrections.
Frequently Asked Questions
1. How does sustainability and ESG pressure affect the Glacial Acrylic Acid Market?
Sustainability pressure is reshaping feedstock choices. Bio-based Acrylic Acid Market capacity remains below 150,000 metric tons globally, but Novomer Inc and Arkema are advancing CO2- and glycerol-based routes. Major producers face EU carbon pricing that adds EUR 25-40 per metric ton for fossil-based output, pushing investment toward lower-carbon processes.
2. Which region dominates the Glacial Acrylic Acid Market and why?
Asia-Pacific dominates with a 48% volume share in 2025, valued at USD 1.33 billion. China alone operates more than 40% of global capacity due to low-cost propylene, integrated acrylic acid and SAP plants, and strong domestic hygiene demand. The region also benefits from lower compliance costs than Europe or North America.
3. What technological innovations are shaping the Glacial Acrylic Acid Market?
Key innovations include high-selectivity oxidation catalysts, energy recovery in acrylic acid reactors, and bio-based routes using glycerol or captured CO2. BASF SE and Nippon Shokubai Co Ltd have improved SAP-grade purity above 99.5%, reducing residual monomer. Novomer Inc CO2-to-acrylic acid platform targets a 30-50% lower carbon footprint at pilot scale.
4. How is investment activity developing in the Glacial Acrylic Acid Market?
Disclosed venture capital remains under USD 100 million since 2020, concentrated in Bio-based Acrylic Acid Market startups such as Novomer Inc. Strategic capital targets Asia-Pacific capacity, with LG Chem Ltd and Formosa Plastics Corporation announcing USD 1.5-2.0 billion in projects through 2027. Private equity interest is limited by USD 300-500 million greenfield capital requirements.
5. What are the pricing trends and cost structure in the Glacial Acrylic Acid Market?
Prices ranged from USD 1,150 to USD 1,350 per metric ton in 2024, tracking propylene at USD 850-1,050 per metric ton. Propylene represents 55-65% of cash cost, and a USD 100 per metric ton propylene rise lifts acrylic acid cost by USD 65-75 per metric ton. Natural gas and logistics add another 10-15% to delivered cost.
6. Which regulations affect the Glacial Acrylic Acid Market?
EU REACH, U.S. EPA TSCA, and China GB standards govern residual acrylic acid limits, worker exposure, and emissions. Compliance adds USD 20-35 per metric ton in testing and documentation, and European plants face Best Available Techniques retrofits costing USD 15-25 million. These rules raise barriers for new entrants but favor integrated producers like BASF SE and Dow Inc.