Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Electronics & Electrical Ceramics Market Trends to 2033
Electronics and Electrical Ceramics Market
Electronics & Electrical Ceramics Market Trends to 2033
Electronics and Electrical Ceramics Market by Product Type (Monolithic Ceramics, Ceramic Matrix Composites, Ceramic Coatings, Others), by End-user Industry (Consumer Appliances, Power Grids, Medical Devices, Others), by Material Type (Alumina Ceramics, Titanate Ceramics, Zirconia Ceramics, Silica Ceramics, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Electronics and Electrical Ceramics Market
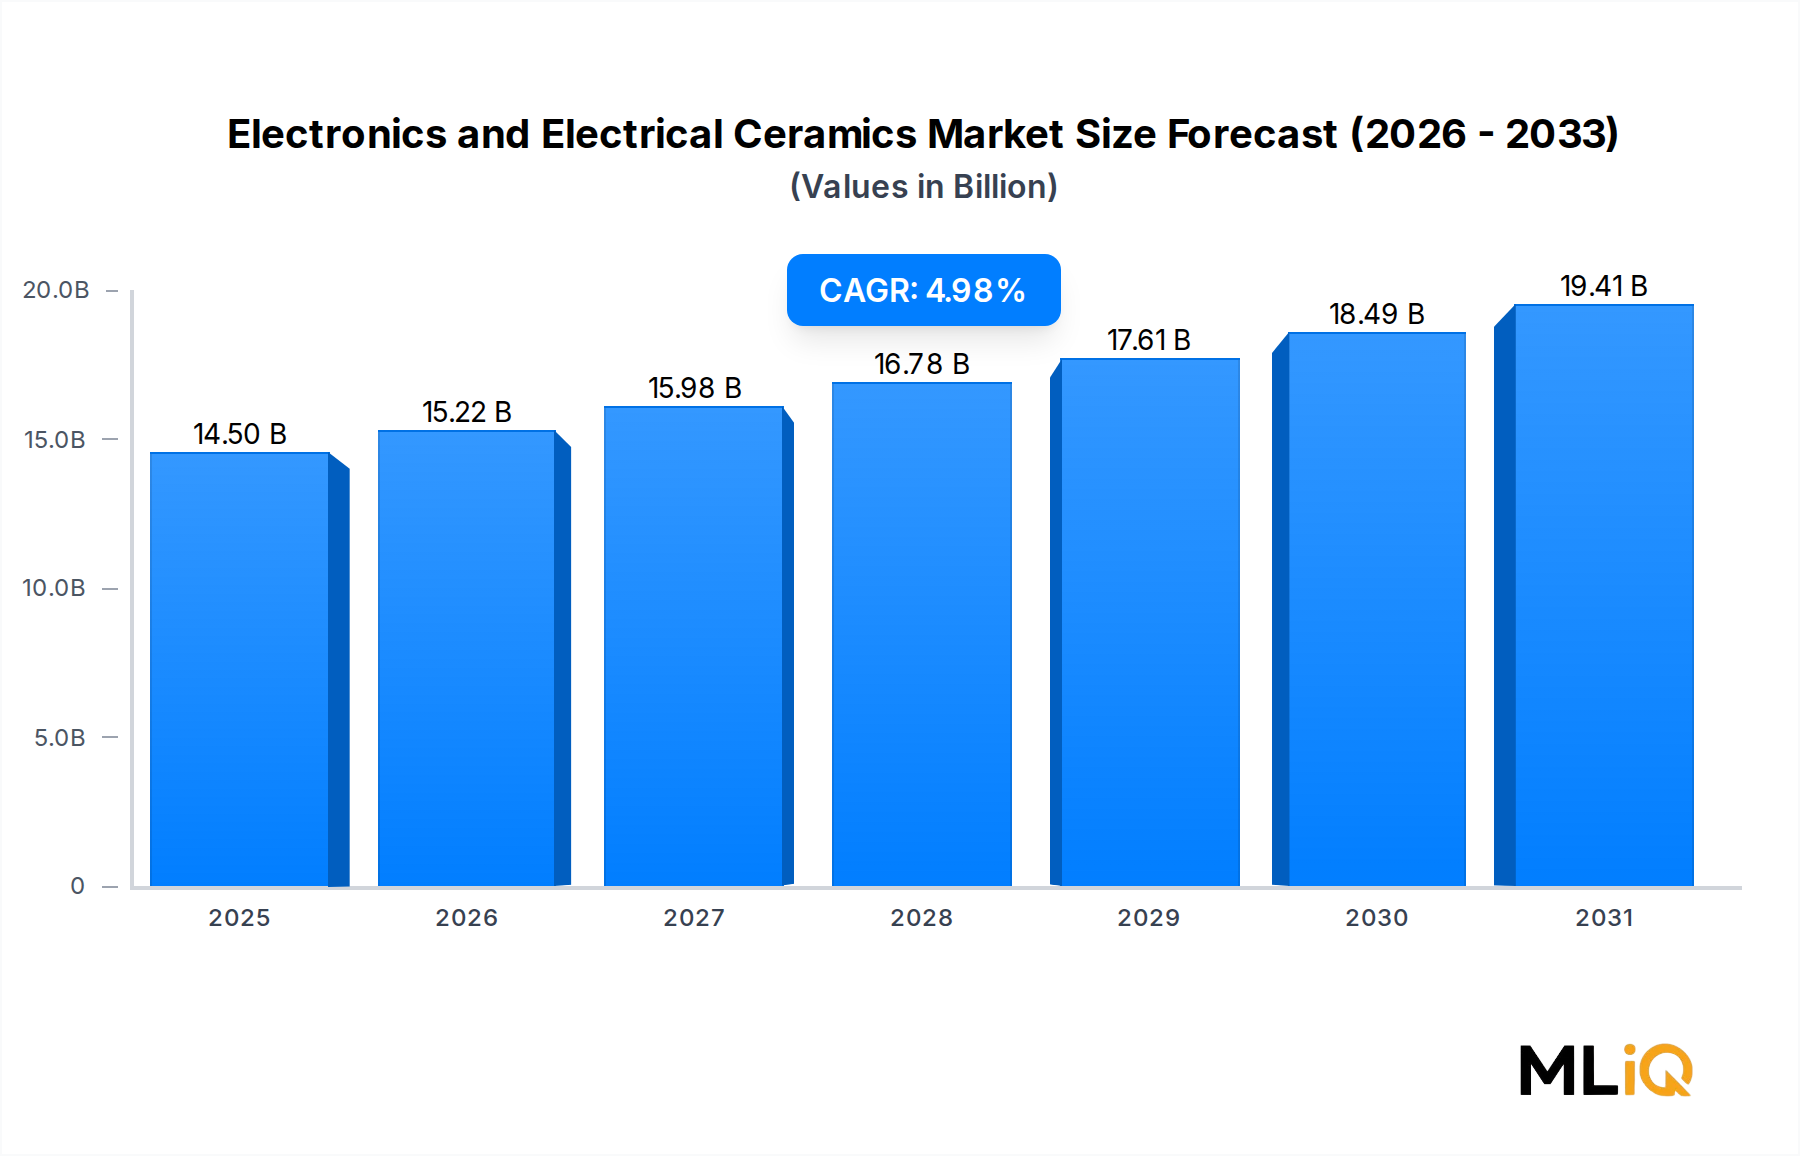
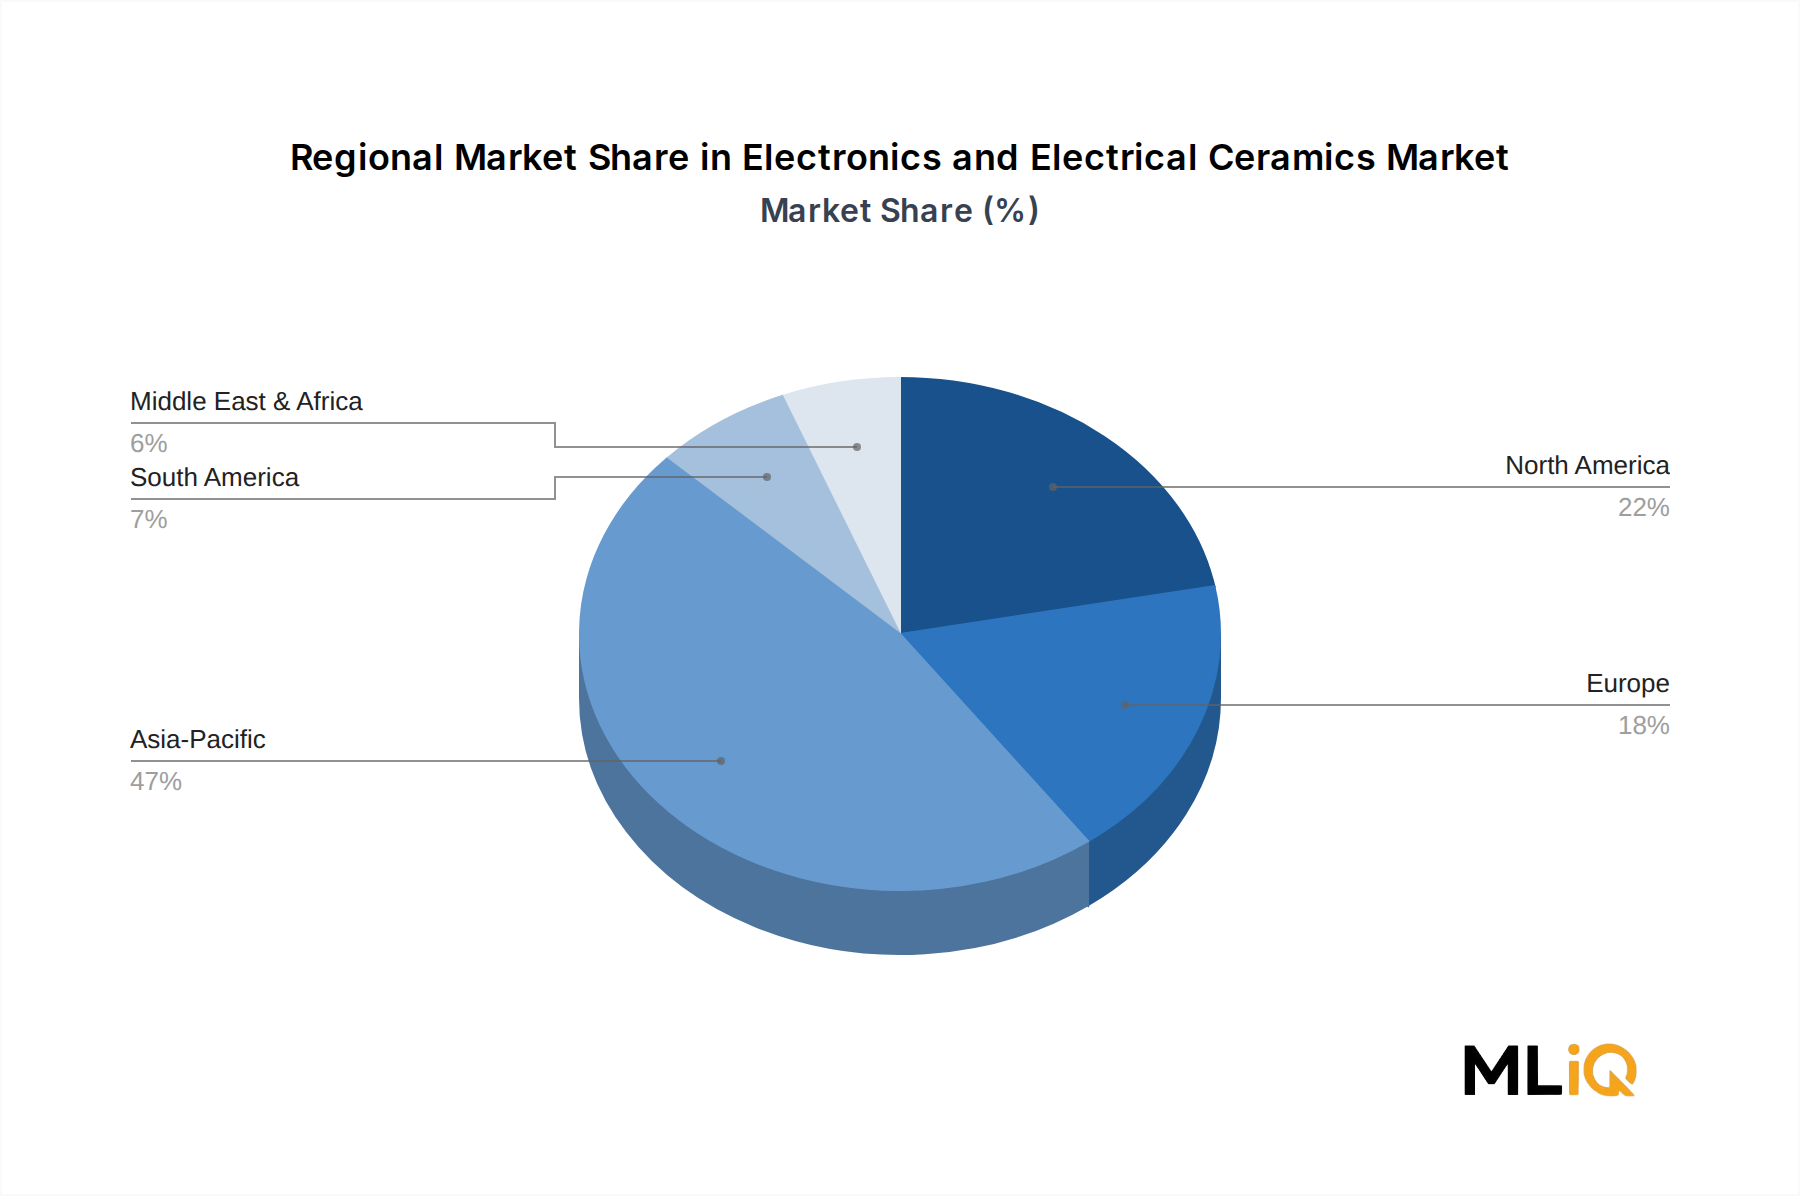
The Technical Ceramics Market is projected to expand from USD 14.5 billion in 2025 to USD 21.4 billion by 2033, advancing at a 4.98% CAGR. Asia-Pacific controls 48% of global consumption, supported by capacitor, insulator, and substrate production in China, Japan, and South Korea. Monolithic ceramics account for 58% of product revenue, while consumer appliances represent the largest end-user block at 31% of demand.
Electronics and Electrical Ceramics Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
14.50 B
2025
15.22 B
2026
15.98 B
2027
16.78 B
2028
17.61 B
2029
18.49 B
2030
19.41 B
2031
Power electronics miniaturization lifts multilayer ceramic capacitor content per device by 8–12% annually.
Grid modernization in India, China, and the GCC requires high-voltage ceramic insulators and surge arresters.
Medical device ceramics benefit from zirconia implants and alumina components, with procedure volumes rising 6% yearly.
Raw material volatility for alumina and barium titanate remains the primary margin risk.
The market remains moderately consolidated. Kyocera Group, Murata Manufacturing, and NGK Insulators lead in high-reliability ceramics, while CeramTec and CoorsTek dominate medical and industrial wear parts. Near-term growth is tied to electric vehicle power modules, 5G infrastructure, and renewable inverter systems. Long-term upside depends on ceramic matrix composite adoption in braking and turbine applications. The forecast period captures a structural shift from metal-alloy components to ceramic alternatives where dielectric strength, thermal stability, and wear resistance justify premium pricing.
Segment Deep-Dive: Monolithic Ceramics Dominance in Electronics and Electrical Ceramics Market
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Monolithic Ceramics Market
5.2%
58%
MLCC, sensors, power electronics
Ceramic Matrix Composites Market
6.1%
14%
Aerospace brake discs, EV brake systems
Ceramic Coatings Market
4.4%
19%
Semiconductor equipment, turbine blades
Revenue Concentration
The Monolithic Ceramics Market generated an estimated USD 8.4 billion in 2025, equal to 58% of total revenue. Sub-segments include multilayer ceramic capacitors, piezoelectric ceramics, varistors, and thermistors. MLCCs alone contribute over 45% of monolithic revenue because every smartphone, EV, and server contains thousands of units. Murata Manufacturing and Kyocera Group hold leading positions in high-capacitance MLCCs.
Ceramic Matrix Composites and Coatings
The Ceramic Matrix Composites Market is smaller but faster-growing at 6.1% CAGR, driven by aircraft brake discs and EV regenerative braking systems. The Ceramic Coatings Market captures 19% share, led by thermal barrier coatings for turbine blades and plasma-resistant coatings for semiconductor etch chambers. CoorsTek and Saint-Gobain supply advanced coating formulations.
Margin Pressures
Energy costs for sintering and hot pressing rose 15–20% in Europe between 2022 and 2024.
High-purity alumina powder prices increased 9% in 2024 due to bauxite supply constraints.
Qualification cycles for medical and aerospace ceramics stretch 18–30 months, limiting rapid capacity response.
Price competition from lower-cost Chinese monolithic ceramic producers compresses margins in consumer-grade segments.
Monolithic ceramics retain dominance because they combine mature tape-casting and sintering processes with high dielectric strength. However, CMC and coating segments offer higher margins where performance requirements justify premium pricing. Suppliers that invest in automated inspection and near-net-shape forming reduce scrap rates by 12–18%, partially offsetting input cost inflation.
Primary Market Drivers & Growth Restraints in Electronics and Electrical Ceramics Market
Factor Type
Description
Impact Level
Timeline
Driver
Consumer electronics demand for MLCCs and sensors
High
Short term
Driver
Power generation and grid projects in Asia-Pacific
High
Long term
Driver
Medical Device Ceramics Market growth for implants
Medium
Long term
Restraint
Higher cost compared to metals and alloys
High
Short term
Restraint
Raw material price volatility for alumina and zirconia
Medium
Short term
Restraint
Unfavorable conditions from COVID-19 disruption
Low
Resolved
Demand Catalysts
The Consumer Appliances Ceramics Market benefits from smart appliances, induction cooktops, and high-efficiency motors. The Power Grid Ceramics Market is expanding as utilities replace porcelain insulators with high-strength alumina and toughened glass-ceramic alternatives. The Medical Device Ceramics Market is supported by an aging population and increased joint replacement procedures. Each segment adds 2–4 percentage points to overall demand growth.
Bottlenecks
Cost disadvantage: technical ceramics can cost 3–5 times more per kilogram than metals and alloys.
Supply concentration: China produces over 60% of global alumina and rare-earth additives.
COVID-19 disruption: plant shutdowns in 2020–2021 delayed MLCC deliveries by 12–20 weeks.
Regulatory compliance: FDA and IEC standards add testing costs, especially for medical and grid applications.
Despite these restraints, the 4.98% CAGR reflects steady substitution where performance justifies price. Power grid and EV applications are the most resilient demand pools because they are tied to infrastructure spending rather than discretionary consumer spending.
Kyocera Group: Supplies ceramic packages for semiconductors and zirconia implants. Its diversified portfolio reduces exposure to individual end markets.
Murata Manufacturing: Dominates high-capacitance MLCCs. Capacity expansions in Japan and Thailand target automotive and 5G demand.
CeramTec: Focuses on medical-grade alumina and zirconia. Long qualification cycles create switching costs for device OEMs.
CoorsTek: Provides ceramic components for semiconductor equipment. Benefits from etch and deposition chamber demand.
NGK Insulators: Leads in high-voltage insulators and automotive honeycomb ceramics. Grid renewal spending supports steady order books.
IBIDEN: Produces ceramic substrates for advanced packaging. AI server growth increases demand for high-reliability substrates.
Strategic Milestones & Recent Developments in Electronics and Electrical Ceramics Market
Date
Company
Event Type
Impact
2025
Murata Manufacturing
Capacity Expansion
High
2024
Kyocera Group
Investment
Medium
2024
CeramTec
Product Launch
Medium
2023
NGK Insulators
Partnership
Medium
2023
CoorsTek
Acquisition
Low
Chronological Details
2025 – Murata Manufacturing: Announced expanded MLCC production lines in Thailand and Japan to serve automotive and 5G customers. The move adds high-capacitance capacity and shortens lead times.
2024 – Kyocera Group: Increased investment in ceramic semiconductor packages and medical zirconia components. The strategy targets data center and orthopedic implant growth.
2024 – CeramTec: Launched a new alumina-toughened zirconia line for dental and orthopedic applications. The product competes with metal alloy implants on wear resistance.
2023 – NGK Insulators: Partnered with a European utility on high-voltage insulator retrofits. The agreement supports grid modernization and renewable integration.
2023 – CoorsTek: Acquired a specialty ceramic coatings asset to expand semiconductor equipment offerings. The deal strengthens its consumable parts business.
Regional Market Analysis & Growth Corridors for Electronics and Electrical Ceramics Market
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Asia-Pacific
5.6%
USD 6.96 Billion
Power grid and EV production
Medium-High
North America
4.2%
USD 3.19 Billion
Medical devices and defense
High
Europe
3.8%
USD 2.61 Billion
Automotive electrification
Very High
LAMEA
4.9%
USD 1.74 Billion
Grid upgrades and consumer electronics
Medium
Fastest-Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing and largest region at 5.6% CAGR. China, Japan, and South Korea host leading MLCC, substrate, and insulator producers. The Power Grid Ceramics Market expands with ultra-high-voltage transmission projects. India and ASEAN add demand from consumer appliance manufacturing.
Mature Markets: North America and Europe
North America grows at 4.2%, led by medical ceramics, defense electronics, and semiconductor equipment.
Europe grows at 3.8%, constrained by high energy costs but supported by EV and renewable energy ceramics.
LAMEA grows at 4.9%, with GCC grid investments and Brazilian appliance assembly.
Regulatory stringency is highest in Europe, where REACH and RoHS compliance shape material selection.
Regional growth corridors depend on infrastructure spending and local content rules. Asia-Pacific retains a cost advantage, but North America and Europe emphasize supply chain resilience for medical and defense-grade ceramics.
Technology Innovation & R&D Trajectory in Electronics and Electrical Ceramics Market
Emerging technologies reshape demand across the forecast period. The most disruptive areas are high-capacitance MLCC dielectrics, ceramic matrix composites for EV braking, and solid-state battery ceramics. The Electric Vehicle Ceramic Components Market benefits from 800-volt architectures, which require ceramic substrates and busbars with high dielectric strength.
Technology
Adoption Timeline
R&D Focus
Impact on Incumbents
High-capacitance MLCCs
2025–2028
Barium titanate nanoparticle control
Reinforces Murata and Kyocera
CMC brake discs
2026–2031
Oxide and SiC fiber composites
Threatens metal brake suppliers
Solid-state battery ceramics
2028–2033
Garnet and sulfide electrolytes
Creates new component demand
Ceramic additive manufacturing
2025–2030
Binder jetting and vat photopolymerization
Lowers prototyping barriers
Patent activity in ceramic dielectrics and solid electrolytes increased 11% annually between 2020 and 2024. R&D spending among leading vendors equals 5–8% of segment revenue. Additive manufacturing threatens traditional tooling but reinforces material suppliers that control ceramic powders.
Supply Chain & Raw Material Dynamics: Electronics and Electrical Ceramics Market
Upstream dependence centers on high-purity alumina, barium titanate, zirconia, and silica. The Alumina Ceramics Market consumes over 60% of technical alumina powder, linking pricing to bauxite and caustic soda costs. China supplies more than 55% of global alumina and 70% of rare-earth dopants.
Input Material
Sourcing Risk
Price Trend
Key Supplier Dependencies
High-purity alumina
High
Up 9% in 2024
China, Australia, Germany
Barium titanate
Medium
Stable to up 4%
Japan, China
Zirconia
High
Up 12% in 2024
Australia, South Africa
Silica
Low
Flat
Global
Historical disruptions include COVID-19 plant closures, China energy rationing in 2021, and Russia-Ukraine logistics shocks in 2022. These events lengthened lead times and raised spot prices. Vendors mitigate risk through multi-year contracts, powder recycling, and alternative suppliers in Brazil and India. Supply chain resilience now carries a premium of 3–6% on qualified ceramic inputs.
Electronics and Electrical Ceramics Market Segmentation
1. Product Type
1.1. Monolithic Ceramics
1.2. Ceramic Matrix Composites
1.3. Ceramic Coatings
1.4. Others
2. End-user Industry
2.1. Consumer Appliances
2.2. Power Grids
2.3. Medical Devices
2.4. Others
3. Material Type
3.1. Alumina Ceramics
3.2. Titanate Ceramics
3.3. Zirconia Ceramics
3.4. Silica Ceramics
3.5. Others
Electronics and Electrical Ceramics Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Electronics and Electrical Ceramics Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.98% from 2020-2034
Segmentation
By Product Type
Monolithic Ceramics
Ceramic Matrix Composites
Ceramic Coatings
Others
By End-user Industry
Consumer Appliances
Power Grids
Medical Devices
Others
By Material Type
Alumina Ceramics
Titanate Ceramics
Zirconia Ceramics
Silica Ceramics
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Monolithic Ceramics
5.1.2. Ceramic Matrix Composites
5.1.3. Ceramic Coatings
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by End-user Industry
5.2.1. Consumer Appliances
5.2.2. Power Grids
5.2.3. Medical Devices
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Material Type
5.3.1. Alumina Ceramics
5.3.2. Titanate Ceramics
5.3.3. Zirconia Ceramics
5.3.4. Silica Ceramics
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Monolithic Ceramics
6.1.2. Ceramic Matrix Composites
6.1.3. Ceramic Coatings
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by End-user Industry
6.2.1. Consumer Appliances
6.2.2. Power Grids
6.2.3. Medical Devices
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Material Type
6.3.1. Alumina Ceramics
6.3.2. Titanate Ceramics
6.3.3. Zirconia Ceramics
6.3.4. Silica Ceramics
6.3.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Monolithic Ceramics
7.1.2. Ceramic Matrix Composites
7.1.3. Ceramic Coatings
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by End-user Industry
7.2.1. Consumer Appliances
7.2.2. Power Grids
7.2.3. Medical Devices
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Material Type
7.3.1. Alumina Ceramics
7.3.2. Titanate Ceramics
7.3.3. Zirconia Ceramics
7.3.4. Silica Ceramics
7.3.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Monolithic Ceramics
8.1.2. Ceramic Matrix Composites
8.1.3. Ceramic Coatings
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by End-user Industry
8.2.1. Consumer Appliances
8.2.2. Power Grids
8.2.3. Medical Devices
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Material Type
8.3.1. Alumina Ceramics
8.3.2. Titanate Ceramics
8.3.3. Zirconia Ceramics
8.3.4. Silica Ceramics
8.3.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Monolithic Ceramics
9.1.2. Ceramic Matrix Composites
9.1.3. Ceramic Coatings
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by End-user Industry
9.2.1. Consumer Appliances
9.2.2. Power Grids
9.2.3. Medical Devices
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Material Type
9.3.1. Alumina Ceramics
9.3.2. Titanate Ceramics
9.3.3. Zirconia Ceramics
9.3.4. Silica Ceramics
9.3.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Monolithic Ceramics
10.1.2. Ceramic Matrix Composites
10.1.3. Ceramic Coatings
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by End-user Industry
10.2.1. Consumer Appliances
10.2.2. Power Grids
10.2.3. Medical Devices
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Material Type
10.3.1. Alumina Ceramics
10.3.2. Titanate Ceramics
10.3.3. Zirconia Ceramics
10.3.4. Silica Ceramics
10.3.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AdValueTech
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Aum Techno Ceramics
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. CeramTec
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. CoorsTek Inc
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Heraeus Holding
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. IBIDEN
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. KCM Corporation Co Ltd
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Kyocera Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. MARUWA Co Ltd
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Murata Manufacturing Co Ltd
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. NGK INSULATORS LTD
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. NIPPON CARBIDE INDUSTRIES CO INC
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. NORITAKE CO LIMITED
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Saint-Gobain
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. TAYCA*List Not Exhaustive
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Electronics and Electrical Ceramics Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Electronics and Electrical Ceramics Market Revenue (billion), by Product Type 2026 & 2034
Figure 3: North America Electronics and Electrical Ceramics Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Electronics and Electrical Ceramics Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 5: North America Electronics and Electrical Ceramics Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 6: North America Electronics and Electrical Ceramics Market Revenue (billion), by Material Type 2026 & 2034
Figure 7: North America Electronics and Electrical Ceramics Market Revenue Share (%), by Material Type 2026 & 2034
Figure 8: North America Electronics and Electrical Ceramics Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Electronics and Electrical Ceramics Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Electronics and Electrical Ceramics Market Revenue (billion), by Product Type 2026 & 2034
Figure 11: South America Electronics and Electrical Ceramics Market Revenue Share (%), by Product Type 2026 & 2034
Figure 12: South America Electronics and Electrical Ceramics Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 13: South America Electronics and Electrical Ceramics Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 14: South America Electronics and Electrical Ceramics Market Revenue (billion), by Material Type 2026 & 2034
Figure 15: South America Electronics and Electrical Ceramics Market Revenue Share (%), by Material Type 2026 & 2034
Figure 16: South America Electronics and Electrical Ceramics Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Electronics and Electrical Ceramics Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Electronics and Electrical Ceramics Market Revenue (billion), by Product Type 2026 & 2034
Figure 19: Europe Electronics and Electrical Ceramics Market Revenue Share (%), by Product Type 2026 & 2034
Figure 20: Europe Electronics and Electrical Ceramics Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 21: Europe Electronics and Electrical Ceramics Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 22: Europe Electronics and Electrical Ceramics Market Revenue (billion), by Material Type 2026 & 2034
Figure 23: Europe Electronics and Electrical Ceramics Market Revenue Share (%), by Material Type 2026 & 2034
Figure 24: Europe Electronics and Electrical Ceramics Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Electronics and Electrical Ceramics Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Electronics and Electrical Ceramics Market Revenue (billion), by Product Type 2026 & 2034
Figure 27: Middle East & Africa Electronics and Electrical Ceramics Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Middle East & Africa Electronics and Electrical Ceramics Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 29: Middle East & Africa Electronics and Electrical Ceramics Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 30: Middle East & Africa Electronics and Electrical Ceramics Market Revenue (billion), by Material Type 2026 & 2034
Figure 31: Middle East & Africa Electronics and Electrical Ceramics Market Revenue Share (%), by Material Type 2026 & 2034
Figure 32: Middle East & Africa Electronics and Electrical Ceramics Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Electronics and Electrical Ceramics Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Electronics and Electrical Ceramics Market Revenue (billion), by Product Type 2026 & 2034
Figure 35: Asia Pacific Electronics and Electrical Ceramics Market Revenue Share (%), by Product Type 2026 & 2034
Figure 36: Asia Pacific Electronics and Electrical Ceramics Market Revenue (billion), by End-user Industry 2026 & 2034
Figure 37: Asia Pacific Electronics and Electrical Ceramics Market Revenue Share (%), by End-user Industry 2026 & 2034
Figure 38: Asia Pacific Electronics and Electrical Ceramics Market Revenue (billion), by Material Type 2026 & 2034
Figure 39: Asia Pacific Electronics and Electrical Ceramics Market Revenue Share (%), by Material Type 2026 & 2034
Figure 40: Asia Pacific Electronics and Electrical Ceramics Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Electronics and Electrical Ceramics Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 2: Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 3: Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 4: Electronics and Electrical Ceramics Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 6: North America Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 7: North America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 8: North America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 13: South America Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 14: South America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 15: South America Electronics and Electrical Ceramics Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 20: Europe Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 21: Europe Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 22: Europe Electronics and Electrical Ceramics Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 33: Middle East & Africa Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 34: Middle East & Africa Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 35: Middle East & Africa Electronics and Electrical Ceramics Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Electronics and Electrical Ceramics Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 43: Asia Pacific Electronics and Electrical Ceramics Market Revenue billion Forecast, by End-user Industry 2020 & 2034
Table 44: Asia Pacific Electronics and Electrical Ceramics Market Revenue billion Forecast, by Material Type 2020 & 2034
Table 45: Asia Pacific Electronics and Electrical Ceramics Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Electronics and Electrical Ceramics Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 70–80% of the research effort, with 20–30% from secondary research.
Interview targets include Director of Ceramic Materials Procurement, Senior Electrical Insulation Engineer, Medical Device Ceramics Product Manager, and Power Transmission Component Sourcing Lead.
Company types surveyed: multilayer ceramic capacitor (MLCC) dielectric powder suppliers; high-purity alumina substrate and tape-casting manufacturers; ceramic matrix composite (CMC) brake disc and turbine component producers; medical-grade zirconia implant and instrument OEMs; power grid insulator and surge arrester assembly vendors.
Quantitative inputs include annual MLCC unit shipments per application segment, kilometers of high-voltage transmission line upgraded per year, number of ceramic hip and knee implant procedures per 100,000 population, and average alumina powder price per metric ton.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Ceramic Materials Procurement
30%
Senior Electrical Insulation Engineer
25%
Medical Device Ceramics Product Manager
25%
Power Transmission Component Sourcing Lead
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
MLCC Dielectric Powder Suppliers
25%
Alumina Substrate and Tape-Casting Manufacturers
20%
CMC Component Producers
15%
Medical-Grade Zirconia OEMs
20%
Power Grid Insulator Vendors
20%
Secondary Research & Industry Benchmarking
Secondary research draws on Bloomberg, Factiva, Hoovers, and PitchBook financial databases: Bloomberg, Factiva, Hoovers, and PitchBook.
Top-down and bottom-up methodologies are used simultaneously and validated via multi-level data triangulation.
Bottom-up calculation multiplies application-level ceramic component volumes by average selling prices, then cross-checks against end-user industry spending.
Top-down modeling applies regional electronics and electrical equipment output, material substitution rates, and import-export trade data.
Segment splits use Product Type (Monolithic Ceramics, Ceramic Matrix Composites, Ceramic Coatings, Others), End-user Industry (Consumer Appliances, Power Grids, Medical Devices, Others), and Material Type (Alumina Ceramics, Titanate Ceramics, Zirconia Ceramics, Silica Ceramics, Others).
Regional models cover North America, South America, Europe, Middle East & Africa, and Asia Pacific with country-level granularity.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level is 85–90%.
Data triangulation compares primary interview ranges, secondary trade statistics, and financial database filings.
Outlier detection uses coefficient of variation thresholds above 15% for re-interview or source replacement.
Final estimates are reviewed by senior analysts and cross-validated against supply-side capacity and demand-side consumption.
Every report is updated to the date of purchase.
Frequently Asked Questions
1. How are supply chain risks affecting the Electronics and Electrical Ceramics Market?
Supply chain risks center on high-purity alumina, barium titanate, and zirconia. China supplies over 55% of global alumina and 70% of rare-earth dopants, so export restrictions or energy rationing can raise prices. COVID-19 shutdowns in 2020–2021 delayed MLCC deliveries by 12–20 weeks. Vendors now qualify alternative suppliers in Australia, Brazil, and India to reduce single-source exposure.
2. Which region dominates the Electronics and Electrical Ceramics Market and why?
Asia-Pacific dominates with 48% of global demand and a projected 5.6% CAGR. China, Japan, and South Korea host Kyocera Group, Murata Manufacturing, and NGK Insulators, which supply MLCCs, substrates, and grid insulators. Lower energy costs, mature supplier clusters, and proximity to consumer electronics assembly reinforce the region's leadership. Government grid modernization programs add long-term demand.
3. How has the Electronics and Electrical Ceramics Market recovered after the COVID-19 pandemic?
Recovery began in 2021 as consumer electronics and automotive production restarted, but MLCC lead times remained extended through 2022. The pandemic accelerated structural shifts toward regional sourcing, automated sintering, and higher inventory buffers. Post-2023 demand normalized, and the market returned to a 4.98% CAGR trajectory. Medical and power grid ceramics proved more resilient than discretionary appliance ceramics.
4. What consumer behavior shifts are changing purchasing trends in the Electronics and Electrical Ceramics Market?
Consumers demand smaller, faster, and more energy-efficient devices, increasing MLCC and sensor content per unit. Electric vehicle adoption raises demand for ceramic substrates, busbars, and brake components. Smart appliances and wearable medical devices add new ceramic applications. These shifts support a 4.98% CAGR from 2025 to 2033, with premium pricing for high-reliability parts.
5. Which end-user industries drive downstream demand in the Electronics and Electrical Ceramics Market?
Consumer appliances account for around 31% of end-user demand, followed by power grids at 24% and medical devices at 17%. Power grid ceramics benefit from ultra-high-voltage transmission upgrades in China and India. Medical Device Ceramics Market growth comes from zirconia implants and alumina surgical tools. Automotive and electronics assembly remain cross-cutting demand pools.
6. What disruptive technologies or substitutes threaten the Electronics and Electrical Ceramics Market?
Solid-state battery ceramics, ceramic additive manufacturing, and polymer-composite insulators are the main disruptive forces. Additive manufacturing lowers prototyping barriers but reinforces demand for advanced ceramic powders. Polymer composites substitute porcelain in lower-voltage grid applications, capping growth in that niche. CMC brake discs could replace metal brakes in premium EVs, expanding the Ceramic Matrix Composites Market.