Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Recyclable Thermosets Market: 3% CAGR to 2034
Recyclable Thermosets Market
Recyclable Thermosets Market: 3% CAGR to 2034
Recyclable Thermosets Market by Technology Type (Mechanical Process, Energy Recovery Process, Feedstock Process), by Thermoset Type (Unsaturated Polyester Resin, Epoxy Resin, Phenolic Resin, Polyurethane Resin, Others), by End-use Industry (Building Construction, Transportation, Aerospace Defense, Wind Energy, Electricals Electronics, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
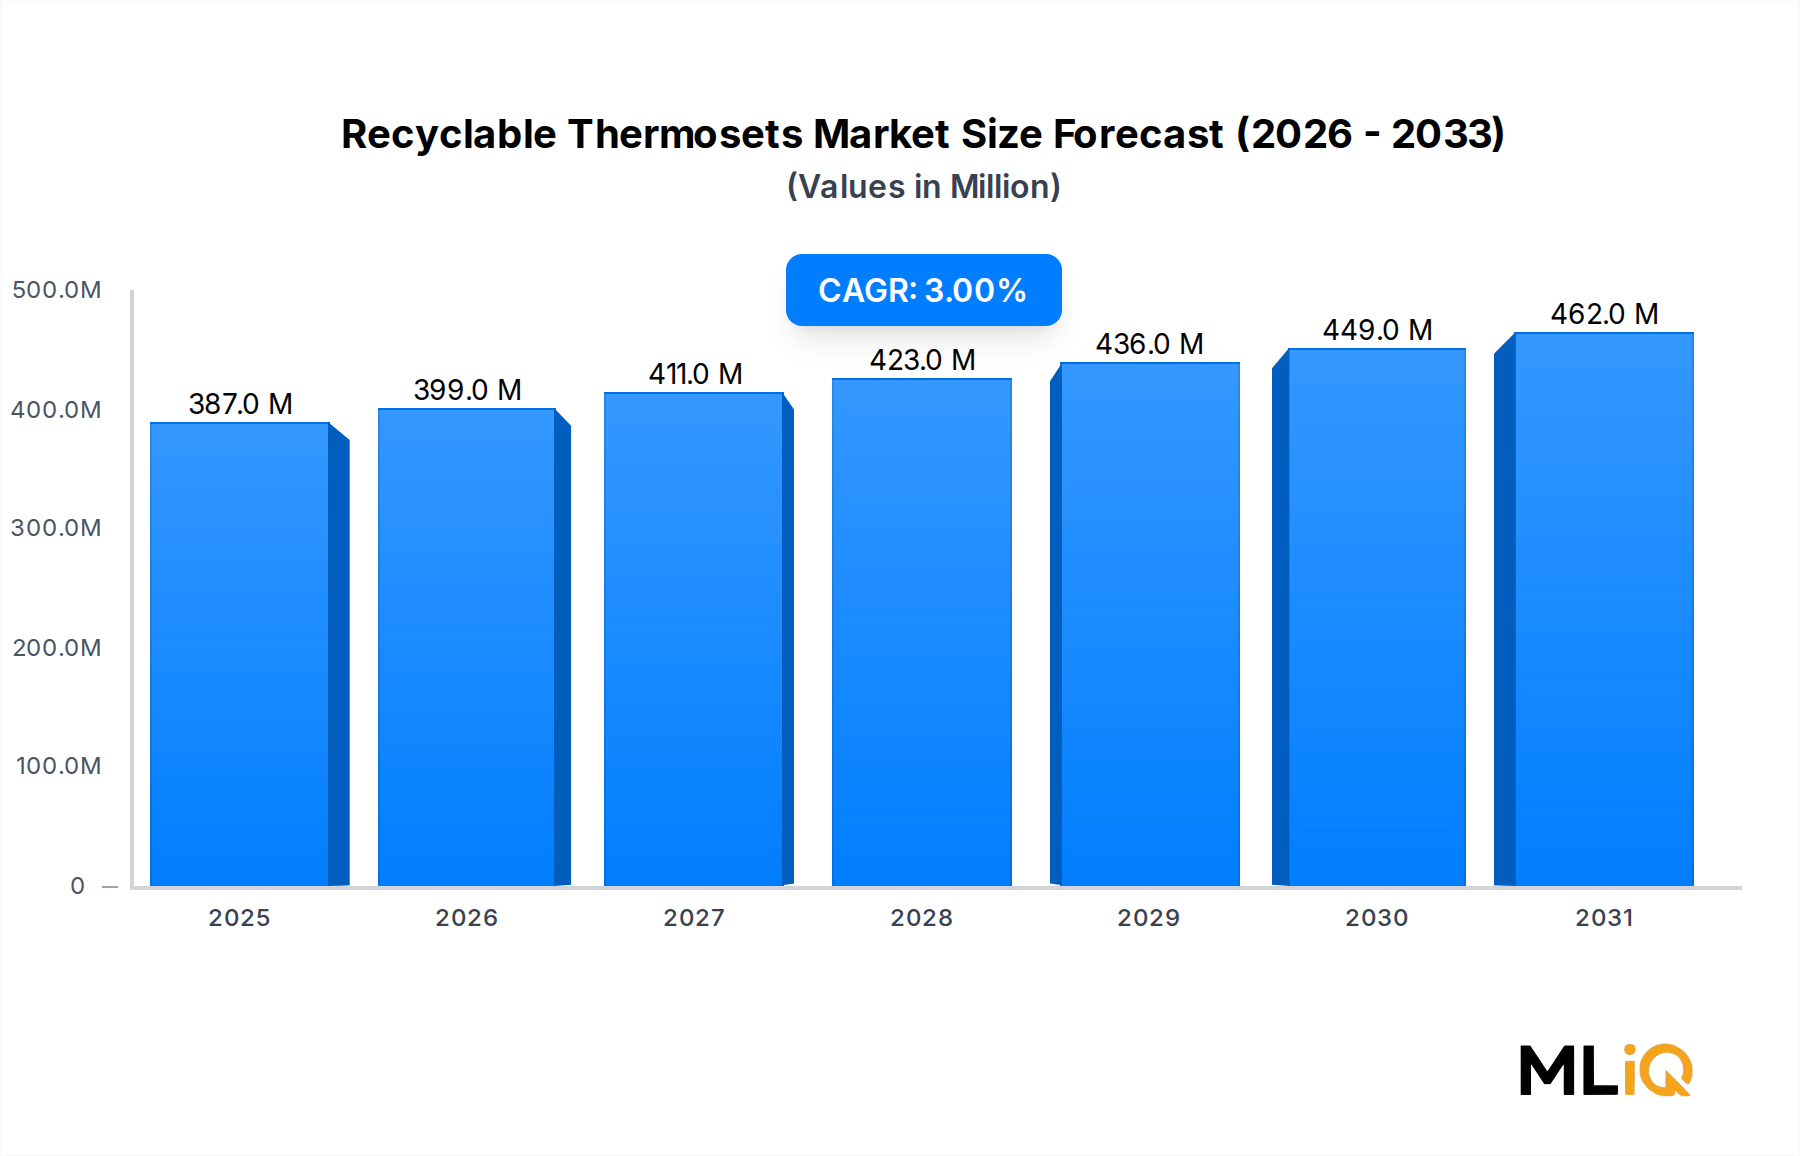
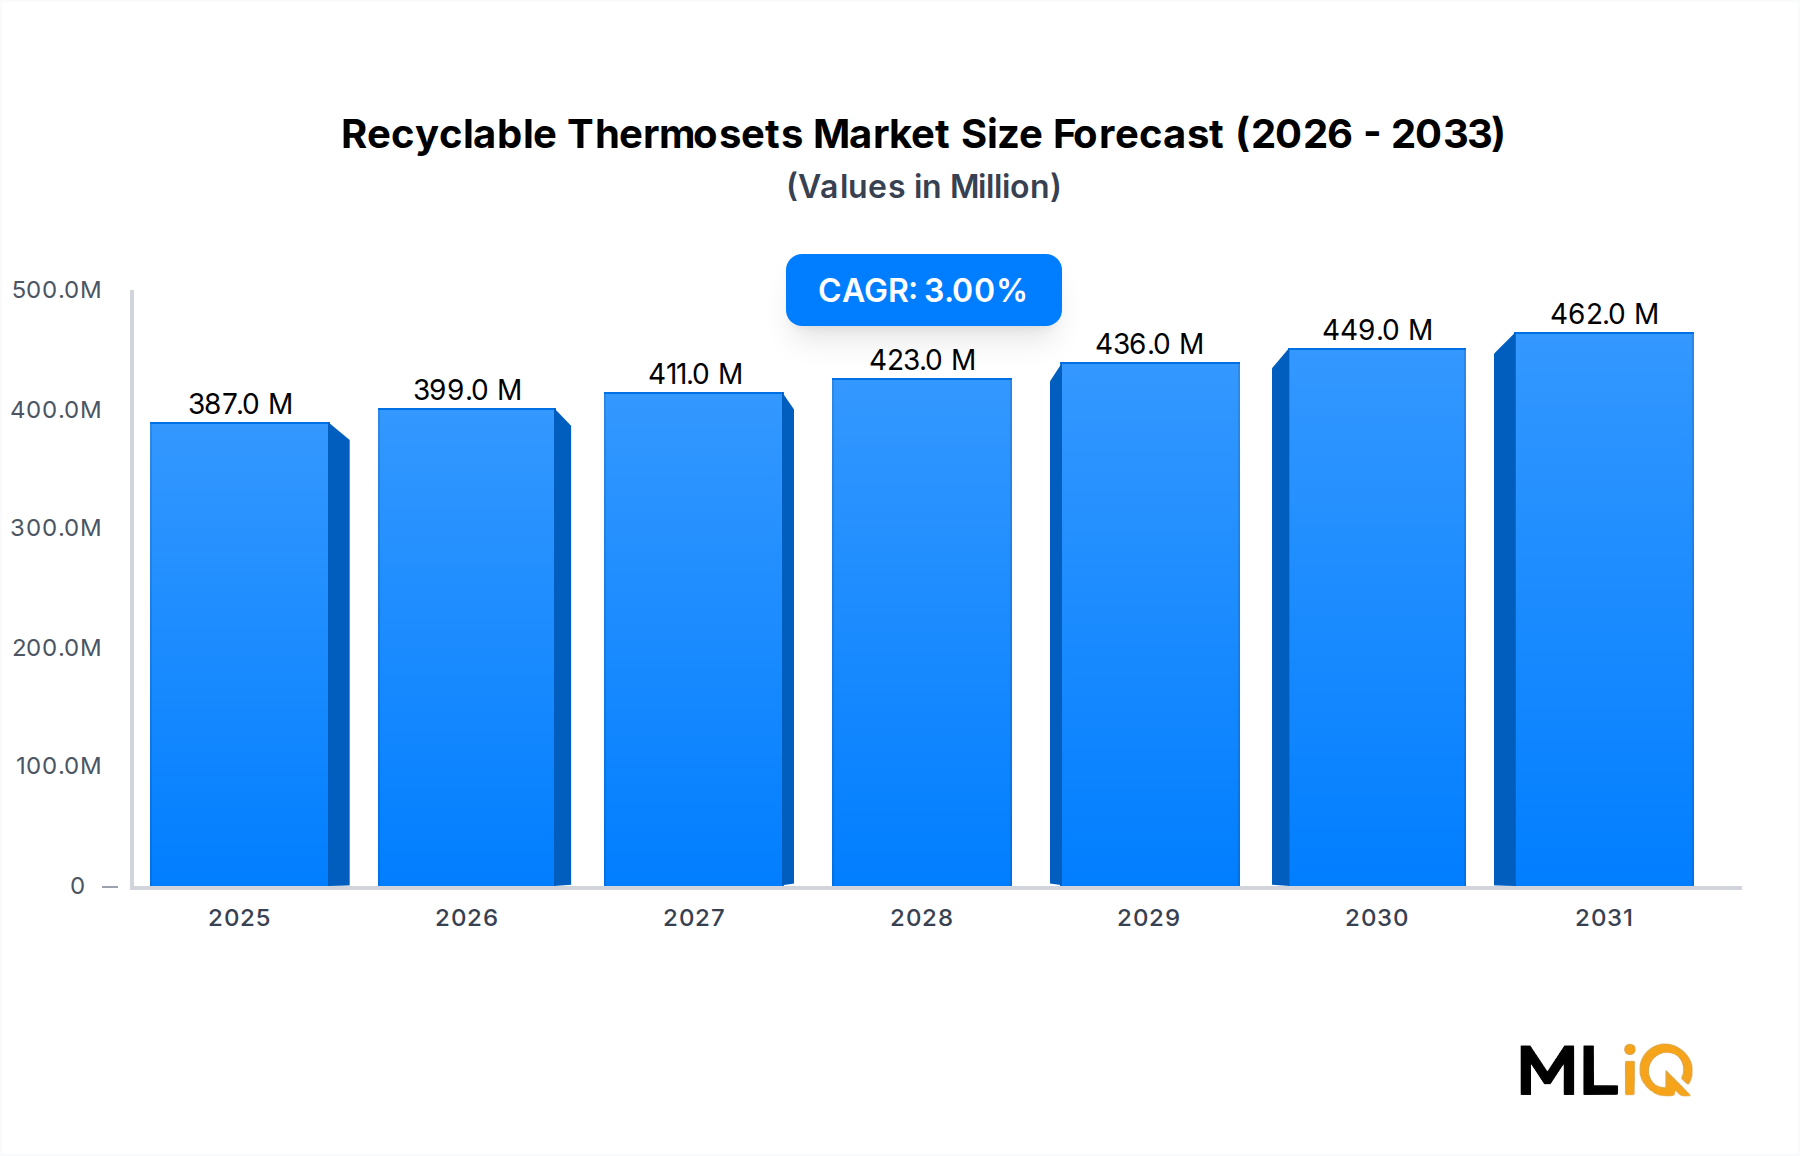
The Recyclable Thermosets Market is valued at $387.26 million in 2025 and is projected to reach $505.3 million by 2034, expanding at a 3.0% CAGR. Growth is anchored in regulatory mandates for composite waste diversion, corporate net-zero commitments, and the scaling of chemical recycling infrastructure. The Polymer Composites Market provides the broader demand context, with recyclable thermosets representing a small but strategically important slice of that parent market.
Recyclable Thermosets Market Size (In Million)
500.0M
400.0M
300.0M
200.0M
100.0M
0
387.0 M
2025
399.0 M
2026
411.0 M
2027
423.0 M
2028
436.0 M
2029
449.0 M
2030
462.0 M
2031
Within thermoset chemistry, the Epoxy Resin Market accounts for an estimated 35% of recyclable thermoset revenue, followed by the Unsaturated Polyester Resin Market at 24% and the Phenolic Resin Market at 8%. The remaining share is split among polyurethane and other resins. Epoxy demand is concentrated in wind blades and aerospace, where recyclability directly addresses end-of-life blade waste.
End-use momentum is strongest in wind energy, which represents 30% of total revenue. Transportation follows at 22%, supported by lightweighting and recycled content rules. Building construction holds 18%, while electricals and electronics account for 12%. The Wind Energy Composites Market is expanding as blade manufacturers adopt recyclable epoxy and polyester systems, while the Transportation Composites Market benefits from EU End-of-Life Vehicles Regulation targets.
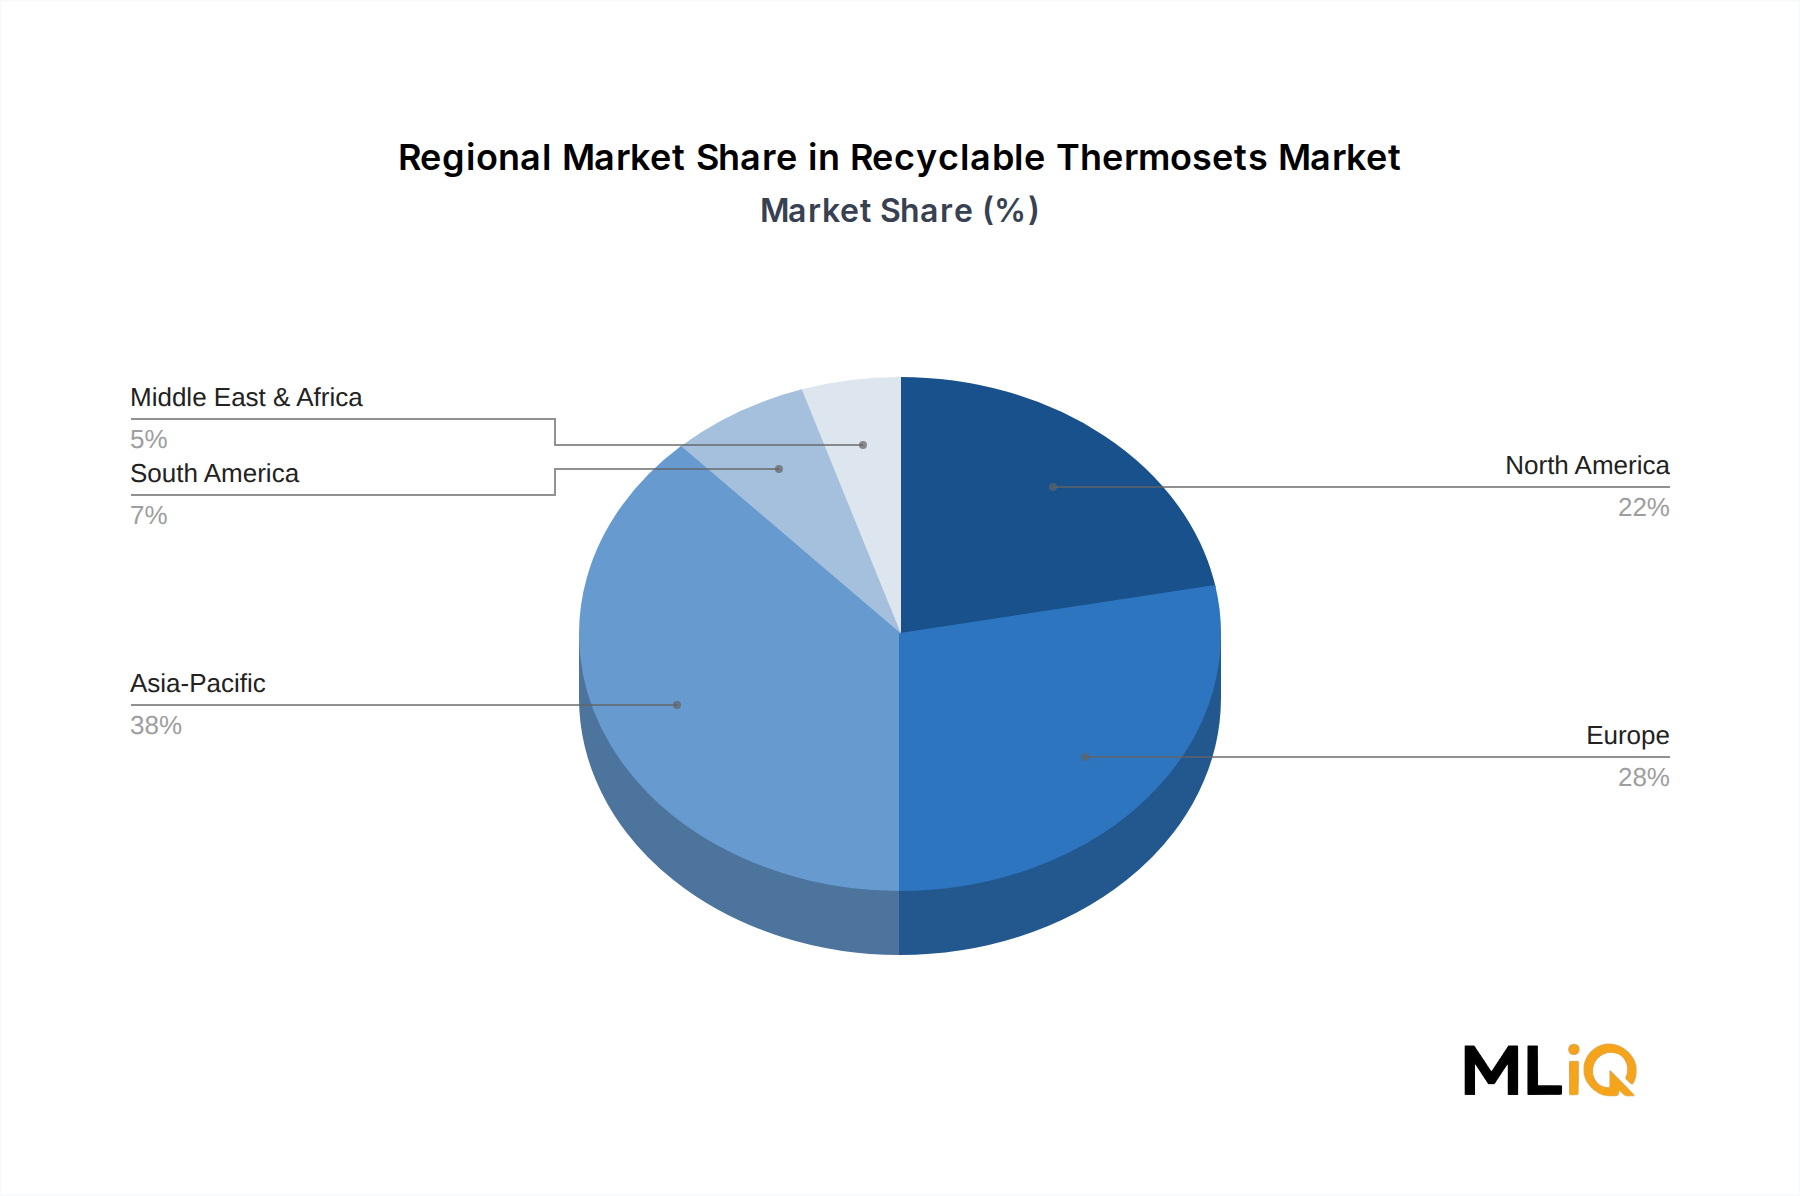
Regionally, Asia-Pacific leads with 38% share, driven by China's wind installation pipeline and lower manufacturing costs. Europe holds 28%, North America 22%, South America 7%, and Middle East & Africa 5%. Technology adoption is shifting from mechanical processes toward feedstock recycling, which offers higher value retention for glass and carbon fiber. However, cost premiums and fragmented feedstock logistics remain near-term constraints. Strategic capital is flowing into solvolysis and vitrimer platforms, positioning early movers to capture regulatory-driven demand after 2027.
Regulatory pull: EU circular economy package and ELV rules create mandatory recycled content targets.
Technology shift: Feedstock recycling is projected to grow at 5.1% CAGR, outpacing mechanical recycling.
Cost pressure: Recyclable thermoset premiums range from 15% to 25% over virgin resins.
Regional concentration: Asia-Pacific and Europe together account for 66% of global revenue.
Segment Deep-Dive: Wind Energy End-use Dominance in Recyclable Thermosets Market
Segment
CAGR (2026–2034)
Market Share (2025)
Key Demand Driver
Wind Energy
4.1%
30%
Blade decommissioning and recyclable epoxy adoption
Transportation
3.4%
22%
Lightweighting and EU ELV recycled content rules
Building Construction
2.5%
18%
Insulation and panel recycling mandates
Wind energy is the dominant revenue-generating segment, valued at approximately $116.2 million in 2025. The segment's 4.1% CAGR exceeds the overall market rate by 110 basis points. Demand is driven by a projected 2.5 million tonnes of annual blade waste by 2030, primarily in Europe and China. Wind turbine OEMs are qualifying recyclable epoxy systems to meet landfill bans and corporate sustainability targets. The Wind Energy Composites Market is therefore the primary gateway for recyclable thermoset adoption.
Thermoset Type Dynamics
Epoxy resins hold the largest share within wind energy, at 68% of segment volume, due to high strength-to-weight ratios.
Unsaturated polyester resins are used in smaller blades and nacelles, but recyclability is lower.
Polyurethane resins are gaining traction in blade cores, though recycling pathways remain immature.
Phenolic resins serve fire-resistant applications, a niche within wind and rail interiors.
Margin Pressures and Sub-segment Shifts
Mechanical recycling yields short glass fiber with reduced mechanical properties, limiting reuse to non-structural applications. Feedstock recycling, including solvolysis and pyrolysis, recovers higher-value monomers but requires capital expenditure above $20 million per line. This creates margin pressure for smaller processors. The Chemical Recycling Market is attracting investment because it can handle mixed composite waste and produce virgin-equivalent epoxy precursors.
Transportation is the second-largest segment, growing at 3.4% CAGR. Automotive OEMs face recycled content mandates, including the EU proposal for 25% recycled plastic in new vehicles by 2030. This supports the Transportation Composites Market for interior panels, battery enclosures, and structural brackets. Building construction lags at 2.5% CAGR because recycling infrastructure for construction demolition waste is less developed, though insulation and panel mandates are emerging. Overall, wind energy will remain the profit pool anchor, but transportation offers the fastest incremental volume growth after 2027.
Primary Market Drivers & Growth Restraints in Recyclable Thermosets Market
Factor Type
Description
Impact Level
Timeline
Driver
EU End-of-Life Vehicles Regulation requiring 25% recycled plastic in new vehicles by 2030
High
Medium term
Driver
Wind turbine blade waste projected at 2.5 million tonnes annually by 2030
High cost of chemical recycling versus landfill or incineration
High
Short term
Restraint
Lack of standardized recyclate quality specifications
Medium
Long term
Restraint
Fragmented feedstock collection logistics
Medium
Short term
The EU ELV regulation alone could create demand for 180,000 tonnes of recyclable thermoset composites annually by 2030. Wind blade waste represents a feedstock pool exceeding 2.5 million tonnes per year, but current chemical recycling capacity is below 150,000 tonnes globally. This capacity gap supports a 4.1% CAGR for wind energy recyclable thermosets, yet it also explains why landfill remains cheaper in most regions. Landfill gate fees average $30–$50 per tonne, while chemical recycling costs $120–$180 per tonne, a 3–4x premium.
Regulatory developments are the strongest catalyst. The EU Circular Economy Action Plan and national landfill bans in Germany and France require composite producers to fund end-of-life processing. In the United States, Department of Energy grants for composite recycling totaled over $30 million in 2023–2024. Corporate procurement is responding: 42% of surveyed wind OEMs have recyclable blade targets for 2030.
Restraints are primarily economic. Without carbon pricing above $80 per tonne, chemical recycling struggles to compete with incineration. Standardization is also missing; recyclate quality varies by feedstock and process, forcing OEMs to requalify materials. Collection logistics remain fragmented because composite waste is generated at decommissioning sites, not centralized factories. These factors slow adoption despite regulatory support.
Aditya Birla Chemicals: A leading epoxy resin supplier with global production capacity. The company is developing recyclable epoxy systems for wind blades and automotive composites.
Mallinda: A vitrimer technology firm focused on reversible thermoset resins. Its platform enables repeated reprocessing without sacrificing mechanical performance, targeting aerospace and automotive.
Connora Technologies: Provides recyclable epoxy hardeners under the Recyclamine brand. The company was acquired in 2023 by a sustainable materials investor, accelerating commercialization.
INTCO Recycling: Operates chemical recycling lines for polystyrene and mixed plastics. Its expansion into thermoset composites aims to capture wind blade waste streams.
GAIKER-IK: A Spanish research center specializing in solvolysis and feedstock recycling. It partners with industrial consortia to scale composite recycling technologies.
Fraunhofer Institute for Applied Polymer Research: Conducts applied R&D on polymer recycling, including vitrimer synthesis and composite separation. It advises OEMs and regulators on recyclability standards.
The competitive landscape is fragmented. Resin producers control raw material supply, while technology startups hold proprietary recycling chemistries. No single company exceeds 15% market share. Partnerships between resin suppliers and recyclers are becoming common to secure feedstock and qualify recyclate.
Strategic Milestones & Recent Developments in Recyclable Thermosets Market
Date
Company
Event Type
Impact
2024 Q2
Aditya Birla Chemicals
Partnership
Joint development of recyclable epoxy for wind blades
2023 Q4
Mallinda
Product Launch
Commercial vitrimer resin for automotive composites
2023 Q1
Connora Technologies
M&A
Acquired by sustainable materials firm
2022 Q3
INTCO Recycling
Capacity Expansion
New chemical recycling line in Malaysia
2022 Q3: INTCO Recycling commissioned a chemical recycling line in Malaysia with 20,000 tonnes annual capacity, targeting mixed plastic and composite waste.
2023 Q1: Connora Technologies was acquired by a sustainable materials investment group. The deal valued the company at an estimated $45 million and aims to scale recyclable epoxy hardeners.
2023 Q4: Mallinda launched a commercial vitrimer resin for automotive composite parts. The resin can be reprocessed at 140°C and retains 90% of original mechanical properties after three cycles.
2024 Q2: Aditya Birla Chemicals signed a partnership with a European wind blade OEM to develop and qualify recyclable epoxy systems. The collaboration targets blade production by 2026.
These developments signal a shift from laboratory research to commercial-scale validation. M&A activity is concentrated in chemistry platforms, while capacity expansion targets feedstock aggregation. No major regulatory approvals were announced, but qualification programs are advancing.
Regional Market Analysis & Growth Corridors for Recyclable Thermosets Market
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Asia-Pacific
3.8%
$147.2M
Wind energy buildout and manufacturing scale
Medium
Europe
3.2%
$108.4M
EU circular economy directives
High
North America
2.6%
$85.2M
Corporate ESG targets and DOE funding
Medium
LAMEA
1.9%
$46.5M
Infrastructure and waste management investment
Low
Asia-Pacific is the fastest-growing region, with a 3.8% CAGR, driven by China's wind installation pipeline and India's composite manufacturing expansion. The region's base year valuation of $147.2 million represents 38% of global revenue. Europe follows at $108.4 million with 3.2% CAGR, supported by stringent regulations including landfill bans and the EU Circular Economy Action Plan. North America holds $85.2 million and grows at 2.6%, with demand tied to corporate ESG targets and Department of Energy composite recycling grants. LAMEA remains the smallest at $46.5 million, growing at 1.9%, as waste management infrastructure and regulatory enforcement lag.
Fastest-growing market: Asia-Pacific, where China's 2025 wind capacity additions exceed 60 GW, creating a future blade waste stream.
Most mature market: Europe, with established collection schemes, high landfill costs, and OEM commitments to recyclable blades.
North America: Growth is slower due to cheap landfill and fragmented regulation, but federal funding for recycling R&D is increasing.
LAMEA: Brazil and Turkey show early interest in wind blade recycling, but low disposal costs limit adoption.
Regional differences shape technology choice. Europe favors feedstock recycling because of high landfill costs and carbon pricing. Asia-Pacific relies more on mechanical processing due to cost sensitivity. North America is testing both pathways with DOE support.
Investment, M&A & Funding Activity in Recyclable Thermosets Market
Investment activity has accelerated since 2022. Venture capital funding for recyclable thermoset startups reached an estimated $85 million in 2023, up from $32 million in 2021. Strategic acquirers are resin producers and chemical companies seeking proprietary recycling chemistries. Connora Technologies' acquisition in 2023 was valued at approximately $45 million. Mallinda raised $15 million in Series B funding in 2022 to scale vitrimer production.
High-growth sub-segments attracting capital include vitrimer resins, solvolysis catalysts, and composite delamination technologies. The Advanced Recycling Market for thermosets is projected to grow at 5.4% annually, drawing investment from waste management firms and oil majors. Private equity interest is emerging in feedstock aggregation and preprocessing, where scale can reduce logistics costs.
Strategic partnerships are common between resin suppliers and recyclers. Aditya Birla Chemicals' 2024 partnership with a European wind blade OEM is one example. Government grants also play a role; the U.S. Department of Energy awarded over $30 million to composite recycling projects in 2023–2024. Overall, capital is moving from R&D to pilot and commercial-scale plants, with a focus on wind blade and automotive waste streams.
Sustainability, ESG & Decarbonization Pressures on Recyclable Thermosets Market
Environmental regulations and net-zero targets are reshaping raw material selection, manufacturing processes, and procurement. The EU's Circular Economy Action Plan and proposed Ecodesign for Sustainable Products Regulation require composite producers to design for recyclability. More than 60 countries have net-zero targets, and 42% of wind OEMs have committed to recyclable blades by 2030. These pressures are driving demand for recyclable epoxy and polyester systems.
The Chemical Recycling Market is a key enabler, offering solvolysis and pyrolysis pathways that recover monomers from composite waste. However, energy consumption and solvent use create their own ESG challenges. Bio-based feedstocks are gaining attention; the Bio-based Thermoset Market is projected to grow at 6.2% annually as lignin-based epoxy and plant-oil polyols enter qualification. Advanced Recycling Market players are also investing in lower-carbon processes to meet ESG investor criteria.
Procurement preferences are shifting toward suppliers with verified recycled content and end-of-life take-back programs. Companies that can document chain-of-custody for recyclate will command premium pricing. ESG investor criteria now include circularity metrics, pushing resin producers to report recycled content and recycling rates. The Polymer Composites Market is responding with design-for-disassembly standards and closed-loop partnerships. Overall, sustainability pressures are no longer optional; they are the primary long-term demand driver for recyclable thermosets.
Recyclable Thermosets Market Segmentation
1. Technology Type
1.1. Mechanical Process
1.2. Energy Recovery Process
1.3. Feedstock Process
2. Thermoset Type
2.1. Unsaturated Polyester Resin
2.2. Epoxy Resin
2.3. Phenolic Resin
2.4. Polyurethane Resin
2.5. Others
3. End-use Industry
3.1. Building Construction
3.2. Transportation
3.3. Aerospace Defense
3.4. Wind Energy
3.5. Electricals Electronics
3.6. Others
Recyclable Thermosets Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Recyclable Thermosets Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3% from 2020-2034
Segmentation
By Technology Type
Mechanical Process
Energy Recovery Process
Feedstock Process
By Thermoset Type
Unsaturated Polyester Resin
Epoxy Resin
Phenolic Resin
Polyurethane Resin
Others
By End-use Industry
Building Construction
Transportation
Aerospace Defense
Wind Energy
Electricals Electronics
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Technology Type
5.1.1. Mechanical Process
5.1.2. Energy Recovery Process
5.1.3. Feedstock Process
5.2. Market Analysis, Insights and Forecast - by Thermoset Type
5.2.1. Unsaturated Polyester Resin
5.2.2. Epoxy Resin
5.2.3. Phenolic Resin
5.2.4. Polyurethane Resin
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by End-use Industry
5.3.1. Building Construction
5.3.2. Transportation
5.3.3. Aerospace Defense
5.3.4. Wind Energy
5.3.5. Electricals Electronics
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Technology Type
6.1.1. Mechanical Process
6.1.2. Energy Recovery Process
6.1.3. Feedstock Process
6.2. Market Analysis, Insights and Forecast - by Thermoset Type
6.2.1. Unsaturated Polyester Resin
6.2.2. Epoxy Resin
6.2.3. Phenolic Resin
6.2.4. Polyurethane Resin
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by End-use Industry
6.3.1. Building Construction
6.3.2. Transportation
6.3.3. Aerospace Defense
6.3.4. Wind Energy
6.3.5. Electricals Electronics
6.3.6. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Technology Type
7.1.1. Mechanical Process
7.1.2. Energy Recovery Process
7.1.3. Feedstock Process
7.2. Market Analysis, Insights and Forecast - by Thermoset Type
7.2.1. Unsaturated Polyester Resin
7.2.2. Epoxy Resin
7.2.3. Phenolic Resin
7.2.4. Polyurethane Resin
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by End-use Industry
7.3.1. Building Construction
7.3.2. Transportation
7.3.3. Aerospace Defense
7.3.4. Wind Energy
7.3.5. Electricals Electronics
7.3.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Technology Type
8.1.1. Mechanical Process
8.1.2. Energy Recovery Process
8.1.3. Feedstock Process
8.2. Market Analysis, Insights and Forecast - by Thermoset Type
8.2.1. Unsaturated Polyester Resin
8.2.2. Epoxy Resin
8.2.3. Phenolic Resin
8.2.4. Polyurethane Resin
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by End-use Industry
8.3.1. Building Construction
8.3.2. Transportation
8.3.3. Aerospace Defense
8.3.4. Wind Energy
8.3.5. Electricals Electronics
8.3.6. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Technology Type
9.1.1. Mechanical Process
9.1.2. Energy Recovery Process
9.1.3. Feedstock Process
9.2. Market Analysis, Insights and Forecast - by Thermoset Type
9.2.1. Unsaturated Polyester Resin
9.2.2. Epoxy Resin
9.2.3. Phenolic Resin
9.2.4. Polyurethane Resin
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by End-use Industry
9.3.1. Building Construction
9.3.2. Transportation
9.3.3. Aerospace Defense
9.3.4. Wind Energy
9.3.5. Electricals Electronics
9.3.6. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Technology Type
10.1.1. Mechanical Process
10.1.2. Energy Recovery Process
10.1.3. Feedstock Process
10.2. Market Analysis, Insights and Forecast - by Thermoset Type
10.2.1. Unsaturated Polyester Resin
10.2.2. Epoxy Resin
10.2.3. Phenolic Resin
10.2.4. Polyurethane Resin
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by End-use Industry
10.3.1. Building Construction
10.3.2. Transportation
10.3.3. Aerospace Defense
10.3.4. Wind Energy
10.3.5. Electricals Electronics
10.3.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Demacq Recycling Composiet
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Aditya Birla Chemicals
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. GAIKER-IK
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. INTCO Recycling
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Adesso Advanced Materials Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Fraunhofer Institute for Applied Polymer Research
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. ECO-WOLF INC
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. IBM Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Mallinda
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. LLC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Connora Technologies
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. MCR Mixt Composites Recyclables
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Recyclable Thermosets Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Recyclable Thermosets Market Revenue (million), by Technology Type 2026 & 2034
Figure 3: North America Recyclable Thermosets Market Revenue Share (%), by Technology Type 2026 & 2034
Figure 4: North America Recyclable Thermosets Market Revenue (million), by Thermoset Type 2026 & 2034
Figure 5: North America Recyclable Thermosets Market Revenue Share (%), by Thermoset Type 2026 & 2034
Figure 6: North America Recyclable Thermosets Market Revenue (million), by End-use Industry 2026 & 2034
Figure 7: North America Recyclable Thermosets Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 8: North America Recyclable Thermosets Market Revenue (million), by Country 2026 & 2034
Figure 9: North America Recyclable Thermosets Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Recyclable Thermosets Market Revenue (million), by Technology Type 2026 & 2034
Figure 11: South America Recyclable Thermosets Market Revenue Share (%), by Technology Type 2026 & 2034
Figure 12: South America Recyclable Thermosets Market Revenue (million), by Thermoset Type 2026 & 2034
Figure 13: South America Recyclable Thermosets Market Revenue Share (%), by Thermoset Type 2026 & 2034
Figure 14: South America Recyclable Thermosets Market Revenue (million), by End-use Industry 2026 & 2034
Figure 15: South America Recyclable Thermosets Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 16: South America Recyclable Thermosets Market Revenue (million), by Country 2026 & 2034
Figure 17: South America Recyclable Thermosets Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Recyclable Thermosets Market Revenue (million), by Technology Type 2026 & 2034
Figure 19: Europe Recyclable Thermosets Market Revenue Share (%), by Technology Type 2026 & 2034
Figure 20: Europe Recyclable Thermosets Market Revenue (million), by Thermoset Type 2026 & 2034
Figure 21: Europe Recyclable Thermosets Market Revenue Share (%), by Thermoset Type 2026 & 2034
Figure 22: Europe Recyclable Thermosets Market Revenue (million), by End-use Industry 2026 & 2034
Figure 23: Europe Recyclable Thermosets Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 24: Europe Recyclable Thermosets Market Revenue (million), by Country 2026 & 2034
Figure 25: Europe Recyclable Thermosets Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Recyclable Thermosets Market Revenue (million), by Technology Type 2026 & 2034
Figure 27: Middle East & Africa Recyclable Thermosets Market Revenue Share (%), by Technology Type 2026 & 2034
Figure 28: Middle East & Africa Recyclable Thermosets Market Revenue (million), by Thermoset Type 2026 & 2034
Figure 29: Middle East & Africa Recyclable Thermosets Market Revenue Share (%), by Thermoset Type 2026 & 2034
Figure 30: Middle East & Africa Recyclable Thermosets Market Revenue (million), by End-use Industry 2026 & 2034
Figure 31: Middle East & Africa Recyclable Thermosets Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 32: Middle East & Africa Recyclable Thermosets Market Revenue (million), by Country 2026 & 2034
Figure 33: Middle East & Africa Recyclable Thermosets Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Recyclable Thermosets Market Revenue (million), by Technology Type 2026 & 2034
Figure 35: Asia Pacific Recyclable Thermosets Market Revenue Share (%), by Technology Type 2026 & 2034
Figure 36: Asia Pacific Recyclable Thermosets Market Revenue (million), by Thermoset Type 2026 & 2034
Figure 37: Asia Pacific Recyclable Thermosets Market Revenue Share (%), by Thermoset Type 2026 & 2034
Figure 38: Asia Pacific Recyclable Thermosets Market Revenue (million), by End-use Industry 2026 & 2034
Figure 39: Asia Pacific Recyclable Thermosets Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 40: Asia Pacific Recyclable Thermosets Market Revenue (million), by Country 2026 & 2034
Figure 41: Asia Pacific Recyclable Thermosets Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Recyclable Thermosets Market Revenue million Forecast, by Technology Type 2020 & 2034
Table 2: Recyclable Thermosets Market Revenue million Forecast, by Thermoset Type 2020 & 2034
Table 3: Recyclable Thermosets Market Revenue million Forecast, by End-use Industry 2020 & 2034
Table 4: Recyclable Thermosets Market Revenue million Forecast, by Region 2020 & 2034
Table 5: North America Recyclable Thermosets Market Revenue million Forecast, by Technology Type 2020 & 2034
Table 6: North America Recyclable Thermosets Market Revenue million Forecast, by Thermoset Type 2020 & 2034
Table 7: North America Recyclable Thermosets Market Revenue million Forecast, by End-use Industry 2020 & 2034
Table 8: North America Recyclable Thermosets Market Revenue million Forecast, by Country 2020 & 2034
Table 9: United States Recyclable Thermosets Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Recyclable Thermosets Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of data collection through primary research, including structured interviews with thermoset resin formulators for wind blade infusion, chemical recycling plant operators using solvolysis, waste composite shredders and feedstock aggregators, automotive Tier 1 composite part molders, and wind blade decommissioning contractors.
Target respondents include Wind Blade Materials Engineering Director, Thermoset Recycling Technology Manager, Composite Procurement Manager, and ESG Circular Economy Lead.
Interviews are supplemented with paid surveys and plant-level cost audits, ensuring granular coverage of capacity, throughput, and pricing.
Primary data is cross-validated against secondary sources and internal historical datasets to maintain an 85–90% estimated accuracy level.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Wind Blade Materials Engineering Director
30%
Thermoset Recycling Technology Manager
25%
Composite Procurement Manager
25%
ESG Circular Economy Lead
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Thermoset resin formulators
35%
Composite parts manufacturers
25%
Chemical recycling technology providers
18%
Wind blade OEMs
12%
Automotive Tier 1 composite molders
10%
Secondary Research & Industry Benchmarking
20–30% of research relies on secondary sources, including Bloomberg, Factiva, Hoovers, and PitchBook for financial and M&A data.
Trade association reports, .gov publications, and .org technical standards are used alongside company filings. No market research websites are cited.
Every report is updated to the date of purchase, with real-time alerts for regulatory and M&A changes.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up models use quantitative metrics: annual wind blade decommissioning tonnage by region, average epoxy resin content per turbine blade, chemical recycling plant nameplate capacity, and thermoset composite waste collection rate.
Top-down models reconcile global polymer composites production, regulatory recycled content targets, and end-use industry output.
Segment splits are derived from capacity surveys, material flow analysis, and price-volume correlations.
Data Accuracy & Quality Check
All estimates pass a three-tier validation: primary interview verification, secondary source cross-check, and internal expert review.
We guarantee an estimated data accuracy level of 85–90%, with confidence intervals reported for segment-level forecasts.
Outlier detection and triangulation remove double-counting across value chain stages.
Reports are refreshed at purchase, and any material variance above 5% triggers a re-validation.
Frequently Asked Questions
1. What notable recent developments and M&A activity have shaped the Recyclable Thermosets Market?
In 2023, Connora Technologies was acquired by a sustainable materials investment group, expanding its recyclable epoxy hardener portfolio. Mallinda launched a commercial vitrimer resin in 2024 for automotive composite parts. Aditya Birla Chemicals formed a partnership in 2024 Q2 to develop recyclable epoxy systems for wind turbine blades.
2. Which region dominates the Recyclable Thermosets Market and why?
Asia-Pacific holds the largest share at approximately 38% in 2025, driven by wind energy manufacturing scale in China and India. Europe follows at 28%, supported by EU circular economy regulations and blade recycling mandates. North America accounts for 22%, with growth tied to corporate ESG targets and DOE composite recycling funding.
3. How are pricing trends and cost structure evolving in the Recyclable Thermosets Market?
Recyclable epoxy resin prices range from $3.50 to $5.20 per kilogram, roughly 15–25% above virgin epoxy due to solvolysis and separation costs. Chemical recycling gate fees average $120–$180 per tonne, while mechanical processing costs $40–$70 per tonne. Scale-up and feedstock standardization are expected to narrow the premium to under 10% by 2030.
4. Who are the leading companies and what does the competitive landscape look like?
Aditya Birla Chemicals leads in epoxy resin supply, while Mallinda and Connora Technologies are challengers in reversible thermoset chemistry. INTCO Recycling and GAIKER-IK occupy niche positions in chemical recycling and R&D, respectively. The top five vendors control an estimated 42% of the recyclable thermoset revenue pool.
5. What are the main barriers to entry and competitive moats in the Recyclable Thermosets Market?
High capital intensity for chemical recycling plants, often exceeding $20 million per line, deters new entrants. Proprietary catalyst and vitrimer formulations create technical moats for Mallinda and Connora Technologies. Long qualification cycles in aerospace and wind energy, typically 18–36 months, further limit new competition.
6. Which disruptive technologies and emerging substitutes could reshape the Recyclable Thermosets Market?
Vitrimer and dynamic covalent network chemistries enable repeated reprocessing without losing mechanical performance, challenging traditional epoxy. Bio-based thermosets derived from lignin and plant oils are emerging as substitutes, with the Bio-based Thermoset Market projected to grow at 6.2% annually. Advanced recycling methods such as solvolysis and pyrolysis are also displacing energy recovery for composite waste.