Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Why APAC Dry Mix Mortar Market Will Grow at 5.33% CAGR?
Asia-Pacific Dry Mix Mortar Market
Why APAC Dry Mix Mortar Market Will Grow at 5.33% CAGR?
Asia-Pacific Dry Mix Mortar Market by Application (Concrete Protection and Renovation, Grouts, Insulation and Finishing Systems, Plaster, Render, Tile Adhesive, Water Proofing Slurries, Other Applications), by Country (Australia, China, India, Indonesia, Japan, Malaysia, South Korea, Thailand, Vietnam, Rest of Asia-Pacific), by End Use Sector (Commercial, Industrial and Institutional, Infrastructure, Residential), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 197
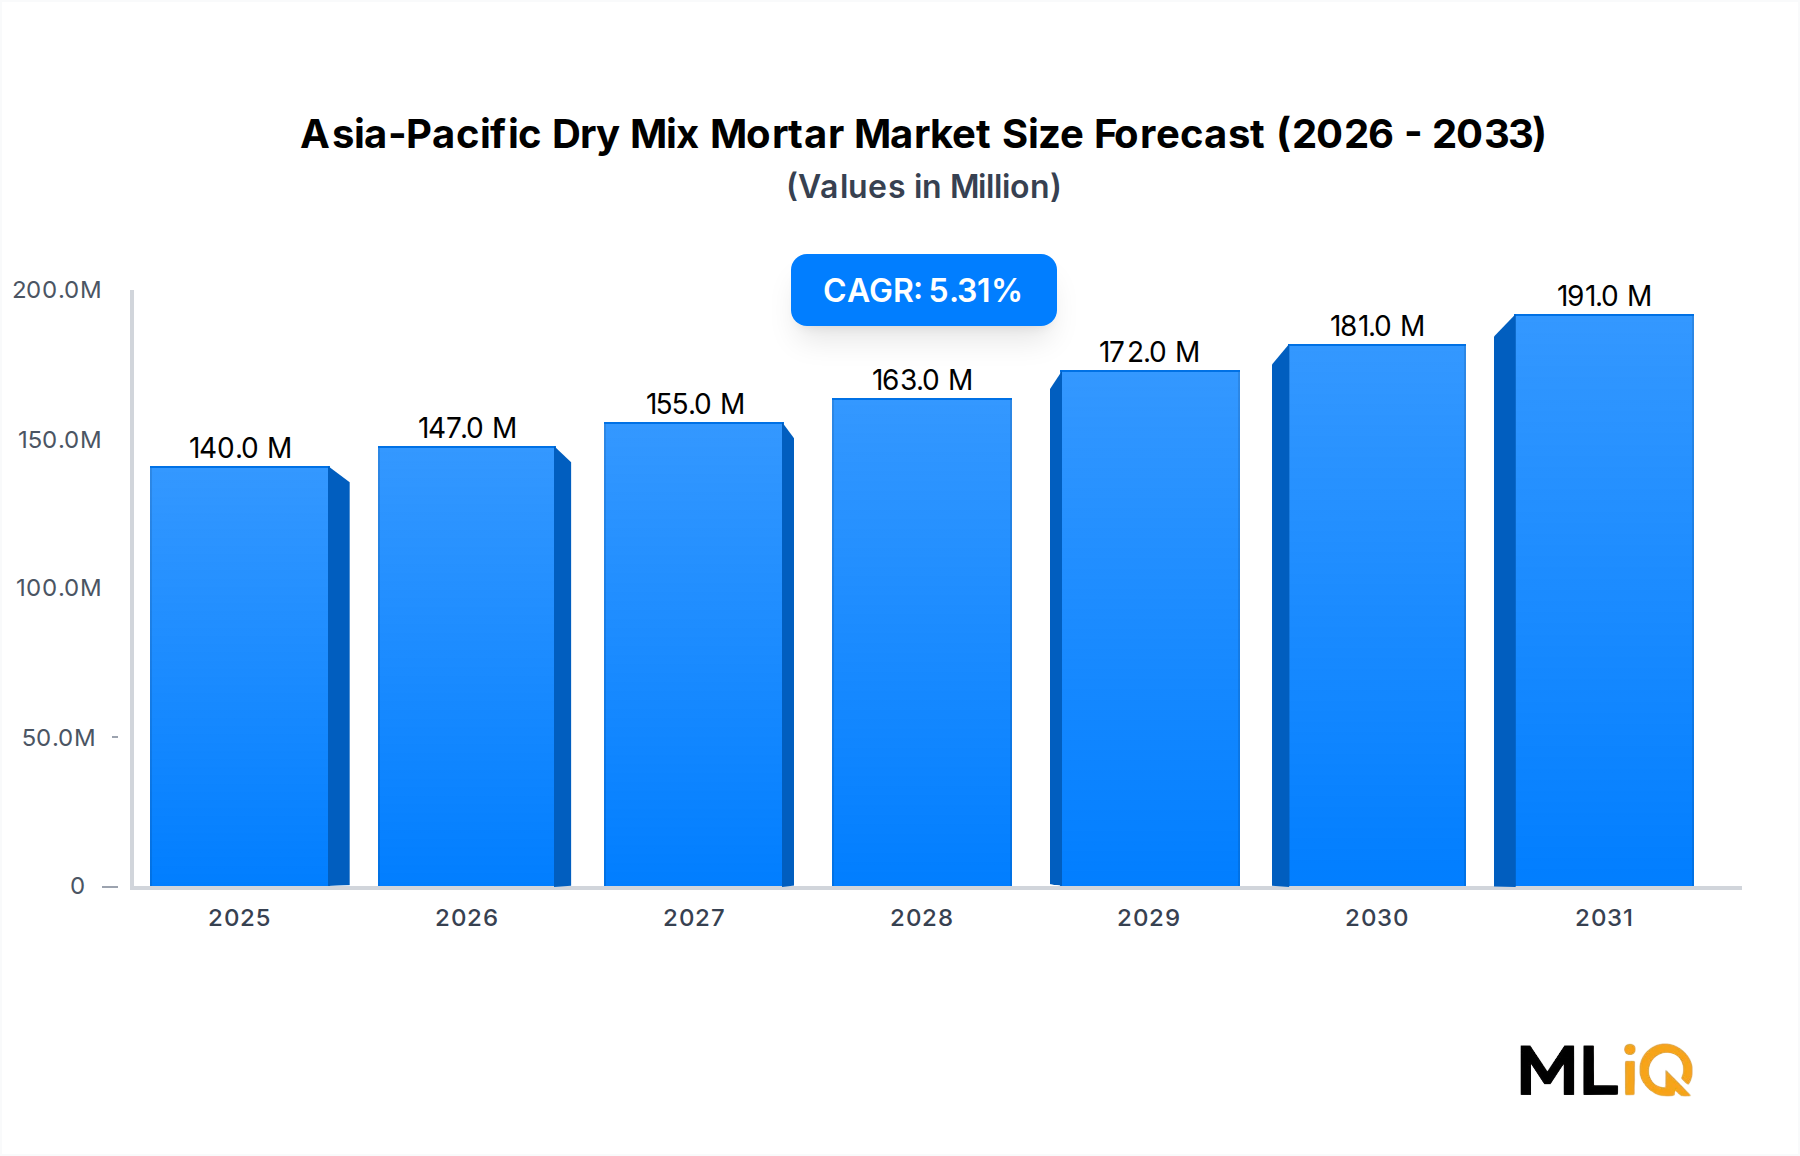
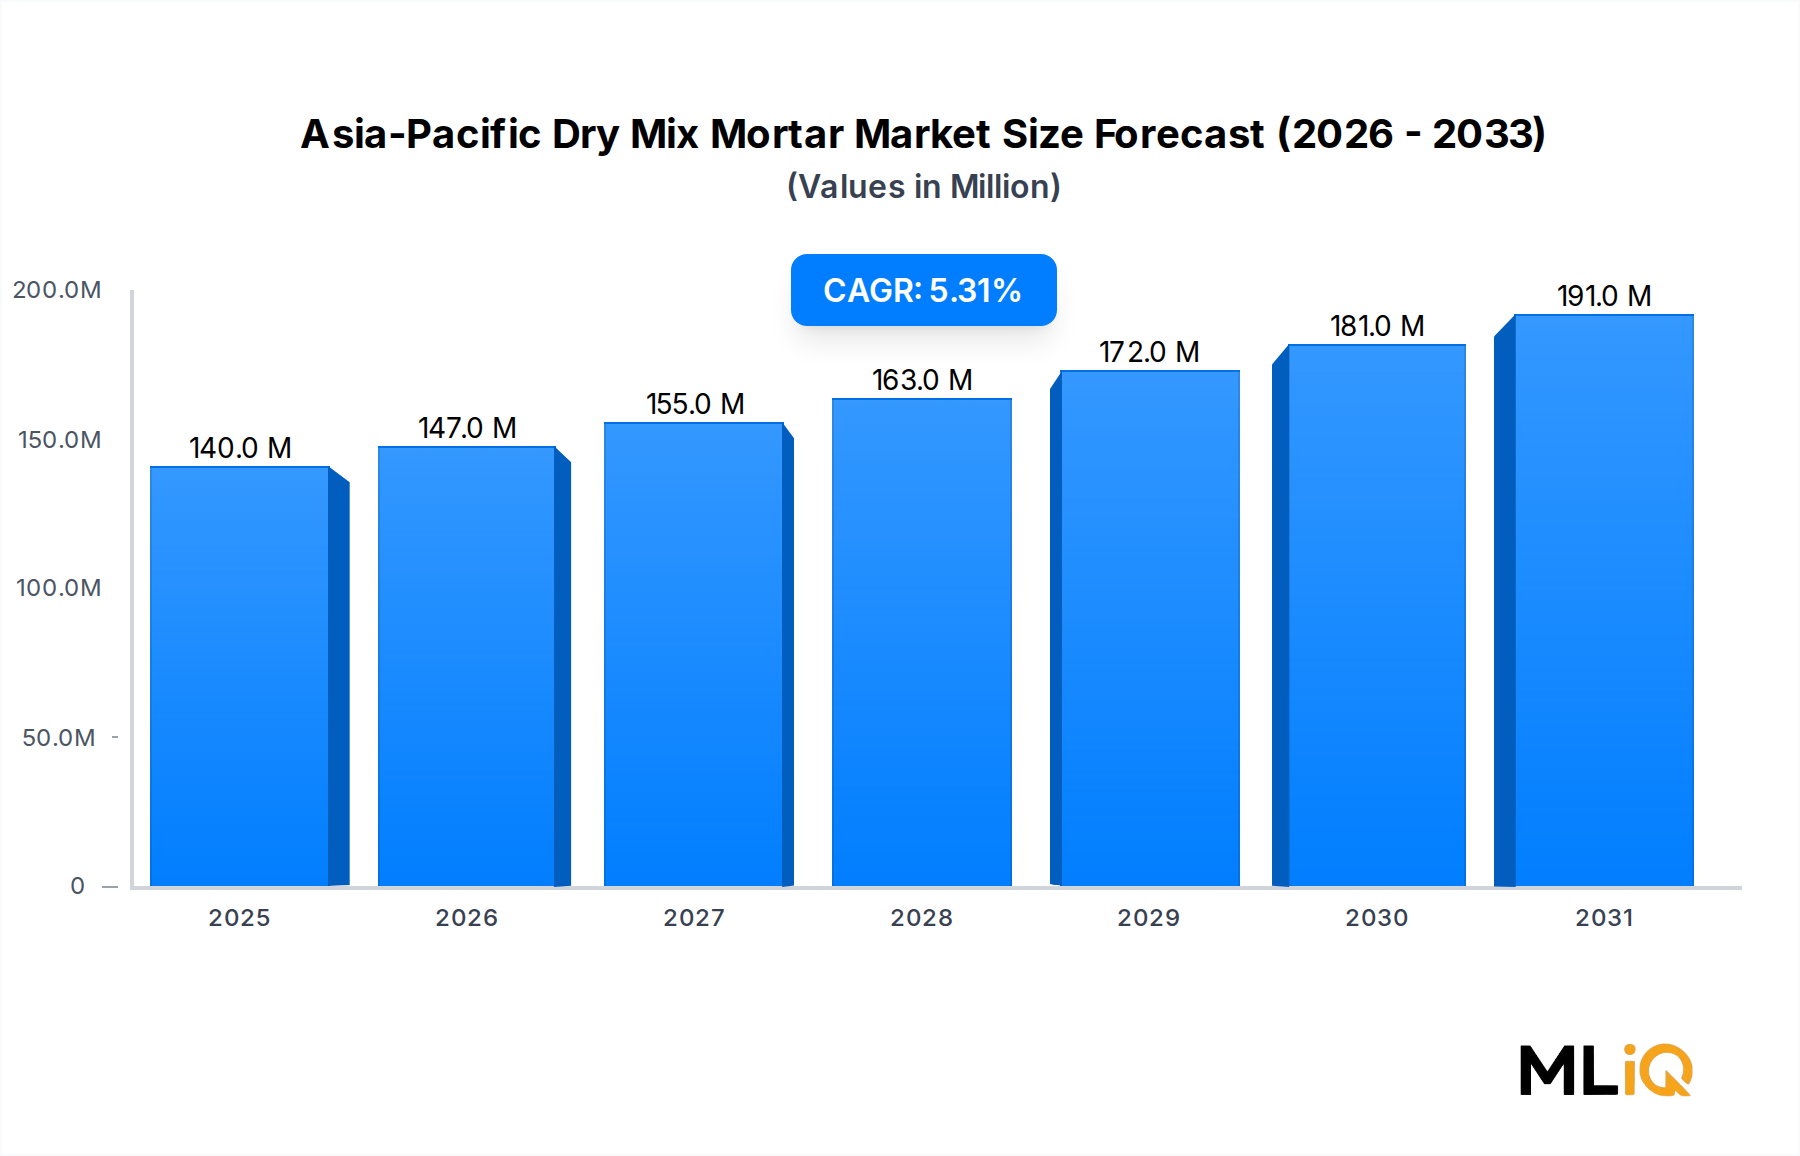
The Asia-Pacific Dry Mix Mortar Market was valued at USD 139.78 million in 2025 and is projected to reach USD 211.8 million by 2033, expanding at a 5.33% CAGR. Growth is tied to urbanization, infrastructure spending, and replacement of site-mixed mortar with factory-produced formulations. China, India, and Southeast Asia account for most volume, with tile adhesive, plaster, and render products leading demand. Government policies encouraging fly ash usage in construction materials lower raw material costs but also create quality and handling constraints. Competitive intensity is high among regional cement producers and global construction chemical firms. The market remains fragmented, with the top ten suppliers holding an estimated 38–42% revenue share. Strategic moves in 2023 included MBCC Group’s divestment to Sika AG and BBMG’s acquisition of a Tianjin mortar producer, signaling consolidation. For suppliers, the key opportunity is in high-performance, low-carbon formulations for green building projects. For contractors, supply reliability and technical support are decisive. For investors, the most attractive segments are tile adhesive and waterproofing slurries due to higher margins and replacement demand.
Asia-Pacific Dry Mix Mortar Market Size (In Million)
Ceramic tile consumption and rapid housing completions
Plaster Market
5.2%
22%
Interior and exterior wall finishing in residential projects
Water Proofing Slurries Market
5.8%
15%
Basement, roof, and wet-area waterproofing regulations
Tile adhesive is the largest revenue-generating segment, with an estimated 34% share of the Asia-Pacific Dry Mix Mortar Market in 2025. It is also among the fastest-growing, forecast at 6.1% CAGR through 2033. Demand is tied to ceramic tile installation in China, India, Vietnam, and Indonesia, where new housing and commercial floor space continue to expand. The Tile Adhesive Market benefits from polymer-modified formulations that improve adhesion, flexibility, and water resistance. Product differentiation centers on open time, slip resistance, and compatibility with large-format tiles. Margin pressure comes from rising polymer and cement costs, but premium products sustain 20–28% gross margins. The Plaster Market is the second-largest segment by volume, driven by residential wall finishing and repair. It is more price-sensitive, with local sand and cement availability shaping regional competitiveness. The Water Proofing Slurries Market is smaller but higher-margin, supported by stricter building codes for wet areas and foundations. Grouts, render, and concrete protection products together account for the remaining share. In cold-weather markets such as Japan and South Korea, demand shifts toward fast-setting and freeze-thaw resistant mortars. Overall, the segment mix favors suppliers with broad product portfolios and technical service teams.
Construction industry expansion and urbanization in China, India, and ASEAN
High
Short to long term
Driver
Government policies promoting fly ash usage in cement and mortar
High
Medium term
Driver
Replacement of site-mixed mortar with factory-produced dry mixes
Medium
Long term
Restraint
Harmful properties of fly ash, including heavy metals and handling risks
Medium
Short to medium term
Restraint
Non-suitability of standard dry mix mortars in cold weather conditions
High
Seasonal
The primary growth driver is increasing demand from the construction industry. Asia-Pacific accounts for over 60% of global cement consumption, and dry mix mortar penetration is rising as contractors seek consistent quality and reduced labor. Government policies in India and China promote fly ash in construction materials, which supports the Fly Ash Market and lowers raw material costs for mortar producers. However, fly ash can contain heavy metals and requires careful handling, creating environmental and worker safety concerns. Non-suitability in cold weather limits adoption in northern China, Korea, and Japan, where freeze-thaw cycles require specialized formulations. Another catalyst is the shift from job-site mixing to factory production, which reduces material waste by 10–15% and improves productivity. Infrastructure programs such as India’s National Infrastructure Pipeline and China’s Belt and Road investments support demand for grouts, render, and concrete protection. Restraints include volatile cement and polymer prices, fragmented distribution, and a shortage of skilled applicators. Regulatory stringency varies by country, with Japan and South Korea enforcing stricter VOC and dust limits than emerging Southeast Asian markets. The net effect is a market that grows steadily but faces regional volatility and raw material cost pressure.
The Construction Chemicals Market in Asia-Pacific is moderately concentrated, with global firms holding an estimated 38–42% share of dry mix mortar revenue. Regional cement producers leverage raw material integration, while global suppliers compete on formulation technology and specification approval.
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Sika AG
Global construction chemicals portfolio and MBCC integration
Infrastructure and commercial contractors
Leader
Saint-Gobain
Weber brand and distribution in Asia-Pacific
Residential and commercial builders
Leader
Oriental Yuhong
Waterproofing and mortar systems in China
Infrastructure, residential, commercial
Leader
MBCC Group
Master Builders Solutions and PCI brands
Industrial and institutional projects
Challenger
SCG
Cement and dry mix mortar in ASEAN
Residential and infrastructure
Leader
UltraTech Cement Ltd
Cement-backed dry mix mortar in India
Residential and infrastructure
Challenger
Asia Cement Co Ltd
Cement and mortar supply in Taiwan and China
Commercial and residential
Niche
BBMG Corporation
Integrated building materials and mortar in China
Infrastructure and residential
Challenger
HANIL HOLDINGS CO LTD
Dry mortar and construction materials in Korea
Commercial and residential
Niche
SAMPYO GROUP
Aggregate and mortar production in Korea
Industrial and residential
Niche
Sika AG: Acquired MBCC Group’s construction systems business in 2023, expanding dry mix mortar and admixture reach across Asia-Pacific. The company leverages global R&D for low-carbon and high-performance formulations.
Saint-Gobain: Its Weber business is a leading tile adhesive and render brand in China, India, and Southeast Asia. Distribution scale and technical training support premium pricing.
Oriental Yuhong: A major Chinese waterproofing and mortar supplier with strong infrastructure and residential channels. It invests in the Green Building Materials Market through integrated system solutions.
MBCC Group: Now part of Sika, its Master Builders Solutions and PCI brands retain a strong specification position in industrial and institutional projects.
SCG: Thailand’s cement major uses vertical integration to supply dry mix mortar across ASEAN. It benefits from local raw material access and contractor relationships.
UltraTech Cement Ltd: India’s largest cement producer extends into tile adhesive and plaster through its construction chemicals arm. It targets residential and infrastructure growth.
Asia Cement Co Ltd: Regional cement and mortar producer with a niche position in Taiwan and parts of China. It focuses on quality consistency and local service.
BBMG Corporation: Chinese integrated building materials group active in mortar and concrete. Its 2023 acquisition of Tianjin Jinyu Treasure Bright Mortar strengthened northern China distribution.
HANIL HOLDINGS CO LTD: Korean cement and dry mortar producer serving commercial and residential projects. It competes on technical support and cold-weather formulations.
SAMPYO GROUP: Korean aggregates and mortar supplier with industrial and residential focus. It emphasizes cost control and regional logistics.
Sold construction systems business to Sika AG, consolidating global dry mix mortar assets
October 2023: Beijing BBMG Mortar Co. Ltd acquired 30% equity in Tianjin Jinyu Treasure Bright Mortar Co. Ltd for approximately USD 2.43 billion. The deal expands BBMG’s mortar capacity and distribution in the Beijing-Tianjin-Hebei region.
May 2023: PCI, an affiliate of MBCC Group, launched PCI Novoment Flow, a ready-mixed flowable screed mortar. The product offers quick setting and curing, reducing project timelines for commercial flooring.
May 2023: MBCC Group divested its construction systems business to Sika AG. The transaction transferred subsidiaries, product portfolios, and technologies, increasing Sika’s share in the Asia-Pacific Dry Mix Mortar Market.
These moves indicate consolidation around global construction chemical platforms and regional cement leaders. Smaller producers face pressure to differentiate through service, formulation, or niche applications.
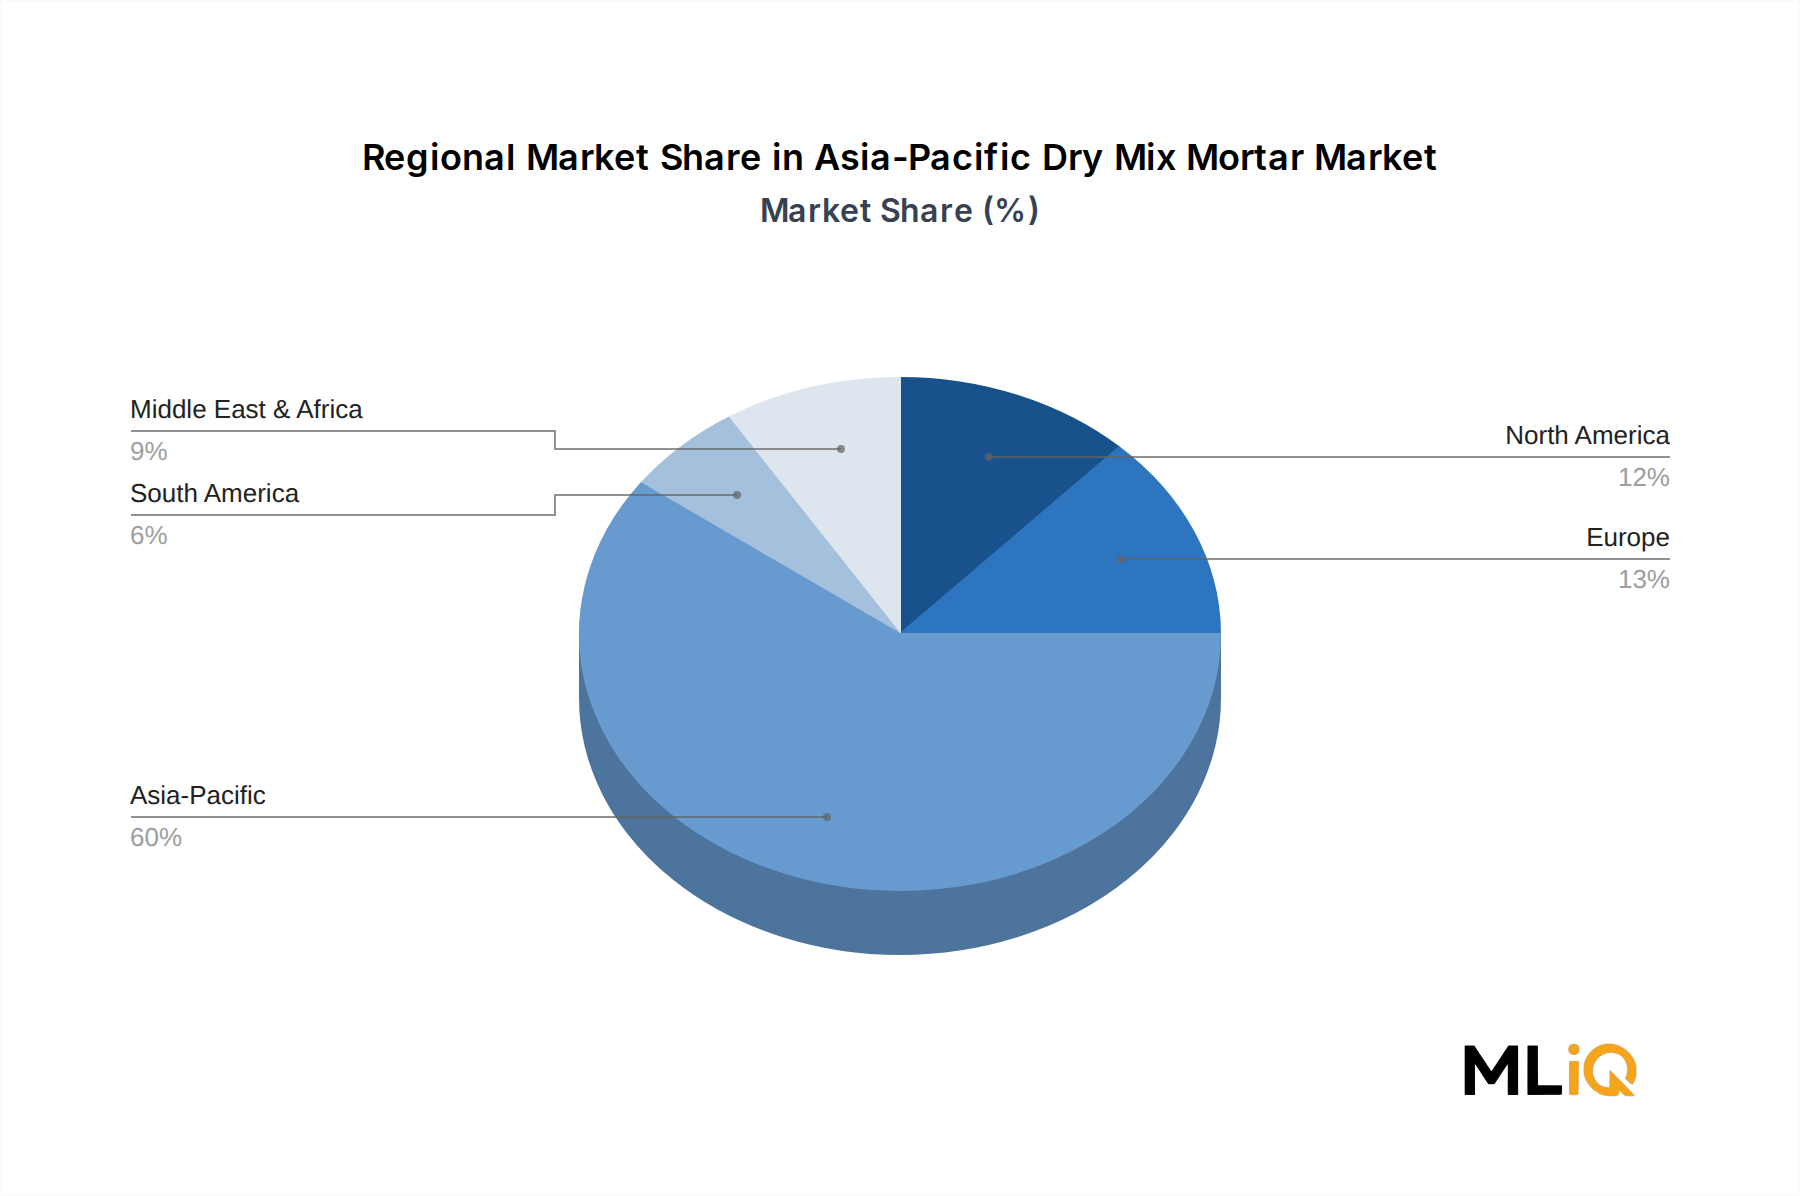
Asia-Pacific is both the largest and fastest-growing region for dry mix mortar, projected at 6.0% CAGR through 2033. China alone accounts for an estimated 45–50% of regional demand, driven by residential completions and infrastructure. India follows with 15–18% share, supported by government housing and the Infrastructure Construction Market. Southeast Asia, particularly Indonesia, Vietnam, and Thailand, is the fastest-growing sub-region due to foreign investment and urban migration. Japan and South Korea are mature markets with replacement demand and strict building codes. North America and Europe grow more slowly, with 3.5–3.8% CAGR, as renovation and the Green Building Materials Market drive premium product demand. LAMEA offers emerging opportunities but faces currency and logistics risks. Regulatory stringency is highest in Europe and Japan, where VOC limits and thermal performance standards shape formulations. The Residential Construction Market remains the largest end-use sector in Asia-Pacific, while infrastructure projects provide counter-cyclical demand. Suppliers should prioritize China and India for scale, and Vietnam and Indonesia for margin expansion.
Dry mix mortar trade is primarily intra-regional because of high logistics costs relative to product value. Key net exporters include China, Thailand, and Vietnam, which ship tile adhesive, grout, and render to Southeast Asia, the Middle East, and Africa. Key importers include Indonesia, the Philippines, and Australia, where local production is insufficient or raw materials are costly. Tariff barriers are generally low under ASEAN-China FTA and RCEP, but non-tariff barriers such as certification, packaging labeling, and VOC limits add cost. For example, Australia’s building code compliance and Japan’s JIS standards require product testing that can delay entry by 3–6 months. Geopolitical tensions and shipping cost volatility affect cross-border shipment volumes, especially for polymer additives sourced from Europe. The Ready-Mix Concrete Market and Construction Chemicals Market also influence trade in complementary admixtures and fibers. Exporters with local blending facilities reduce tariff exposure and improve service. Over the forecast period, trade flows will shift toward higher-value, low-carbon formulations.
Average selling prices (ASP) for dry mix mortar in Asia-Pacific range from USD 180–260 per ton for standard plaster and render, and USD 320–480 per ton for high-performance tile adhesive and waterproofing slurries. Raw materials account for 55–65% of production cost, with cement, sand, polymers, and additives being the main inputs. Energy and logistics represent 15–20%, and labor and overhead make up the remainder. Margin pressure is intense in commodity plaster, where local competition and sand availability set price ceilings. Differentiated products with technical certifications sustain 22–30% gross margins, while standard mortars often operate at 10–15%. Inflation in cement and polymer prices in 2022–2024 squeezed margins, but producers passed through 5–9% price increases in India and ASEAN. Pricing power is strongest for global brands with specification approval and for suppliers integrated with cement or fly ash sources. The Fly Ash Market provides a cost advantage when quality is consistent, but variability can increase reject rates. Logistics costs favor regional production over long-distance export, limiting trade in low-value products. Overall, margin expansion depends on product mix, local sourcing, and technical service.
Asia-Pacific Dry Mix Mortar Market Segmentation
1. Application
1.1. Concrete Protection and Renovation
1.2. Grouts
1.3. Insulation and Finishing Systems
1.4. Plaster
1.5. Render
1.6. Tile Adhesive
1.7. Water Proofing Slurries
1.8. Other Applications
2. Country
2.1. Australia
2.2. China
2.3. India
2.4. Indonesia
2.5. Japan
2.6. Malaysia
2.7. South Korea
2.8. Thailand
2.9. Vietnam
2.10. Rest of Asia-Pacific
3. End Use Sector
3.1. Commercial
3.2. Industrial and Institutional
3.3. Infrastructure
3.4. Residential
Asia-Pacific Dry Mix Mortar Market Segmentation By Geography
Table 52: Rest of Asia Pacific Asia-Pacific Dry Mix Mortar Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of data inputs come from primary interviews, surveys, and field visits; 20–30% from secondary sources.
We interview 4–5 specific company types: dry mix mortar plant operators, tile adhesive formulators, polymer additive suppliers, fly ash processing companies, and automated batching equipment vendors.
Stakeholder titles include Dry Mix Mortar Procurement Director, Construction Chemicals R&D Manager, Infrastructure Project Specification Engineer, and Tile Adhesive Product Line Manager.
Primary research covers pricing, capacity utilization, product certification, and channel margins across Australia, China, India, Indonesia, Japan, Malaysia, South Korea, Thailand, Vietnam, and Rest of Asia-Pacific.
Regulatory databases from Japan’s Ministry of Land, Infrastructure, Transport and Tourism (MLIT) and Australia’s Department of Industry, Science and Resources (DISR) are reviewed for building codes and material standards.
No market research websites are cited as primary sources; all third-party market estimates are used only for triangulation.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up variables include annual tile adhesive consumption per 1,000 new housing units, average dry mix mortar plant capacity utilization rate, fly ash availability from coal power plants per region, and square meters of wall and floor tiling installed per capita.
Top-down modeling uses construction output, cement consumption, and infrastructure spending from national statistics offices.
Segment forecasts are built by application, country, and end-use sector, with cross-checks against company revenue disclosures and import-export records.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%.
Every report is updated to the date of purchase; historical baselines are revised when new cement, construction, or trade data become available.
Quality checks include outlier detection, expert review, and reconciliation of primary interview ranges with secondary benchmarks.
Final market sizes are rounded to the nearest USD 0.1 million and CAGR to two decimal places.
Frequently Asked Questions
1. Who are the leading companies in the Asia-Pacific Dry Mix Mortar Market?
Sika AG, Saint-Gobain, Oriental Yuhong, SCG, and UltraTech Cement Ltd are among the leaders. MBCC Group, now part of Sika, remains a major challenger through Master Builders Solutions and PCI brands. The top ten suppliers control an estimated 38–42% revenue share, leaving room for regional consolidation.
2. What barriers to entry and competitive moats shape the Asia-Pacific Dry Mix Mortar Market?
High logistics costs, local sand and cement sourcing, and contractor specification approval create entry barriers. Established suppliers benefit from distribution networks, technical service teams, and brand trust in tile adhesive and waterproofing systems. Regulatory certification for VOC limits and building codes adds 3–6 months to market entry, favoring incumbents.
3. What is the current market size and CAGR projection through 2033 for the Asia-Pacific Dry Mix Mortar Market?
The market was valued at USD 139.78 million in 2025 and is forecast to reach USD 211.8 million by 2033, expanding at a 5.33% CAGR. Growth is supported by construction activity in China, India, and ASEAN. Tile adhesive is the dominant segment with an estimated 34% share.
4. How do export-import dynamics affect the Asia-Pacific Dry Mix Mortar Market?
Trade is mostly intra-regional because dry mix mortar is heavy and low-value relative to freight costs. China, Thailand, and Vietnam are net exporters of tile adhesive and grout to Southeast Asia and the Middle East. RCEP and ASEAN-China FTA reduce tariffs, but Australian and Japanese certification standards act as non-tariff barriers.
5. What are the primary growth drivers and demand catalysts in the Asia-Pacific Dry Mix Mortar Market?
Urbanization, infrastructure spending, and the shift from site-mixed mortar to factory-produced dry mixes are the main catalysts. Government policies promoting fly ash usage lower raw material costs for the Fly Ash Market and mortar producers. India’s National Infrastructure Pipeline and China’s Belt and Road investments support demand for grouts, render, and concrete protection.
6. Which technological innovations and R&D trends are shaping the Asia-Pacific Dry Mix Mortar Market?
Polymer-modified formulations for large-format tile adhesion, fast-setting screeds, and low-carbon cement blends are leading R&D areas. PCI’s Novoment Flow launched in May 2023 with quick-setting and curing properties. Suppliers are also developing dust-reduced and VOC-compliant products for green building materials.