Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Non-woven Adhesives Market to Reach $14.0B by 2033, 9.9% CAGR
Non-woven Adhesives Market
Non-woven Adhesives Market to Reach $14.0B by 2033, 9.9% CAGR
Non-woven Adhesives Market by Type (Styrenic Block Copolymers, Ethylene Vinyl Acetate, Polyolefin, Others), by Application (Baby Diapers, Feminine Hygiene, Adult Incontinence, Medical Products, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 150
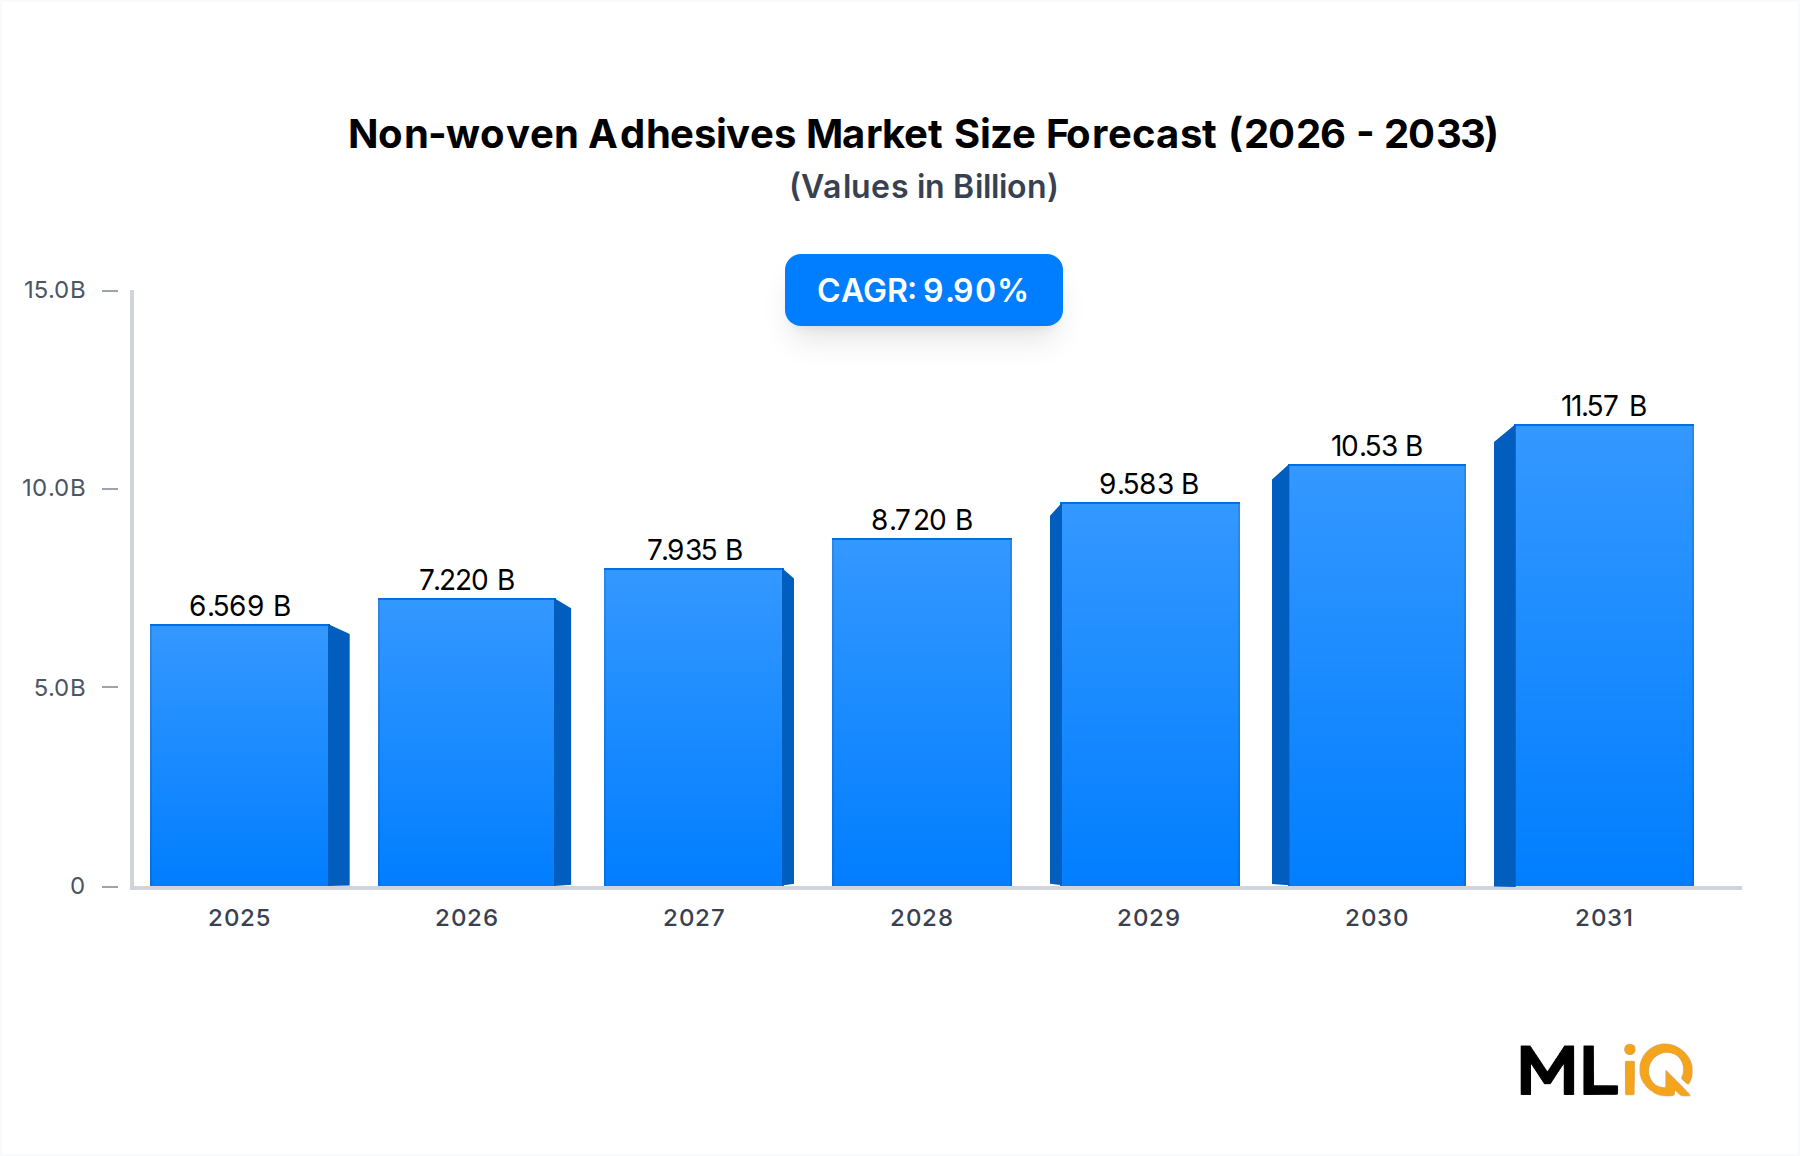
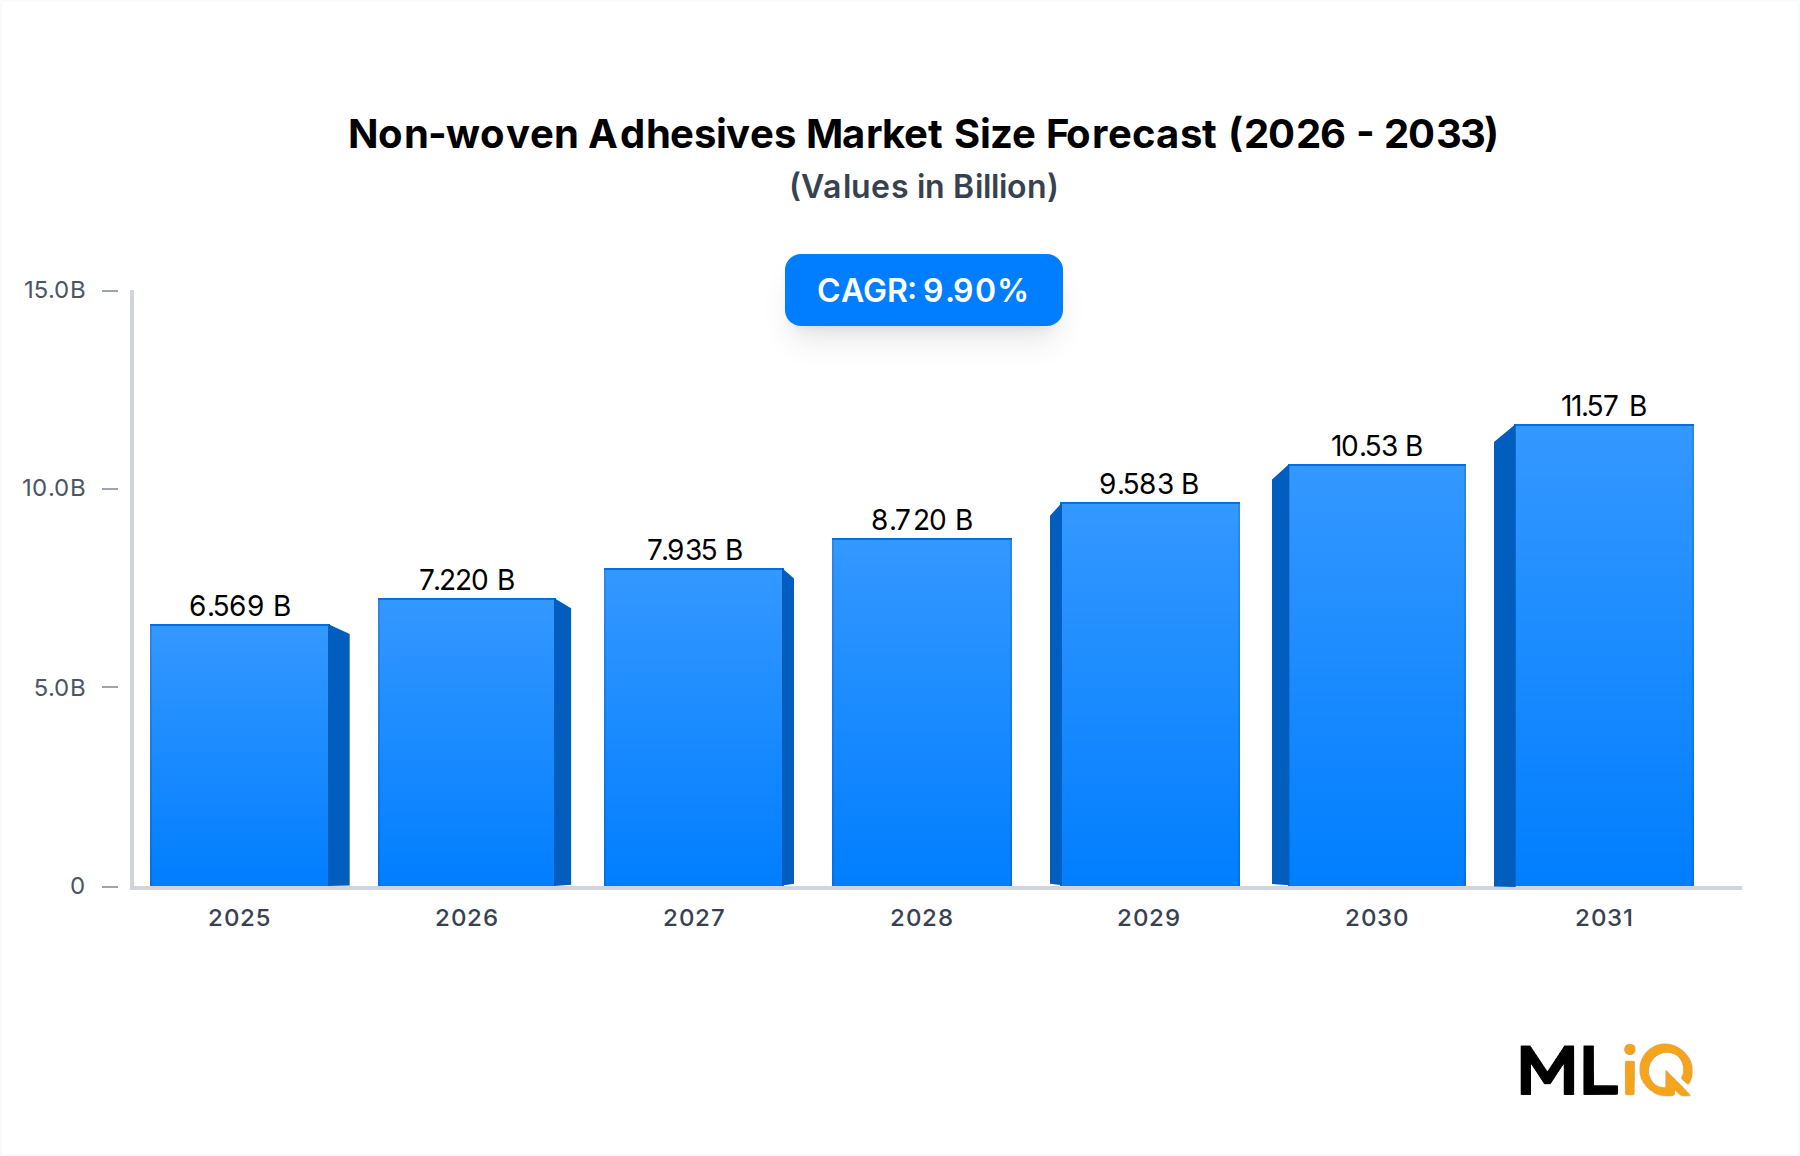
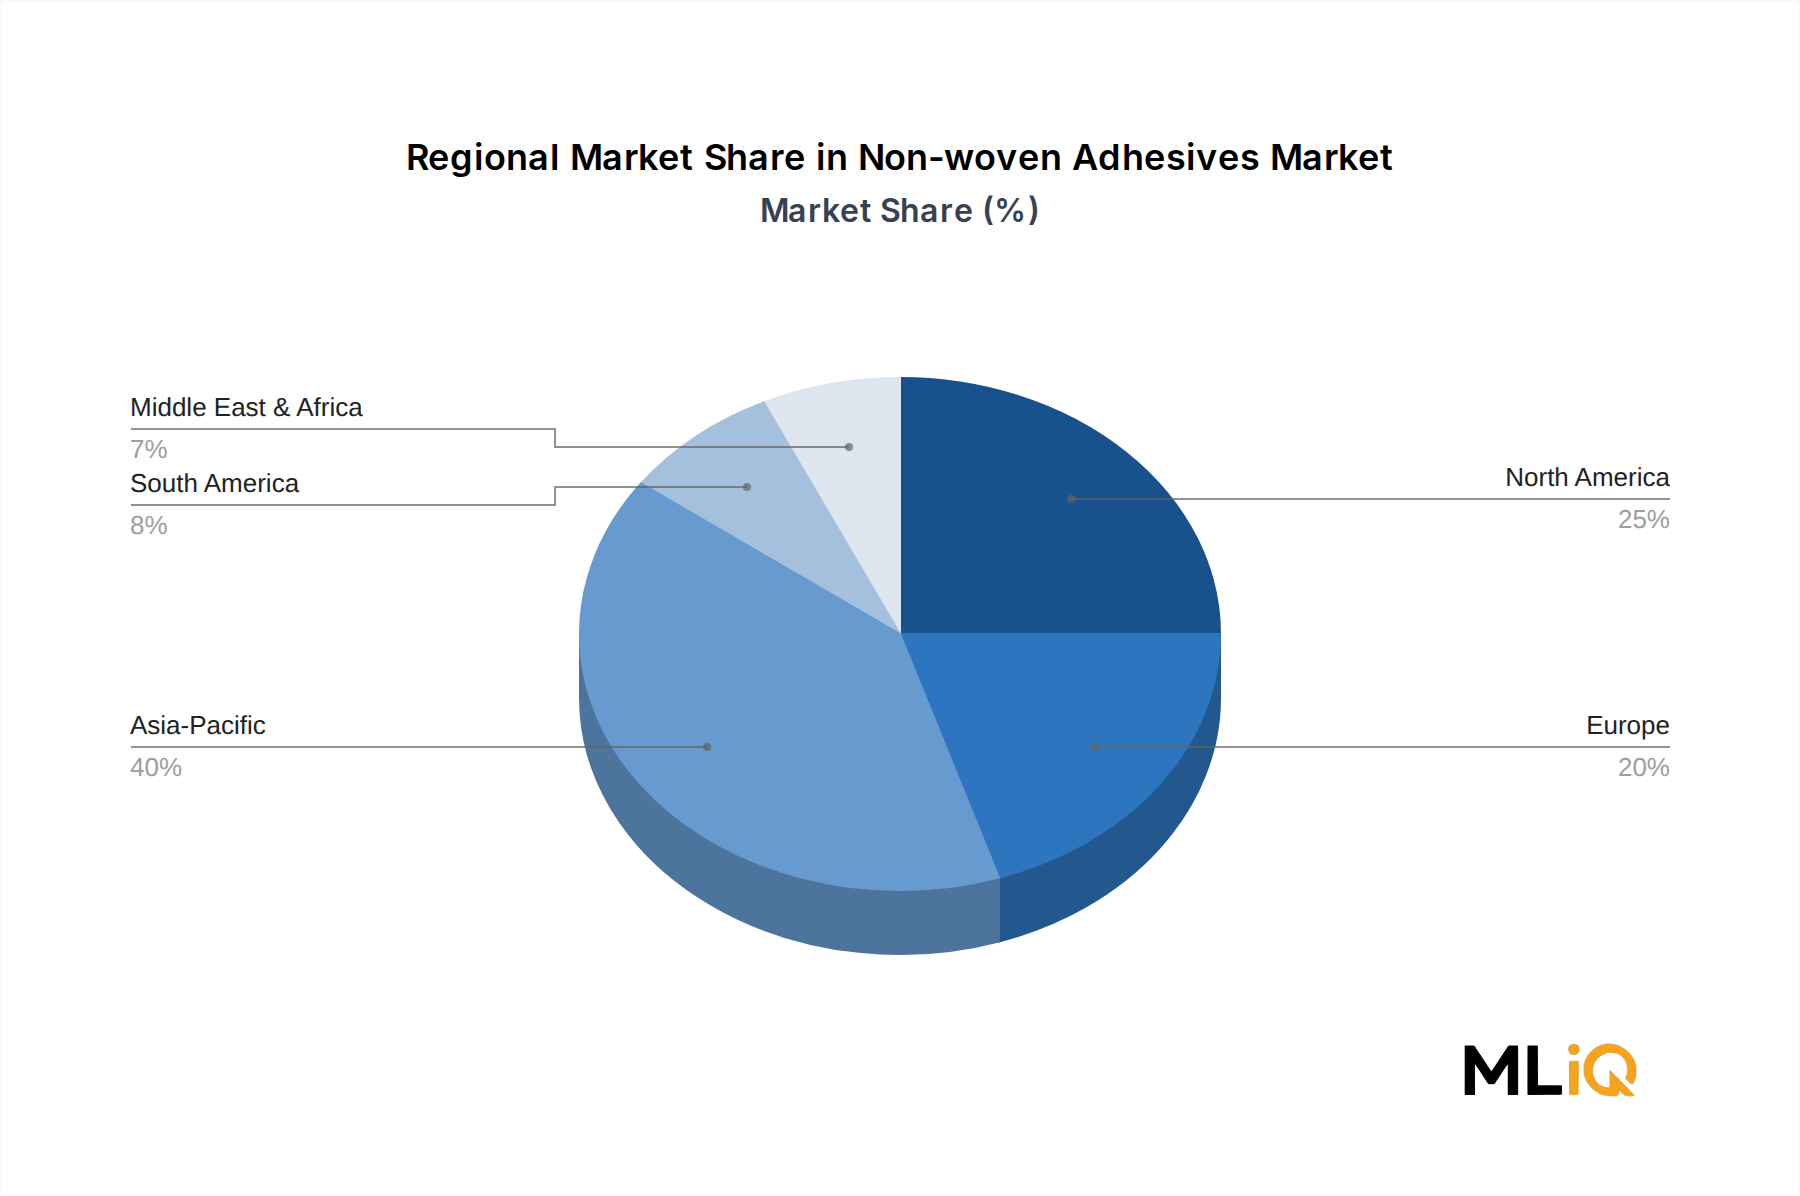
The Non-woven Adhesives Market is projected to grow from $6,569.48 million in 2025 to $13,963 million by 2033, registering a 9.9% CAGR. This growth is underpinned by increasing demand for disposable hygiene products and medical supplies. Asia-Pacific is the largest regional market, holding a 40% share, driven by high birth rates and expanding healthcare infrastructure in China and India. North America and Europe follow, with mature markets focusing on product innovation and sustainability. The Baby Diapers Market represents the dominant application, accounting for 50% of total consumption, while the Feminine Hygiene Market and Adult Incontinence segments are also significant. Among product types, the Styrenic Block Copolymers Market leads with a 45% share, favored for its elasticity and thermal stability. The Ethylene Vinyl Acetate Market and Polyolefin Adhesives Market are also prominent, with polyolefin gaining traction due to low odor and color stability. Rising adoption of Hot Melt Adhesives Market technologies, which now represent over 60% of adhesive volume in non-woven applications, enhances production speed and reduces energy costs. The Pressure Sensitive Adhesives Market is expanding in medical tapes and wound care, complementing traditional thermal adhesives. However, the Adhesives and Sealants Market faces headwinds from volatile raw material prices, which escalated by 15-20% in 2022-2023, squeezing margins. Regulatory pressures, such as the EU's REACH and FDA's medical device guidelines, are pushing formulators toward bio-based and low-VOC chemistries. Strategic initiatives include Henkel's launch of a bio-based adhesive for hygiene products in 2024, reducing carbon footprint by 30%. The forecast period 2025-2033 is expected to witness consolidation, with key players acquiring regional formulators to expand capacity. Macro drivers include urbanization, rising female workforce participation, and aging populations in developed regions, which boost demand for adult incontinence products. Technological shifts, such as the integration of smart adhesives with sensors for medical monitoring, are emerging but remain niche. The competitive landscape is moderately consolidated, with the top five players accounting for ~55% of global revenue. Investment in R&D for sustainable raw materials is a critical differentiator. Overall, the market presents robust opportunities, but stakeholders must navigate supply chain disruptions and compliance costs.
Non-woven Adhesives Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.569 B
2025
7.220 B
2026
7.935 B
2027
8.720 B
2028
9.583 B
2029
10.53 B
2030
11.57 B
2031
Segment Deep-Dive: Baby Diapers Dominance in Non-woven Adhesives Market
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Baby Diapers
9.5%
50%
Rising birth rates in emerging markets
Feminine Hygiene
10.2%
25%
Increasing female hygiene awareness
Adult Incontinence
11.0%
15%
Aging population in developed regions
The Baby Diapers Market dominates the Non-woven Adhesives Market, accounting for 50% of total consumption in 2025. This segment's growth is driven by high birth rates in Asia-Pacific and Africa, coupled with increasing disposable income. Diaper manufacturers demand adhesives with high cohesion, low creep, and excellent adhesion to polyolefin films. Styrenic block copolymers are preferred for their balance of elasticity and tack, but the Ethylene Vinyl Acetate Market offers cost-effective alternatives for lower-performance applications. The Polyolefin Adhesives Market is gaining share in diapers due to its low odor and thermal stability, though at a higher price point. Margin pressures arise from raw material price fluctuations, particularly for styrene and butadiene, which can vary by 20-30% annually. Formulators are investing in bio-based raw materials to mitigate volatility and meet sustainability targets. Within the feminine hygiene segment, the Feminine Hygiene Market is expanding at 10.2% CAGR, driven by product innovation such as ultra-thin pads and panty liners. Adult incontinence is the fastest-growing segment at 11.0% CAGR, fueled by demographic shifts in Japan, Europe, and North America. The Medical Adhesives Market, overlapping with these applications, requires specialized formulations that meet biocompatibility standards. Overall, baby diapers remain the volume anchor, but adult incontinence presents the highest growth potential.
Baby Diapers: Volume Anchor
The Baby Diapers Market commands the largest share, with global consumption exceeding 100 billion units annually. Adhesive content per diaper ranges from 0.5 to 1.5 grams, translating to significant volume. Innovations focus on reducing adhesive coat weight without compromising bond strength, driven by cost and sustainability. Key suppliers like Henkel and H.B. Fuller provide tailored solutions that enhance line speeds up to 1,000 diapers per minute.
Feminine Hygiene: Steady Growth
The Feminine Hygiene Market is projected to grow at 10.2% CAGR, with increasing demand for organic and biodegradable products. Adhesives must balance skin-friendliness with secure attachment. The shift toward ultra-thin pads reduces adhesive usage per unit but increases performance requirements.
Adult Incontinence: Emerging Opportunity
The Adult Incontinence segment is the fastest-growing at 11.0% CAGR, propelled by aging populations. In Japan, over 30% of the population is above 65, driving demand. Adhesives for adult incontinence products require higher absorbency and odor control, often using specialized polyolefin-based formulations. Margin pressures: Raw material costs account for 60-70% of adhesive production costs. Price volatility in crude oil derivatives directly impacts profitability. Formulators are pursuing long-term contracts and backward integration to stabilize supply. The Styrenic Block Copolymers Market remains dominant but faces competition from Ethylene Vinyl Acetate Market in cost-sensitive regions.
Primary Market Drivers & Growth Restraints in Non-woven Adhesives Market
Factor Type
Description
Impact Level
Timeline
Driver
Rising demand for disposable hygiene products
High
Short-term
Driver
Technological advancements in hot melt adhesives
High
Medium-term
Driver
Growth in medical and healthcare applications
Medium
Long-term
Restraint
Volatile raw material prices
High
Short-term
Restraint
Stringent environmental regulations
Medium
Long-term
Restraint
Supply chain disruptions
Medium
Short-term
Key drivers include the expanding global population and increasing hygiene awareness, particularly in Asia-Pacific and Africa. The Baby Diapers Market alone is expected to add $2.1 billion in adhesive demand by 2033. Hot Melt Adhesives Market technologies offer processing advantages, such as solvent-free application and lower energy consumption, reducing production costs by 15-20%. The Medical Adhesives Market is driven by an aging population and the rise of home healthcare, requiring specialized pressure-sensitive adhesives. Restraints: Raw material price volatility, especially for styrenic block copolymers and ethylene vinyl acetate, directly impacts margins. Environmental regulations, such as the EU's Single-Use Plastics Directive, are pushing manufacturers to develop recyclable and biodegradable adhesives, increasing R&D costs. Supply chain risks include geopolitical tensions affecting petrochemical feedstock availability and logistics disruptions. The Pressure Sensitive Adhesives Market faces similar pressures but benefits from diversification into electronics and automotive. Overall, drivers outweigh restraints, but companies must invest in sustainable sourcing and compliance to maintain competitiveness. Regulatory landscape: FDA and EMA guidelines for medical adhesives require rigorous testing, adding 6-12 months to product development cycles. The Adhesives and Sealants Market is also influenced by trade policies, such as tariffs on raw materials from China, which can increase costs by 10-15%. On the demand side, urbanization and rising female workforce participation boost feminine hygiene product usage. In mature markets, adult incontinence is a key growth driver, with Japan's adult diaper market growing at 12% annually. Technological trends include the development of bio-based adhesives from plant starches and soy, which reduce carbon footprint by up to 50%. However, bio-based adhesives often underperform in high-speed manufacturing, limiting adoption. Companies are investing in hybrid solutions that blend bio-based and synthetic polymers. The competitive intensity is high, with over 200 formulators globally, but the top 10 control ~70% of the market. This concentration allows leaders to influence pricing and innovation. Restraints also include the high cost of switching adhesives in existing production lines, which can deter end-users from adopting new formulations.
Henkel AG & Co. KGaA: Global leader with a wide range of hot melt adhesives for hygiene applications. Its Technomelt series is widely adopted in baby diapers.
3M Corporation: Focuses on medical-grade pressure-sensitive adhesives, leveraging its healthcare division. Strong in wound care and transdermal patches.
H.B. Fuller Company: Provides custom adhesive solutions and has a significant presence in North America and Europe. Recent acquisitions expanded its hygiene portfolio.
Bostik SA (ARKEMA): Emphasizes sustainable adhesives, including bio-based options. Targets feminine hygiene and medical markets.
The Dow Chemical Company: Integrates raw material production with adhesive formulation, offering cost advantages. Supplies ethylene vinyl acetate and polyolefin-based adhesives.
Evonik Industries AG: Specializes in high-performance specialty chemicals, including bio-based adhesives. Focuses on medical and hygiene applications.
Kraton Corporation: Leading producer of styrenic block copolymers, a key raw material for non-woven adhesives. Its polymers enhance elasticity and adhesion.
Moresco Corporation: Japanese formulator known for olefin-based adhesives with low odor. Strong in Asia-Pacific hygiene market.
The competitive landscape is moderately consolidated, with the top five players holding ~55% share. Strategic moves include capacity expansions in Asia and investments in bio-based R&D. Niche players compete on specialty formulations and regional service.
Strategic Milestones & Recent Developments in Non-woven Adhesives Market
Date
Company
Event Type
Impact
2023
Henkel
Product Launch
Bio-based adhesive for hygiene, 30% lower carbon footprint
2024
H.B. Fuller
Acquisition
Acquired an Asian adhesive producer to expand capacity
2023
3M
Partnership
Collaborated with medical device firm for advanced wound care adhesives
2022
Bostik
Product Launch
Introduced recyclable hot melt adhesive for feminine hygiene
2024
Kraton
Expansion
Increased SBC production capacity in Europe by 20%
2022: Bostik launched a recyclable hot melt adhesive for feminine hygiene, aligning with EU circular economy goals.
2023: Henkel introduced a bio-based adhesive for baby diapers, reducing carbon footprint by 30% and meeting demand for sustainable products.
2023: 3M partnered with a medical device company to develop pressure-sensitive adhesives for wearable health monitors, expanding into digital health.
2024: H.B. Fuller acquired a specialty adhesive producer in Asia, adding 15,000 metric tons of annual capacity to serve regional hygiene manufacturers.
2024: Kraton expanded its styrenic block copolymer capacity in Europe by 20% to meet growing demand from the Feminine Hygiene Market.
2025: Evonik announced a new bio-based polyolefin adhesive for medical applications, targeting a 25% reduction in VOC emissions.
These developments indicate a strategic shift toward sustainability and regional capacity building. The Medical Adhesives Market is a key focus area, with companies investing in biocompatible formulations.
Regional Market Analysis & Growth Corridors for Non-woven Adhesives Market
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
11.2%
$2,627.8 million
Population growth, urbanization
Medium
North America
8.5%
$1,642.4 million
Medical innovations, aging population
High
Europe
8.0%
$1,313.9 million
Sustainability mandates
High
South America
9.0%
$525.6 million
Hygiene awareness, economic growth
Low
Middle East & Africa
10.5%
$459.9 million
Rising birth rates, healthcare investment
Low
Asia-Pacific is the fastest-growing region, with a 11.2% CAGR, driven by China and India. China alone accounts for 40% of regional demand, supported by local diaper production. North America is a mature market with a 8.5% CAGR, focusing on advanced medical adhesives and adult incontinence. Europe grows at 8.0%, with stringent regulations driving bio-based adhesive adoption. The region's focus on circular economy is reshaping product design. South America shows moderate growth at 9.0%, with Brazil leading due to increasing hygiene product penetration. The Middle East & Africa is an emerging market with 10.5% CAGR, fueled by population growth and improving healthcare infrastructure. Regulatory stringency varies: North America and Europe have high compliance requirements, while Asia-Pacific and LAMEA have more lenient frameworks, though tightening. The Medical Adhesives Market is a key growth corridor in North America and Europe, while the Baby Diapers Market drives volume in Asia-Pacific. In Asia-Pacific, capacity expansions by Henkel and H.B. Fuller are reducing import reliance. In North America, the aging population (over 20% above 65 by 2030) boosts adult incontinence demand. Europe's regulatory stringency, including REACH and the Single-Use Plastics Directive, pushes formulators toward recyclable adhesives, increasing R&D costs but creating differentiation. South America's growth is constrained by economic volatility, but Brazil's large birth rate supports the Baby Diapers Market. Middle East & Africa benefits from rising healthcare expenditure, particularly in GCC countries. The Adhesives and Sealants Market in these regions is also influenced by construction and automotive sectors, but non-woven adhesives remain a niche high-growth segment.
Sustainability, ESG & Decarbonization Pressures on Non-woven Adhesives Market
The Non-woven Adhesives Market faces increasing pressure to decarbonize. The EU's Green Deal and Circular Economy Action Plan mandate recyclable and bio-based materials. Net-zero targets by 2050 from major brands like Procter & Gamble and Kimberly-Clark are pushing adhesive suppliers to reduce carbon footprints. Bio-based raw materials, such as plant-based starches and soy, are gaining traction, but performance trade-offs remain. The Styrenic Block Copolymers Market is challenged to develop bio-based SBCs, while the Ethylene Vinyl Acetate Market benefits from bio-EVA innovations. Manufacturing processes are shifting to solvent-free hot melt adhesives, which reduce VOC emissions by up to 90%. ESG investor criteria are influencing procurement, with companies scoring higher on sustainability indices gaining preferential supplier status. However, the higher cost of bio-based adhesives (20-30% premium) limits adoption in price-sensitive markets. The Medical Adhesives Market faces additional biocompatibility requirements. Overall, sustainability is a double-edged sword: it drives innovation but adds cost and complexity.
Export, Cross-Border Trade & Tariff Impact on Non-woven Adhesives Market
Major trade corridors for non-woven adhesives include Asia-Pacific to North America and Europe. China is the largest net exporter, accounting for 35% of global adhesive exports, followed by South Korea and Japan. Europe is a net importer, sourcing from Southeast Asia due to cost advantages. Tariffs on raw materials, such as the US Section 301 tariffs on Chinese chemicals, have increased input costs by 10-15%, prompting some manufacturers to shift sourcing to India and Southeast Asia. The USMCA agreement facilitates trade within North America, but rules of origin require substantial transformation, impacting adhesive formulations. Non-tariff barriers, such as REACH compliance in Europe, add testing and documentation costs. Geopolitical tensions, including the Russia-Ukraine conflict, have disrupted petrochemical feedstock supply, causing price spikes. The Adhesives and Sealants Market is also affected by these trade dynamics. Post-pandemic, companies are diversifying supply chains, with nearshoring to Mexico and Eastern Europe. Export volumes of non-woven adhesives are projected to grow at 7% annually through 2033, driven by hygiene product demand. However, trade policy uncertainty remains a risk.
Non-woven Adhesives Market Segmentation
1. Type
1.1. Styrenic Block Copolymers
1.2. Ethylene Vinyl Acetate
1.3. Polyolefin
1.4. Others
2. Application
2.1. Baby Diapers
2.2. Feminine Hygiene
2.3. Adult Incontinence
2.4. Medical Products
2.5. Others
Non-woven Adhesives Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Non-woven Adhesives Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.9% from 2020-2034
Segmentation
By Type
Styrenic Block Copolymers
Ethylene Vinyl Acetate
Polyolefin
Others
By Application
Baby Diapers
Feminine Hygiene
Adult Incontinence
Medical Products
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Styrenic Block Copolymers
5.1.2. Ethylene Vinyl Acetate
5.1.3. Polyolefin
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Baby Diapers
5.2.2. Feminine Hygiene
5.2.3. Adult Incontinence
5.2.4. Medical Products
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Styrenic Block Copolymers
6.1.2. Ethylene Vinyl Acetate
6.1.3. Polyolefin
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Baby Diapers
6.2.2. Feminine Hygiene
6.2.3. Adult Incontinence
6.2.4. Medical Products
6.2.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Styrenic Block Copolymers
7.1.2. Ethylene Vinyl Acetate
7.1.3. Polyolefin
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Baby Diapers
7.2.2. Feminine Hygiene
7.2.3. Adult Incontinence
7.2.4. Medical Products
7.2.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Styrenic Block Copolymers
8.1.2. Ethylene Vinyl Acetate
8.1.3. Polyolefin
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Baby Diapers
8.2.2. Feminine Hygiene
8.2.3. Adult Incontinence
8.2.4. Medical Products
8.2.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Styrenic Block Copolymers
9.1.2. Ethylene Vinyl Acetate
9.1.3. Polyolefin
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Baby Diapers
9.2.2. Feminine Hygiene
9.2.3. Adult Incontinence
9.2.4. Medical Products
9.2.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Styrenic Block Copolymers
10.1.2. Ethylene Vinyl Acetate
10.1.3. Polyolefin
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Baby Diapers
10.2.2. Feminine Hygiene
10.2.3. Adult Incontinence
10.2.4. Medical Products
10.2.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Adtek Malaysia SDN BHD
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. 3M Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. The Dow Chemical Company
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Evonik Industries AG
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Henkel AG & Co. KGaA
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. H.B. Fuller Company
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Moresco Corporation
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Beardow Adams Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Kraton Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Bostik SA (ARKEMA)
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Non-woven Adhesives Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Non-woven Adhesives Market Revenue (million), by Type 2026 & 2034
Figure 3: North America Non-woven Adhesives Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Non-woven Adhesives Market Revenue (million), by Application 2026 & 2034
Figure 5: North America Non-woven Adhesives Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Non-woven Adhesives Market Revenue (million), by Country 2026 & 2034
Figure 7: North America Non-woven Adhesives Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Non-woven Adhesives Market Revenue (million), by Type 2026 & 2034
Figure 9: South America Non-woven Adhesives Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Non-woven Adhesives Market Revenue (million), by Application 2026 & 2034
Figure 11: South America Non-woven Adhesives Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Non-woven Adhesives Market Revenue (million), by Country 2026 & 2034
Figure 13: South America Non-woven Adhesives Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Non-woven Adhesives Market Revenue (million), by Type 2026 & 2034
Figure 15: Europe Non-woven Adhesives Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Non-woven Adhesives Market Revenue (million), by Application 2026 & 2034
Figure 17: Europe Non-woven Adhesives Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Non-woven Adhesives Market Revenue (million), by Country 2026 & 2034
Figure 19: Europe Non-woven Adhesives Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Non-woven Adhesives Market Revenue (million), by Type 2026 & 2034
Figure 21: Middle East & Africa Non-woven Adhesives Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Non-woven Adhesives Market Revenue (million), by Application 2026 & 2034
Figure 23: Middle East & Africa Non-woven Adhesives Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Non-woven Adhesives Market Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Non-woven Adhesives Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Non-woven Adhesives Market Revenue (million), by Type 2026 & 2034
Figure 27: Asia Pacific Non-woven Adhesives Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Non-woven Adhesives Market Revenue (million), by Application 2026 & 2034
Figure 29: Asia Pacific Non-woven Adhesives Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Non-woven Adhesives Market Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Non-woven Adhesives Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Non-woven Adhesives Market Revenue million Forecast, by Type 2020 & 2034
Table 2: Non-woven Adhesives Market Revenue million Forecast, by Application 2020 & 2034
Table 3: Non-woven Adhesives Market Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Non-woven Adhesives Market Revenue million Forecast, by Type 2020 & 2034
Table 5: North America Non-woven Adhesives Market Revenue million Forecast, by Application 2020 & 2034
Table 6: North America Non-woven Adhesives Market Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Non-woven Adhesives Market Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Non-woven Adhesives Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% of research effort is dedicated to primary interviews and surveys, ensuring data authenticity and granularity.
We conduct in-depth interviews with procurement directors, R&D managers, and production heads at adhesive formulators, non-woven fabric manufacturers, and hygiene product OEMs.
Specific company types targeted include styrenic block copolymer producers, hot melt adhesive formulators, non-woven fabric manufacturers, baby diaper OEMs, and medical adhesive specialists.
Primary research validates demand-side trends, pricing structures, adoption rates, and supply chain dynamics across key regions.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Adhesive Procurement Manager
30%
Product Development Director
25%
Manufacturing Operations Head
25%
Regulatory Compliance Officer
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Adhesive Raw Material Suppliers
20%
Adhesive Formulators
30%
Non-woven Fabric Manufacturers
25%
Hygiene Product OEMs
15%
Medical Device Manufacturers
10%
Secondary Research & Industry Benchmarking
20-30% of research is derived from secondary sources, including financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook for benchmarking and competitive intelligence.
We reference .gov and .org sources, such as the U.S. Food and Drug Administration (FDA), European Chemicals Agency (ECHA), and the Adhesive and Sealant Council (ASC).
Industry associations like EDANA (baby diapers), INDA (non-wovens), and ASTM International provide testing standards and market data.
Demand Modeling & Market Estimation
We use both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up calculation uses quantitative metrics: global baby diaper production (billion units), adhesive content per diaper (grams), average adhesive price per ton, non-woven fabric production volume, and medical adhesive consumption per procedure.
Top-down analysis leverages regional hygiene product sales and adhesive market share by type, cross-referenced with trade data.
The guaranteed estimated data accuracy level is 85-90%.
Data Accuracy & Quality Check
Every report is updated to the date of purchase, ensuring the latest market developments are incorporated.
We perform multi-level triangulation across primary and secondary data to reconcile discrepancies and validate findings.
Quality checks include cross-verification with trade data from UN Comtrade and company annual reports.
Estimates are validated by industry experts and our internal quality assurance team before publication.
Frequently Asked Questions
1. What recent developments have occurred in the Non-woven Adhesives Market?
Henkel launched a bio-based adhesive for hygiene applications in 2024, reducing carbon footprint by 30%. H.B. Fuller acquired a specialty adhesive producer in Asia to expand capacity by 15,000 metric tons. These moves target growth in the baby diapers segment and align with sustainability goals.
2. How do export-import dynamics affect the Non-woven Adhesives Market?
Asia-Pacific is a net exporter, with China accounting for 35% of global adhesive exports. Europe imports significant volumes from Southeast Asia due to cost advantages, while North America relies on intra-regional trade under USMCA. Tariffs on raw materials can increase costs by 10-15%, disrupting trade flows.
3. What are the major challenges facing the Non-woven Adhesives Market?
Volatility in raw material prices, especially for styrenic block copolymers, poses a significant restraint, with price swings of 20-30% annually. Stringent environmental regulations in Europe, such as REACH, increase compliance costs. Supply chain disruptions from geopolitical tensions can delay production and raise logistics expenses.
4. What is the current size and projected growth rate of the Non-woven Adhesives Market?
The market was valued at $6,569.48 million in 2025 and is projected to reach $13,963 million by 2033, growing at a CAGR of 9.9%. This growth is driven by increasing demand for hygiene products and medical applications. Asia-Pacific is the largest regional market, holding a 40% share.
5. What are the barriers to entry in the Non-woven Adhesives Market?
High capital requirements for R&D and manufacturing create significant barriers. Established players like Henkel and 3M benefit from strong patents, brand loyalty, and long-term contracts with diaper manufacturers. Regulatory approvals for medical-grade adhesives add complexity and cost, deterring new entrants.
6. Which segments dominate the Non-woven Adhesives Market?
Styrenic block copolymers hold the largest share at 45% due to their elasticity and adhesion properties. Baby diapers are the leading application, accounting for 50% of consumption. Medical products are the fastest-growing application at a CAGR of 11.2%, driven by aging populations.