Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Air Separation Unit Market Trends and Growth to 2034
Air Separation Unit Market
Air Separation Unit Market Trends and Growth to 2034
Air Separation Unit Market by Process (Cryogenic Distillation, Non-Cryogenic Distillation), by Gas Type (Oxygen, Nitrogen, Argon, Others), by End-Use Industry (Iron and Steel, Petrochemical, Medical, Chemical Manufacturing, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 5, 2026|Base Year : 2025|Pages : 350
Key Insights & Executive Summary: Air Separation Unit Market
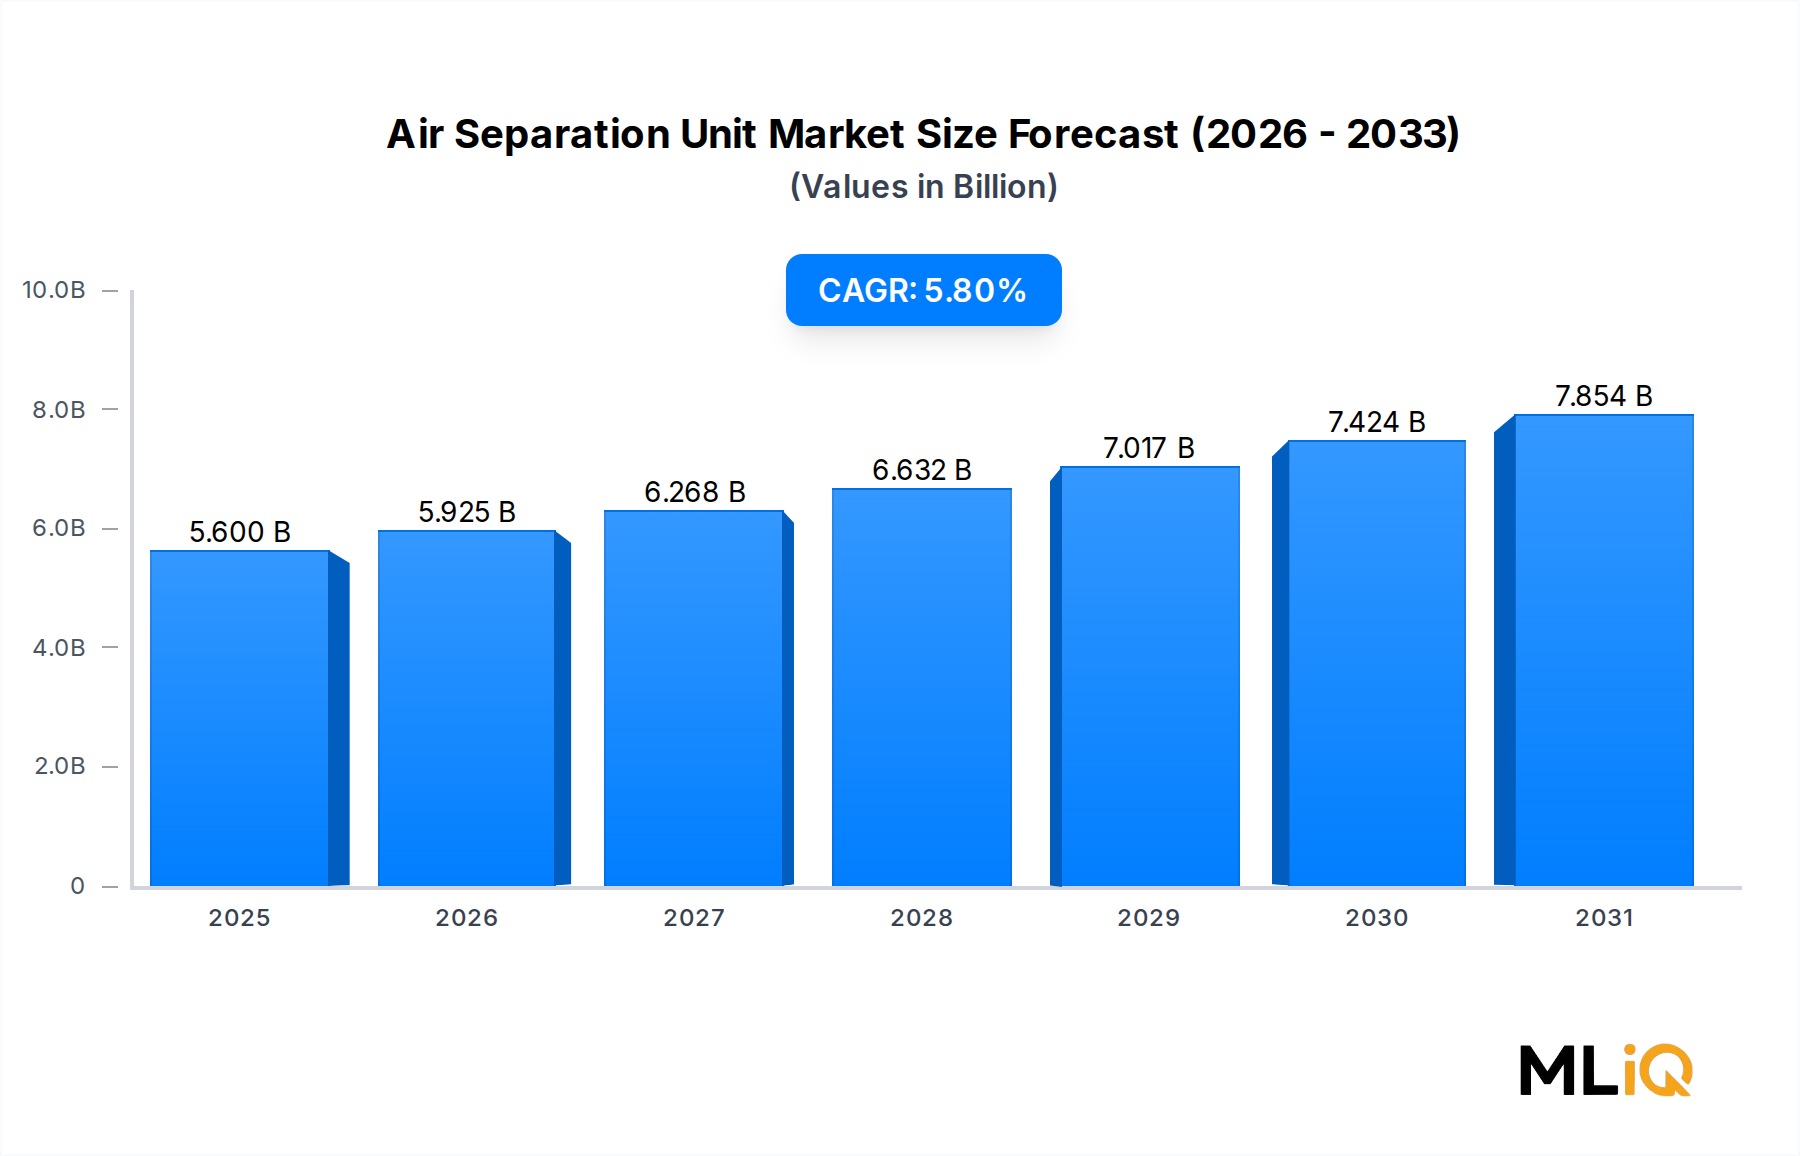
The Air Separation Unit Market will expand from USD 5.6 billion in 2024 to approximately USD 9.8 billion by 2034. Growth is uneven across project types. Integrated gas producers control an increasing share of new orders for ultra-large trains above 250,000 Nm3/h, while smaller industrial users depend on modular standardized vessels. The Industrial Gases Market acts as the demand engine for this expansion because the largest industrial gas suppliers are also the main buyers and operators of ASU hardware. Commercial terms for oxygen, nitrogen, and argon continue to move from simple commodity sales toward bundled packages of gas, equipment, compressor maintenance, and digital supervision.
Air Separation Unit Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
5.600 B
2025
5.925 B
2026
6.268 B
2027
6.632 B
2028
7.017 B
2029
7.424 B
2030
7.854 B
2031
Capital spending in the Air Separation Unit Market now follows three decision criteria. The first is production scale and purity. Many new projects need oxygen purity above 99.5%, which cannot be produced reliably by adsorption or membrane alternatives. The second is energy delivery cost: electricity often accounts for one-third of a plant’s lifetime cost and heavily influences site selection. The third is contractual duration. Long-term offtake contracts of 15-20 years let plant owners use debt financing without destroying margin flexibility.
The Oxygen Generation Plant Market and the Nitrogen Generation System Market are frequently confused with complete ASU demand. In reality, both are subsystem-level markets. Oxygen generation plants include PSA and cryogenic equipment used for medical, water, and industrial duties. Nitrogen generation systems include PSA, membrane, and cryogenic equipment for blanketing, electronic annealing, and LNG service. Their technical buyers differ, but their equipment spending is influenced by air separation unit economics. This forecast includes complete ASU solutions and associated services, while subsystem-only units receive separate competitive evaluation.
Segment Deep-Dive: Cryogenic Distillation Dominance in Air Separation Unit Market
Cryogenic distillation is the largest processing route in the Air Separation Unit Market because it is the only single-train technology that can recover high-purity oxygen, nitrogen, and argon simultaneously at very large throughput. The Cryogenic Distillation Market accounts for roughly 78% of global ASU revenue in the base year. It is also the asset class that industrial gas providers monetize for 20- to 30-year gas contracts. Capacity scale lowers specific capital and operating costs, but oxygen safety requirements and rotating machinery complexity create a high cost of entry for new suppliers.
Scale Economies and Plant Sizing
A single cryogenic train producing 100,000 Nm3/h of oxygen can serve a large integrated steel complex. Because of this scale effect, the largest liquid ASUs are usually sanctioned only when the developer can secure a 15-year anchor supply agreement for oxygen plus a merchant nitrogen stream. In contrast, the Non-Cryogenic Air Separation Unit Market depends on vacuum pressure-swing adsorption and can deliver oxygen capacities below 10,000 Nm3/h at 90-93% purity. Those units are simpler to install and faster to redeploy, yet they do not reach the 99.5% or higher purity required in oxy-fuel combustion, chemical gasification, or electronic specialty gas networks. Non-cryogenic capacity is therefore a complement for small users, not a substitute for installed cryogenic production.
Gas Mix and Argon Recovery
Within cryogenic plants, oxygen remains the revenue anchor, followed by high-purity nitrogen. Argon is produced almost entirely inside cryogenic cold boxes because argon recovery requires a separate distillation column operating between oxygen and nitrogen separation stages. The Argon Recovery Unit Market is growing faster than standalone oxygen-only trains because stainless steel fabrication, solar polysilicon, and additive manufacturing require cost-effective argon supply at modest consumer volumes. Large oxygen train owners add argon recovery columns when the extra column, compressor, and storage equipment can be integrated without disturbing the main column hydraulics. Offtake contracts for liquid argon also stabilize plant utilization and enable merchants to diversify outside steel-cycle demand.
Margin Dynamics
Cryogenic technology still faces margin pressure from rising energy tariffs, compressor delivery delays, and more stringent ASME recertification requirements. Operators are defending returns by adding variable-speed drives, digital twin controls, and remote operation centers that reduce specific energy consumption by 5-8% on older trains. Although capital discipline is improving, average plant lifetime is projected to stretch from 30 to almost 40 years as owners postpone greenfield replacement, making component integrity management more important than in the previous decade.
Primary Market Drivers & Growth Restraints in Air Separation Unit Market
Growth Drivers
The most measurable driver is steel manufacturing. The Steel Manufacturing Gas Market is rising because basic oxygen furnace bottom stirring, electric arc furnace oxygen-lance systems, and new DRI plants configured for hydrogen-rich reduction all consume larger oxygen volumes. Integrating oxygen production with a 5-million-tonne-per-year steel site requires multiple ASU trains, and this repeats in India, Southeast Asia, and the Gulf states. A second driver is petrochemical throughput. The Petrochemical Gas Supply Market is expanding with ethylene and methanol projects in China and the Middle East; each plant requires nitrogen for purging, instrument air, flare gas cleanup, and product blanketing. Medical oxygen regulations form the third catalyst, especially in economies that have adopted emergency bulk liquid oxygen standards for intensive care hospitals.
Restraints
ASU plants are major electricity consumers. Specific power for a large cryogenic air separation unit usually ranges from 0.35 to 0.45 kWh/Nm3 of gaseous oxygen, so electric rate volatility directly changes project payback. Carbon pricing above USD 100/tCO2 in Europe makes older, inefficient plants less competitive, while grid connection approvals add 12-24 months to final investment decisions. Supply chain constraints for aluminum brazed plate-fin heat exchangers and axial compressors have also increased lead times by roughly 20-30% relative to pre-2020 levels. Transportation economics act as a secondary restraint because liquid oxygen and nitrogen shipping costs limit merchant distance, and pipeline revenue viability depends on utilization above 80%.
Competitive Ecosystem & Key Vendor Profiles: Air Separation Unit Market
Competition in the Air Separation Unit Market includes both industrial gas producers and specialist equipment builders. The order backlog for cryogenic columns, cold boxes, compressors, and pumps remains concentrated in fewer than ten international engineering groups, while small rebuild and service contractors occupy regional aftermarket niches. The ASU Aftermarket Services Market is expanding as the installed fleet ages and digital condition monitoring becomes a mandatory service layer.
Linde PLC: Global leader in air separation engineering and integrated gas contracts, with strong positions in steel oxygen and blue ammonia projects.
Air Products and Chemicals, Inc.: Major supplier of on-site oxygen and nitrogen trains, particularly active in U.S. Gulf Coast hydrogen and clean-energy capex.
TAIYO NIPPON SANSO CORPORATION: Strong high-purity nitrogen franchise serving semiconductor fabs and electronics gas supply chains in Asia and Europe.
Hangzhou Nuzhuo Technology Group Co., Ltd.: Chinese cryogenic equipment specialist with broad plate-fin heat exchanger and low-temperature column fabrication capacity.
Nikkiso: Global supplier of cryogenic pumps, expanders, and cold-box rotating equipment for LNG and industrial gas applications.
INOX-Air Products Inc.: Leading Indian merchant and on-site industrial gas company, supported by Air Products technical capability and an expanding medical oxygen network.
Bhuruka Gases Limited: Regional Indian merchant gas provider operating cryogenic storage, cylinder filling, and medical gas distribution assets.
Brise Chemicals: Industrial chemical and gas supplier serving commercial gas users with oxygen, nitrogen, and dissolved gas products in select Asian markets.
ING. L. & A. BOSCHI ITALY: Specialist in valves, gas control systems, and low-temperature safety equipment used in cryogenic process lines.
Comi Polaris Systems: Designer and integrator of gas vaporization, pressure reduction, and purge gas systems for industrial and medical gas facilities.
Maddox Industrial Group: U.S. construction and maintenance contractor focused on air separation plant installation, turnarounds, and piping integrity inspection.
Strategic Milestones & Recent Developments in Air Separation Unit Market
Sample milestones tracked during the report window are listed chronologically.
March 2024: Linde PLC signed a long-term on-site supply agreement for a planned clean ammonia project in the United States, with two cryogenic air separation trains included in the gas supply complex.
June 2024: Air Products and Chemicals, Inc. expanded its Texas Gulf Coast merchant oxygen and nitrogen network by starting a new packaged gas production train and increased storage capacity.
September 2024: TAIYO NIPPON SANSO CORPORATION announced completion of an upgraded high-purity nitrogen generator supporting semiconductor device production in Japan.
January 2025: Nikkiso secured new cryogenic pump supply contracts for LNG application, reinforcing ASU-side component demand from adjacent energy projects.
March 2025: INOX-Air Products Inc. increased bulk liquid medical oxygen storage capacity in western India to improve hospital supply resilience during seasonal demand peaks.
Regional Market Analysis & Growth Corridors for Air Separation Unit Market
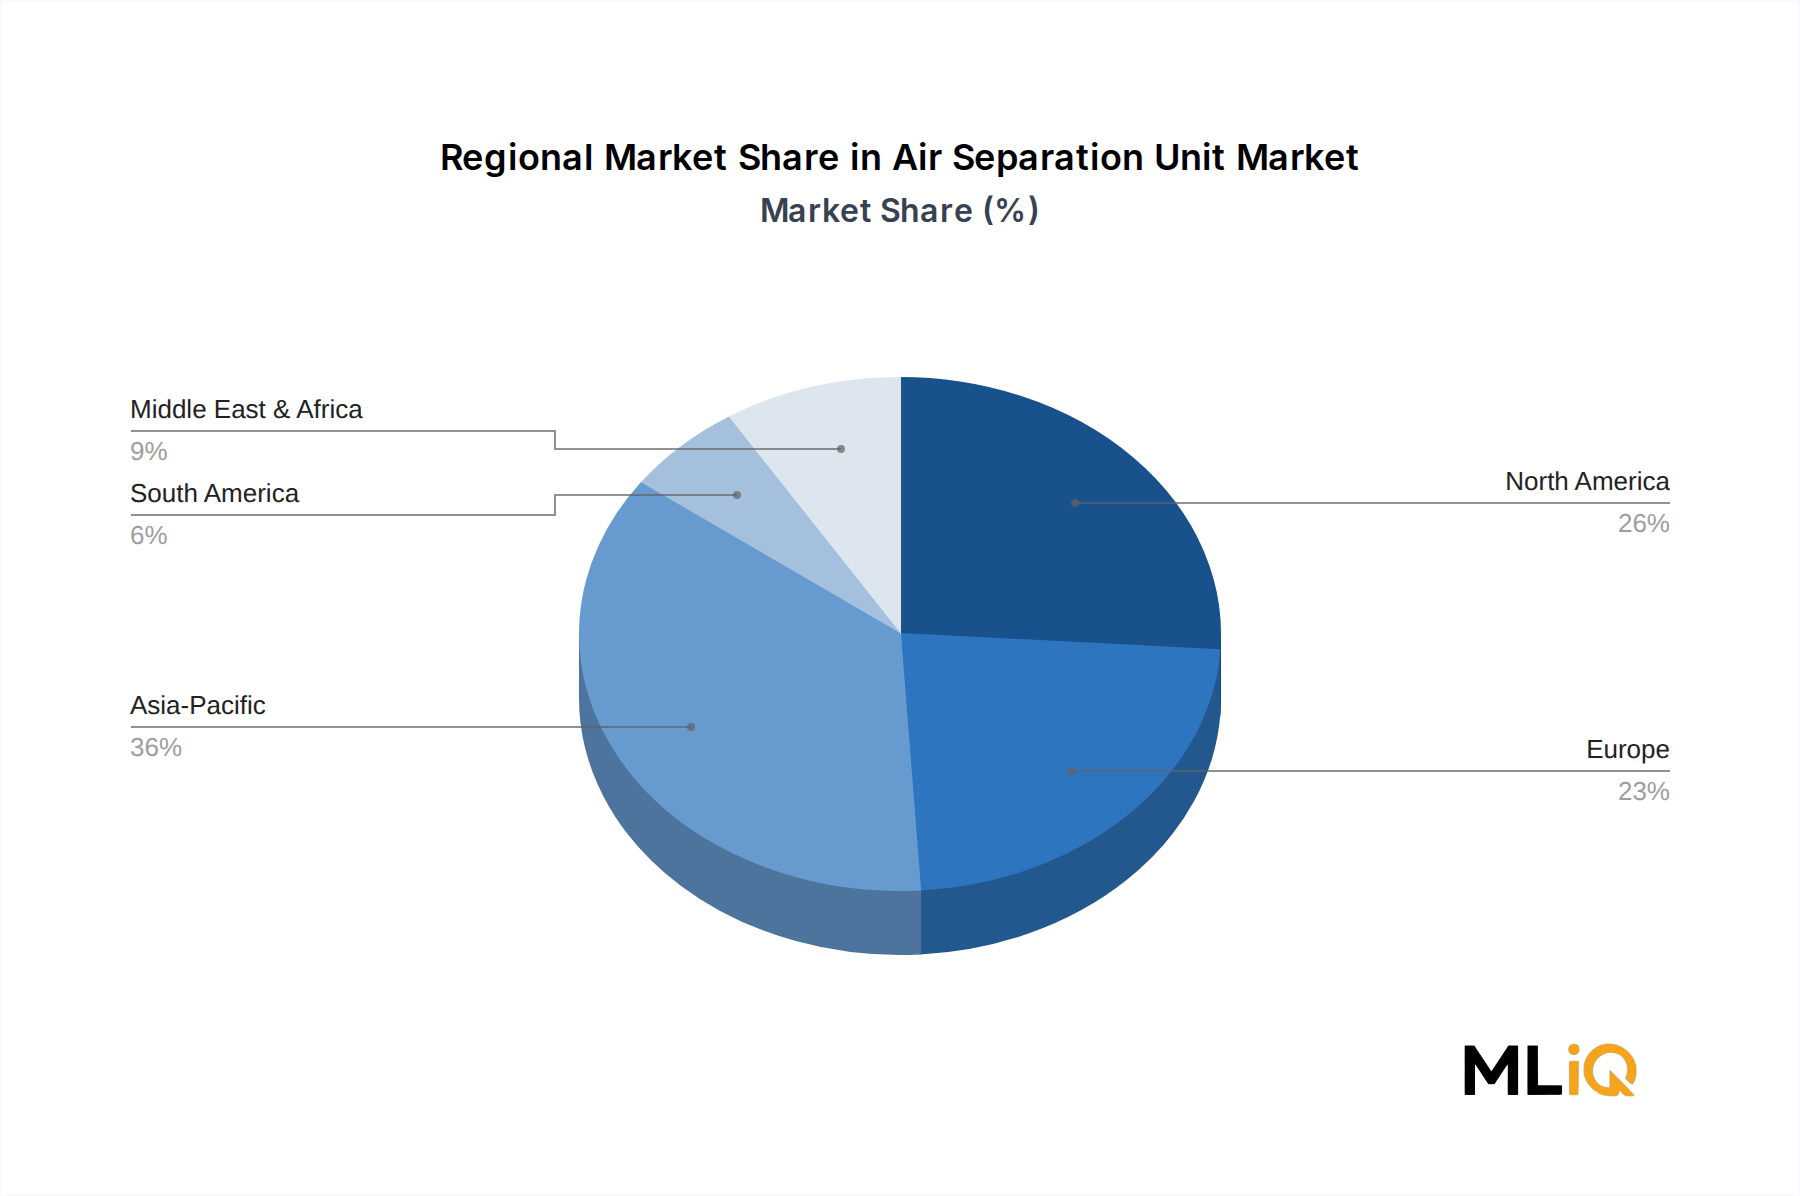
Asia Pacific remains the largest regional ASU market with 36% of global value in 2024. China’s installed base is mature, although replacement projects continue as steel producers modernize old oxygen plants. India is the largest greenfield engine, with new steel mills and merchant gas suppliers placing orders for oxygen, nitrogen, and argon units. Japan and South Korea generate high-value nitrogen demand from electronics and semiconductor clients, giving regional revenue a premium mix. The Asia Pacific region is growing at an estimated CAGR of 6.0%, driven by petrochemical expansions and the Steel Manufacturing Gas Market in emerging economies.
North America holds 26% of global share. U.S. Gulf Coast petrochemical and blue hydrogen investments are lifting oxygen requirements for gasification and ammonia synthesis. Existing plants are also adding digital controls and debottlenecking to increase output without new foundations. North America is the most mature in terms of safety regulation, with OSHA and ASME oversight slowing project pace but raising quality barriers. Europe holds 23% of global value. Growth is muted, around 4.6% CAGR, because steel plant closures and carbon costs limit new capacity. European replacement demand focuses on energy efficiency and compact footprints, while combined heat and power integration is becoming a standard requirement.
The Middle East & Africa region accounts for about 9% of global value but has one of the fastest CAGRs, estimated at 6.4%, due to blue and green ammonia projects in the GCC and increased mineral processing activity in North Africa and South Africa. South America is the smallest region at 6% of value, with Brazil controlling most demand through iron ore pelletizing and petrochemical complexes. The Petrochemical Gas Supply Market there is smaller than in Asia but is expanding with new nitrogen facilities for gas-field startup and refinery turnaround support.
Technology Innovation & R&D Trajectory in Air Separation Unit Market
Technology programs in the Air Separation Unit Market are shifting away from pure cold-box scale advancement. The first disruptive area is digital twin optimization. Operators now combine column pressure profiling, compressor surge maps, and weather forecasts to reduce specific energy by 5-10% on existing assets. This weakens the traditional cost advantage of new massive plants because older units can be operated closer to physical limits.
The second focus is ceramic oxygen transport membrane development. Ceramic membranes are at pilot scale for oxy-fuel combustion and reforming applications where high-purity oxygen is needed without a full cryogenic plant. The largest barrier is module sealing and degradation under repeated thermal cycling. Commercial deployment is still uncertain, but patent analysis shows concentrated filing activity in Japan, Germany, and the United States. A mature membrane system would compress the low-to-mid oxygen segment of the Non-Cryogenic Air Separation Unit Market, although it is unlikely to challenge 300-tonne-per-day cryogenic train economics.
The third innovation area is flexible operation for power-grid arbitrage. Renewable-heavy grids create volatile power prices, and ASU owners are designing rapid turndown and liquid storage buffers to produce oxygen when electricity is cheap and sell liquid product when prices recover. This changes the system of record for plant design from baseload oxygen supply to demand-response optimization, and it is expected to be a defining technical requirement for new trains ordered after 2027.
Regulatory & Policy Landscape: Air Separation Unit Market
In North America, the most relevant frameworks are ASME B31.3 process piping, ASME Boiler and Pressure Vessel Code Section VIII, and OSHA 29 CFR 1910 for compressed gas and oxygen safety. Medical oxygen produced in ASUs is subject to FDA 21 CFR equipment and pharmaceutical rules. Recent FDA inspection trends emphasize oxygen purity testing and cylinder traceability, which raises compliance costs for smaller producers.
In Europe, pressure equipment is governed by the Pressure Equipment Directive 2014/68/EU, and cryogenic vessels must meet harmonized standards for low-temperature metallic materials. ATEX directives affect electrical and control systems installed where oxygen enrichment could create ignition risk. The European Industrial Gases Association publishes safety and product quality guidance that conditions supply into large chemical and steel customers.
In Asia Pacific, China enforces TSG 21 and GB/T 150 pressure vessel rules, while Japan applies High Pressure Gas Safety Act requirements to oxygen and nitrogen facilities. India is moving toward more rigorous approval gateways for installed liquid oxygen storage and steel-plant gas systems. Carbon border adjustment mechanisms in Europe and the U.S. Section 45V hydrogen rules are becoming de facto technology filters because their emission accounting determines whether an ASU is eligible for low-carbon investment tax credits. Compliance impact now reaches procurement decisions before ground breaking, not after commissioning.
Air Separation Unit Market Segmentation
1. Process
1.1. Cryogenic Distillation
1.2. Non-Cryogenic Distillation
2. Gas Type
2.1. Oxygen
2.2. Nitrogen
2.3. Argon
2.4. Others
3. End-Use Industry
3.1. Iron and Steel
3.2. Petrochemical
3.3. Medical
3.4. Chemical Manufacturing
3.5. Others
Air Separation Unit Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Air Separation Unit Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.8% from 2020-2034
Segmentation
By Process
Cryogenic Distillation
Non-Cryogenic Distillation
By Gas Type
Oxygen
Nitrogen
Argon
Others
By End-Use Industry
Iron and Steel
Petrochemical
Medical
Chemical Manufacturing
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Process
5.1.1. Cryogenic Distillation
5.1.2. Non-Cryogenic Distillation
5.2. Market Analysis, Insights and Forecast - by Gas Type
5.2.1. Oxygen
5.2.2. Nitrogen
5.2.3. Argon
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by End-Use Industry
5.3.1. Iron and Steel
5.3.2. Petrochemical
5.3.3. Medical
5.3.4. Chemical Manufacturing
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Process
6.1.1. Cryogenic Distillation
6.1.2. Non-Cryogenic Distillation
6.2. Market Analysis, Insights and Forecast - by Gas Type
6.2.1. Oxygen
6.2.2. Nitrogen
6.2.3. Argon
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by End-Use Industry
6.3.1. Iron and Steel
6.3.2. Petrochemical
6.3.3. Medical
6.3.4. Chemical Manufacturing
6.3.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Process
7.1.1. Cryogenic Distillation
7.1.2. Non-Cryogenic Distillation
7.2. Market Analysis, Insights and Forecast - by Gas Type
7.2.1. Oxygen
7.2.2. Nitrogen
7.2.3. Argon
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by End-Use Industry
7.3.1. Iron and Steel
7.3.2. Petrochemical
7.3.3. Medical
7.3.4. Chemical Manufacturing
7.3.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Process
8.1.1. Cryogenic Distillation
8.1.2. Non-Cryogenic Distillation
8.2. Market Analysis, Insights and Forecast - by Gas Type
8.2.1. Oxygen
8.2.2. Nitrogen
8.2.3. Argon
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by End-Use Industry
8.3.1. Iron and Steel
8.3.2. Petrochemical
8.3.3. Medical
8.3.4. Chemical Manufacturing
8.3.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Process
9.1.1. Cryogenic Distillation
9.1.2. Non-Cryogenic Distillation
9.2. Market Analysis, Insights and Forecast - by Gas Type
9.2.1. Oxygen
9.2.2. Nitrogen
9.2.3. Argon
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by End-Use Industry
9.3.1. Iron and Steel
9.3.2. Petrochemical
9.3.3. Medical
9.3.4. Chemical Manufacturing
9.3.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Process
10.1.1. Cryogenic Distillation
10.1.2. Non-Cryogenic Distillation
10.2. Market Analysis, Insights and Forecast - by Gas Type
10.2.1. Oxygen
10.2.2. Nitrogen
10.2.3. Argon
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by End-Use Industry
10.3.1. Iron and Steel
10.3.2. Petrochemical
10.3.3. Medical
10.3.4. Chemical Manufacturing
10.3.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Hangzhou Nuzhuo Technology Group Co.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Ltd.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Brise Chemicals
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. INOX-Air Products Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ING. L. & A. BOSCHI ITALY
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Bhuruka Gases Limited
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Linde PLC
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Nikkiso
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. TAIYO NIPPON SANSO CORPORATION
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Comi Polaris Systems
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Air Products and Chemicals
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Inc.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Maddox Industrial Group
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Air Separation Unit Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Air Separation Unit Market Revenue (billion), by Process 2026 & 2034
Figure 3: North America Air Separation Unit Market Revenue Share (%), by Process 2026 & 2034
Figure 4: North America Air Separation Unit Market Revenue (billion), by Gas Type 2026 & 2034
Figure 5: North America Air Separation Unit Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 6: North America Air Separation Unit Market Revenue (billion), by End-Use Industry 2026 & 2034
Figure 7: North America Air Separation Unit Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 8: North America Air Separation Unit Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Air Separation Unit Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Air Separation Unit Market Revenue (billion), by Process 2026 & 2034
Figure 11: South America Air Separation Unit Market Revenue Share (%), by Process 2026 & 2034
Figure 12: South America Air Separation Unit Market Revenue (billion), by Gas Type 2026 & 2034
Figure 13: South America Air Separation Unit Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 14: South America Air Separation Unit Market Revenue (billion), by End-Use Industry 2026 & 2034
Figure 15: South America Air Separation Unit Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 16: South America Air Separation Unit Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Air Separation Unit Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Air Separation Unit Market Revenue (billion), by Process 2026 & 2034
Figure 19: Europe Air Separation Unit Market Revenue Share (%), by Process 2026 & 2034
Figure 20: Europe Air Separation Unit Market Revenue (billion), by Gas Type 2026 & 2034
Figure 21: Europe Air Separation Unit Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 22: Europe Air Separation Unit Market Revenue (billion), by End-Use Industry 2026 & 2034
Figure 23: Europe Air Separation Unit Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 24: Europe Air Separation Unit Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Air Separation Unit Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Air Separation Unit Market Revenue (billion), by Process 2026 & 2034
Figure 27: Middle East & Africa Air Separation Unit Market Revenue Share (%), by Process 2026 & 2034
Figure 28: Middle East & Africa Air Separation Unit Market Revenue (billion), by Gas Type 2026 & 2034
Figure 29: Middle East & Africa Air Separation Unit Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 30: Middle East & Africa Air Separation Unit Market Revenue (billion), by End-Use Industry 2026 & 2034
Figure 31: Middle East & Africa Air Separation Unit Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 32: Middle East & Africa Air Separation Unit Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Air Separation Unit Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Air Separation Unit Market Revenue (billion), by Process 2026 & 2034
Figure 35: Asia Pacific Air Separation Unit Market Revenue Share (%), by Process 2026 & 2034
Figure 36: Asia Pacific Air Separation Unit Market Revenue (billion), by Gas Type 2026 & 2034
Figure 37: Asia Pacific Air Separation Unit Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 38: Asia Pacific Air Separation Unit Market Revenue (billion), by End-Use Industry 2026 & 2034
Figure 39: Asia Pacific Air Separation Unit Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 40: Asia Pacific Air Separation Unit Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Air Separation Unit Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 2: Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 3: Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 4: Air Separation Unit Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 6: North America Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 7: North America Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 8: North America Air Separation Unit Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 13: South America Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 14: South America Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 15: South America Air Separation Unit Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 20: Europe Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 21: Europe Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 22: Europe Air Separation Unit Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 33: Middle East & Africa Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 34: Middle East & Africa Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 35: Middle East & Africa Air Separation Unit Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Air Separation Unit Market Revenue billion Forecast, by Process 2020 & 2034
Table 43: Asia Pacific Air Separation Unit Market Revenue billion Forecast, by Gas Type 2020 & 2034
Table 44: Asia Pacific Air Separation Unit Market Revenue billion Forecast, by End-Use Industry 2020 & 2034
Table 45: Asia Pacific Air Separation Unit Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Air Separation Unit Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
This report applies a 70-80% primary / 20-30% secondary research split. In practice, approximately 75% of final data inputs came from primary interviews and field questionnaires, with 25% reserved for validation against public financial and technical disclosures.
Interview targets included Air Separation Plant Operations Directors, Industrial Gas Engineering and Energy Procurement Managers, Cryogenic Process Safety Engineers, and Plant Turnaround Planners who manage cold-box maintenance and compressor overhauls.
Company-type quotas were set for ASU licensors and EPC contractors, air separation equipment manufacturers, cryogenic cold-box and compressor suppliers, industrial gas merchants, and industrial gas safety service providers.
Interviews covered project economics, capacity expansion, supply chain lead times, technology roadmaps, and aftermarket contract renewal patterns. No anonymous participant-level data is exposed in this report.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Air Separation Plant Operations Directors
35%
Plant Engineering Heads
25%
Industrial Gas Procurement Managers
20%
Process Technology Managers
12%
Environmental and Safety Compliance Officers
8%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Industrial gas producers
35%
ASU equipment manufacturers
25%
Engineering, procurement, and construction firms
20%
Technology licensors
10%
Aftermarket service providers
10%
Secondary Research & Industry Benchmarking
Corporate filings, annual reports, project permits, and trade press were screened through Bloomberg, Factiva, Hoovers, and PitchBook databases.
Industry associations and public-interest sources included the European Industrial Gases Association (EIGA), the Compressed Gas Association (CGA), and the U.S. Energy Information Administration (EIA).
Equipment pricing was triangulated using project contract announcements, engineering cost curves, and pressure vessel fabrication indexes.
Market research websites were not used as foundational inputs because they lack auditable methodology.
Demand Modeling & Market Estimation
The top-down model started from reported capital expenditure in air separation projects and distributed revenue across process, gas type, end-use industry, and region.
The bottom-up model used installed cryogenic train capacity in Nm3/h, average capacity utilization, specific power consumption, and replacement cycles for cold boxes and main compressors.
Additional quantitative metrics included regional oxygen demand per tonne of steel produced, nitrogen purity requirements by electronics application, argon consumption per tonne of stainless steel, and average turnaround frequency for large air separation units.
Top-down and bottom-up results were generated simultaneously and reconciled through multi-level data triangulation, requiring agreement between three modeling passes before publication.
Data Accuracy & Quality Check
This report is checked to a guaranteed estimated data accuracy level of 85-90%.
Values that deviated by more than 5% between top-down and bottom-up methods triggered additional primary interviews or deeper secondary checks.
Every report is updated to the date of purchase. Model revisions are not rolled forward automatically after the customer order date, ensuring the buyer receives a version that reflects all information available at the time of purchase.
Frequently Asked Questions
1. What barriers exist for new entrants in the air separation unit industry?
High capital intensity is the core barrier. A large cryogenic train can require USD 300-500 million, and engineering design, commissioning, and safety records cannot be compressed into short schedules. Linde PLC, Air Products and Chemicals Inc., and TAIYO NIPPON SANSO CORPORATION also reuse proprietary design knowledge, making imitation costly and slow.
2. Which emerging technologies could disrupt the Air Separation Unit Market?
Modular VPSA and membrane oxygen systems are eroding lower-purity demand, while ceramic oxygen transport membranes are being tested for oxy-fuel and chemical-looping applications. These substitutes are disruptive only below 95% oxygen purity or below roughly 10,000 Nm3/h of capacity. Cryogenic distillation remains the only large-scale route when high-purity argon is required.
3. Who are the leading manufacturers and market share leaders for air separation units?
Linde PLC, Air Products and Chemicals Inc., and TAIYO NIPPON SANSO CORPORATION are the largest integrated industrial gas players. The top three companies control close to 45% of global installed cryogenic ASU capacity, while specialist equipment engineers such as Hangzhou Nuzhuo and Nikkiso supply roughly 25% of new trains.
4. Which market segment is expected to remain the largest source of revenue?
The Cryogenic Distillation segment will remain the largest source of revenue, accounting for approximately 78% of equipment sales in this market in 2024. Oxygen is the dominant gas type because steelmaking, chemical production, and oxy-fuel processes require high-purity oxygen at very large flow rates. Non-cryogenic units serve smaller sites with lower purity requirements.
5. Why are raw material and sourcing decisions important for ASU project economics?
Cold-box fabrication depends on aluminum alloy brazed heat exchangers, stainless steel, and nickel-based materials for oxygen-enriched service. Lead times for these components rose by 20-30% after 2021, pushing Final Investment Decision dates into later quarters. Access to low-cost, dispatchable electricity is another raw input because power can represent one-third of lifetime operating expense.
6. What end-use industries drive downstream demand for air separation products?
Iron and steel is the largest end user, representing about 30% of oxygen demand in the Air Separation Unit Market. Petrochemical, medical, and electronics sectors follow, with medical liquid oxygen governed by hospital bulk storage and regulatory verification requirements. INOX Air Products and Air Products have used long-term medical oxygen agreements to support reliable hospital supply chains.