Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Why Thermal Sprayed Aluminum Coatings Market CAGR Is 4.7%
Thermal Sprayed Aluminum Coatings Market
Why Thermal Sprayed Aluminum Coatings Market CAGR Is 4.7%
Thermal Sprayed Aluminum Coatings Market by Product Type (Flame Spraying, Oxyethylene Flame Powder Coating Spraying, Arc Spraying), by Application (Anti-Corrosion, Decorative Coatings, Wear Resistant, Thermal Barrier, Others), by End-use Industry (Oil Gas, Chemical Petrochemical, Marine, Automotive Aerospace, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 0
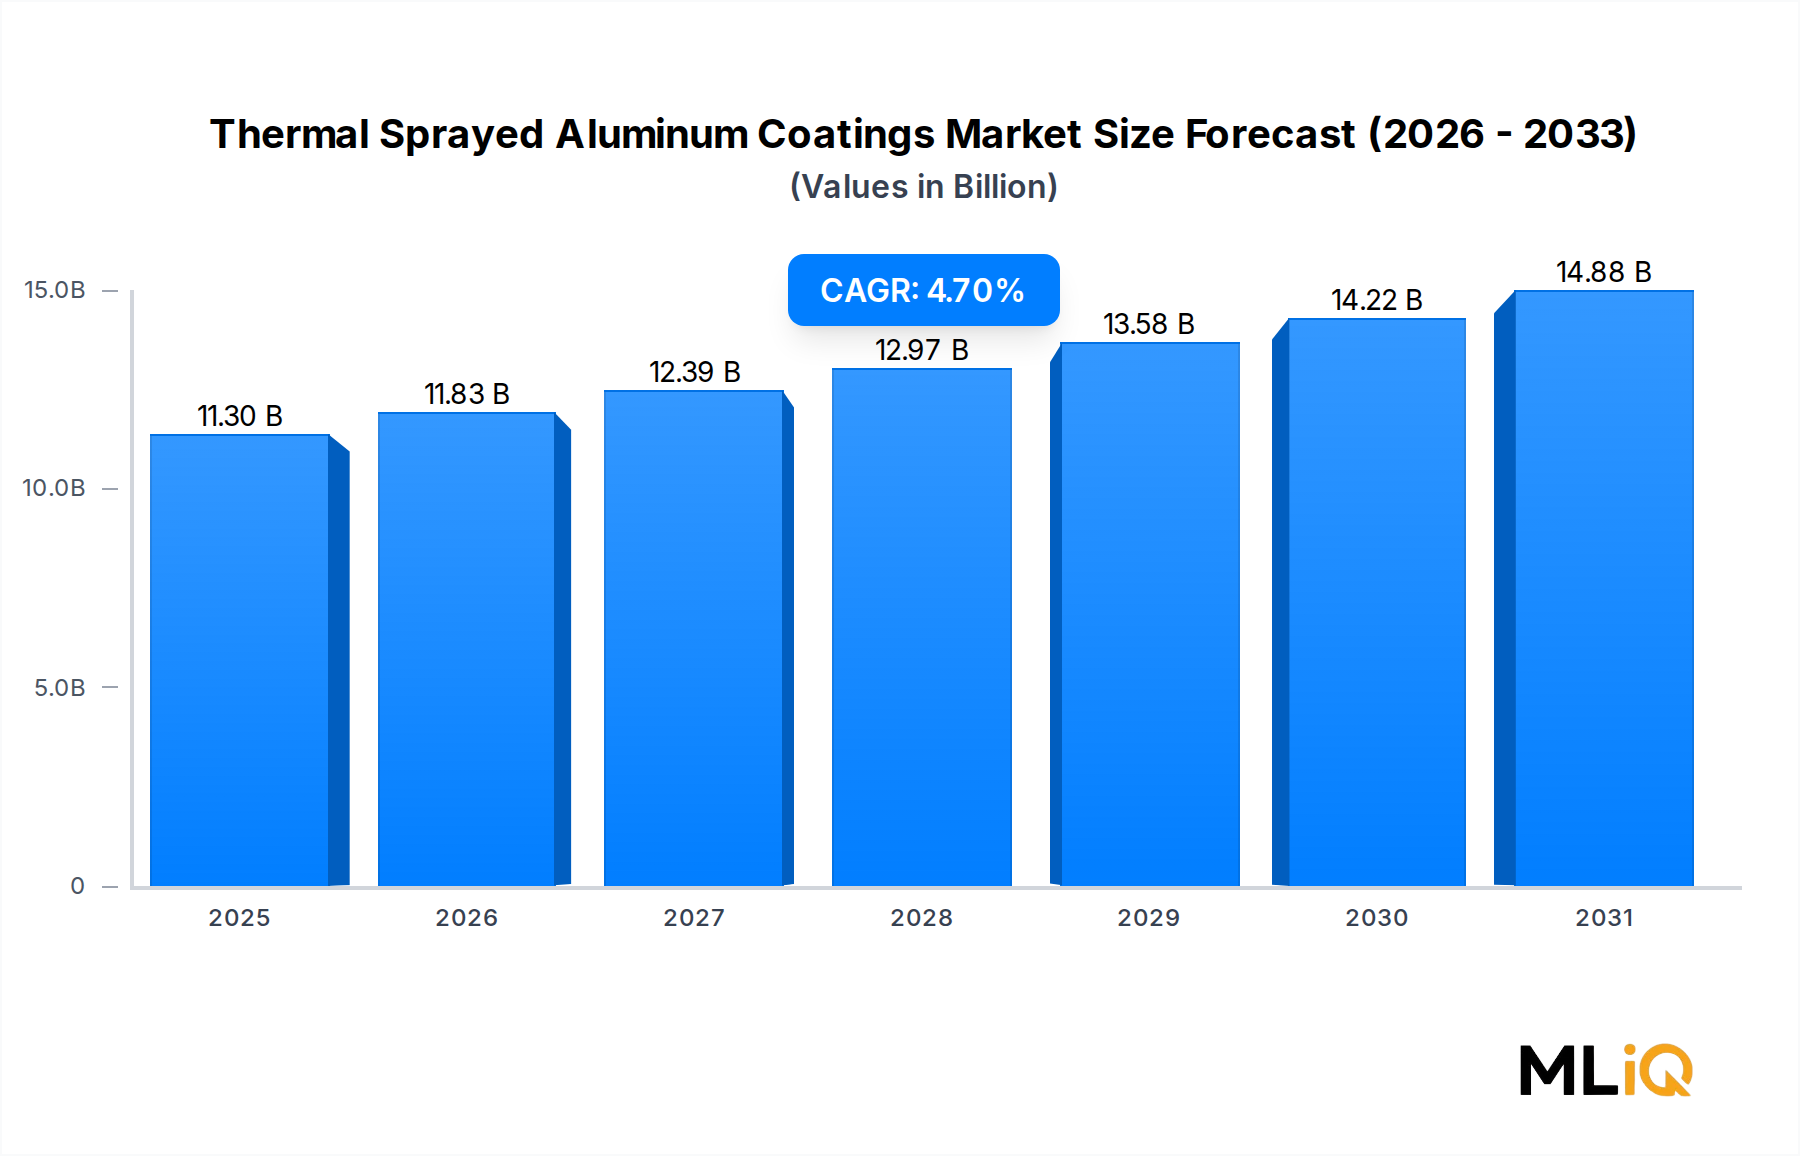
Thermal Sprayed Aluminum Coatings Market Size (In Billion)
15.0B
10.0B
5.0B
0
11.30 B
2025
11.83 B
2026
12.39 B
2027
12.97 B
2028
13.58 B
2029
14.22 B
2030
14.88 B
2031
Market at a Glance
The Thermal Sprayed Aluminum Coatings Market enters 2025 at $11.3 billion, with a 4.7% CAGR pushing valuation to $16.3 billion by 2033. Growth is anchored in oil and gas asset integrity, marine corrosion protection, and aerospace thermal management. Anti-corrosion applications generate 42% of revenue, while arc spraying remains the volume-leading product type at 38% share. Aluminum wire feedstock costs, which represent 48–55% of applied coating cost, introduce margin volatility, but field-applied automation and low-fume wire formulations reduce labor intensity.
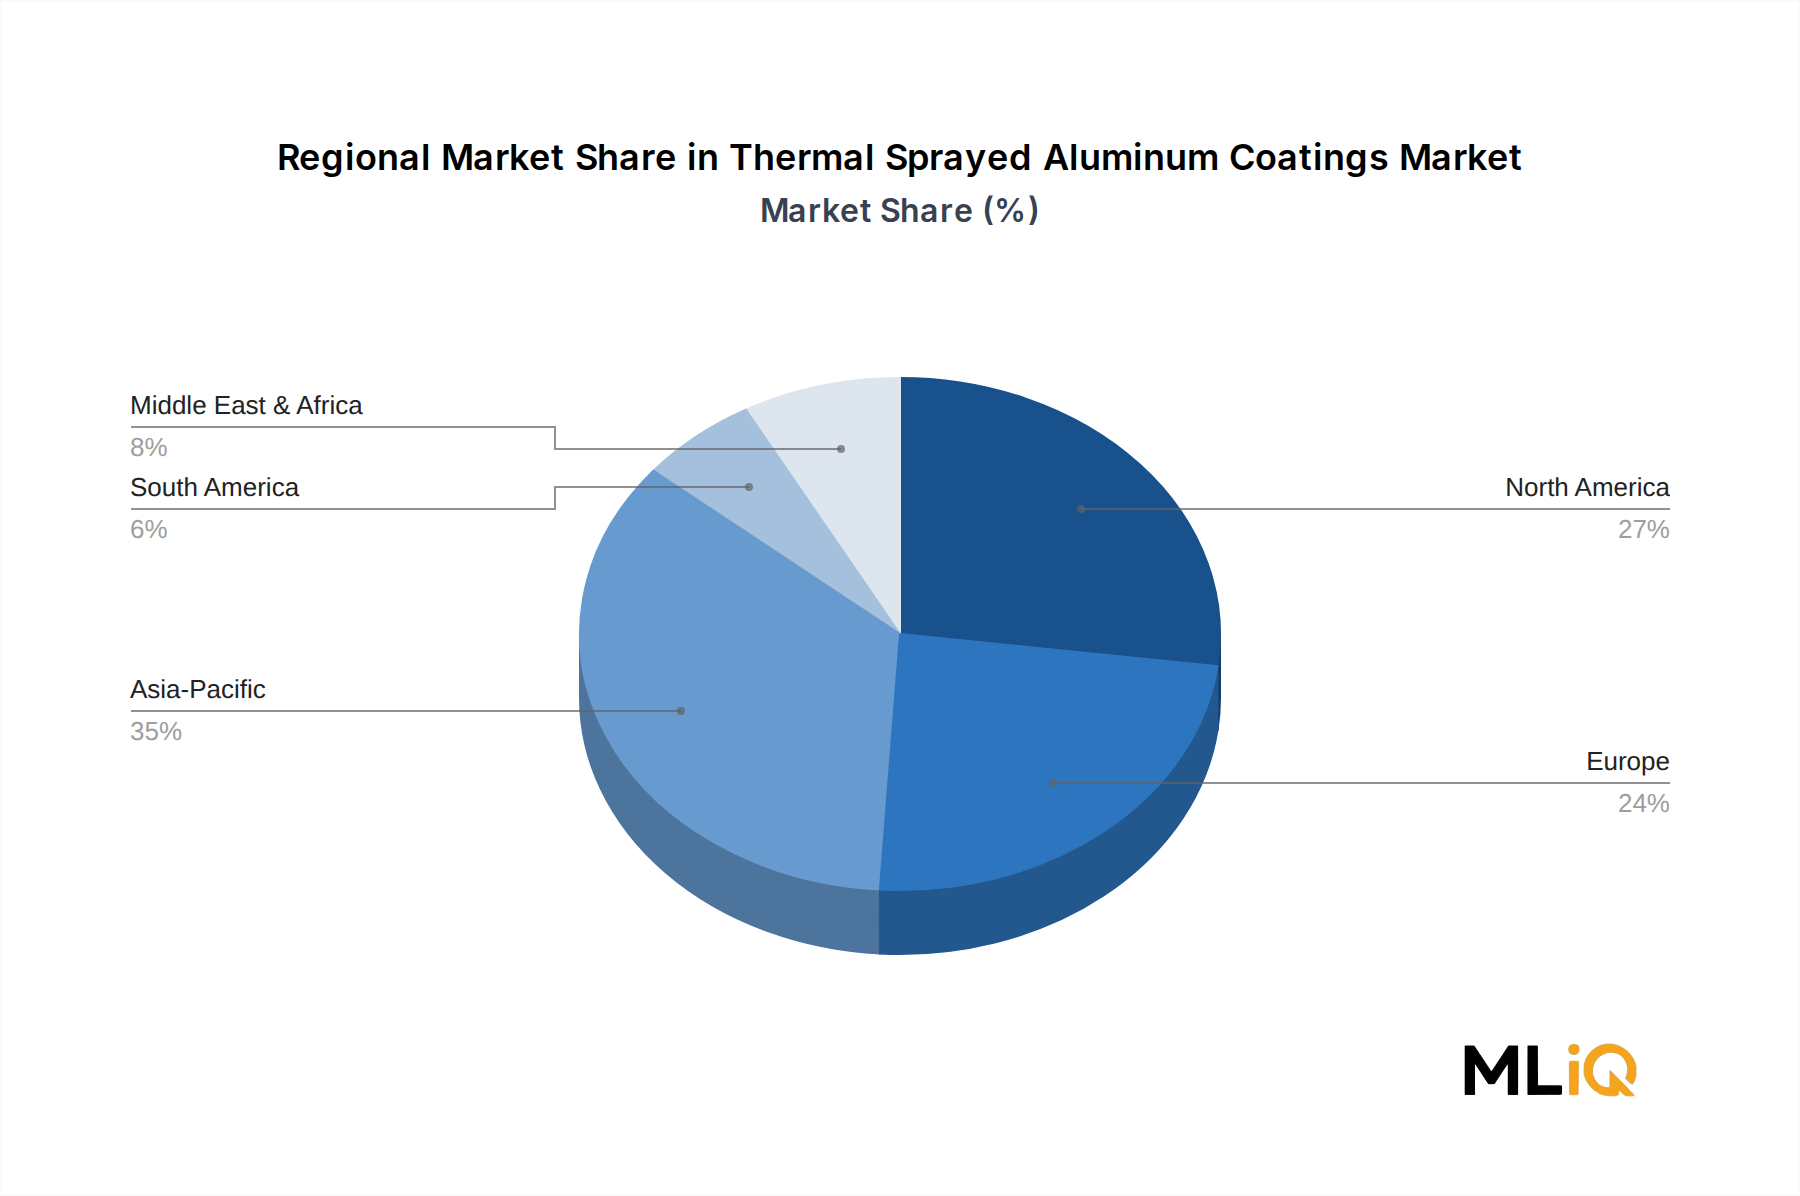
Asia-Pacific leads regional demand with 35% of global revenue, driven by Chinese and Indian refinery expansions, shipbuilding output, and pipeline construction. North America and Europe follow at 27% and 24%, respectively, supported by strict corrosion management rules such as AMPP SP0188 and ISO 12944. South America and Middle East & Africa account for 14% combined, with offshore oil and gas projects in Brazil and the GCC supporting high-spec coating demand.
Key segment momentum:
Anti-Corrosion Thermal Spray Coatings Market holds the largest application share, exceeding 42% of revenue.
Oil Gas Thermal Spray Coatings Market demand is tied to pipeline replacement cycles and refinery turnarounds.
Flame Spraying Coatings Market and Arc Spraying Coatings Market together represent over 70% of product-type revenue.
Aluminum Thermal Spray Wire Market remains the critical input, with 99.5%+ purity wire commanding premium pricing.
Thermal Barrier Coatings Market grows faster in aerospace, albeit from a smaller base.
Strategic takeaway: Suppliers that secure low-cost aluminum wire, offer on-site application services, and comply with REACH and OSHA exposure limits will capture share as end users shift from paint-only systems to metallurgically bonded aluminum coatings.
Oil and gas pipeline, marine hull, and offshore platform corrosion protection
Wear Resistant
4.4%
18%
Mining, cement, and power plant component life extension
Thermal Barrier
5.6%
11%
Aerospace turbine and automotive exhaust thermal management
Decorative Coatings
3.1%
9%
Architectural and consumer product surface finishes
Anti-corrosion is the dominant revenue engine in the Thermal Sprayed Aluminum Coatings Market, projected to remain 42% of total value through 2027. The segment benefits from the intrinsic sacrificial action of aluminum in chloride-rich environments. Arc-sprayed aluminum coatings on offshore platforms and bridge structures deliver 15–25 years of protection, compared with 5–8 years for conventional paint systems. This performance differential supports a 5.1% CAGR for anti-corrosion despite raw material inflation.
Sub-Segment Dynamics
Arc Spraying: Largest product type by volume, with 38% share. Preferred for field-applied pipelines and ship hulls due to high deposition rates (10–30 kg/h).
Flame Spraying: Second at 33% share, used where portability and lower capital cost matter. Flame Spraying Coatings Market demand is strong in smaller fabrication shops.
Oxyethylene Flame Powder Coating Spraying: Niche but rising at 4.9% CAGR for decorative and wear-resistant applications. The Oxyethylene Flame Powder Coating Spraying Market remains equipment-dependent.
Wear Resistant Coatings Market: Expands at 4.4% as mining and cement operators adopt aluminum-based coatings for pump housings and fan blades.
Margin Pressures
Aluminum wire accounts for 48–55% of direct coating cost. Energy and labor each represent 12–18% and 15–22%, respectively. Margins compress when LME aluminum prices rise above $2,800/t, as coating applicators cannot always pass through increases in fixed-price service contracts. Automation, such as robotic arc spray cells, reduces labor per square meter by 20–30%, partially offsetting pressure.
Ceramic and metal coating materials, global distribution
Aerospace, automotive, energy
Leader
Linde Plc.
Gas supply and thermal spray process gases
Coating applicators, OEMs
Challenger
Morgan Advanced Materials Plc.
Advanced ceramic and thermal management components
Aerospace, semiconductor, industrial
Challenger
KCC Corporation
Coatings and specialty materials in Asia
Marine, construction, industrial
Niche
A&A Thermal Spray Coatings, Inc.
On-site coating services for large structures
Oil and gas, bridges, marine
Niche
APS Materials, Inc.
Specialty thermal spray coatings and R&D
Aerospace, medical, industrial
Niche
Integrated Global Services, Inc.
Field-applied corrosion and wear coatings
Refining, petrochemical, power
Challenger
Profiles:
Oerlikon Metco: Offers integrated arc spray and flame spray equipment plus aluminum wire feedstock, targeting high-volume oil and gas corrosion projects.
3M: Supplies thermal spray materials and ceramic powders, leveraging global distribution into aerospace and automotive Wear Resistant Coatings Market demand.
Linde Plc.: Provides process gases and gas management systems that improve flame spray efficiency and coating porosity control.
Morgan Advanced Materials Plc.: Focuses on high-temperature ceramic components and thermal barrier systems for turbine and industrial applications.
KCC Corporation: Maintains a strong Asian coatings portfolio, with aluminum thermal spray products used in marine and construction corrosion protection.
A&A Thermal Spray Coatings, Inc.: Delivers mobile arc spray services for bridges, tanks, and offshore structures, competing on turnaround speed.
APS Materials, Inc.: Specializes in custom coatings for aerospace and medical devices, emphasizing low-porosity aluminum and alloy coatings.
Integrated Global Services, Inc.: Provides on-site thermal spray solutions for refinery and petrochemical assets, reducing downtime versus shop-applied coatings.
Asia-Pacific is the fastest-growing and largest regional market, with 35% of global revenue. China and India account for 68% of regional demand, driven by pipeline construction, shipbuilding, and refinery capacity additions. The Anti-Corrosion Thermal Spray Coatings Market in Asia-Pacific benefits from lower labor costs but faces rising environmental enforcement.
North America and Europe are mature, with growth tied to maintenance and replacement. North America’s $3.05B base is supported by strict pipeline integrity rules and a large installed base of oil and gas infrastructure. Europe’s $2.71B market is shaped by ISO 12944 and REACH, pushing suppliers toward low-VOC and low-fume aluminum wire.
Middle East & Africa grows at 4.9%, with GCC offshore platforms and desalination plants requiring chloride-resistant coatings. South America grows at 4.0%, led by Brazil’s pre-salt oil fields and mining wear applications. LAMEA’s combined share is 14%, but project lumpiness creates revenue volatility.
Trade corridors for thermal sprayed aluminum coatings follow aluminum wire feedstock and equipment flows. Key net exporters of aluminum wire and spray equipment include China, Germany, and the United States. Major importers are oil and gas project hubs in the GCC, Southeast Asia, and Brazil. China supplies an estimated 30–35% of global aluminum thermal spray wire volume, while Germany and the U.S. supply high-end arc spray systems and alloy wires.
Trade Flow
Key Countries
Product Focus
Tariff/Barrier Risk
China to Asia-Pacific
China, ASEAN, India
Aluminum wire, arc spray equipment
Medium; anti-dumping scrutiny
Germany to Europe/MEA
Germany, GCC, Turkey
High-end flame spray systems
Low; EU trade agreements
U.S. to North America/LATAM
U.S., Mexico, Brazil
Aluminum wire, coating services
Medium; Section 232 aluminum tariffs
Japan/South Korea to Asia
Japan, South Korea, China
Precision thermal spray components
Low; RCEP benefits
Tariffs on aluminum products, including U.S. Section 232 duties, raise wire feedstock costs by 5–10% for import-dependent applicators. Non-tariff barriers include REACH registration for coating chemicals and OSHA exposure documentation. Regional trade agreements such as RCEP reduce equipment tariffs but do not eliminate certification costs. The Aluminum Thermal Spray Wire Market remains exposed to geopolitical disruptions, with freight and insurance adding 3–7% to landed costs during peak periods.
Average selling prices (ASP) for thermal sprayed aluminum coatings range from $18/kg for standard arc-sprayed wire to $35/kg for high-purity alloy wire, while applied coating services price at $25–$60 per square meter depending on thickness and access. Cost structures vary by process:
Raw materials (aluminum wire, powders, gases): 45–60%
Labor: 15–25%
Energy: 10–18%
Logistics and overhead: 8–15%
Cost Component
Share of Total Cost
Pricing Sensitivity
Aluminum wire/powder
48–55%
High
Labor
15–22%
Medium
Energy
12–18%
Medium
Logistics
5–10%
Low to medium
Compliance/QA
4–8%
Medium
Margin pressure intensifies when LME aluminum prices exceed $2,800/t, squeezing applicators with fixed-price contracts. Suppliers with backward integration into wire drawing or long-term aluminum hedges maintain 18–24% gross margins, compared with 10–14% for service-only applicators. The Wear Resistant Coatings Market and Thermal Barrier Coatings Market support premium pricing because performance failures carry high downtime costs. Automation and low-fume wire reduce labor and compliance costs, but capital outlays delay payback by 2–3 years for smaller applicators.
Table 52: Rest of Asia Pacific Thermal Sprayed Aluminum Coatings Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of total research effort through primary interviews, surveys, and on-site verification. Target data accuracy: 85–90%.
Interviewed Thermal Spray Process Development Directors, Corrosion Engineering Managers, Oil & Gas Asset Integrity Procurement Leads, and Marine Coatings Technical Superintendents.
Surveyed and interviewed 4–5 specific company types: thermal spray aluminum wire feedstock producers; arc/flame spray equipment OEMs for field-applied corrosion coatings; oil and gas asset integrity service contractors; marine coating applicators and shipyards; aerospace thermal barrier coating job shops; and chemical/petrochemical plant engineering firms.
Primary questions covered applied coating cost per square meter, aluminum wire consumption per arc spray system, replacement cycles for offshore and marine assets, and compliance costs for OSHA and REACH.
Cross-checked interview responses against purchase orders, tender documents, and service contract data where available.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Corrosion Engineering Manager
30%
Thermal Spray Process Development Director
25%
Oil & Gas Asset Integrity Procurement Lead
20%
Marine Coatings Technical Superintendent
15%
Aerospace Materials Engineer
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Thermal spray aluminum wire feedstock producers
28%
Arc/flame spray equipment OEMs for field-applied corrosion coatings
Reviewed company filings, investor presentations, trade association reports, and government export-import statistics for aluminum wire, thermal spray equipment, and coating services.
Every report is updated to the date of purchase, with data refreshed for aluminum price movements, regulatory changes, and project announcements.
Demand Modeling & Market Estimation
Applied top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up variables included: global installed base of oil and gas pipelines requiring corrosion protection (km); average annual thermal spray wire consumption per active arc spray system (kg); number of active shipyards and offshore platforms by region; average coating replacement cycle in marine and offshore assets (years); and coating spend per refinery turnaround.
Top-down variables included: regional oil and gas capital expenditure, marine newbuild and MRO spending, aerospace engine overhaul volumes, and industrial maintenance budgets.
Segmented demand by Product Type (Flame Spraying, Oxyethylene Flame Powder Coating Spraying, Arc Spraying), Application (Anti-Corrosion, Decorative Coatings, Wear Resistant, Thermal Barrier, Others), and End-use Industry (Oil Gas, Chemical Petrochemical, Marine, Automotive Aerospace, Others).
Regional models covered North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific).
Forecast period: 2026–2034; base year: 2025.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, achieved through multi-level triangulation of primary interviews, financial databases, and trade statistics.
Each segment and regional estimate was validated against at least two independent sources, including .gov trade data, .org technical standards, and trade association shipment reports.
Outlier detection removed responses inconsistent with LME aluminum price benchmarks and known project timelines.
Final market sizes were reconciled with company-level revenue for Oerlikon Metco, 3M, Linde Plc., Morgan Advanced Materials Plc., KCC Corporation, and Integrated Global Services, Inc.
Reports are updated to the date of purchase; clients receive revision notes for material changes in tariffs, aluminum prices, or regulatory exposure limits.
Frequently Asked Questions
1. What notable developments, M&A activity, or product launches have shaped the Thermal Sprayed Aluminum Coatings Market recently?
In 2024–2025, Oerlikon Metco launched low-fume aluminum arc spray wire, Integrated Global Services expanded Gulf Coast on-site coating capacity, and Morgan Advanced Materials acquired thermal barrier coating assets. 3M also formed an Asian distribution partnership for thermal spray materials. These moves target stricter OSHA exposure limits and growing marine and aerospace demand.
2. How do export-import dynamics and trade flows affect the Thermal Sprayed Aluminum Coatings Market?
China supplies an estimated 30–35% of global aluminum thermal spray wire volume, while Germany and the U.S. export high-end arc and flame spray systems. U.S. Section 232 aluminum tariffs raise wire feedstock costs by 5–10% for import-dependent applicators. RCEP reduces equipment tariffs in Asia but does not remove REACH or OSHA certification costs.
3. What are current pricing trends and cost structure dynamics in the Thermal Sprayed Aluminum Coatings Market?
Average selling prices range from $18/kg for standard arc-sprayed wire to $35/kg for high-purity alloy wire, with applied coating services at $25–$60 per square meter. Aluminum wire represents 48–55% of direct cost, followed by labor at 15–22% and energy at 12–18%. Gross margins vary from 10–14% for service-only applicators to 18–24% for backward-integrated suppliers.
4. What is the current market size, valuation, and CAGR projection through 2033 for the Thermal Sprayed Aluminum Coatings Market?
The market is valued at $11.3 billion in 2025 and is projected to reach $16.3 billion by 2033, expanding at a 4.7% CAGR over the forecast period 2026–2034. Asia-Pacific accounts for 35% of global revenue, followed by North America at 27% and Europe at 24%. Anti-corrosion applications contribute 42% of total value.
5. Which regulatory bodies and compliance rules impact the Thermal Sprayed Aluminum Coatings Market?
OSHA permissible exposure limits for aluminum oxide fume, EU REACH registration, and ISO 12944 corrosion protection standards shape coating formulation and application. AMPP SP0188 and ASTM B08 test methods influence qualification for oil and gas and marine projects. Compliance can add 4–8% to total coating cost and favors larger, automated applicators.
6. What are the major challenges, restraints, or supply-chain risks in the Thermal Sprayed Aluminum Coatings Market?
Aluminum wire prices fluctuated 20–30% between 2021 and 2024, destabilizing fixed-price service contracts. Certified thermal spray operators require 6–12 months of training, and enclosed fume control systems cost $150,000–$500,000 per cell. Project lumpiness in LAMEA and freight cost spikes of 3–7% further pressure supply chains.