Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Microencapsulated Ingredients Market: 5.3% CAGR to 2033
North America & Europe Microencapsulated Ingredients Market
Microencapsulated Ingredients Market: 5.3% CAGR to 2033
North America & Europe Microencapsulated Ingredients Market by Ingredients (Pigments, Vitamins, UV filters, Skin Lightening Components, Essential Oils, Antiaging Components, Active Ingredients), by Application (Color Cosmetics, Sunscreen Lotions/UV Protection, Whitening & Lightening Creams, Anti-Wrinkle & Antiaging Creams, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 376
Ingredients - Vitamins & Active Ingredients (est. 34%); Application - Color Cosmetics (est. 31%)
Key Insights & Executive Summary: North America & Europe Microencapsulated Ingredients Market
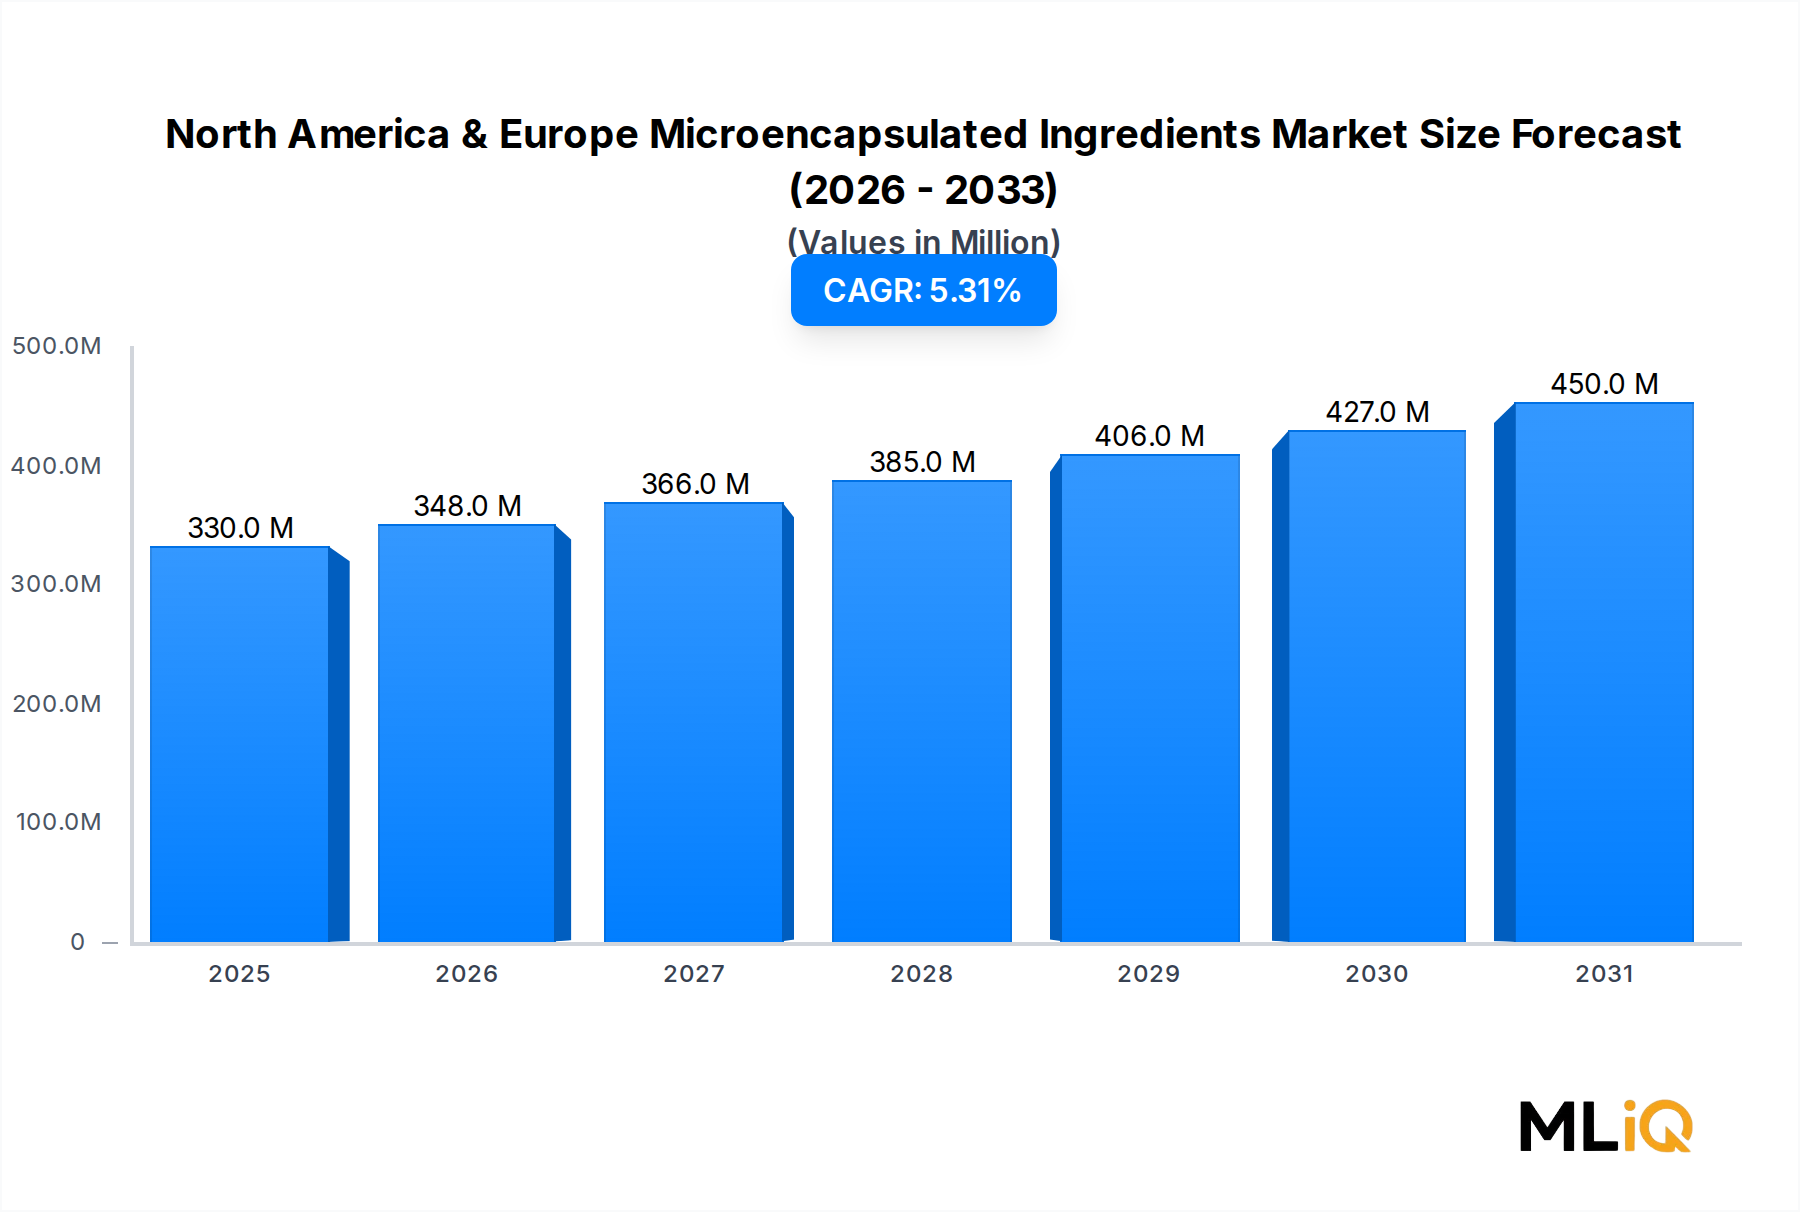
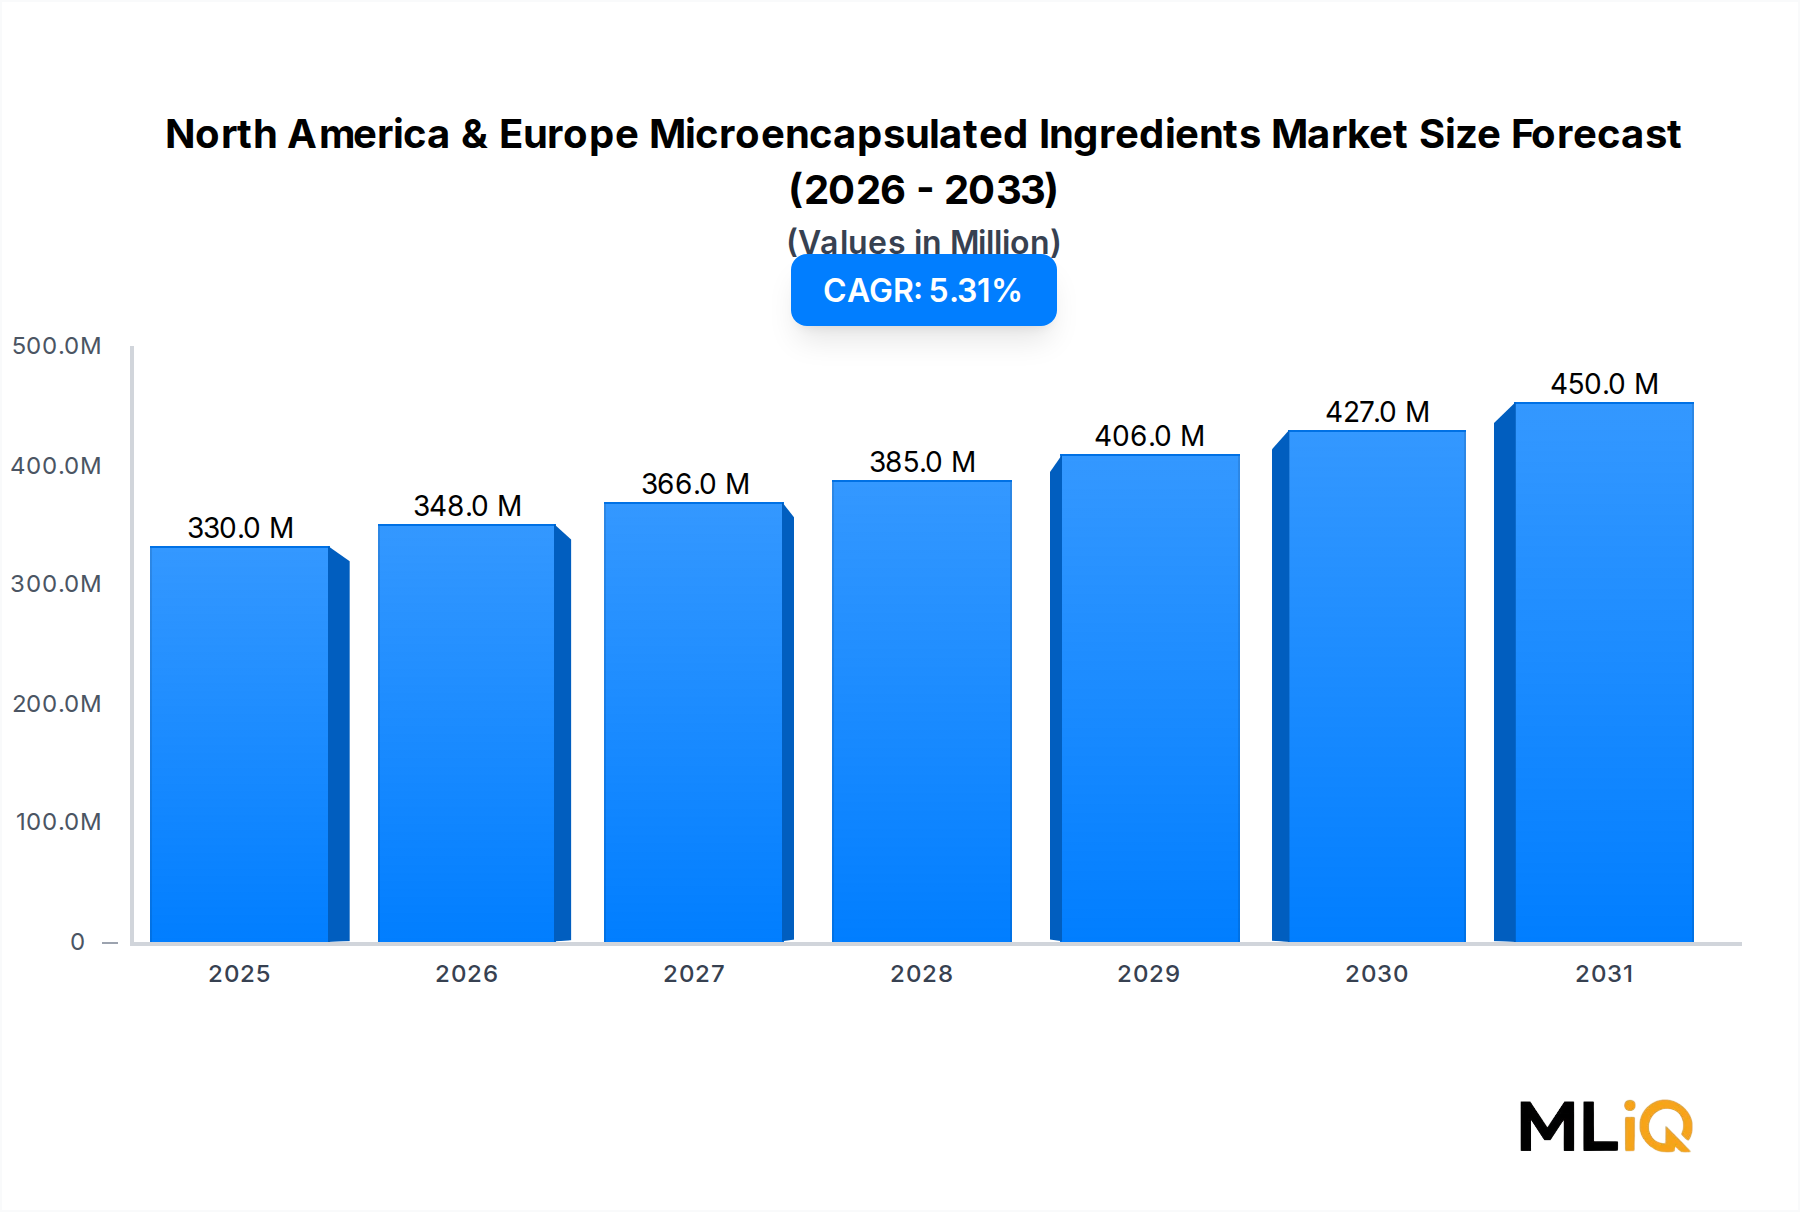
North America & Europe Microencapsulated Ingredients Market Size (In Million)
500.0M
400.0M
300.0M
200.0M
100.0M
0
330.0 M
2025
348.0 M
2026
366.0 M
2027
385.0 M
2028
406.0 M
2029
427.0 M
2030
450.0 M
2031
Market at a Glance
The North America & Europe microencapsulated ingredients market is valued at USD 330.02 million in 2025 and is projected to reach USD 498.8 million by 2033, expanding at a 5.3% CAGR. Growth is being pulled by reformulation in skin care and sun care, where encapsulated actives deliver better stability, lower irritation profiles and reduced use rates per unit of finished product.
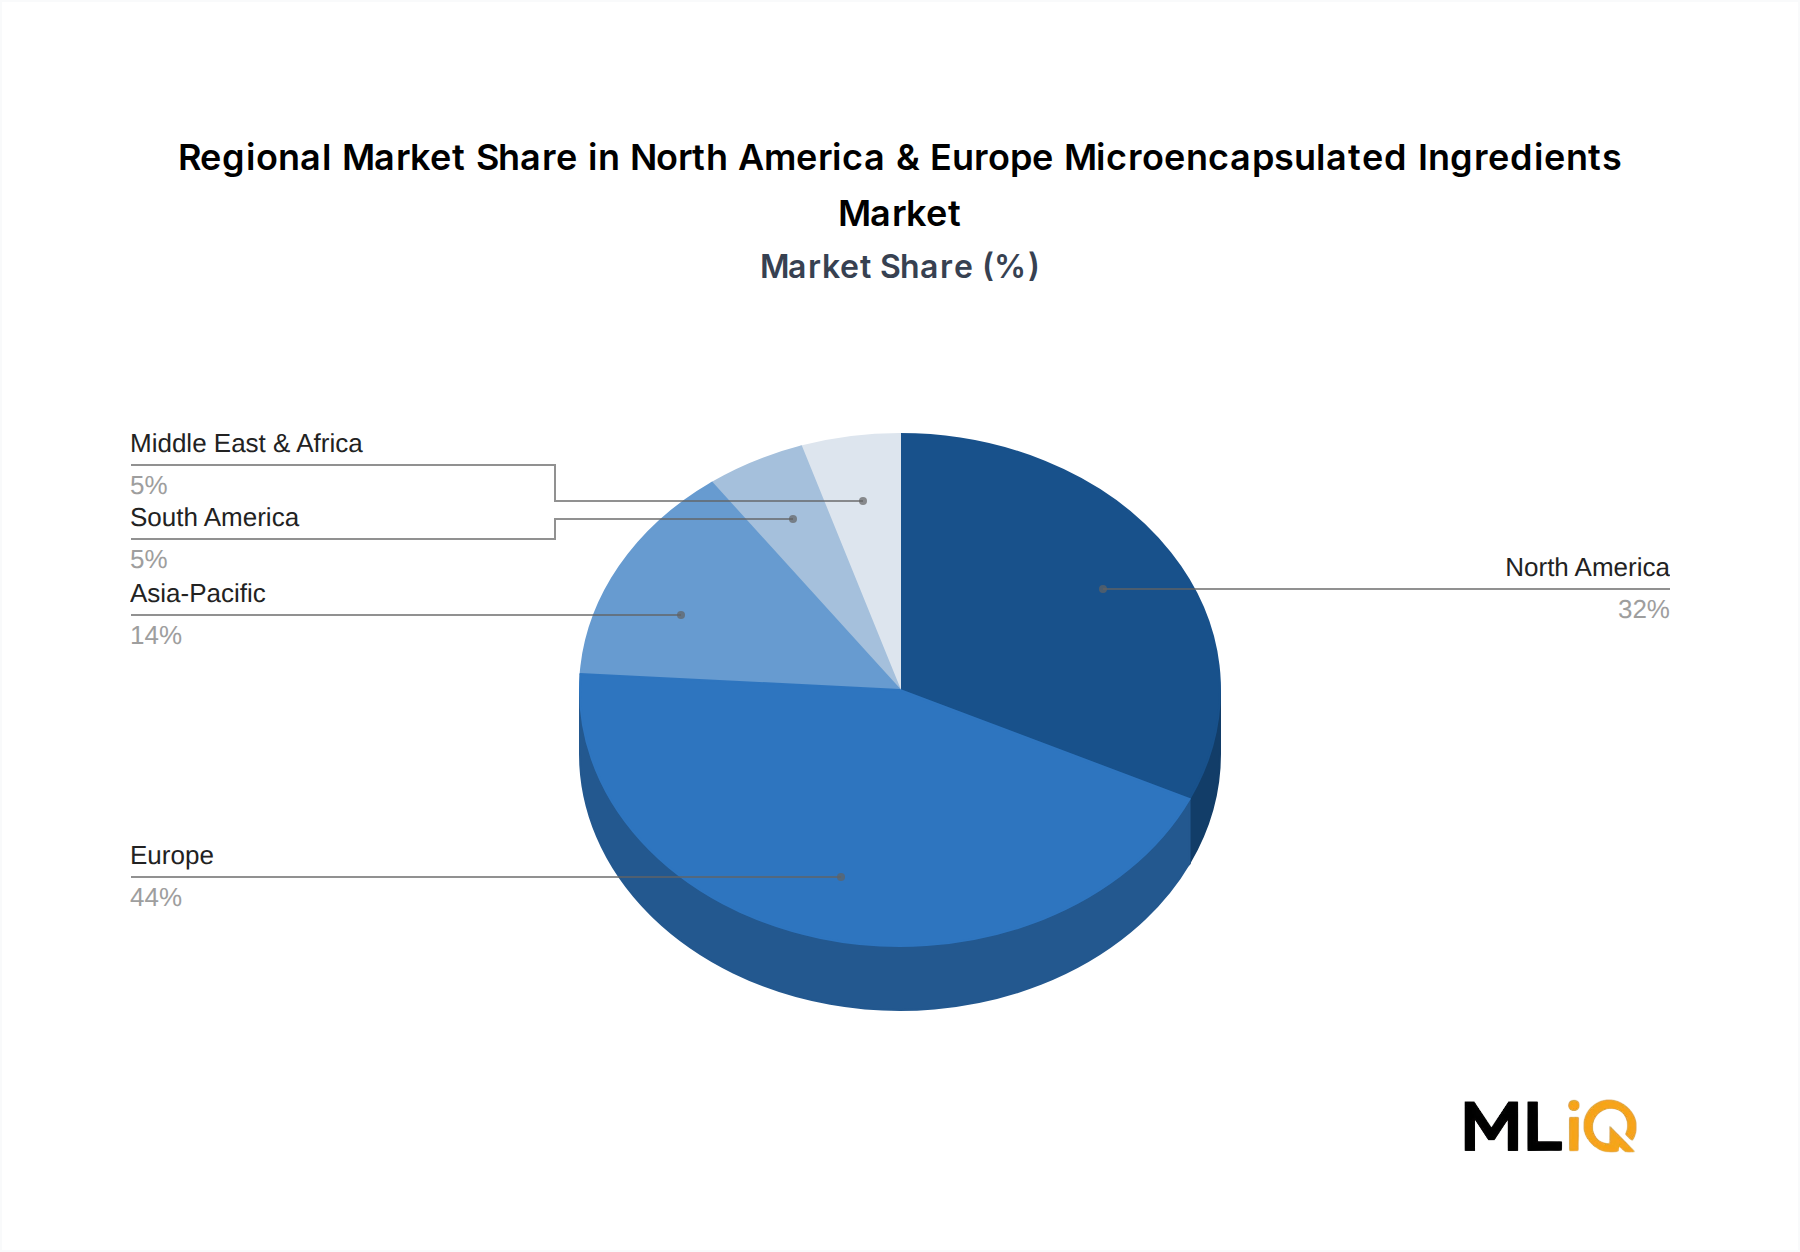
Europe holds an estimated 44% of combined revenue, supported by stringent photostability, safety-dossier and microplastic-restriction requirements that push formulators toward engineered delivery systems.
North America follows at roughly 32%, where the Color Cosmetics Market and the Anti-Aging Creams Market absorb the largest volumes of encapsulated pigments, retinoids and vitamin derivatives.
Price realization is stronger in the Encapsulated UV Filters Market than in commodity pigment grades because technical service, photostability testing and regulatory documentation are bundled into the sale.
The Microencapsulated Vitamins Market is the fastest-moving product block, with retinol, ascorbic acid and tocopherol formats pulling premium pricing of 1.8x to 3.2x their free-form equivalents.
What Is Driving Momentum
Sun care reformulation remains the single largest near-term catalyst. Filter approvals, photostability claims and irritation-reduction labelling all push demand toward encapsulated systems, and brand owners are increasingly purchasing encapsulated intermediates rather than raw powders. Suppliers with in-house spray-drying, fluid-bed coating and lipid-matrix extrusion capacity capture the highest margin per kilogram, while toll processors compete mainly on price.
Where the Risk Sits
Margin pressure is concentrated in pigment and essential oil encapsulation, where differentiation is limited and customers run multi-source tenders annually. Regulatory divergence between the EU REACH microplastic restriction and the US approach under MoCRA creates dual compliance cost, particularly for polymer-shell carriers. Volume growth is projected slightly below value growth, confirming a mix shift toward higher-priced, technically specified grades.
Strategic Signal
2025 Reading
2033 Implication
Value vs. volume growth gap
Value 5.3%, volume est. 4.6%
Continued premium mix shift
Europe share of revenue
44%
Regulatory-led specification power
Encapsulated active price premium
1.8x-3.2x
Margin pool stays with encapsulators
Segment Deep-Dive: Ingredients Segment Dominance in North America & Europe Microencapsulated Ingredients Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Ingredients - Vitamins & Active Ingredients
6.1
34
Stability-protected retinol, ascorbic acid and niacinamide in premium skin care
Photostability, phototoxicity compliance and SPF performance claims
Ingredients - Pigments & Essential Oils
4.4
22
Long-wear color, low-migration formats and controlled fragrance release
Application - Color Cosmetics
5.0
31
Pigment dispersion stability and clean-label texture demand
Application - Anti-Wrinkle & Antiaging Creams
5.9
24
Encapsulated retinoids with controlled release and lower irritation
Vitamins and Active Ingredients Lead Revenue
Vitamins and active ingredients generate the largest single revenue block, estimated at 34% of combined market value. The economics are straightforward: encapsulation protects labile molecules from oxidation and pH-driven degradation, extending shelf life and allowing higher effective payloads per gram of finished formulation. Retinoid encapsulation alone carries a price premium of 2.0x to 3.2x over free retinol because it directly addresses the irritation complaints that constrain use rates.
Ascorbic acid and its derivatives are the highest-volume encapsulated actives, driven by brightening and antioxidant claims in both regions.
Retinoid systems command the highest per-kilogram margin but face the longest formulation qualification cycles, often 9-18 months.
Niacinamide and peptide blends are growing fastest off a smaller base, with double-digit volume gains in premium skin care.
Pigments and the Color Cosmetics Pull
The Microencapsulated Pigments Market is the most mature block and the most price-sensitive. Encapsulation here solves dispersion stability, oil migration and shade drift in long-wear formats, but buyers treat the technology as a base requirement rather than a premium feature. As a result, gross margins in this block typically run 6-10 percentage points below the actives block.
Sub-Segment Dynamics and Margin Pressure
UV filters are shifting toward encapsulated organic and inorganic hybrids to reduce skin penetration concerns and improve SPF efficiency per gram.
Skin lightening components face tightening scrutiny in Europe, pushing suppliers toward lower-concentration, encapsulated delivery that preserves efficacy at reduced actives load.
Essential oils demand is driven by home and personal care fragrance release, where microcapsule wall chemistry determines both burst and longevity profiles.
Margin compression is sharpest in pigment grades, where annual tenders and multi-source qualification trim pricing power by an estimated 2-4% per year in nominal terms.
Primary Market Drivers & Growth Restraints in North America & Europe Microencapsulated Ingredients Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Migration from free-form to encapsulated Cosmetic Actives to cut irritation and extend shelf life
High
Short term
Driver
Sun care reformulation cycles in the EU and US requiring photostable filter systems
High
Short term
Driver
Premiumization across the Anti-Aging Creams Market and clean-label claims
Medium
Short term
Driver
Encapsulated vitamin premixes in beauty-from-within and nutraceutical adjacencies
Medium
Long term
Restraint
Narrow qualified supplier base for food-grade modified starches and gelatin wall materials
High
Short term
Restraint
EU restrictions on intentionally added microplastics and polymer-shell carriers
High
Long term
Restraint
Capital intensity of spray-drying and fluid-bed lines with long qualification cycles
Medium
Long term
Restraint
Price competition from conventional non-encapsulated Specialty Chemicals Market substitutes
Medium
Short term
Quantifying the Catalysts
The Cosmetic Actives Market is being structurally reshaped by claims regulation. When irritancy and photostability claims must be substantiated, encapsulation becomes the cheapest route to compliant performance rather than a marketing add-on. Premium skin care launches in Europe and North America disclosed encapsulated actives in an estimated 38% of new anti-aging SKUs in 2024, up from roughly 27% five years earlier.
Actives-led reformulation delivers a measurable cost offset: encapsulated systems allow actives loading reductions of 15-30% while maintaining consumer-perceived efficacy.
Sun care carries the strongest regulatory pull, with EU filter review cycles forcing dossier renewal and, in turn, reformulation toward encapsulated blends.
Quantifying the Bottlenecks
On the restraint side, wall-material concentration is the binding constraint. Fewer than ten global suppliers can deliver pharmaceutical-grade modified starch and gelatin at cosmetic specification, and a single supply interruption can stall launches for two quarters. The Specialty Chemicals Market offers abundant non-encapsulated substitutes at 40-60% lower unit cost, which caps pricing power in pigment and fragrance grades where performance differentiation is weakest.
Competitive Ecosystem & Key Vendor Profiles: North America & Europe Microencapsulated Ingredients Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
BASF SE
Broad actives portfolio and global encapsulation capability
Multinational beauty and personal care brands
Leader
DSM-Firmenich
Vitamin and UV filter systems with strong clinical substantiation
Premium skin care and sun care
Leader
Symrise AG
Encapsulated fragrance and cosmetic active delivery
Fragrance houses and beauty brands
Leader
Croda International Plc
Specialty actives and bio-based delivery systems
Clean-label and premium skin care
Leader
Ashland Global Holdings Inc.
Controlled-release actives and polymer expertise
Pharmaceutical-adjacent beauty
Challenger
Lonza Group Ltd
Encapsulation for sensitive actives and nutritional formats
Nutrition and personal care
Challenger
Merck KgaA
High-purity actives and pigment specialties
Color cosmetics and dermocosmetics
Challenger
Sensient Technologies Corporation
Encapsulated colorants and cosmetic pigments
Color cosmetics formulators
Challenger
Salvona LLC
Microsphere delivery platforms and licensing
Mid-size beauty brands
Niche
Reed Pacific Specialty Chemicals
Specialized cosmetic encapsulation inputs
Regional formulators
Niche
Vendor Profiles
BASF SE: Operates the widest actives-plus-delivery portfolio in the region, positioning it as the default specification partner for multinational launches requiring dual-region compliance documentation.
DSM-Firmenich: Combines vitamin manufacturing depth with UV filter know-how, giving it leverage in both the Microencapsulated Vitamins Market and encapsulated sun care systems.
Symrise AG: Differentiates through encapsulated fragrance and active blends, with strong pull from prestige beauty and home care customers.
Croda International Plc: Leans into bio-based and biodegradable shell chemistry, aligning directly with European microplastic restriction timelines.
Ashland Global Holdings Inc.: Bridges pharmaceutical-grade controlled release into cosmetic applications, targeting dermocosmetic and clinical skin care brands.
Lonza Group Ltd: Applies capsule and coating expertise across nutrition and personal care, capturing crossover demand for encapsulated vitamins.
Merck KgaA: Holds a defensible position in high-purity pigment specialties and active grades for dermocosmetics.
Sensient Technologies Corporation: Focuses on encapsulated colorants where visual performance and shade consistency drive repeat specification.
Salvona LLC: Licenses microsphere delivery platforms, giving mid-size brands access to encapsulation without capital investment.
Reed Pacific Specialty Chemicals: Serves regional formulators with specialized inputs, holding a defensible niche in smaller-volume applications.
Strategic Milestones & Recent Developments in North America & Europe Microencapsulated Ingredients Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2023-2024
BASF SE
Capacity / portfolio expansion
Widened actives encapsulation supply for premium skin care
2023-2024
DSM-Firmenich
Portfolio realignment
Consolidated vitamin and UV filter delivery capabilities
2024
Croda International Plc
Bio-based platform launch
Positioned against EU microplastic restriction timelines
2024
Symrise AG
Delivery system launch
Extended encapsulated fragrance and active offerings
2024-2025
Ashland Global Holdings Inc.
Technical partnership
Linked pharma-grade controlled release to cosmetic actives
2025
Salvona LLC
Licensing agreement
Broadened microsphere access for mid-size brands
Chronological Detail
2023-2024: Suppliers prioritized capacity additions in spray drying and fluid-bed coating rather than greenfield plants, a lower-capital route to volume that shortens payback to an estimated 4-6 years.
2024: Biodegradable shell chemistry moved from R&D to commercial specification as European customers began pre-qualifying carriers ahead of REACH microplastic transition deadlines.
2024-2025: Cross-sector technology transfer accelerated, with controlled-release pharmaceutical and nutritional coating expertise reapplied to cosmetic actives.
2025: Licensing and toll-manufacturing models expanded, allowing smaller brands to specify encapsulation without owning capital equipment.
Deal values in this segment are typically undisclosed, so competitive positioning is best read through capacity announcements, specification wins and licensing structures rather than headline transaction multiples.
Regional Market Analysis & Growth Corridors for North America & Europe Microencapsulated Ingredients Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (USD Mn)
Primary Catalyst
Regulatory Stringency
North America
4.9
105.6
Premium skin care and sun care reformulation; MoCRA compliance
High
Europe
5.5
145.2
REACH microplastic restriction and photostability rules
Very High
Asia-Pacific
6.8
46.2
Capacity build-out and domestic beauty demand
Medium to High
LAMEA
5.1
33.0
Neashoring of cosmetics filling and regional brand growth
Medium
Fastest-Growing vs. Most Mature Markets
Europe is the most mature and largest revenue pool at an estimated USD 145.2 million in 2025, with growth capped by market saturation but supported by the strictest regulatory pull in the world.
Asia-Pacific is the fastest-growing corridor at a projected 6.8% CAGR, driven by encapsulation capacity additions in China, India and South Korea plus rising domestic premium beauty demand.
North America expands at 4.9%, with the United States contributing roughly 80% of regional value and Mexico emerging as a nearshoring hub for cosmetic filling.
LAMEA remains a small but improving corridor at 5.1%, led by GCC premium beauty retail and South African personal care manufacturing.
Where Growth Corridors Form
Europe's regulatory stringency is a growth driver rather than a drag: it forces reformulation, and reformulation is the primary purchase trigger for encapsulated intermediates. North America's trajectory depends more on brand premiumization and the pace of MoCRA-driven safety documentation, which favors suppliers with mature dossier libraries. Asia-Pacific growth is supply-led, and several regional players now compete with European encapsulators on cost for pigment and essential oil grades.
Supply Chain & Raw Material Dynamics: North America & Europe Microencapsulated Ingredients Market
Upstream Dependency Map
Input
Primary Source Region
Price Trend Direction
Substitution Risk
Modified starch and maltodextrin
North America, EU
Stable to +3%
Low
Gum arabic
Sahelian Africa
Volatile, ±20%
Medium
Gelatin (pharma grade)
EU, North America
+4% to +6%
Medium
Alginate and cellulose derivatives
Asia-Pacific, EU
Stable
Low
Ascorbic acid and vitamin actives
China, EU
Volatile, ±25%
High
Organic UV filters
EU, Asia-Pacific
+2% to +5%
Low
Sourcing Risk and Historical Disruption
Wall materials determine both capsule performance and supply continuity, and the qualified supplier base is narrow. Modified starches and maltodextrin are broadly available, but pharmaceutical-grade gelatin and cosmetic-specification gum arabic come from fewer than ten credible global sources. Gum arabic remains the most volatile input because harvests are concentrated in acacia belts subject to drought and regional instability, and replacement in beverage and fragrance encapsulation requires a full re-qualification cycle.
Energy costs are a second-order risk: spray drying is energy-intensive, so a 30% regional gas price swing can move conversion cost by an estimated 8-12%.
Buffer stock has become standard practice, with leading formulators holding 8-12 weeks of wall material inventory.
Dual sourcing across at least two regions is now a prerequisite in most multinational supply contracts.
Price Volatility and Mitigation
Actives themselves carry the highest volatility. Ascorbic acid and vitamin E pricing has historically moved 20-40% year over year on upstream capacity shifts, which is why long-dated supply agreements and index-linked pricing clauses have become common. Encapsulation partially hedges this exposure by allowing lower actives loading per finished unit.
Export, Cross-Border Trade & Tariff Impact on North America & Europe Microencapsulated Ingredients Market
Trade Corridor Map
Corridor
Net Position
Key Commodity Flow
Trade Barrier Type
EU to North America
Net exporter
Encapsulated actives, UV filter systems
Tariff low; documentation heavy
North America to EU
Balanced
Pigment and colorant specialties
REACH compliance requirements
Asia-Pacific to EU/NA
Net exporter
Ascorbic acid, pigments, wall materials
Tariff moderate; anti-dumping scrutiny
Intra-EU
Net internal
Encapsulated intermediates for filling
None; single market
Trade Policy Exposure
Cross-border flows in this market are shaped more by regulatory documentation than by tariff levels. Encapsulated actives and cosmetic ingredients typically move under low or zero most-favored-nation duties, but EU REACH registration, the Cosmetics Regulation (EC) No 1223/2009 product information file, and US MoCRA facility registration each add cost and lead time that function as effective non-tariff barriers.
Asia-Pacific exporters face the steepest friction, primarily around dossier completeness and microplastic carrier classification rather than duty rates.
Intra-EU trade accounts for the largest share of encapsulated intermediate movements, since filling sites are frequently located outside the country of encapsulation.
North American imports of ascorbic acid and pigment intermediates remain concentrated, leaving formulators exposed to freight rate swings and port congestion.
Nearshoring into Mexico and Eastern Europe is shortening corridors and reducing landed cost by an estimated 5-9% for high-volume pigment grades.
Quantified Policy Impact
Where tariffs do apply, the effect is modest relative to compliance cost. A hypothetical 5% tariff on encapsulated intermediates would raise formulation input cost by roughly 2-3%, whereas a failed REACH dossier or microplastic reclassification can strand an entire SKU line for 12-24 months. This asymmetry explains why suppliers invest in regulatory affairs headcount faster than in tariff engineering.
North America & Europe Microencapsulated Ingredients Market Segmentation
1. Ingredients
1.1. Pigments
1.2. Vitamins
1.3. UV filters
1.4. Skin Lightening Components
1.5. Essential Oils
1.6. Antiaging Components
1.7. Active Ingredients
2. Application
2.1. Color Cosmetics
2.2. Sunscreen Lotions/UV Protection
2.3. Whitening & Lightening Creams
2.4. Anti-Wrinkle & Antiaging Creams
2.5. Others
North America & Europe Microencapsulated Ingredients Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
North America & Europe Microencapsulated Ingredients Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.3% from 2020-2034
Segmentation
By Ingredients
Pigments
Vitamins
UV filters
Skin Lightening Components
Essential Oils
Antiaging Components
Active Ingredients
By Application
Color Cosmetics
Sunscreen Lotions/UV Protection
Whitening & Lightening Creams
Anti-Wrinkle & Antiaging Creams
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Ingredients
5.1.1. Pigments
5.1.2. Vitamins
5.1.3. UV filters
5.1.4. Skin Lightening Components
5.1.5. Essential Oils
5.1.6. Antiaging Components
5.1.7. Active Ingredients
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Color Cosmetics
5.2.2. Sunscreen Lotions/UV Protection
5.2.3. Whitening & Lightening Creams
5.2.4. Anti-Wrinkle & Antiaging Creams
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Ingredients
6.1.1. Pigments
6.1.2. Vitamins
6.1.3. UV filters
6.1.4. Skin Lightening Components
6.1.5. Essential Oils
6.1.6. Antiaging Components
6.1.7. Active Ingredients
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Color Cosmetics
6.2.2. Sunscreen Lotions/UV Protection
6.2.3. Whitening & Lightening Creams
6.2.4. Anti-Wrinkle & Antiaging Creams
6.2.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Ingredients
7.1.1. Pigments
7.1.2. Vitamins
7.1.3. UV filters
7.1.4. Skin Lightening Components
7.1.5. Essential Oils
7.1.6. Antiaging Components
7.1.7. Active Ingredients
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Color Cosmetics
7.2.2. Sunscreen Lotions/UV Protection
7.2.3. Whitening & Lightening Creams
7.2.4. Anti-Wrinkle & Antiaging Creams
7.2.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Ingredients
8.1.1. Pigments
8.1.2. Vitamins
8.1.3. UV filters
8.1.4. Skin Lightening Components
8.1.5. Essential Oils
8.1.6. Antiaging Components
8.1.7. Active Ingredients
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Color Cosmetics
8.2.2. Sunscreen Lotions/UV Protection
8.2.3. Whitening & Lightening Creams
8.2.4. Anti-Wrinkle & Antiaging Creams
8.2.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Ingredients
9.1.1. Pigments
9.1.2. Vitamins
9.1.3. UV filters
9.1.4. Skin Lightening Components
9.1.5. Essential Oils
9.1.6. Antiaging Components
9.1.7. Active Ingredients
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Color Cosmetics
9.2.2. Sunscreen Lotions/UV Protection
9.2.3. Whitening & Lightening Creams
9.2.4. Anti-Wrinkle & Antiaging Creams
9.2.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Ingredients
10.1.1. Pigments
10.1.2. Vitamins
10.1.3. UV filters
10.1.4. Skin Lightening Components
10.1.5. Essential Oils
10.1.6. Antiaging Components
10.1.7. Active Ingredients
10.2. Market Analysis, Insights and Forecast - by Application
Figure 1: North America & Europe Microencapsulated Ingredients Market Revenue Breakdown (million, %) by Product 2026 & 2034
Figure 2: North America & Europe Microencapsulated Ingredients Market Value Share (%), by Ingredients 2026 & 2034
Figure 3: North America & Europe Microencapsulated Ingredients Market Value Share (%), by Application 2026 & 2034
Figure 4: North America & Europe Microencapsulated Ingredients Market Share (%) by Company 2026
List of Tables
Table 1: North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 2: North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 3: North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Region 2020 & 2034
Table 4: North America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 5: North America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 6: North America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Country 2020 & 2034
Table 7: United States North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 11: South America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 12: South America North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 17: Europe North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 18: Europe North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 29: Middle East & Africa North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 30: Middle East & Africa North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Ingredients 2020 & 2034
Table 38: Asia Pacific North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Application 2020 & 2034
Table 39: Asia Pacific North America & Europe Microencapsulated Ingredients Market Revenue million Forecast, by Country 2020 & 2034
Table 40: China North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific North America & Europe Microencapsulated Ingredients Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total study effort, with 20-30% derived from secondary and syndicated sources. Surveys, structured interviews and validation calls are conducted directly with decision-makers across the North America and Europe microencapsulated ingredients value chain.
Target respondent types include: (1) encapsulation technology managers at contract manufacturers operating spray-drying and fluid-bed coating lines; (2) ingredient category buyers at color cosmetics and sun care brand owners; (3) suppliers of wall materials such as modified starch, maltodextrin, gelatin, alginate and cyclodextrin; (4) regulatory and product safety leads handling EU Cosmetics Regulation (EC) No 1223/2009 and US MoCRA submissions; (5) specialty chemical distributors serving personal care formulators in North America and Europe.
Interviewed job titles include Director of Encapsulation R&D, Personal Care Ingredients Procurement Manager, Regulatory Affairs Lead - Cosmetics, Global Category Manager for Cosmetic Actives, and Process Engineering Manager - Spray Drying. Each respondent validates volume, price and specification data for the segment they own.
Primary inputs are cross-checked against shipment records, technical data sheets, tender documentation and qualification timelines shared under confidentiality.
Brand Owner Formulators (color cosmetics, sun care, skin care)
25%
Wall Material & Shell Polymer Suppliers
20%
Specialty Ingredient Distributors
15%
Active Ingredient Producers (vitamins, UV filters, pigments)
10%
Secondary Research & Industry Benchmarking
Secondary research covers published filings, trade statistics, patent activity, technical literature and regulatory dockets. Financial and transaction data are drawn from Bloomberg, Factiva, Hoovers and PitchBook.
Trade flow data are reconciled against national customs databases, HS-code level import-export records and published tariff schedules for cosmetic ingredients and encapsulated intermediates.
No market research reseller websites are used as primary source material; all third-party inputs are traced to originating filings, regulators or trade bodies.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously. The bottom-up build aggregates demand from formulator-level consumption and scales to regional totals; the top-down build allocates from ingredient-category and application-level revenue envelopes.
Specific quantitative metrics used in the bottom-up calculation include: (1) annual tonnage of encapsulated active ingredient consumed by cosmetic formulators in North America and Europe; (2) average encapsulation loading rate, expressed as percentage active per gram of microcapsule, by ingredient class; (3) average delivered price per kilogram for encapsulated vitamin, UV filter and pigment grades; (4) number of new color cosmetics and sun care SKUs launched annually per region that specify encapsulated actives; and (5) fill-volume by application category for sunscreen lotions, whitening creams and anti-aging creams.
Segment splits are validated against supplier revenue disclosures, distributor margin structures and toll-manufacturing fee benchmarks.
Forecasts to 2033 are built on base, mid and high scenarios, with the mid scenario anchored to a 5.3% CAGR and sensitivity tested against raw material price movement and regulatory transition timing.
Data Accuracy & Quality Check
Multi-level data triangulation is applied: primary interview data, secondary regulatory and trade data, and financial database inputs must reconcile within tolerance before a figure enters the model.
The study carries a guaranteed estimated data accuracy level of 85-90%, with confidence intervals disclosed for segment-level estimates where respondent samples are thinner.
Outlier responses are re-contacted for confirmation, and any divergence greater than 10% between top-down and bottom-up outputs triggers a reconciliation review.
Every report is updated to the date of purchase, so all market sizing, company profiles and regulatory references reflect the most recent available information at delivery.
Frequently Asked Questions
1. What are the biggest supply-chain risks facing this market?
The heaviest exposure sits upstream in wall materials: food-grade modified starches, maltodextrin, gum arabic and pharmaceutical-grade gelatin, where only a small group of qualified suppliers serve encapsulation formulators in both regions. Gum arabic sourcing remains concentrated in Sahelian acacia belts, and a single poor harvest can move spot prices by 15-25% within a season, forcing reformulation qualification cycles of 6-12 months. Spray-drying and fluid-bed capacity is also capital-intensive, so a line outage at one contract manufacturer can delay customer launches across multiple SKUs.
2. Who are the leading companies and how concentrated is the competitive field?
The field is moderately fragmented. BASF SE, DSM-Firmenich, Symrise AG, Croda International Plc, Ashland Global Holdings Inc. and Lonza Group Ltd hold the broadest actives and delivery-system portfolios, while Nouryon, Clariant AG, Sensient Technologies Corporation and Lycored compete on regional or sub-segment strength. No single vendor is estimated to exceed a 12-14% revenue share of the combined North America and Europe microencapsulated ingredients market, and switching costs are highest in UV filter and retinol encapsulation where regulatory dossiers must be re-filed.
3. How are raw materials sourced and how volatile are input prices?
Key inputs include modified starches, maltodextrin, gum arabic, alginate, gelatin, cyclodextrins, hydrogenated vegetable oils and silica shells, plus the active payloads themselves, such as ascorbic acid, retinoids, tocopherols and organic UV filters. Ascorbic acid and vitamin E pricing has historically swung 20-40% year over year on Chinese upstream capacity shifts, while energy-intensive spray drying ties production cost closely to regional gas and electricity rates. Most large formulators now dual-source wall materials across at least two suppliers and hold 8-12 weeks of buffer stock.
4. How do sustainability and ESG requirements affect product design?
Brand owners are pressing suppliers to eliminate microplastic-classified carriers and shift toward biodegradable shells such as starch, cellulose, alginate and protein-based systems. The EU restriction on intentionally added microplastics under REACH Annex XVII is the single strongest regulatory signal, with transition timelines running into the late 2020s for leave-on cosmetic uses. Vendors that publish third-party biodegradability data and lower solvent use in encapsulation processing are winning specification slots in premium skin care, and several have tied ESG targets to Scope 2 energy reduction at spray-drying sites.
5. Which region is growing fastest and where are the emerging opportunities?
Europe remains the largest revenue block at an estimated 44% share, but Asia-Pacific is the fastest-growing supply and demand corridor, expanding at a projected 6.5-7.0% CAGR as Chinese, Indian and South Korean formulators add encapsulation capacity. Within North America, Mexico is the fastest-moving manufacturing location for color cosmetics and sun care filling, benefiting from nearshoring. Adjacent opportunities sit in encapsulated probiotics, fragrance microcapsules for home care, and controlled-release agrochemical and pharmaceutical coatings that share the same equipment base.
6. What is the current market size and the CAGR projection through 2033?
The North America & Europe microencapsulated ingredients market is valued at **USD 330.02 million in 2025** and is forecast to reach approximately **USD 498.8 million by 2033**, growing at a **5.3% CAGR** across the 2025-2033 period. Ingredients-grade demand, principally encapsulated vitamins and active ingredients, contributes the largest share at roughly 34%, while color cosmetics and sun care together account for more than half of application-level consumption. Volume growth is projected slightly below value growth, implying continued mix shift toward higher-priced, technically specified encapsulation grades.