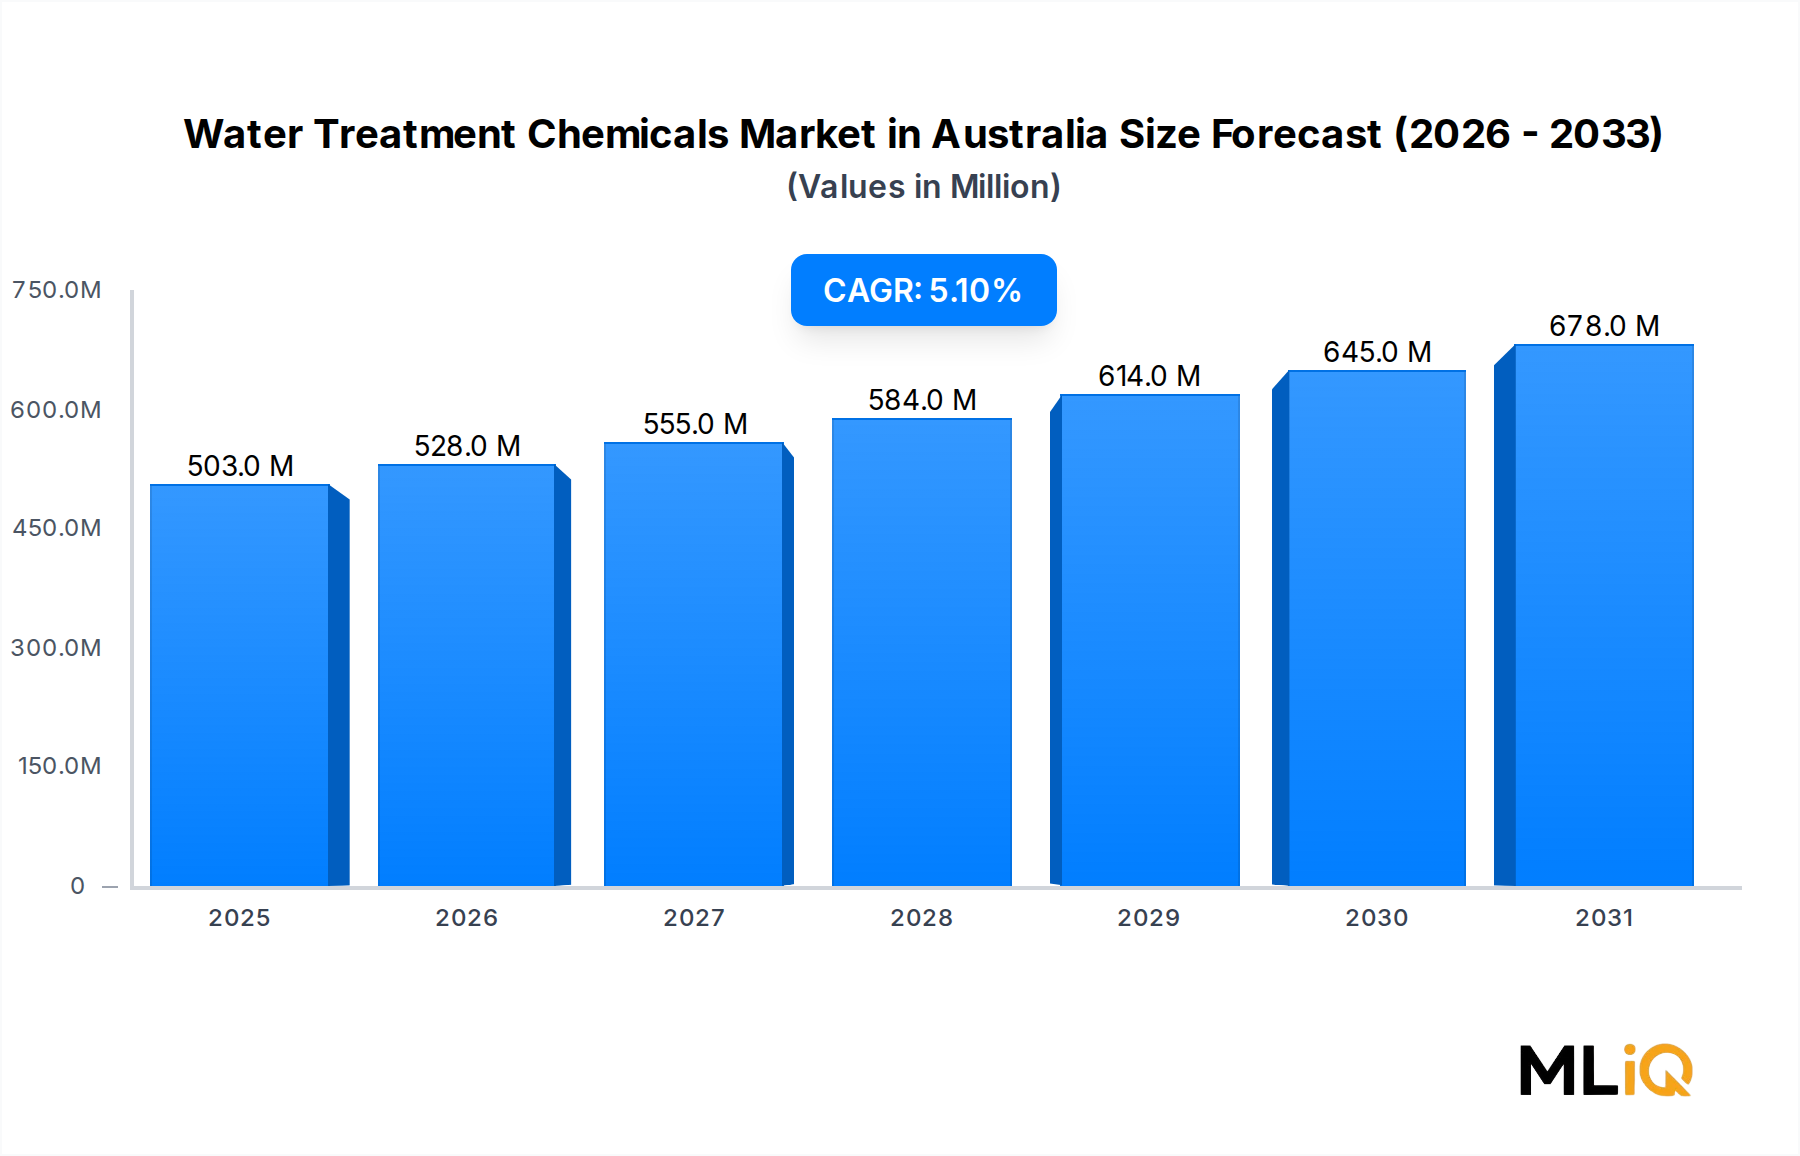
The Water Treatment Chemicals Market in Australia was valued at USD 502.71 million in 2025 and is projected to reach USD 749.0 million by 2033 at a CAGR of 5.11%. Demand is not evenly distributed across the value pool; product mix, water source characteristics, and sector-specific treatment requirements determine growth. Coagulants and flocculants dominate because municipal and mining operators need solids removal capacity under tightening discharge limits.
Municipal end-user industry remains the largest buyer, supported by population growth and investment in recycled water schemes. At the same time, high-value specialist chemistries such as corrosion inhibitors and membrane anti-scalants are expanding in power generation and mining applications. These reinforcing demand signals explain why suppliers continue to add local blending, automated dosing, and digital monitoring capacity in Australia.
Australia's regulatory environment influences procurement decisions. State environmental regulators issue binding nutrient load limits for wastewater discharges, while mining operators face stricter water quality criteria for process water release. Water utilities increasingly contract for treatment outcomes rather than product tonnes, shifting risk to chemical suppliers. The Industrial Water Treatment Chemicals Market benefits from this trend because industrial facilities require multi-product programs, not single chemistry.
The market is also exposed to global macro forces. Energy-intensive products, especially chlorine-based biocides and inorganic coagulants, have experienced raw material cost inflation since 2022. These costs have largely passed through to municipal budgets due to indexed contracts, although commercial mining and oil and gas buyers use multiple supplier negotiations to reset prices at each renewal. Pricing power is strongest in patented polymer blends and biological control programs.
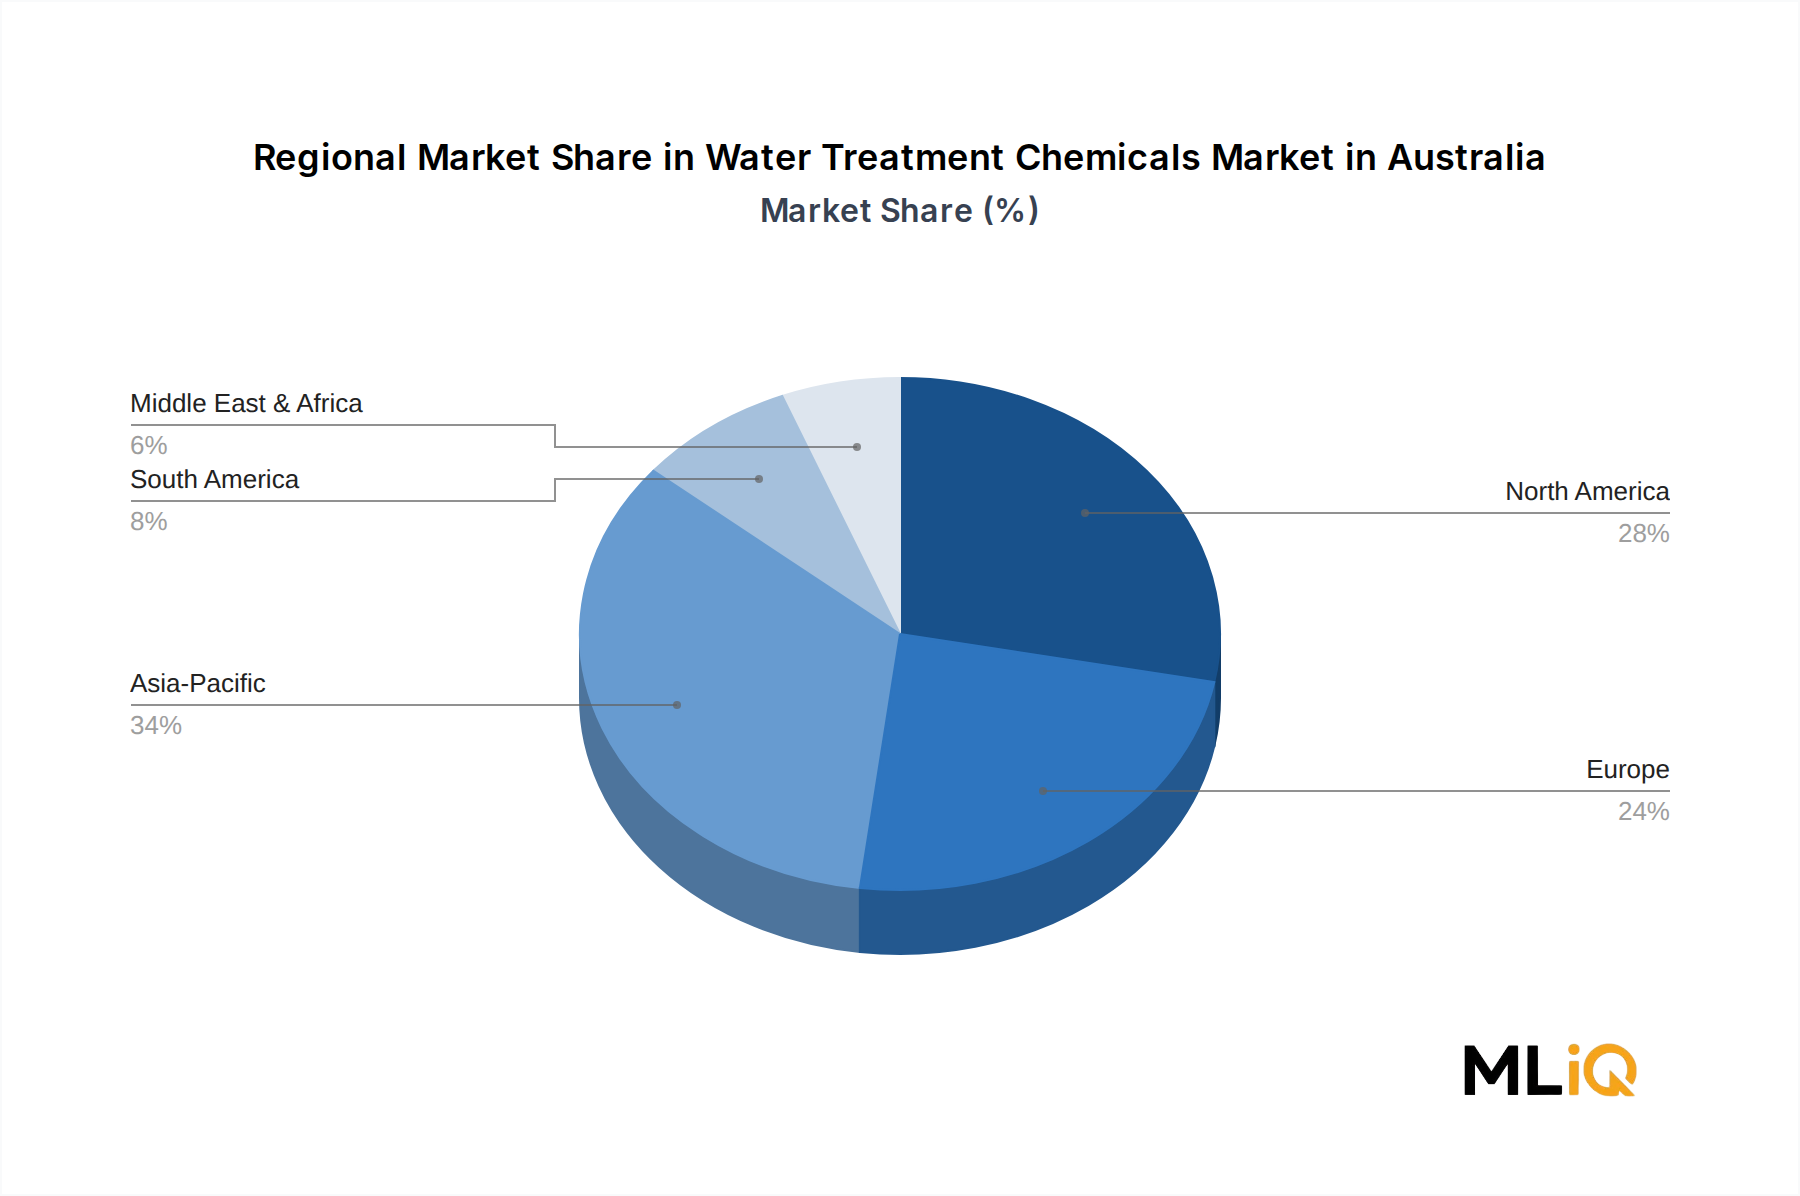
Supply security remains a strategic concern. Because Australia imports many active ingredients from North America, Europe, and Asia, the Asia-Pacific supply corridor has become increasingly important. Local distributors such as Ixom have expanded chemical storage and blending to insulate buyers from global shipment delays. The Green Water Treatment Chemicals Market is starting to influence tenders, with low-phosphorus polymers and bio-based coagulants receiving preferred status in some state-based contracts.
In summary, the market is transitioning from commodity chemical supply to sustainability-linked performance services. The forecast CAGR of 5.11% is attainable only if suppliers solve local regulatory approval, logistics, and skilled workforce constraints. The pages that follow provide segment-level, company-level, and regional benchmarks to support enterprise planning.