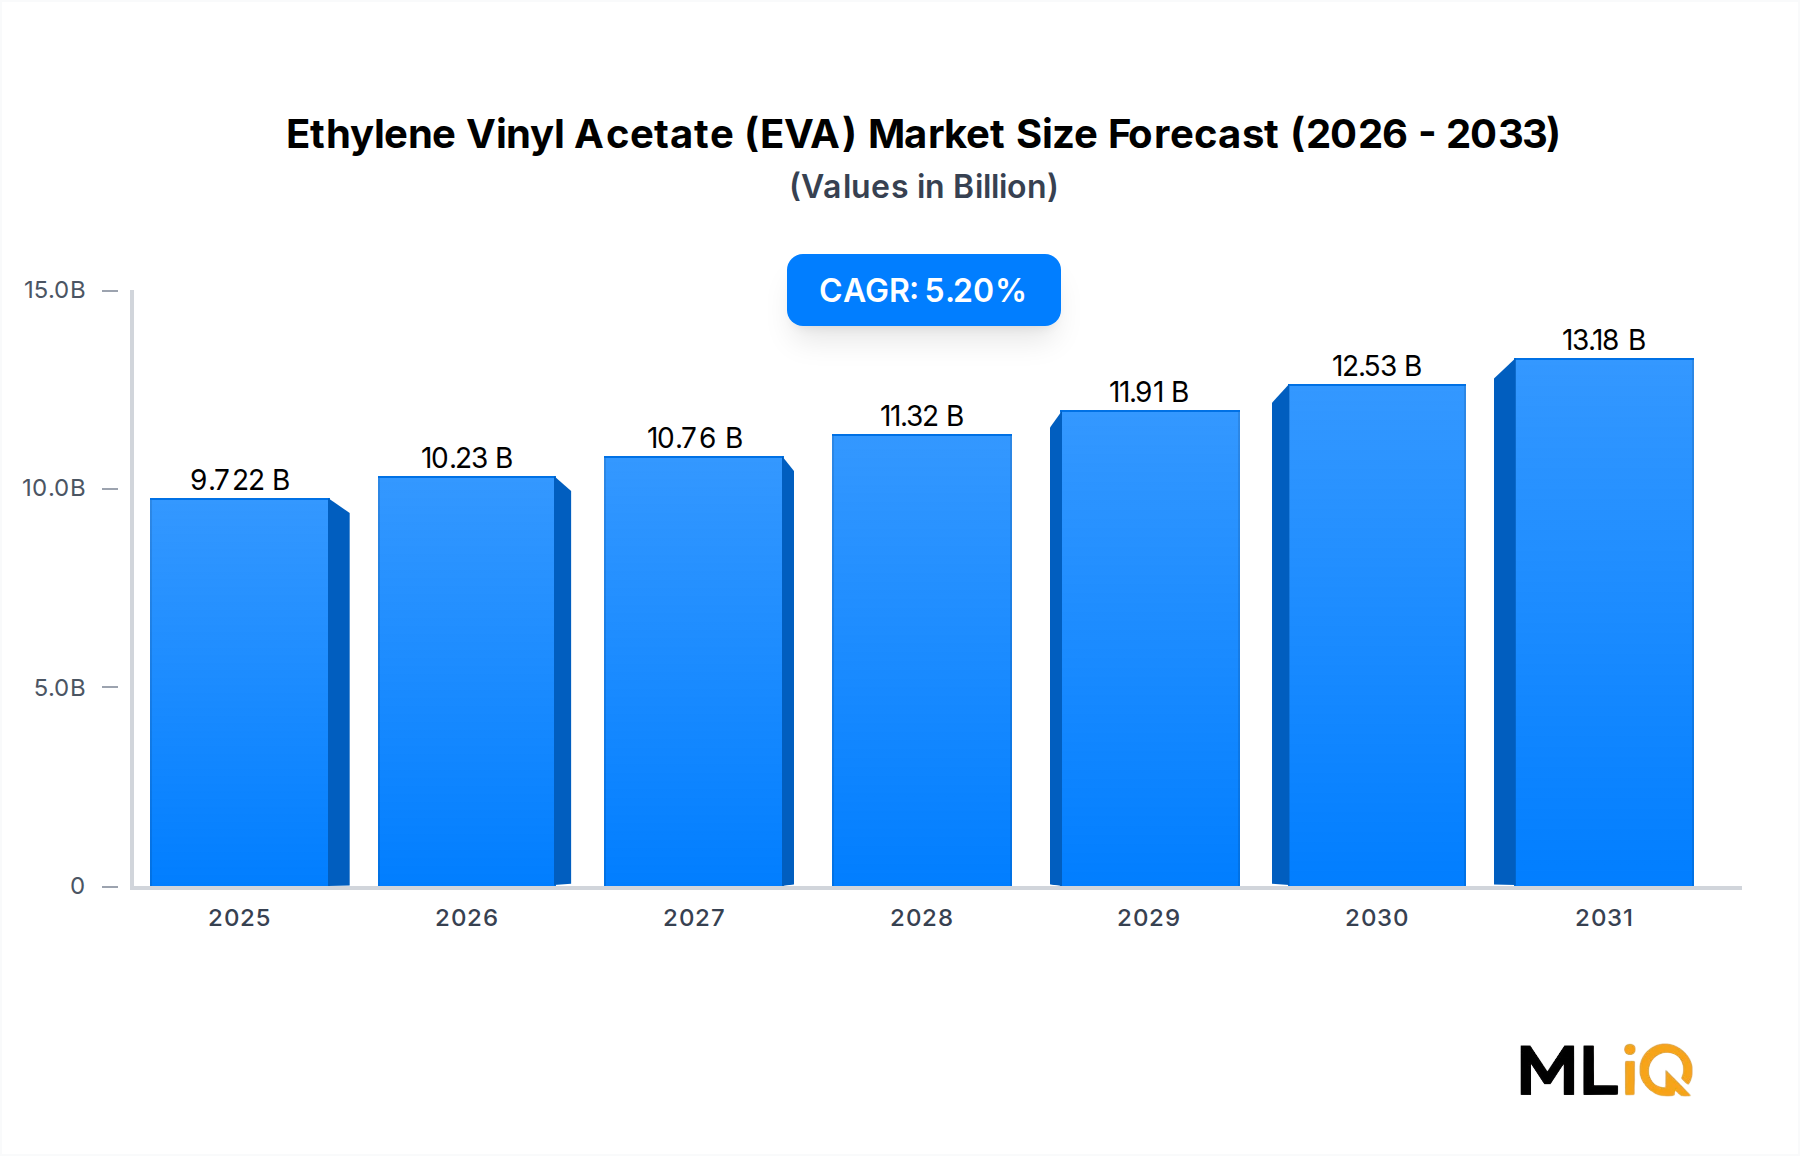
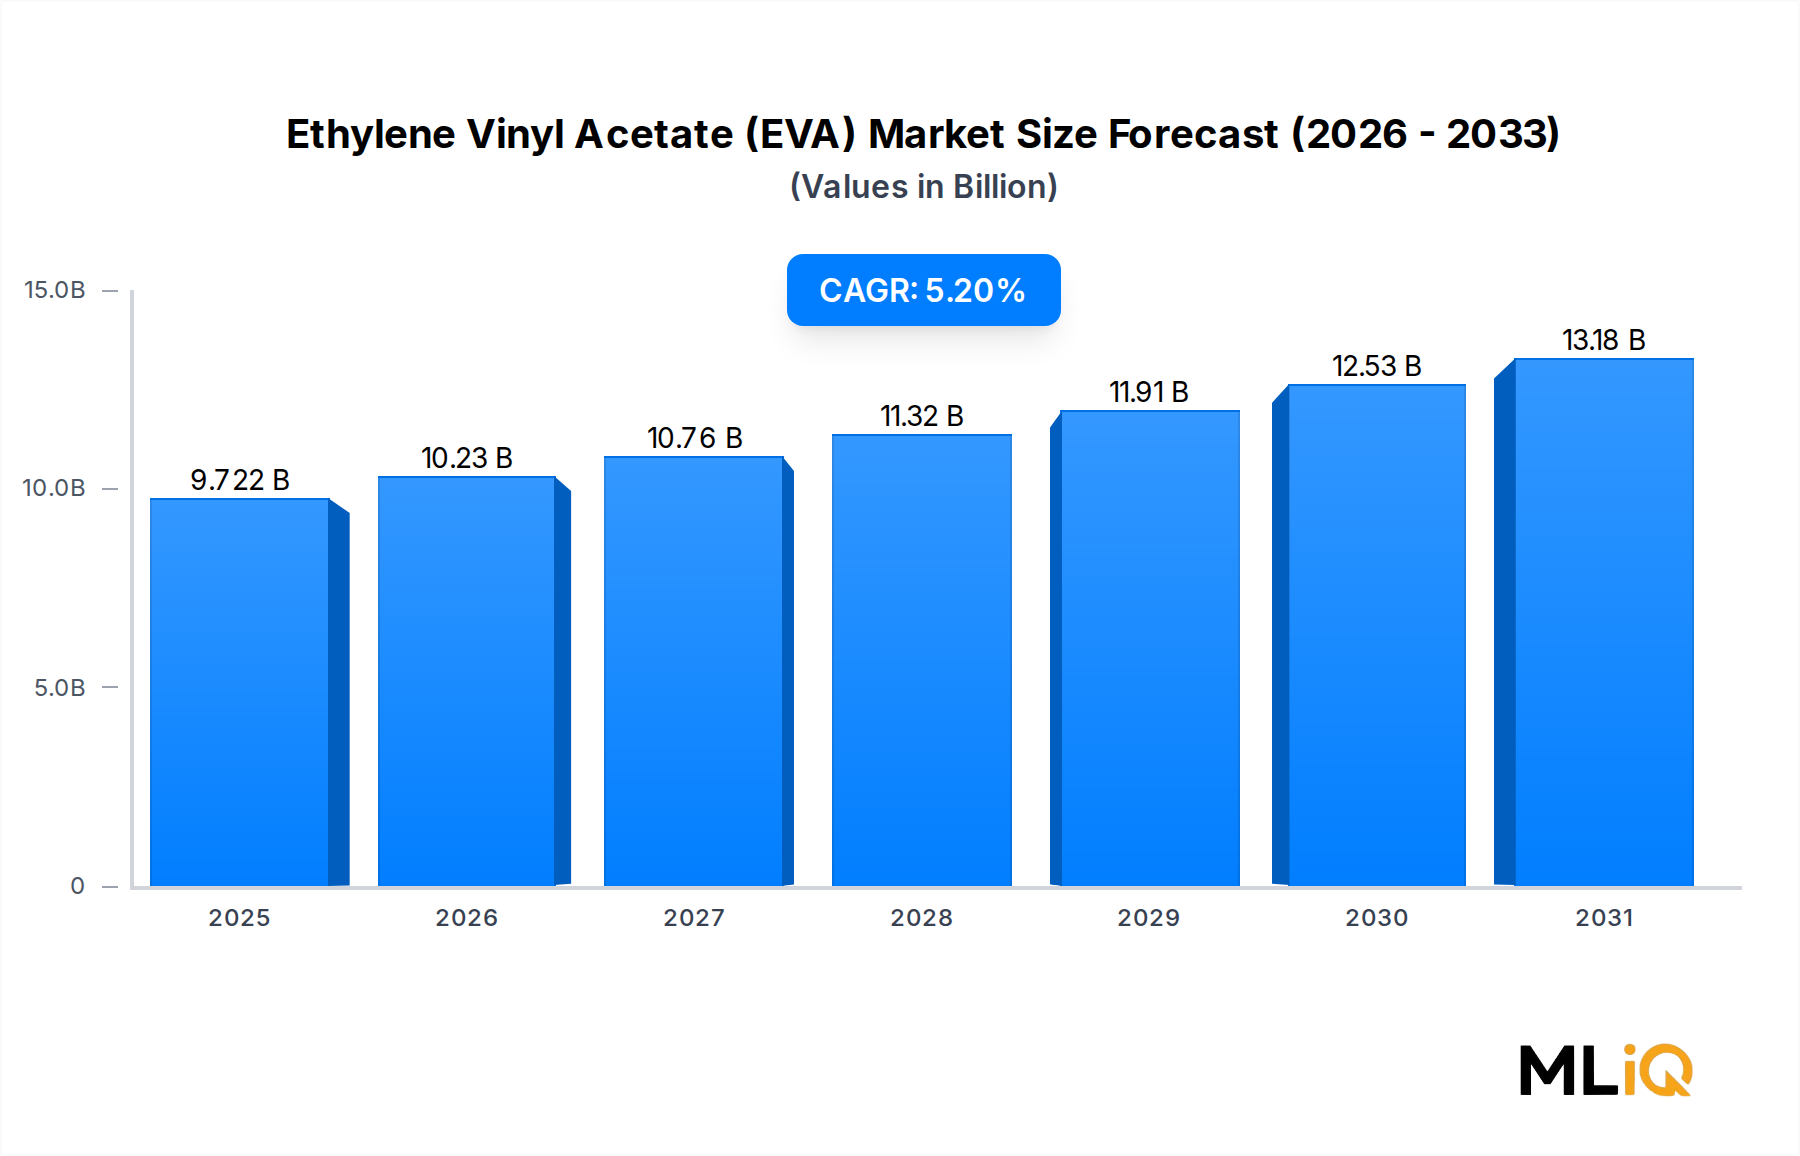
The global Ethylene Vinyl Acetate (EVA) market was valued at approximately $9,721.9 million in 2024 and is projected to expand at a compound annual growth rate (CAGR) of 5.2% through 2033, reflecting robust demand from a diverse array of end-use industries. This trajectory positions EVA as one of the more resilient copolymer segments within the broader materials and chemicals landscape, benefiting simultaneously from secular trends in renewable energy deployment, agricultural intensification, and flexible packaging modernization.
Ethylene vinyl acetate is a copolymer synthesized from ethylene and vinyl acetate monomers, and its physical properties — including flexibility at low temperatures, optical clarity, UV resistance, and strong adhesion characteristics — make it uniquely suited for high-performance applications. The vinyl acetate content can be tailored across a spectrum from roughly 4% to 40% by weight, enabling manufacturers to engineer grades optimized for films, foams, adhesives, or encapsulants depending on end-use requirements.
The most structurally significant demand driver is the accelerating global adoption of solar photovoltaic (PV) technology. EVA serves as the dominant encapsulant material in crystalline silicon solar panels, and as governments in Asia, Europe, and North America aggressively expand renewable energy capacity to meet decarbonization targets, solar installations are growing at double-digit annual rates in key markets. This single application segment has meaningfully elevated the global demand ceiling for EVA over the past five years and is expected to remain the most dynamic growth vector through 2033.
Packaging industry demand — particularly for food-safe stretch films, shrink wraps, and multilayer barrier films — constitutes a second major demand pillar. EVA-based films offer superior seal strength and flexibility compared with conventional low-density polyethylene alternatives, driving substitution across fresh produce, dairy, and processed food supply chains.
Macro tailwinds include expanding agricultural output in Asia Pacific and Latin America, rising consumer spending on footwear (where EVA foams are extensively used in midsoles), and increasing infrastructure investment in emerging markets. Counterbalancing these drivers is the competitive threat from alternative encapsulant materials such as polyolefin elastomers (POE) and thermoplastic polyurethane (TPU), which offer longer service life under high-humidity conditions and may erode EVA's dominance in premium solar module segments over the medium term.
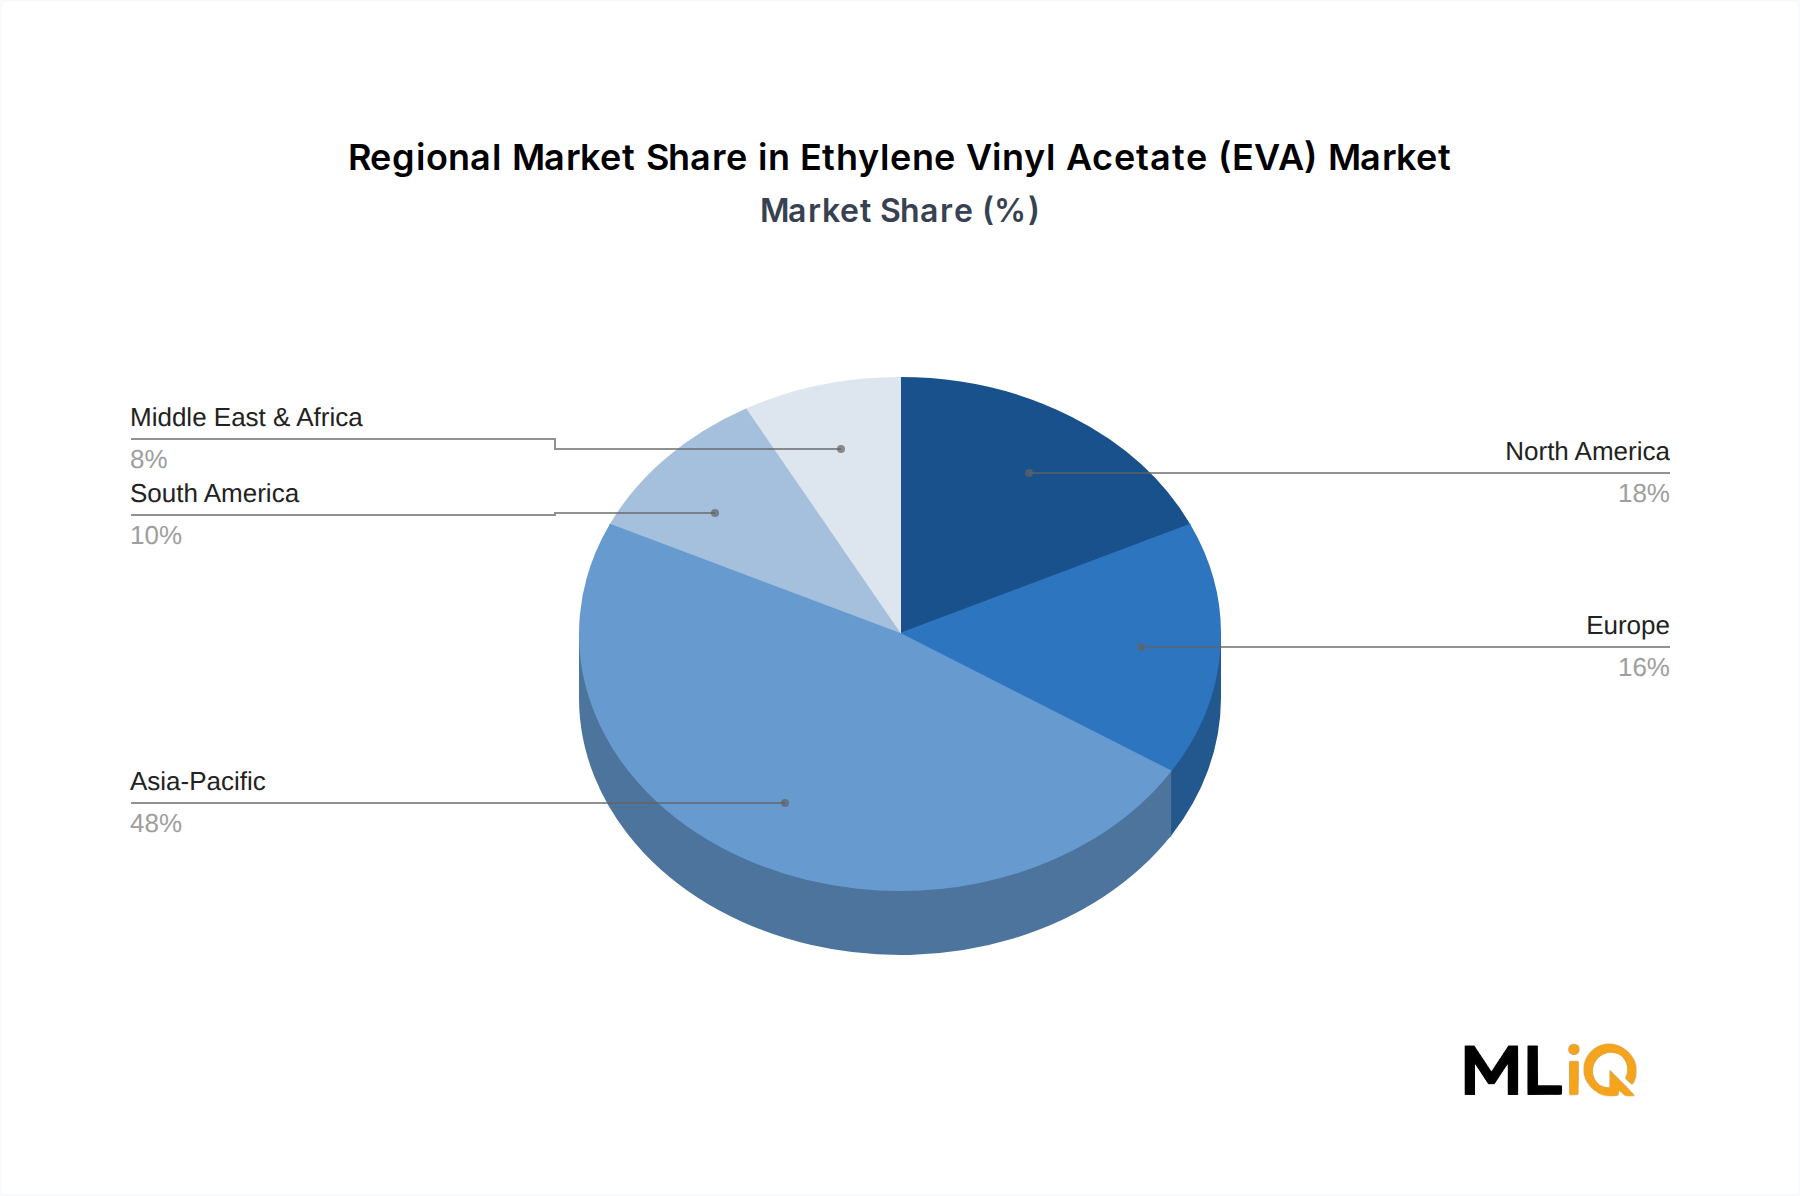
Geographically, Asia Pacific commands the largest revenue share, underpinned by China's dominant position as both a manufacturer and consumer of EVA across solar, footwear, and packaging applications. North America and Europe present more mature but innovation-led demand profiles, with specialty-grade EVA commanding premium pricing. The forward-looking outlook is constructive: the combination of solar expansion, agricultural modernization, and structural packaging upgrades positions the market for sustained mid-single-digit growth through the forecast horizon.